
 Adhesive Equipment Market | 2026-2036
Adhesive Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Equipment Market Intelligence
A capital-intensity divergence between automated robotic dispensing lines and manual benchtop units is reorganizing competitive tiers in adhesive equipment. Nordson Corporation leverages its precision fluid management heritage to dominate high-throughput hot melt installations for packaging OEMs. Henkel sustains integrated adhesive-plus-equipment bundling that anchors recurring consumable revenue streams. Graco Inc. competes through rugged industrial pump architectures designed for construction and woodworking floor environments.
Adhesive equipment encompasses engineered dispensing, metering, and curing systems that apply controlled volumes of bonding agents to substrates, typically operating at pressures from 20 psi to 3,000 psi and temperatures up to 200°C for hot melt configurations. These systems serve primary industrial purposes of ensuring repeatable bond strength, minimizing material waste, and accelerating cycle times in automated production environments. Pneumatic systems retain the largest installed base across mature manufacturing economies, while robotic dispensing platforms capture the fastest expansion as electronics and automotive assemblers pursue micron-level placement accuracy. Hot melt technology leads value generation due to its instant-set characteristics eliminating clamp stations, though UV curing segments attract premium margins in medical device and optical bonding applications where thermal damage risks exclude heat-based methods.
The EPA regulates volatile organic compound emissions from solvent-based adhesive operations under Clean Air Act provisions, compelling equipment manufacturers to engineer sealed delivery architectures and vapor recovery interfaces. REACH restricts specific chemical constituents in European adhesive formulations, directly influencing equipment compatibility requirements and material pathway designs. OSHA workplace exposure limits for isocyanates and hexavalent chromium compounds shape personal protective equipment integration and ventilation specifications for spray-applied systems. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as these substance bans threaten existing adhesive chemistries and demand rapid equipment requalification cycles.
Market Dynamics
Robotic dispensing platforms are compressing cycle times in automotive and electronics assembly, forcing equipment manufacturers to requalify architectures for micron-level precision while solvent-based systems face phasedown pressure from tightening EPA and REACH emission limits.
Growth Catalysts
- Automotive Lightweighting Mandates:German and Chinese OEMs are expanding adhesive bonding lines for composite panels, driving demand for high-pressure metering systems capable of processing structural methacrylates.
- REACH Chemical Restrictions:ECHA's evolving substance restrictions are accelerating equipment replacement cycles as manufacturers reconfigure sealed delivery pathways to handle reformulated water-based and hot melt chemistries.
- Electronics Miniaturization:Microdispensing valves with piezoelectric actuation are penetrating smartphone and wearable assembly lines in Shenzhen and Seoul, enabling sub-nanoliter deposition control.
Market Restraints
- Steel and Aluminum Input Volatility:Pump housing and frame fabrication costs fluctuate with commodity metal indices, compressing margins for mid-tier pneumatic system manufacturers.
- Precision Component Supply Concentration:High-frequency dispensing nozzles and ceramic metering pumps concentrate production in southern Germany and western Japan, creating single-source vulnerability.
- UV Curing Throughput Ceiling:Optical bonding applications face line-speed constraints from lamp intensity limitations and oxygen inhibition in radical-cure acrylates, restricting expansion beyond niche medical device segments.
Strategic Opportunities
- India Packaging Corridor Expansion:Maharashtra and Gujarat states are attracting corrugated board and flexible packaging investments, creating first-mover openings for hot melt tank and hose system providers.
- EU Green Deal Industrial Incentives:CSRD-aligned capital subsidies for energy-efficient manufacturing are steering automotive Tier-1 suppliers toward electrically heated melt systems with closed-loop temperature control.
- AI-Enabled Predictive Maintenance:Convergence of IoT pressure sensors and machine learning platforms is enabling remote pump health monitoring, opening subscription revenue streams for equipment vendors.
Industry Challenges
- Mechatronics Talent Scarcity:Programming and maintaining six-axis robotic dispensing cells requires cross-trained technicians fluent in both adhesive rheology and motion control architecture, a skill combination concentrated in aging workforces.
- Legacy Pneumatic Retrofit Complexity:Brownfield automotive plants in the US Midwest face integration friction when grafting precision metering pumps onto existing PLC networks designed for 1990s-era manual stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Equipment Market |
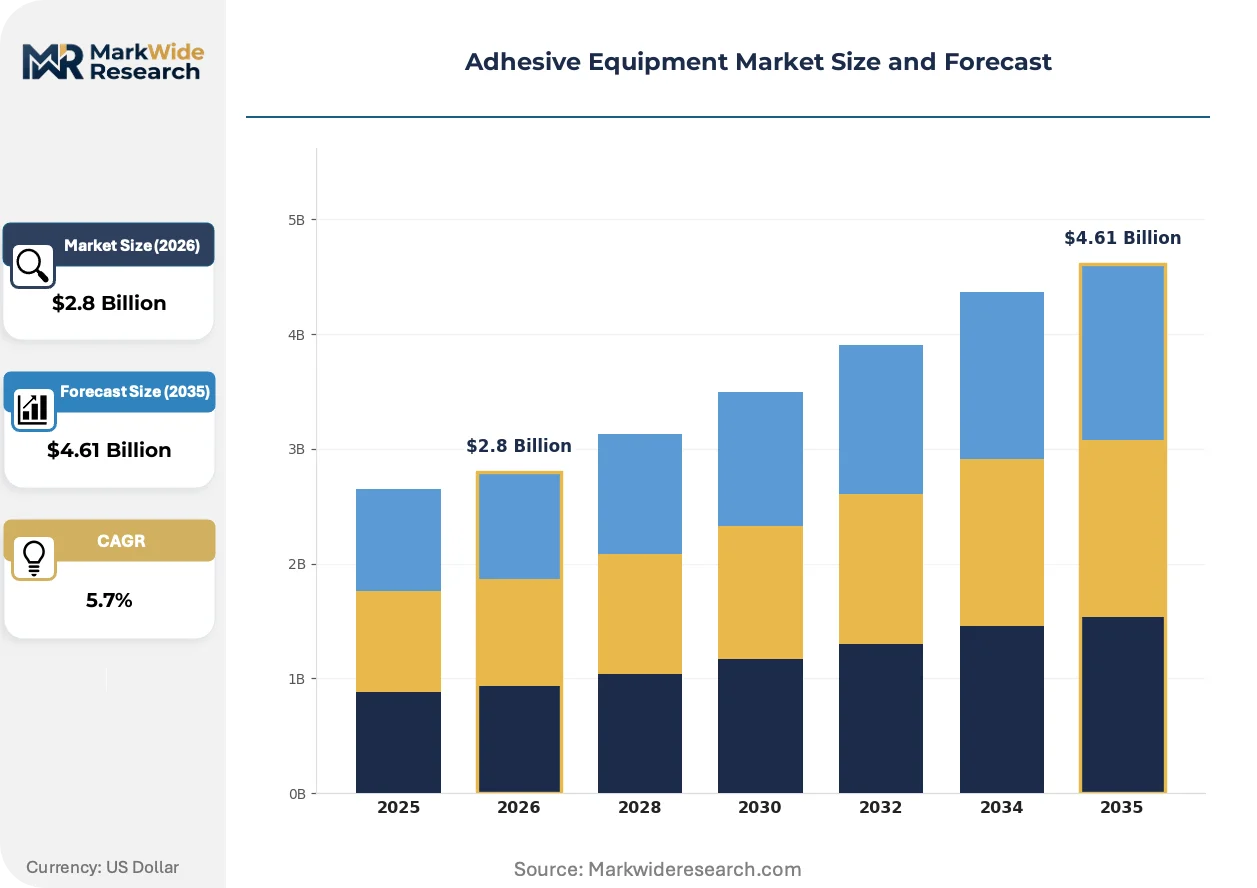
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Manual, Robotic Technology: Hot Melt, Pressure Sensitive, Solvent Based, UV Curing End User: Manufacturing, Automotive, Packaging, Construction Application: Woodworking, Electronics, Aerospace, Textile |
| Companies Covered | Valco Melton, Robatech, Nordson Corporation, 3M, ITW Dynatec, Graco Inc., Dymax Corporation, Glue Machinery Corporation, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Equipment Market Strategic Shifts & Innovations
Equipment architectures are splitting between high-throughput automated cells and flexible benchtop units, while regulatory chemistry restrictions and buyer consolidation reshape competitive positioning across adhesive dispensing tiers.
Hot melt dispensing technology is bifurcating the installed base. Tank-based bulk systems dominate corrugated packaging lines in Germany and the United States, while cartridge-fed micro-melt units penetrate medical device cleanrooms and electronics rework stations. Automotive assemblers in Stuttgart and Shanghai are adopting hybrid configurations that switch between bulk supply for body-in-white and precision cartridge systems for interior trim, compressing the addressable market for single-purpose equipment.
REACH Annex XVII restrictions on diisocyanates and forthcoming PFAS limitations are forcing equipment redesigns across European manufacturing. Sealed drum unloading stations with vapor recovery interfaces are becoming mandatory for polyurethane spray operations in construction applications. German pump manufacturers are responding with nitrogen-purged material pathways and closed transfer systems that eliminate atmospheric exposure during adhesive changeover.
Consolidated procurement by multinational packaging OEMs is compressing vendor margins and unbundling after-sales service contracts. Buyers in China's eastern manufacturing corridor now negotiate regional framework agreements covering adhesive supply, equipment lease, and preventive maintenance as a single spend category. Equipment vendors face pressure to absorb consumable inventory risk and guarantee uptime metrics, shifting revenue recognition from capital sale to performance-based service fees.
Adhesive Equipment Market Segmentation
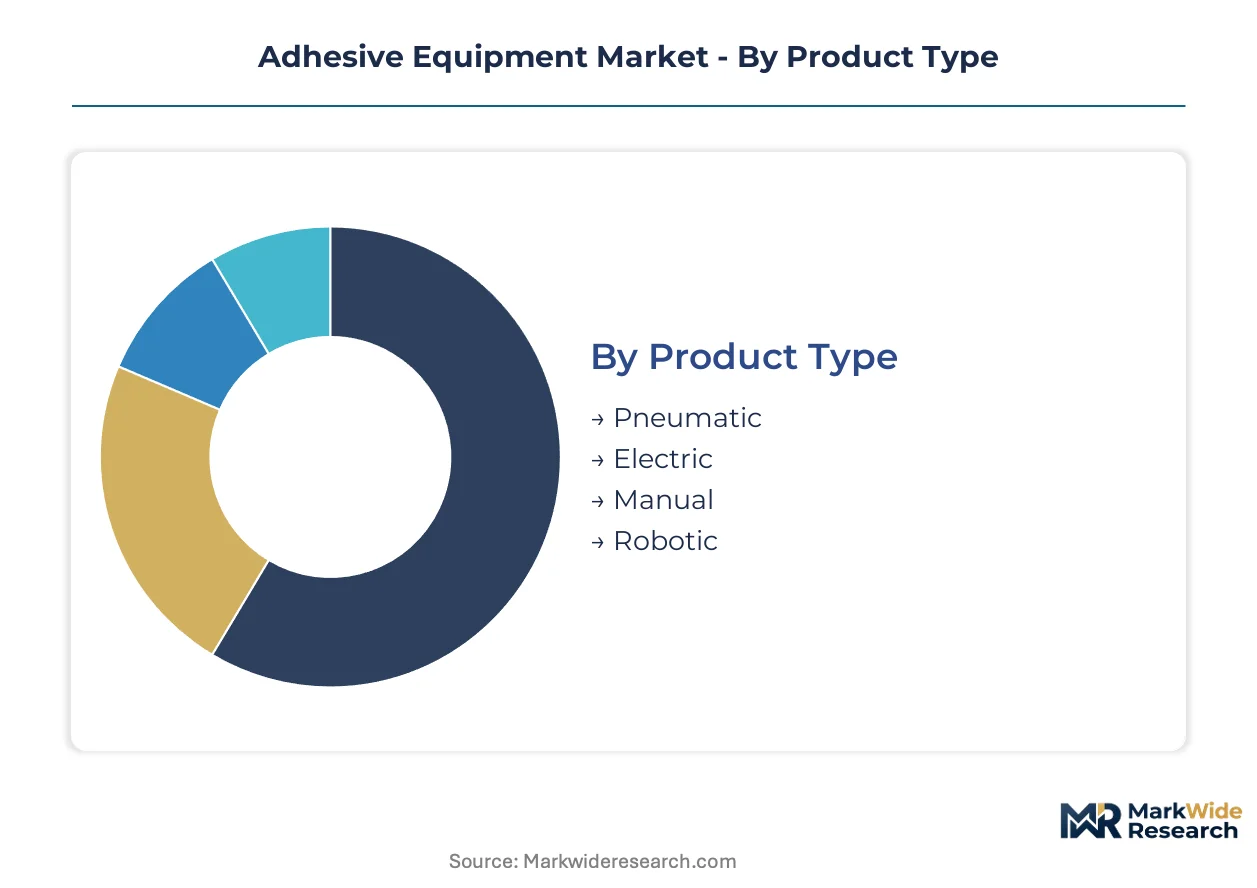
Adhesive equipment segmentation reflects divergent capital intensity across automation tiers and regulatory pressure on chemistry pathways. Equipment buyers segment procurement by precision requirements, emission compliance obligations, and integration complexity with existing production lines.
Product Type:
EPA emission enforcement and OSHA workplace exposure limits create divergent equipment specifications across pneumatic, electric, and robotic architectures.
- Robotic:Six-axis dispensing cells with micron-level placement accuracy serve automotive body-in-white and smartphone assembly lines in Stuttgart and Shenzhen. German and Chinese OEMs specify these systems for structural methacrylate bonding of carbon fiber composite panels, compressing cycle times while meeting repeatability thresholds.
- Pneumatic:Compressed-air-driven piston pumps dominate legacy installations across US Midwest automotive plants and European corrugated packaging corridors. REACH solvent restrictions and EPA volatile organic compound rules are forcing sealed pathway retrofits onto existing pneumatic frames, extending replacement cycles.
- Electric:Servo-driven metering systems with closed-loop pressure control penetrate medical device cleanrooms where pneumatic oil contamination risks exclude compressed air.
- Manual:Handheld dispensers and benchtop guns retain position in electronics rework stations and low-volume woodworking shops where capital constraints block automation.
Established volume favors pneumatic systems; emerging adoption favors robotic platforms.
Technology:
Cost tier differentiation separates instant-set chemistries requiring heated delivery from ambient-cure systems demanding extended clamp stations.
- Hot Melt:Thermoplastic adhesive systems operating at 150°C to 200°C eliminate curing stations through rapid crystallization. Tank-based bulk configurations dominate German corrugated packaging lines, while cartridge-fed micro-melt units penetrate medical device assembly in cleanroom environments.
- UV Curing:Radical-cure acrylates activated by mercury or LED lamp arrays command premium pricing in optical bonding and medical device applications where thermal damage risks exclude hot melt methods. Oxygen inhibition and lamp intensity constraints restrict line speeds.
- Solvent Based:Hydrocarbon-carried adhesives face phasedown pressure from EPA Clean Air Act enforcement and REACH Annex XVII restrictions on specific constituents.
- Pressure Sensitive:Permanent-tack formulations applied via slot-die or roll-coat methods serve label manufacturing and tape converting operations with minimal capital equipment.
Revenue concentration sits with hot melt technology; steepest expansion trajectory belongs to UV curing in medical and optical segments.
End User:
Customer type determines specification intensity, with automotive and aerospace buyers imposing traceability and validation requirements absent in construction procurement.
- Automotive:OEMs and Tier-1 suppliers in Germany and China specify high-pressure metering systems for structural bonding of lightweight composites, driven by fuel efficiency mandates and crashworthiness requirements.
- Packaging:Corrugated board and flexible film converters in China's eastern manufacturing corridor drive demand for hot melt tank systems with rapid warm-up cycles and pattern control.
- Manufacturing:General industrial assemblers span electronics, appliance, and furniture production with heterogeneous precision requirements.
- Construction:Spray-applied polyurethane and sealant operations face tightening OSHA isocyanate exposure limits and EPA volatile organic compound regulations.
Procurement volume concentrates in packaging; specification complexity peaks in automotive.
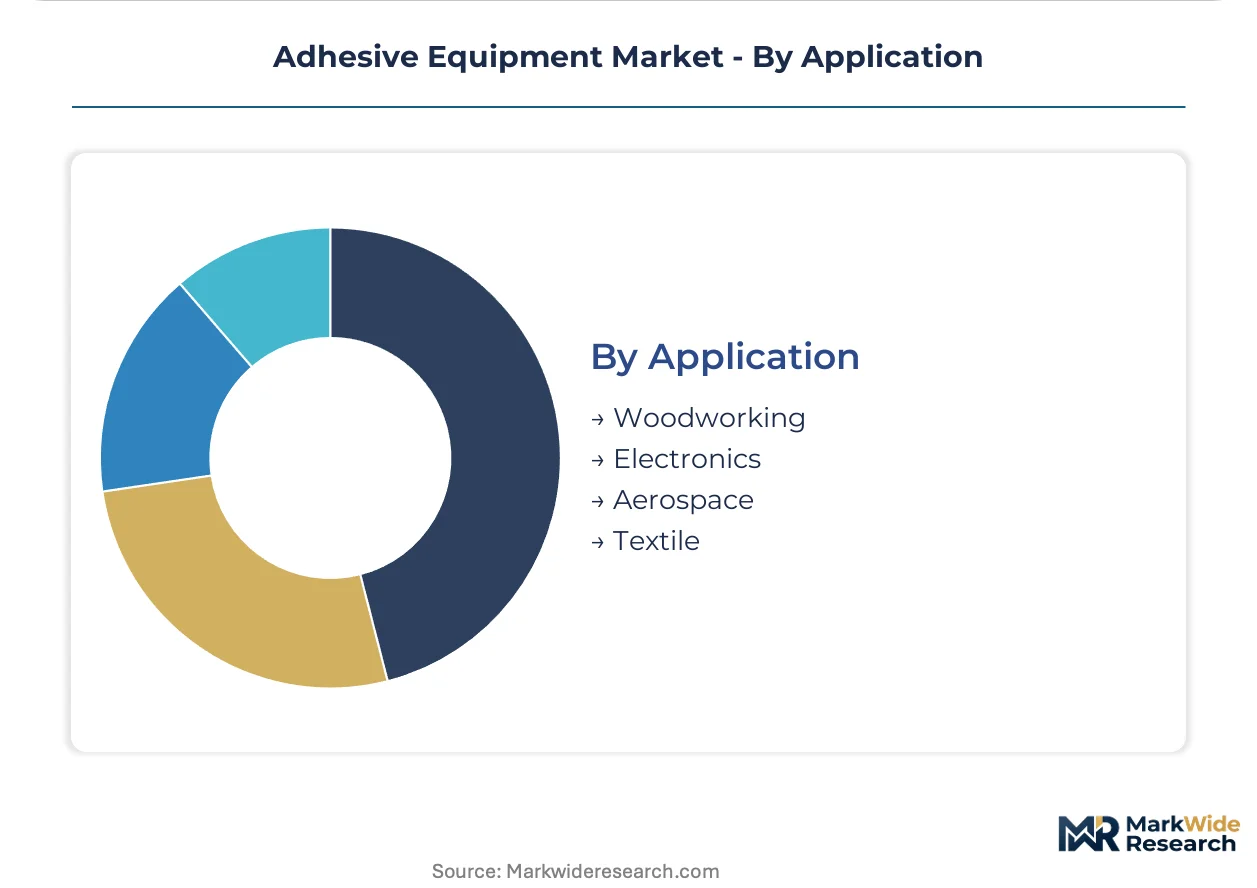
Application:
Application-specific requirements for bond line thickness, thermal tolerance, and substrate compatibility dictate equipment architecture selection.
- Electronics:Microdispensing valves with piezoelectric actuation enable sub-nanoliter deposition control for smartphone and wearable assembly in Shenzhen and Seoul, where miniaturization trends demand placement accuracy below 50 microns.
- Aerospace:Structural adhesive bonding of aluminum and composite airframe components requires vacuum-assisted resin transfer and autoclave-compatible metering systems with batch traceability.
- Woodworking:Edgebanding and panel assembly operations in European furniture manufacturing employ hot melt roller and spray systems with rapid changeover capability.
- Textile:Lamination and seam sealing applications in technical textiles and footwear production utilize rotary screen and dot-pattern dispensing with moisture-cure polyurethane chemistry.
Precision requirements favor electronics; capital intensity peaks in aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German precision-equipment fabricators commanding premium multiples, while Chinese manufacturers compete on throughput scale across the eastern manufacturing corridor.
United States
Automotive lightweighting mandates from NHTSA fuel demand for structural bonding systems in Michigan and Ohio assembly plants. EPA Clean Air Act enforcement tightens solvent-based equipment specifications, compelling vapor recovery retrofits. Packaging OEMs in Wisconsin and Illinois drive hot melt tank installations for corrugated board lines.
Germany
Stuttgart OEMs specify robotic dispensing cells for carbon fiber composite bonding in body-in-white operations. REACH Annex XVII diisocyanate restrictions force nitrogen-purged material pathway redesigns. Bavarian pump manufacturers engineer closed transfer systems eliminating atmospheric exposure during adhesive changeover.
China
Electronics miniaturization in Shenzhen and Shanghai demands piezoelectric microdispensing valves with sub-nanoliter precision. MEE enforcement of dual carbon goals steers manufacturers toward electrically heated melt systems. The Yangtze River Delta packaging corridor concentrates procurement of tank-based hot melt configurations.
Japan
Medical device cleanrooms in Osaka and Tokyo specify cartridge-fed micro-melt units for optical bonding applications. METI industrial efficiency standards accelerate servo-driven electric system adoption. Kyushu semiconductor packaging facilities deploy UV curing platforms for thermal-sensitive substrate assembly.
India
Maharashtra and Gujarat states attract corrugated board investments creating openings for hot melt system providers. BIS certification requirements shape equipment import specifications for domestic manufacturers. The Delhi-Mumbai Industrial Corridor clusters flexible packaging converters negotiating integrated adhesive-plus-equipment contracts.
Adhesive Equipment Market Key Industry Players
Concentration sits with diversified industrial conglomerates controlling precision fluid management heritage. Three structural tiers organize the vendor base: multinational adhesive-plus-equipment bundlers, specialized dispensing technology pure-plays, and regional fabrication houses serving cost-sensitive procurement. Dominant competitive moves include vertical integration into consumable supply chains and geographic expansion through distribution partnerships in emerging manufacturing corridors.
Within the precision-engineering tier, Nordson Corporation and Graco Inc. exemplify divergent strategic positioning. Nordson anchors high-throughput packaging installations through heritage fluid control architectures. Graco occupies rugged industrial environments with pump systems designed for construction floor conditions. Henkel represents the integrated bundling archetype, capturing recurring revenue through combined adhesive and equipment procurement frameworks.
| Leading Market Players |
|---|
| Valco Melton |
| Robatech |
| Nordson Corporation |
| 3M |
| ITW Dynatec |
| Graco Inc. |
| Dymax Corporation |
| Glue Machinery Corporation |
| Henkel |
| Others |
Cost & Logistics Intelligence
Long-term equipment lease contracts with embedded consumable minimums lock in supply access and price visibility for packaging OEMs across China's eastern manufacturing corridor, compressing spot-market exposure while transferring inventory risk to vendors.
Pricing Analysis
Configured-to-order pricing for robotic dispensing cells commands a 40-60% premium over standard pneumatic benchtop units. Three-tier pricing structure across premium, standard, and economy levels segments by automation tier, precision specification, and after-sales service bundling. Cost compression in mid-tier pneumatic systems is intensifying because consolidated procurement by multinational packaging OEMs unbundles service contracts and squeezes vendor margins. Small woodworking shops and electronics rework stations exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Ceramic metering pump fabrication in southern Germany and western Japan creates a single-source chokepoint for high-frequency dispensing nozzles. Precision component manufacturing draws from Japanese ceramics expertise, German precision machining, and Chinese steel forging capacity. Supply chain risk centers on single-source vulnerability for piezoelectric microdispensing valves, where alternative qualification cycles exceed 18 months. Distribution runs through OEM-direct sales for automotive and electronics sectors, with regional distributors serving fragmented construction and woodworking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adhesive equipment market sits in early-cycle recovery, with capital expenditure normalization in automotive and electronics assembly driving replacement demand after two years of deferred investment.
For Market Incumbents: Shield installed base revenue through captive consumable supply contracts that bundle adhesive procurement with equipment uptime guarantees. Deepen backward integration into precision nozzle manufacturing to reduce exposure to German and Japanese single-source suppliers. Prioritize certification investment for REACH-compliant sealed pathway architectures ahead of PFAS restriction implementation.
For New Entrants and Emerging Players: Differentiate on AI-enabled predictive maintenance platforms that convert capital sales into recurring subscription revenue. Target India's Maharashtra and Gujarat packaging corridor, where first-mover openings exist for hot melt tank providers before incumbent distribution networks solidify. Pursue integrated adhesive-plus-equipment bundling modeled on Henkel's procurement framework to anchor recurring revenue streams.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision fluid management pure-plays with proprietary nozzle architectures. Over the coming decade, equipment vendors with captive software platforms and service revenue above 40% of total sales will outcompete hardware-only competitors. Monitor automotive OEM adhesive bonding line expansion announcements in Stuttgart and Shanghai as the primary inflection signal for capital equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Nozzle Manufacturing | Captive supply of ceramic metering pumps eliminates single-source vulnerability to German and Japanese suppliers. |
| AI-Enabled Predictive Maintenance Platform Launch | IoT pressure sensors and machine learning convert capital sales to subscription revenue with higher lifetime value. |
| REACH-Compliant Sealed Pathway Certification | Nitrogen-purged material pathways qualify equipment for European polyurethane spray operations under ECHA restrictions. |
| India Distribution Partnership Expansion | Maharashtra and Gujarat corrugated board investments create first-mover positioning before incumbent networks establish. |
| Integrated Adhesive-Plus-Equipment Bundling | Combined procurement frameworks anchor recurring consumable revenue and reduce customer churn risk. |
Research Approach
Desk research of SEC 10-K filings, customs trade databases, and ECHA regulatory submissions preceded structured interviews with plant engineers at automotive Tier-1 suppliers, packaging OEM procurement directors, and aftermarket service heads at equipment distributors. Primary fieldwork with adhesive equipment operators in Germany, China, and the United States validated secondary estimates of installed base and replacement cycles. Bottom-up unit economics triangulated against top-down manufacturing output projections across automotive, packaging, and electronics end-use segments.
Variance decomposition across product type, technology pathway, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand modeling that weights capital expenditure intentions against regulatory compliance deadlines. Forecast inputs incorporated automotive lightweighting mandates from NHTSA, REACH Annex XVII substance restriction timelines, and electronics miniaturization trends in Shenzhen and Seoul assembly lines.
Material uncertainties — commodity metal price volatility, PFAS regulatory scope expansion, and mechatronics talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about capital expenditure normalization and regulatory compliance deadlines that may shift with macroeconomic conditions. Practitioners should keep alternative scenarios live as EPA enforcement intensity and ECHA substance restriction scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market