
 Latin America Laboratory Automation Market | 2026-2036
Latin America Laboratory Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Laboratory Automation Market Intelligence
A shift from single-source instrument procurement to multi-vendor integrated platforms is realigning how clinical laboratories across Latin America structure capital budgets. Danaher Corporation anchors its position through extensive distribution networks spanning Brazil and Mexico. Agilent Technologies differentiates via specialized chromatography-automation bundles for pharmaceutical quality control. Thermo Fisher Scientific leverages its software-robotics integration to compete in high-throughput screening installations.
Latin America laboratory automation encompasses electromechanical systems, programmable liquid handling robots, and laboratory information management software designed to execute repetitive analytical protocols with precision measured in microliter volumes and cycle times under five minutes. Clinical diagnostics applications lead segment value due to chronic disease screening expansion, while AI integration within automation software represents the fastest-growing technology dimension as laboratories seek predictive maintenance and error-reduction capabilities. Robotics hardware retains mature margin pools in pharmaceutical manufacturing quality control, where validated repeatability standards dominate purchasing criteria.
ANVISA in Brazil and COFEPRIS in Mexico enforce medical device registration and Good Manufacturing Practice standards that directly shape automation equipment market access requirements across the region. Argentina's national administration of drugs, foods and medical technology applies parallel conformity assessment protocols that extend compliance timelines for imported systems. Stakeholders must monitor evolving data integrity mandates from these regulators to anticipate validation documentation demands on software-centric automation platforms.
Market Dynamics
ANVISA's updated Good Manufacturing Practice requirements for diagnostic devices are compressing validation timelines and forcing pharmaceutical manufacturers across Brazil to accelerate automated quality control retrofits. This regulatory pressure is redistributing capital toward integrated robotics platforms capable of generating audit-ready documentation streams.
Growth Catalysts
- Chronic Disease Screening Expansion:Clinical laboratories in São Paulo's biomedical research corridor are scaling high-throughput diagnostic installations to address diabetes and cardiovascular disease prevalence.
- COFEPRIS Medical Device Registration Streamlining:Mexico's national health regulator has reduced approval timelines for Class II automation equipment, accelerating market access for liquid handling systems.
- AI-Integrated Predictive Maintenance:Machine learning algorithms embedded in laboratory information management software are reducing equipment downtime through failure-pattern recognition.
Market Restraints
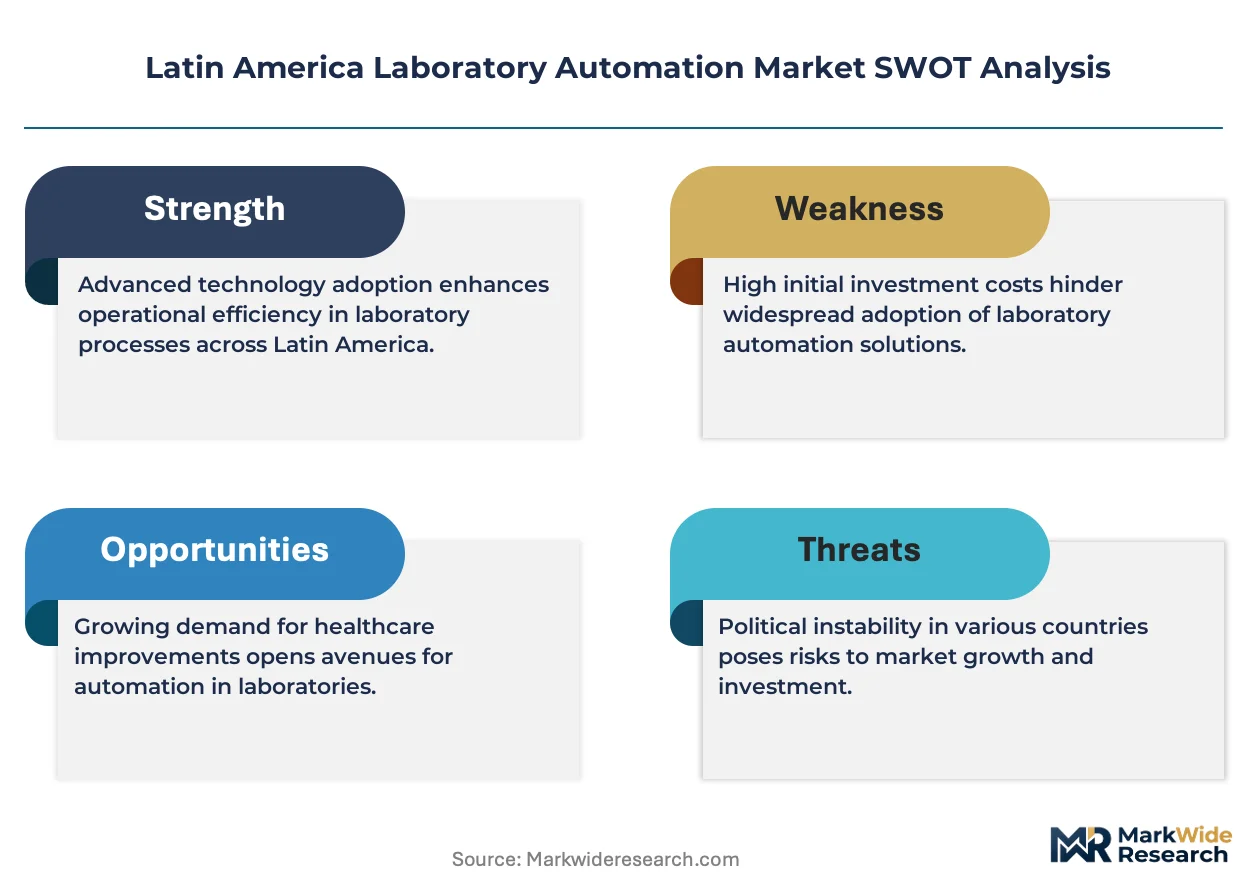
- Import Duty Volatility:Argentina's national administration of drugs, foods and medical technology applies parallel conformity assessment protocols that extend compliance timelines and inflate landed costs for electromechanical systems.
- Technical Specialist Scarcity:The region's limited pool of certified robotics technicians constrains deployment velocity for programmable liquid handling installations.
- Capital Intensity Threshold:Multi-vendor integrated platforms require upfront investment levels that mid-sized clinical laboratories cannot access without external financing.
Strategic Opportunities
- Colombia's Underpenetrated Clinical Network:Bogotá's emerging biomedical cluster presents whitespace for automated sample preparation systems serving private diagnostic chains.
- Cloud-Native LIMS Convergence:Remote monitoring capabilities are unifying distributed laboratory networks across Brazilian state health systems.
- ANVISA Data Integrity Mandates:Electronic signature and audit trail requirements are creating replacement demand for legacy automation software lacking 21 CFR Part 11 equivalence.
Industry Challenges
- Legacy System Integration Complexity:Pharmaceutical quality control departments struggle to interface new robotics hardware with existing chromatography data systems without custom middleware development.
- Validation Documentation Burden:Software-centric automation platforms require extensive IQ/OQ/PQ protocols that strain quality assurance staffing at mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Laboratory Automation Market |
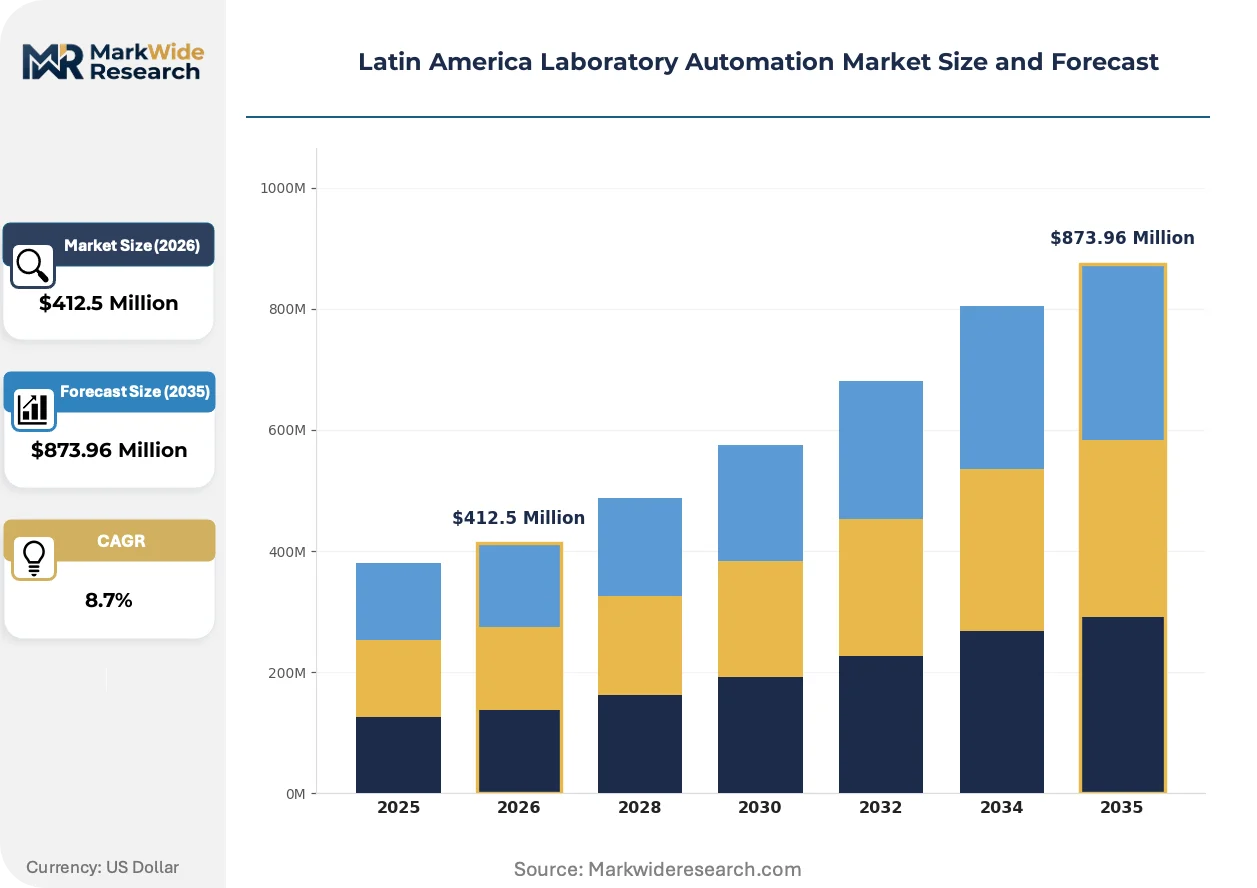
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling Systems, Robotics, Software, Microplate Readers Application: Drug Discovery, Clinical Diagnostics, Quality Control, Research & Development End User: Pharmaceutical Companies, Academic Institutions, Clinical Laboratories, Biotech Firms Technology: Automation Software, AI Integration, High-Throughput Screening, Advanced Analytics |
| Companies Covered | Abbott, Agilent Technologies, Danaher Corporation, Siemens Healthcare, Honeywell International, ABB, Rockwell Automation, Emerson Electric, Thermo Fisher Scientific, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Laboratory Automation Market Strategic Shifts & Innovations
Artificial intelligence is embedding into laboratory automation at the workflow orchestration layer, compressing error rates and enabling predictive intervention before sample integrity degrades. This convergence is reshaping competitive differentiation around software-robotics integration rather than hardware specifications alone.
Modular robotics architectures are unifying previously siloed pre-analytical, analytical, and post-analytical stages within single platform footprints. Brazilian pharmaceutical manufacturers are adopting these configurations fastest where ANVISA audit frequency intensifies. The structural consequence is consolidation of vendor relationships as laboratories reduce integration touchpoints.
ANVISA's alignment with FDA data integrity guidance is mandating audit trail completeness for all diagnostic device manufacturing workflows. This regulatory convergence is elevating software validation to equal priority with hardware qualification. High-throughput screening installations in São Paulo's research corridor are responding by embedding electronic signature capture at every liquid handling step.
After-sales service unbundling is disrupting traditional capital equipment procurement in Mexico's private laboratory sector. Diagnostic chains now purchase robotics hardware through distributor networks while contracting software maintenance directly with original developers. This bifurcation is most visible in Mexico City, where COFEPRIS-registered service providers compete on response-time guarantees separate from equipment financing terms.
Latin America Laboratory Automation Market Segmentation
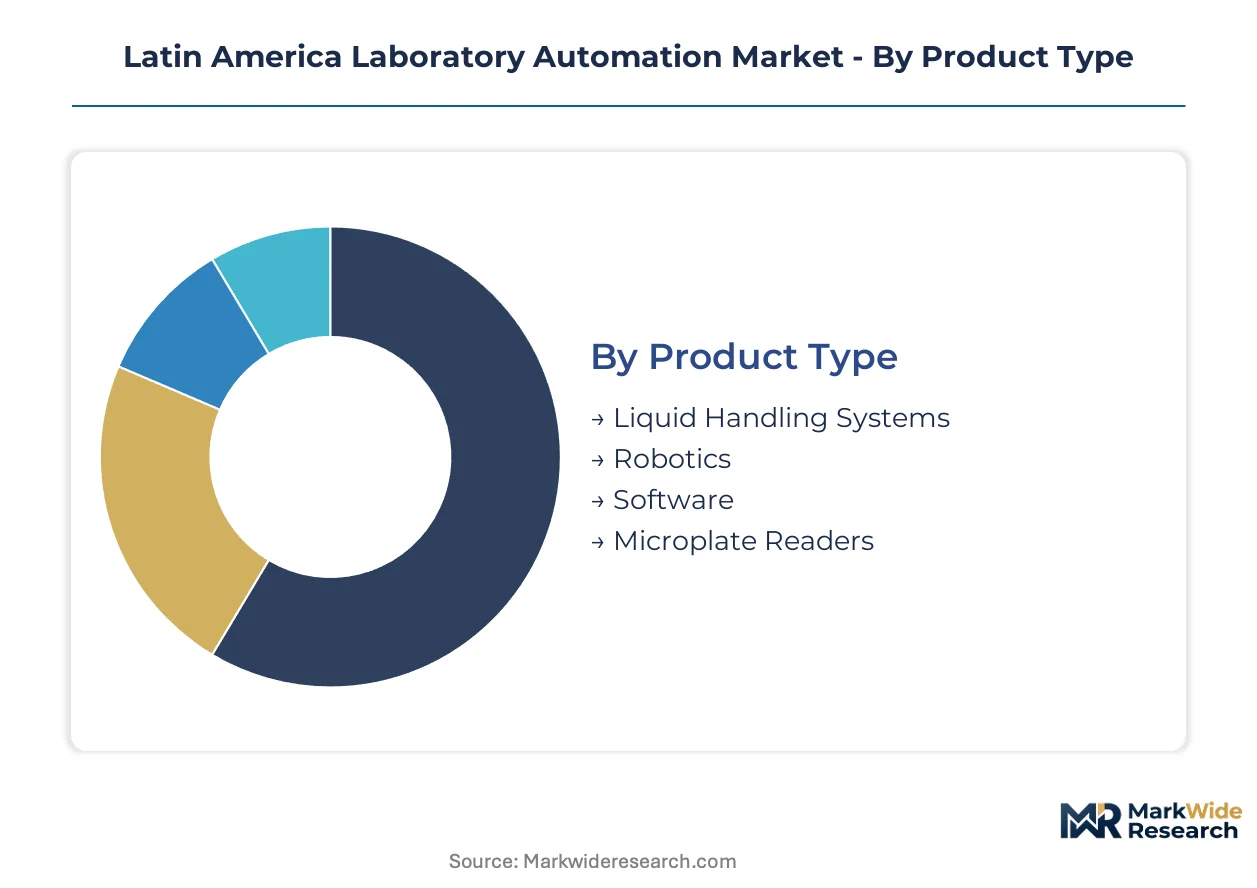
Segmentation in laboratory automation reveals how regulatory complexity, technical intensity, and end-use specialization fragment purchasing behavior across Latin America. Equipment categories face divergent ANVISA and COFEPRIS validation pathways, while application segments concentrate in distinct geographic clusters with incompatible workflow requirements.
Product Type:
Certification burden varies sharply: liquid handling systems and robotics hardware face extended ANVISA electromechanical safety reviews, while software platforms navigate data integrity mandates under updated FDA-aligned guidance.
- Liquid Handling Systems:Programmable pipetting workstations with microliter precision execute sample preparation protocols across 96- and 384-well formats. Demand concentrates in São Paulo's pharmaceutical quality control corridors where ANVISA audit frequency accelerates automated retrofits.
- Robotics:Electromechanical arms and transport systems integrate pre-analytical, analytical, and post-analytical stages within unified footprints. Brazilian manufacturers prioritize these configurations to compress validation touchpoints and satisfy electronic signature requirements.
- Software:Laboratory information management systems with cloud-native architectures enable remote monitoring of distributed networks.
- Microplate Readers:Detection instruments for absorbance, fluorescence, and luminescence measurements complete automated screening workflows.
Leading the category by volume: Liquid Handling Systems. Growing fastest: Software.
Application:
Cost tier stratification separates capital-intensive drug discovery installations from mid-budget clinical diagnostic deployments and lean research configurations.
- Clinical Diagnostics:High-throughput screening for diabetes, cardiovascular disease, and infectious agents dominates São Paulo's biomedical research corridor. Chronic disease prevalence and public health system expansion sustain instrument procurement despite capital intensity barriers.
- Quality Control:Validated repeatability protocols for pharmaceutical manufacturing face compressed timelines under ANVISA's updated GMP requirements. Automated retrofits redistribute capital toward audit-ready documentation streams.
- Drug Discovery:Target identification and lead optimization workflows require integrated robotics-software platforms with predictive maintenance capabilities.
- Research & Development:Flexible automation configurations serve academic and biotech exploration with lower throughput demands.
Highest capital deployment: Clinical Diagnostics. Steepest expansion trajectory: Quality Control.
End User:
Customer type determines procurement modality — pharmaceutical companies favor multi-vendor integrated platforms, while academic institutions prioritize modular, financing-flexible configurations.
- Pharmaceutical Companies:Brazil's largest manufacturers anchor regional demand through automated quality control investments tied to ANVISA compliance deadlines. These buyers consolidate vendor relationships to reduce integration complexity.
- Clinical Laboratories:Private diagnostic chains across Mexico City and São Paulo scale high-throughput installations for chronic disease screening. COFEPRIS registration streamlining accelerates liquid handling system access.
- Academic Institutions:University research centers in Bogotá's emerging biomedical cluster adopt entry-level automation for sample preparation.
- Biotech Firms:Venture-backed developers in Argentina's constrained import environment face extended compliance timelines for electromechanical systems.
Category leader by installed base: Pharmaceutical Companies. Gaining share fastest: Clinical Laboratories.
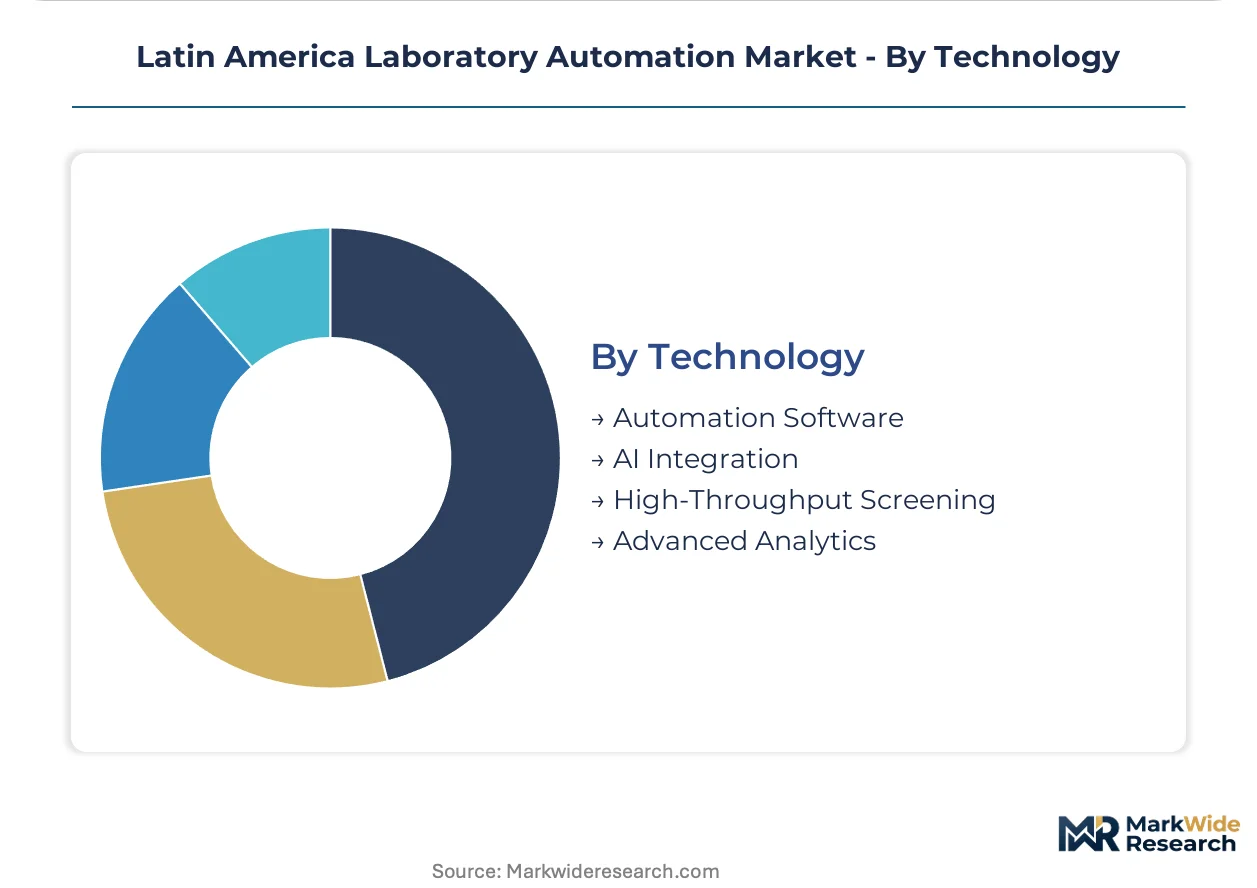
Technology:
Maturity gradient separates established automation software from emerging AI integration, with high-throughput screening representing proven volume and advanced analytics occupying experimental positioning.
- AI Integration:Machine learning algorithms embedded in workflow orchestration layers reduce error rates through predictive intervention. São Paulo research installations lead adoption where sample integrity degradation carries highest cost.
- High-Throughput Screening:Parallel processing architectures execute thousands of assays daily with cycle times under five minutes. Brazilian pharmaceutical quality control departments deploy these systems to satisfy validated repeatability standards.
- Automation Software:Laboratory information management platforms with electronic signature and audit trail capabilities address ANVISA data integrity mandates.
- Advanced Analytics:Pattern recognition and statistical process control tools optimize equipment utilization across distributed networks.
Deepest installed base: High-Throughput Screening. Climbing the fastest: AI Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the Gulf of Mexico anchors Mexico's automation assembly capacity, while precision electronics components flow through São Paulo's industrial corridor into Brazilian laboratory systems.
Brazil
Chronic disease screening expansion and pharmaceutical manufacturing retrofits drive instrument procurement. ANVISA's updated Good Manufacturing Practice requirements compress validation timelines for diagnostic devices. São Paulo's biomedical research corridor concentrates high-throughput installations serving both public health systems and private diagnostic chains.
Mexico
COFEPRIS medical device registration streamlining accelerates liquid handling system approvals for private laboratories. The country's national pharmaceutical regulator has reduced Class II equipment timelines significantly. Mexico City Metro hosts the densest concentration of diagnostic chains adopting unbundled after-sales service models.
Argentina
Extended compliance timelines for electromechanical systems constrain biotech firm expansion. The country's national administration of drugs, foods and medical technology applies parallel conformity assessment protocols that inflate landed costs. Buenos Aires maintains research automation demand despite import duty volatility affecting capital budgets.
Colombia
Underpenetrated clinical networks create whitespace for automated sample preparation systems. The national health regulator maintains streamlined medical device pathways for established manufacturers. Bogotá's emerging biomedical cluster attracts entry-level automation serving university research centers and private diagnostic expansion.
Chile
Copper mining revenues fund public health infrastructure modernization including laboratory automation. The national pharmaceutical regulator enforces ISO-aligned quality management standards for imported diagnostic equipment. Santiago's consolidated healthcare procurement system favors multi-vendor integrated platforms for regional hospital networks.
Latin America Laboratory Automation Market Key Industry Players
Global majors compete with regional champions across distribution network depth and regulatory navigation capabilities. The market structure consolidates around three tiers: diversified life science conglomerates with full-stack portfolios, specialized automation pure-plays with robotics-software integration, and regional distributors with service-level advantages. Strategic archetypes include validation-focused pharmaceutical specialists, high-throughput clinical screening providers, and modular research system vendors. Dominant competitive moves encompass geographic expansion through distributor acquisitions and portfolio diversification into AI-integrated software layers.
Within the diversified conglomerate tier, Danaher Corporation and Thermo Fisher Scientific exemplify scale-driven positioning through extensive Brazilian and Mexican distribution infrastructure. Agilent Technologies occupies a specialized position representing chromatography-automation bundle providers targeting pharmaceutical quality control validation requirements. These three anchors illustrate how vendor selection concentrates around regulatory compliance capabilities and multi-vendor integration expertise rather than hardware specifications alone.
| Leading Market Players |
|---|
| Abbott |
| Agilent Technologies |
| Danaher Corporation |
| Siemens Healthcare |
| Honeywell International |
| ABB |
| Rockwell Automation |
| Emerson Electric |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Certified robotics technician pools in São Paulo's industrial corridor create labor-cost differentials that widen pricing-tier spreads between premium service-bundled installations and economy hardware-only configurations. ANVISA validation documentation demands concentrate skilled labor premiums in Brazilian pharmaceutical corridors, compressing margins for mid-tier automation vendors competing on unbundled procurement models.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier pharmaceutical installations from economy clinical laboratory configurations across Latin America. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA validation grade and COFEPRIS registration status as primary differentiation drivers. Cost compression in economy tiers intensifies because import duty volatility in Argentina and technical specialist scarcity inflate landed service costs. Mid-sized clinical laboratories exhibit highest price sensitivity, while multinational pharmaceutical manufacturers prioritize compliance-grade premiums over capital expenditure minimization.
Supply Chain Analysis
Single-source vulnerability sits with precision electromechanical component suppliers concentrated in Germany, Japan, and the United States. Brazilian automation assemblers draw from these geographies for servo motors, optical sensors, and motion control systems. Tariff exposure through Argentina's extended conformity assessment protocols creates supply chain risk for biotech firms sourcing complete robotics platforms. Distribution runs through Danaher and Thermo Fisher Scientific's captive Brazilian and Mexican networks, with regional distributors capturing aftermarket service margins in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ANVISA's FDA-aligned data integrity mandates erect barrier-to-entry moats favoring incumbents with established validation documentation capabilities and regulatory affairs infrastructure.
For Market Incumbents: Anchor market position through backward integration into cloud-native LIMS development, capturing recurring software revenue streams as diagnostic chains unbundle after-sales service. Consolidate distributor relationships in São Paulo's biomedical corridor to preempt emerging entrant access to high-throughput screening installations. Prioritize certification investment for 21 CFR Part 11 equivalence ahead of ANVISA enforcement intensification. For New Entrants and Emerging Players: Mid-tier private diagnostic chains in Bogotá's emerging biomedical cluster represent underserved buyer archetype with whitespace for modular sample preparation systems. Colombia's underpenetrated clinical network offers lowest competitive density for entry-level automation configurations. Pursue direct software maintenance contracting as go-to-market angle, bypassing established distributor financing relationships that incumbent conglomerates dominate. For Investors and Strategic Acquirers: Re-rating potential sits with specialized automation pure-plays possessing AI-integrated workflow orchestration capabilities given chronic disease screening expansion across Brazilian state health systems. Long-term viability hinges on software-robotics integration depth rather than hardware manufacturing scale. Monitor ANVISA audit frequency acceleration as inflection indicator for replacement demand cycles in pharmaceutical quality control retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native LIMS Development | Captures recurring revenue as Brazilian diagnostic chains unbundle hardware from software maintenance. |
| ANVISA Validation Documentation Investment | Creates compliance moat against mid-tier competitors lacking FDA-aligned data integrity capabilities. |
| Distributor Network Consolidation | Secures channel control in São Paulo's biomedical corridor where high-throughput demand concentrates. |
| AI-Integrated Workflow Orchestration | Differentiates offerings as laboratories prioritize predictive maintenance over hardware specifications. |
| Modular Robotics Architecture Deployment | Addresses integration complexity barriers facing pharmaceutical quality control departments. |
Research Approach
Independent corroboration across primary interviews with laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists, combined with secondary validation through ANVISA registration databases, COFEPRIS medical device filings, and pharmaceutical manufacturer SEC disclosures, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing from equipment shipment data and installed base estimates ensures analytical consistency across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, application, end user, and technology segmentation dimensions. CAGRs derive from regression analysis of historical equipment procurement patterns projected against ANVISA compliance deadline schedules and chronic disease screening expansion trajectories. Forecast inputs incorporate regulatory pathway timelines, distributor network coverage metrics, and technical specialist availability indices by country.
Revisions become necessary when ANVISA enforcement intensity exceeds modeled assumptions, COFEPRIS registration streamlining reverses, or import duty volatility in Argentina disrupts capital equipment procurement cycles. Forecasts reflect documented assumptions about regulatory alignment pace and laboratory consolidation trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Global SCADA Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Smart Industries Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Warehousing Automation Equipment Market