
 Duct Tapes Market | 2026-2036
Duct Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Duct Tapes Market Analysis
The gap between contractor-grade procurement and DIY retail purchasing is collapsing as commercial buyers consolidate volume through direct distribution agreements. 3M Company leverages its adhesive chemistry portfolio to dominate specification-driven segments where engineers mandate certified performance. Berry Global Group anchors North American supply through vertical film extrusion and coating capacity. Tesa SE Group differentiates via automotive OEM qualifications that lock out commodity competitors.
Duct tape comprises a polyethylene-coated cloth backing laminated with a synthetic rubber or hot-melt adhesive layer, engineered for tensile strength exceeding 20 pounds per inch and clean removal within specified temperature windows; its primary function spans temporary sealing, bundling, and surface protection across industrial maintenance and construction phases. General-purpose grades occupy the volume base but face margin compression from private-label competition, while high-temperature formulations command premium positioning in automotive underhood and industrial process applications. Water-resistant variants lead growth in HVAC and exterior construction where moisture barriers determine warranty compliance.
EPA regulations on volatile organic compound emissions from adhesive manufacturing push reformulation toward solvent-free hot-melt systems, while OSHA workplace exposure standards elevate demand for low-odor, low-fogging products in enclosed construction environments. ASTM D3330 peel-adhesion testing and UL flame-resistance certifications function as gatekeepers for contractor specification lists, filtering out uncertified imports. Stakeholders must monitor adhesive raw material volatility and certification renewal cycles to preserve margin and access.
Market Dynamics
Contractor-grade specification tightening is compressing the historical price gap between certified industrial tapes and commodity retail products, forcing manufacturers to consolidate adhesive chemistry capabilities or exit specification-driven segments entirely.
Growth Catalysts
- Building Energy Code Stringency:Tighter HVAC efficiency mandates in Germany and the United States are expanding demand for moisture-barrier tapes that meet warranty compliance standards. Installers now specify certified grades for duct sealing applications.
- Solvent-Free Reformulation:EPA volatile organic compound regulations are accelerating hot-melt adhesive adoption across North American manufacturing facilities. Producers investing in solvent-free coating lines capture specification preference from environmentally scored procurement programs.
- Automotive Underhood Applications:High-temperature tape demand from electric vehicle thermal management systems is pulling specialized formulations into volume production. OEM qualification requirements lock in supplier relationships for platform life cycles.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic rubber and polyethylene resin costs fluctuate with crude oil derivatives, compressing margin on standard-grade products where pricing power is weakest.
- Private-Label Import Pressure:Uncertified Asian suppliers without ASTM D3330 or UL testing credentials undercut domestic producers in DIY retail channels, degrading price floors for non-specification grades.
- Substitution by Mechanical Fasteners:Zip ties and cable management systems displace bundling applications in data center and telecom infrastructure where reusability outweighs adhesive convenience.
Strategic Opportunities
- India Infrastructure Buildout:National highway and metro rail expansion creates demand for weather-resistant exterior sealing tapes in civil construction applications where specification standards are still forming.
- EU F-Gas Regulation Compliance:Refrigerant containment mandates in commercial HVAC systems are elevating tape to critical system component status, enabling premium positioning for certified low-permeability formulations.
- Direct Distribution Platforms:Contractor purchasing cooperatives and industry-specific e-procurement portals are disintermediating traditional two-step distribution, rewarding manufacturers with captive logistics capabilities.
Industry Challenges
- Adhesive Chemist Talent Scarcity:Formulation expertise for high-temperature and solvent-free systems concentrates among senior specialists approaching retirement, constraining R&D throughput for mid-tier producers.
- Certification Renewal Cycles:UL flame-resistance and ASTM peel-adhesion testing requires continuous revalidation, consuming technical resources and creating timing risk for specification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duct Tapes Market |
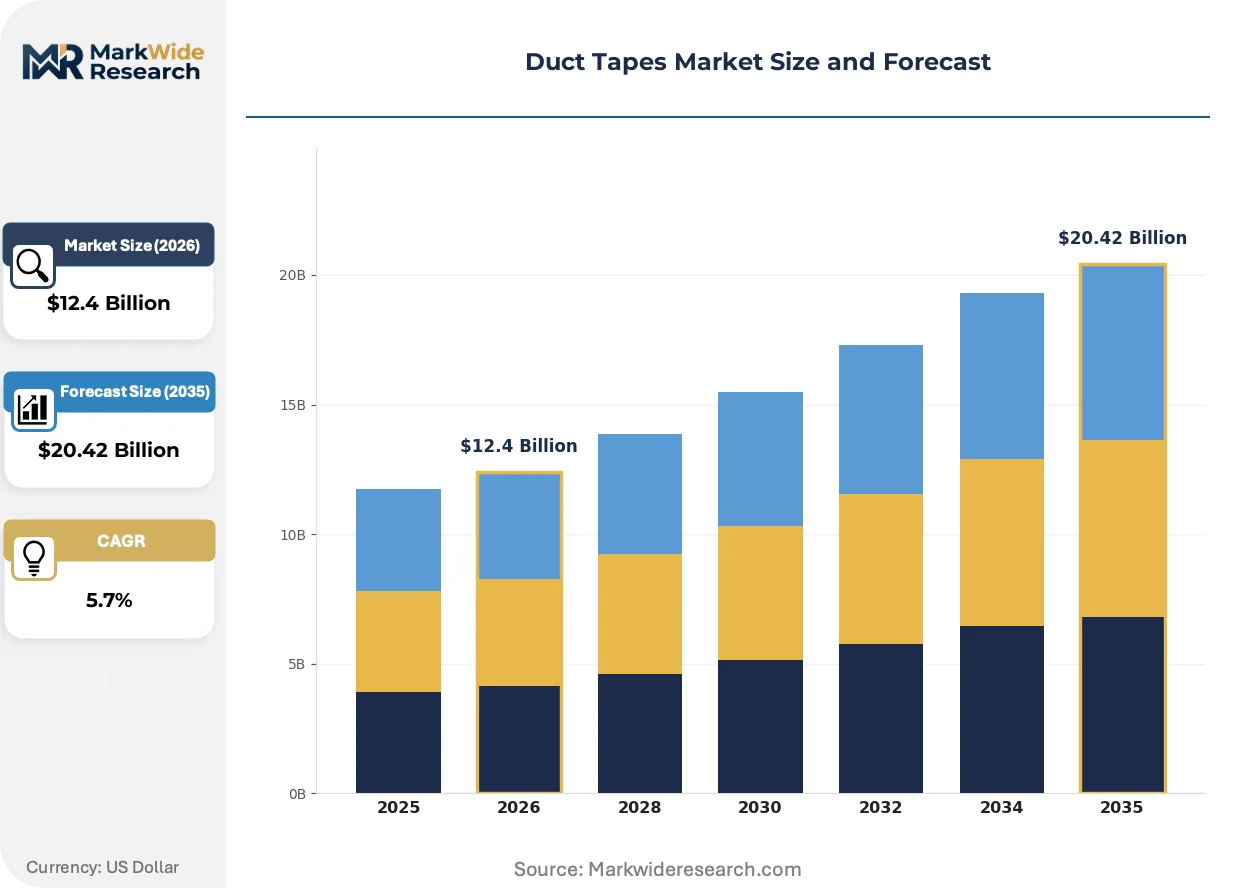
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, Water-Resistant, High-Temperature, Electrical Application: Construction, Automotive, HVAC, Household End User: Contractors, DIY Enthusiasts, Automotive Professionals, Industrial Users Distribution Channel: Online Retail, Hardware Stores, Wholesale, Supermarkets |
| Companies Covered | 3M Company, Intertape Polymer Group, Berry Global Group, Shurtape Technologies, Tesa SE Group, Scapa Group, Avery Dennison, Saint-Gobain, Pro Tapes & Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duct Tapes Market Emerging Trajectories
Adhesive chemistry advancement and procurement digitization are restructuring how performance credentials translate into commercial access, with certification authority and supply chain transparency becoming decisive competitive variables.
Hot-melt adhesive technology is bifurcating the market between solvent-capable legacy producers and reformulated clean-chemistry specialists. Automotive OEMs and commercial HVAC contractors are specifying hot-melt grades exclusively for enclosed-space applications. This technology divide is compressing margin for manufacturers lacking solvent-free coating capacity while enabling premium positioning for compliant producers.
REACH substance restrictions in Europe are eliminating specific plasticizers and tackifiers from adhesive formulations. Compounders must reformulate certified products without performance degradation or face withdrawal from EU specification lists. German and French industrial distributors are now requiring full material disclosure documentation as a listing prerequisite.
Buyer concentration among national contractor purchasing cooperatives is consolidating volume through direct manufacturer agreements. Traditional distribution intermediaries lose share in commercial construction segments where specification compliance and volume pricing dominate selection criteria. This channel restructuring is most visible in United States mechanical contracting and German facility management procurement.
Duct Tapes Market Segmentation
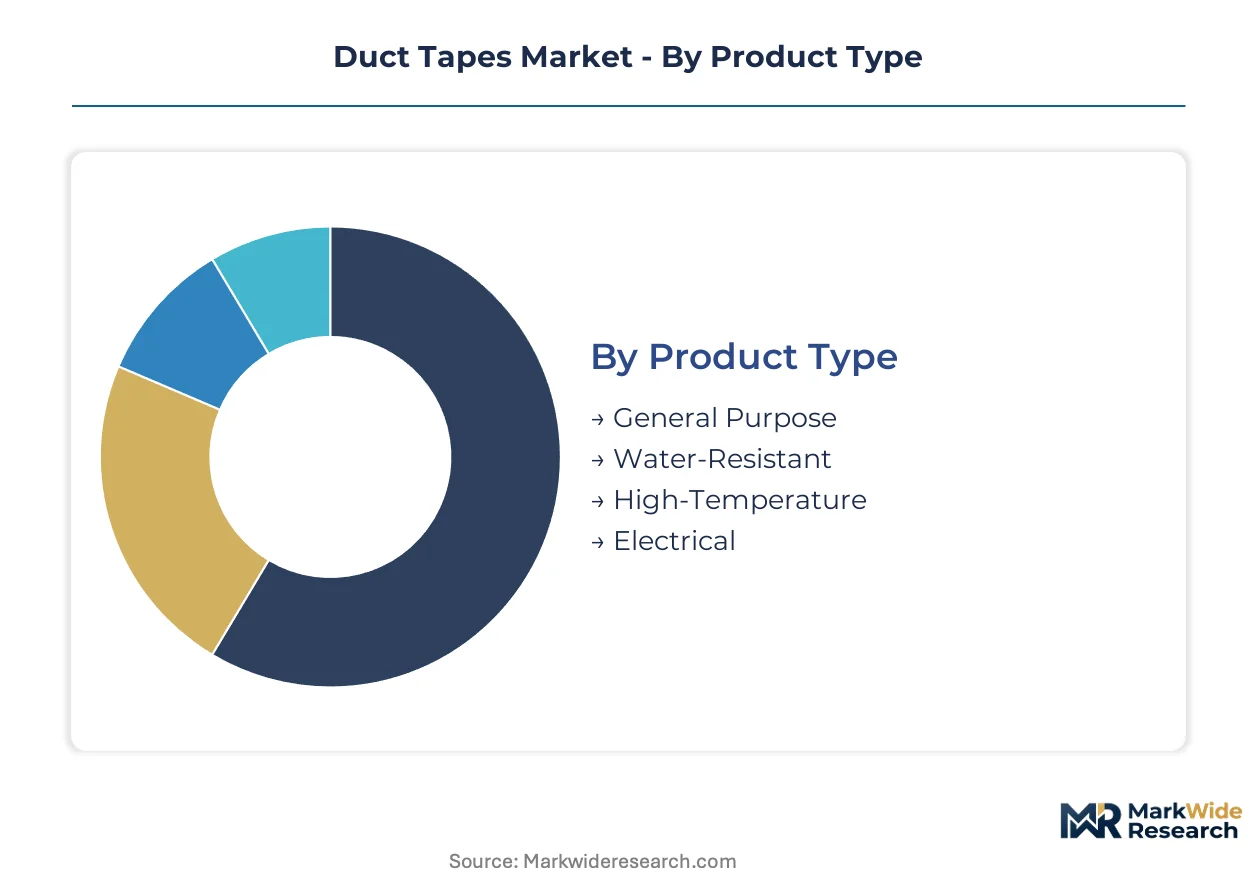
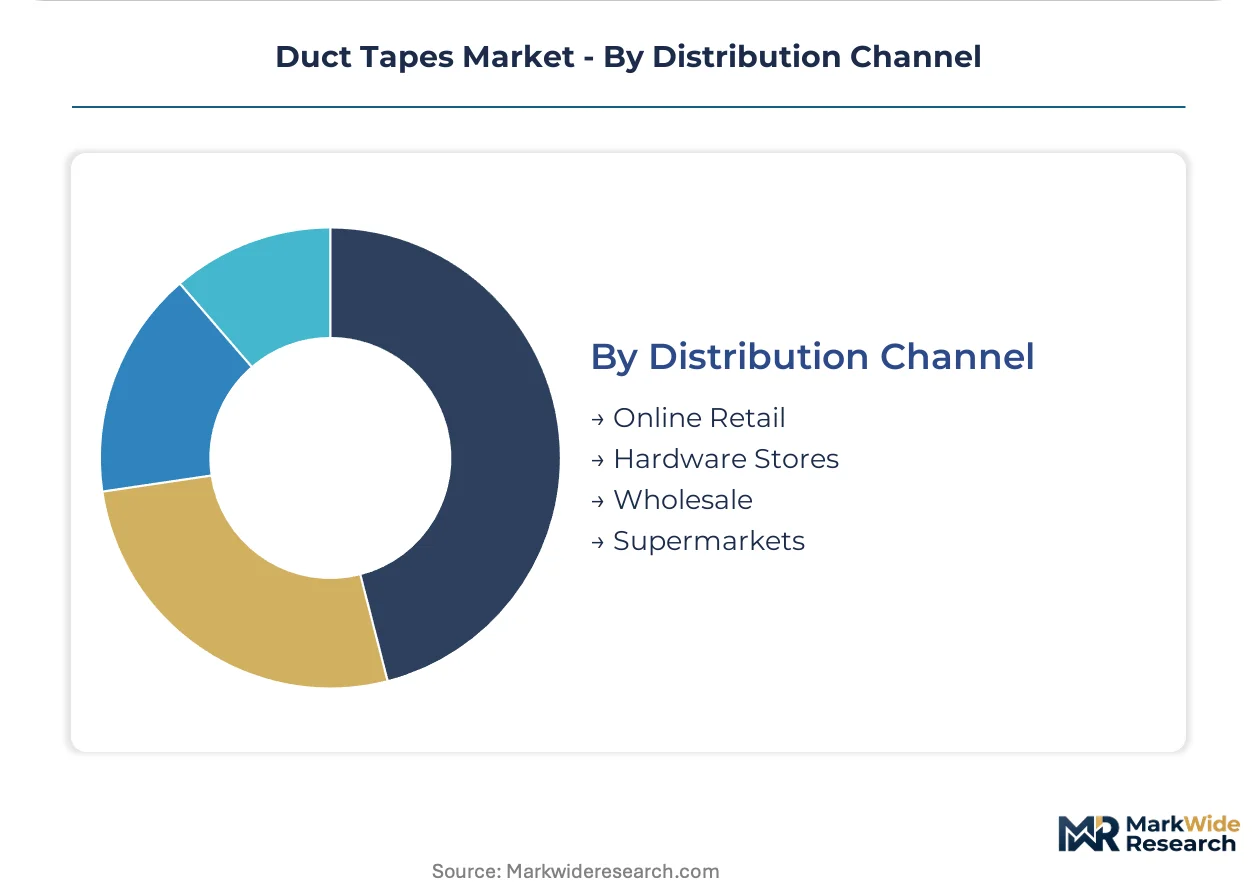
Duct tape segmentation reflects divergent procurement logics across specification-driven commercial channels and price-sensitive retail outlets. Channel strategy determines which formulations manufacturers prioritize, with certified grades flowing through contractor cooperatives and commodity products saturating big-box retail.
Product Type:
General-purpose grades move primarily through hardware stores and supermarket chains, while certified formulations concentrate in wholesale distribution serving mechanical contractors.
- General Purpose:Polyethylene-coated cloth with synthetic rubber adhesive delivers tensile strength above 20 pounds per inch for temporary sealing and bundling. Demand concentrates in DIY retail channels across the United States and Germany where price sensitivity dominates purchasing decisions.
- Water-Resistant:Moisture-barrier backing with enhanced adhesive formulation meets warranty compliance for exterior HVAC applications. Installers in North American and German construction markets specify these grades exclusively for duct sealing under tightening energy codes.
- High-Temperature:Specialized formulations withstand thermal cycling in automotive underhood and industrial process environments.
- Electrical:Insulating grades carry UL certification for voltage-rated applications in electrical contracting.
General-purpose grades dominate installed base volume. Water-resistant formulations are where expansion concentrates.
Application:
Cost tier stratification separates premium specification-grade demand from economy retail consumption across end-use segments.
- Construction:Moisture-barrier and high-strength tapes seal building envelopes and protect surfaces during active construction phases. German facility management procurement and United States mechanical contracting drive specification-grade volume through direct distribution agreements.
- HVAC:Low-permeability formulations function as critical system components for refrigerant containment and duct sealing under EU F-Gas Regulation mandates. OEM qualification requirements lock supplier relationships for platform life cycles in commercial installations.
- Automotive:Thermal management applications in electric vehicles pull specialized high-temperature grades into volume production.
- Household:General-purpose grades serve temporary repair and craft applications through retail channels.
Construction commands the largest revenue base. HVAC is climbing the fastest as energy code stringency elevates tape to system-critical status.
End User:
Customer type determines margin structure, with consolidated contractor purchasing cooperatives extracting volume pricing while fragmented DIY consumers absorb retail markups.
- Contractors:Mechanical and electrical contractors mandate ASTM D3330 and UL certified products for warranty compliance and code adherence. United States and German purchasing cooperatives consolidate volume through direct manufacturer agreements, disintermediating traditional distribution.
- Industrial Users:Maintenance departments in process industries specify high-temperature and solvent-free formulations for enclosed-space applications under OSHA exposure standards.
- Automotive Professionals:OEM and tier-one supplier technicians apply qualified grades for thermal management and wire harness bundling.
- DIY Enthusiasts:Price-driven consumers purchase general-purpose grades through retail channels with minimal specification requirements.
Contractors dominate specification-grade procurement. Industrial users are gaining share fastest as EPA regulations accelerate solvent-free reformulation demand.
Distribution Channel:
Supply concentration varies sharply by channel, with wholesale and online retail consolidating around certified suppliers while hardware stores and supermarkets absorb private-label import pressure.
- Wholesale:Two-step and direct distribution serve contractor and industrial accounts with certified products, technical documentation, and volume pricing. German and United States mechanical contracting markets show fastest channel consolidation around direct manufacturer relationships.
- Online Retail:E-procurement portals and industry-specific platforms enable specification comparison and bulk purchasing for mid-size contractors. REACH material disclosure requirements in Europe now function as listing prerequisites for German and French industrial distributors.
- Hardware Stores:Mixed-grade assortments serve professional and consumer segments with varying certification levels.
- Supermarkets:General-purpose commodity products face margin compression from uncertified Asian imports lacking ASTM or UL credentials.
Wholesale channels anchor specification-grade volume. Online retail is expanding most quickly as procurement digitization penetrates contractor purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export certified formulations to United States mechanical contractors under tightening energy code alignment, while Asian producers supply commodity grades to European retail channels facing REACH compliance barriers.
United States
Mechanical contractors in Texas and Florida drive specification-grade volume for HVAC duct sealing under ASHRAE Standard 90.1 efficiency mandates. EPA VOC regulations push adhesive reformulation toward hot-melt systems in Ohio and Illinois manufacturing corridors. The Southeast construction belt around Atlanta anchors distribution consolidation through purchasing cooperatives.
Germany
Facility management procurement in Bavaria and North Rhine-Westphalia mandates low-permeability tapes for EU F-Gas Regulation compliance in commercial refrigeration. ECHA REACH restrictions eliminate legacy plasticizers from adhesive formulations. The Stuttgart automotive cluster qualifies specialized grades for electric vehicle thermal management platforms.
China
Infrastructure buildout in Yangtze River Delta and Pearl River Delta regions absorbs weather-resistant grades for highway and metro rail sealing. MIIT industrial standards elevate certification requirements for construction material imports. Zhejiang and Jiangsu provinces concentrate private-label export capacity serving Southeast Asian retail markets.
India
National highway expansion and smart city programs in Maharashtra and Gujarat create demand for exterior-grade moisture barriers. BIS certification requirements for construction materials filter uncertified imports from specification channels. The Delhi-Mumbai Industrial Corridor anchors civil engineering procurement volume for infrastructure contractors.
Japan
Automotive OEMs in Aichi Prefecture specify high-temperature formulations for hybrid and electric vehicle wire harness bundling. METI energy efficiency standards elevate tape performance requirements in building HVAC retrofits. The Osaka-Kobe industrial zone maintains precision coating capacity for electronics-grade specialty tapes.
Duct Tapes Market Vendor Landscape
Player mix skews toward diversified adhesive conglomerates with captive chemistry capabilities. Market structure concentrates specification-grade supply among three to four integrated producers while fragmenting commodity retail across regional converters and import distributors. Two strategic archetypes dominate: vertically integrated film extruders controlling backing supply, and formulation specialists leveraging OEM qualification lock-ins. Competitive moves center on solvent-free coating line investments and direct distribution platform construction bypassing traditional two-step channels.
Within the diversified conglomerate tier, 3M Company and Berry Global Group exemplify integrated players with adhesive chemistry portfolios spanning specification-driven segments. Tesa SE Group occupies a position among European specialists differentiated through automotive OEM qualification requirements. Intertape Polymer Group and Shurtape Technologies represent North American converters consolidating volume through contractor cooperative relationships. These five anchors illustrate the competitive divide between certified specification suppliers and commodity-grade price competitors.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group |
| Berry Global Group |
| Shurtape Technologies |
| Tesa SE Group |
| Scapa Group |
| Avery Dennison |
| Saint-Gobain |
| Pro Tapes & Specialties |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day adhesive resin lead times in North American manufacturing corridors concentrate pricing power among producers with captive polyethylene extrusion capacity, while Asian import availability compresses margins for distributors lacking direct mill relationships. This inventory compression dynamic separates specification-grade suppliers commanding ASTM-certified premiums from commodity converters absorbing spot-market volatility.
Pricing Analysis
Hot-melt versus solvent-based adhesive technology pricing gaps now exceed fifteen percent at the formulation level, with next-generation low-VOC grades commanding contractor cooperative premiums and legacy solvent systems facing EPA-driven obsolescence. Three-tier pricing structure across certified industrial, commercial-grade, and private-label retail levels stratifies the market, with ASTM D3330 and UL flame-resistance credentials functioning as the primary price differentiation drivers. Pricing pressure stems from uncertified Asian imports flooding supermarket and hardware channels where DIY buyers exhibit maximum price sensitivity, while mechanical contractors in Texas and Florida show minimal elasticity for warranty-compliant grades.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for polyethylene resin and synthetic rubber feedstocks, compressing margins for converters without long-term freight contracts. Supply concentrates in the United States, Germany, and China, with Zhejiang and Jiangsu provinces anchoring private-label export capacity while Ohio and Illinois manufacturing corridors retain specification-grade coating lines. Raw material dependencies center on crude oil-derived synthetic rubber, polyethylene resin, and hot-melt adhesive polymers, exposing producers to petrochemical feedstock volatility. Single-source vulnerability concentrates in certified adhesive chemist talent pools approaching retirement age. Distribution runs through contractor purchasing cooperatives disintermediating traditional two-step wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating rapidly as mechanical contractor purchasing cooperatives in the United States and facility management alliances in Germany consolidate volume through direct manufacturer agreements, extracting price concessions and technical compliance guarantees that fragment smaller competitors.
For Market Incumbents: Fortify specification-grade positioning by investing in solvent-free hot-melt coating capacity ahead of EPA VOC enforcement deadlines, and deepen captive supply of polyethylene film backing through backward integration into extrusion assets. Certification maintenance costs for ASTM D3330 and UL flame-resistance testing function as a defensive moat against private-label import threats, while direct distribution platform construction bypasses eroding wholesale margins. For New Entrants and Emerging Players: Differentiate on REACH-compliant material disclosure documentation for German and French industrial distributors where full chemical transparency now functions as a listing prerequisite. India's infrastructure buildout offers the most penetrable geography, with national highway and metro rail expansion creating demand for weather-resistant exterior grades before BIS certification requirements fully mature. A technical specification-focused go-to-market approach targeting civil engineering procurement offices outperforms price-competing in saturated retail channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-grade supply concentrates among three to four integrated producers with adhesive chemistry portfolios, while commodity retail fragments across regional converters vulnerable to margin compression. Acquisition targets should exhibit captive film extrusion capacity and established automotive OEM qualification relationships. The signal to watch is contractor cooperative procurement digitization velocity, which accelerates volume consolidation around direct manufacturer relationships and starves traditional distribution intermediaries.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Line Investment | EPA VOC regulations in Ohio and Illinois manufacturing corridors mandate reformulation for specification access. |
| Backward Integration into Film Extrusion | Captive polyethylene backing supply insulates margin from resin spot-price volatility in Texas and Louisiana. |
| Automotive OEM Qualification Pursuit | Stuttgart and Aichi Prefecture thermal management platforms lock supplier relationships for electric vehicle life cycles. |
| Direct Distribution Platform Construction | United States mechanical cooperatives and German facility management alliances consolidate volume through manufacturer-direct agreements. |
| REACH Material Disclosure Compliance | German and French industrial distributors now require full chemical transparency as a listing prerequisite. |
Methodological Framework
A standing panel of adhesive formulation chemists, mechanical contractor procurement directors, HVAC systems engineers, and industrial distribution channel managers provided ongoing calibration throughout the study period. Primary interviews with plant managers at Ohio and Illinois coating facilities, technical R&D directors at integrated producers, and aftermarket service heads at automotive tier-one suppliers combined with secondary validation from EPA regulatory filings, ASTM certification databases, ECHA REACH substance restrictions, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up volume modeling across product grades and top-down macroeconomic triangulation anchored the analytical framework.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled segmentation dimensions including adhesive technology type, certification tier, end-use application intensity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specification-grade adoption curves and commodity-grade price elasticity observations. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance timelines and electric vehicle thermal management content-per-vehicle trajectories.
Material uncertainties — adhesive raw material volatility, certification renewal timing risks, and contractor cooperative procurement digitization velocity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and OEM qualification lock-in durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Thermal Transfer Tapes Market
Tapes
Gummed Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
India Masking Tapes Market
Tapes
Washi Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Pre-Printed Tape Market
Tapes
India Reflective Tapes Market
Tapes
PVC Tapes Market
Tapes
Global Non Woven Tape Market
Tapes
Heat Sealing Tape Market
Tapes
Dry Wall Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Paper Tapes Market
Tapes
Tissue Tapes Market
Tapes
Global Acrylic Foam Tapes Market