
 Utility Equipment Market | 2026-2036
Utility Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Equipment Market Insights
North American transformer manufacturers is rebalancing output toward higher-efficiency units after regional raw material constraints eased. Schneider Electric leverages backward integration into medium-voltage switchgear components to protect margin pools. ABB anchors its position through marine-grade transformer specialization for offshore wind interconnection. Siemens dominates European smart grid deployment with IEC 61850-compliant automation architectures.
Utility equipment encompasses electromechanical apparatus rated from low-voltage distribution through extra-high-voltage transmission, typically operating at 50-60 Hz with insulation classes up to 765 kV, designed to generate, transform, switch, or regulate electrical power for public and industrial grids. Smart Grid technology leads technology segment investment as utilities deploy two-way communication-enabled substation automation to reduce outage duration. Renewable Energy Solutions represents the fastest-expanding technology category, driven by inverter-duty transformers and hybrid switchgear for solar-wind hybrid plants. Generators retain the largest product type volume share, though margin pools concentrate in gas-insulated switchgear and dry-type transformers where technical certification barriers limit supplier entry.
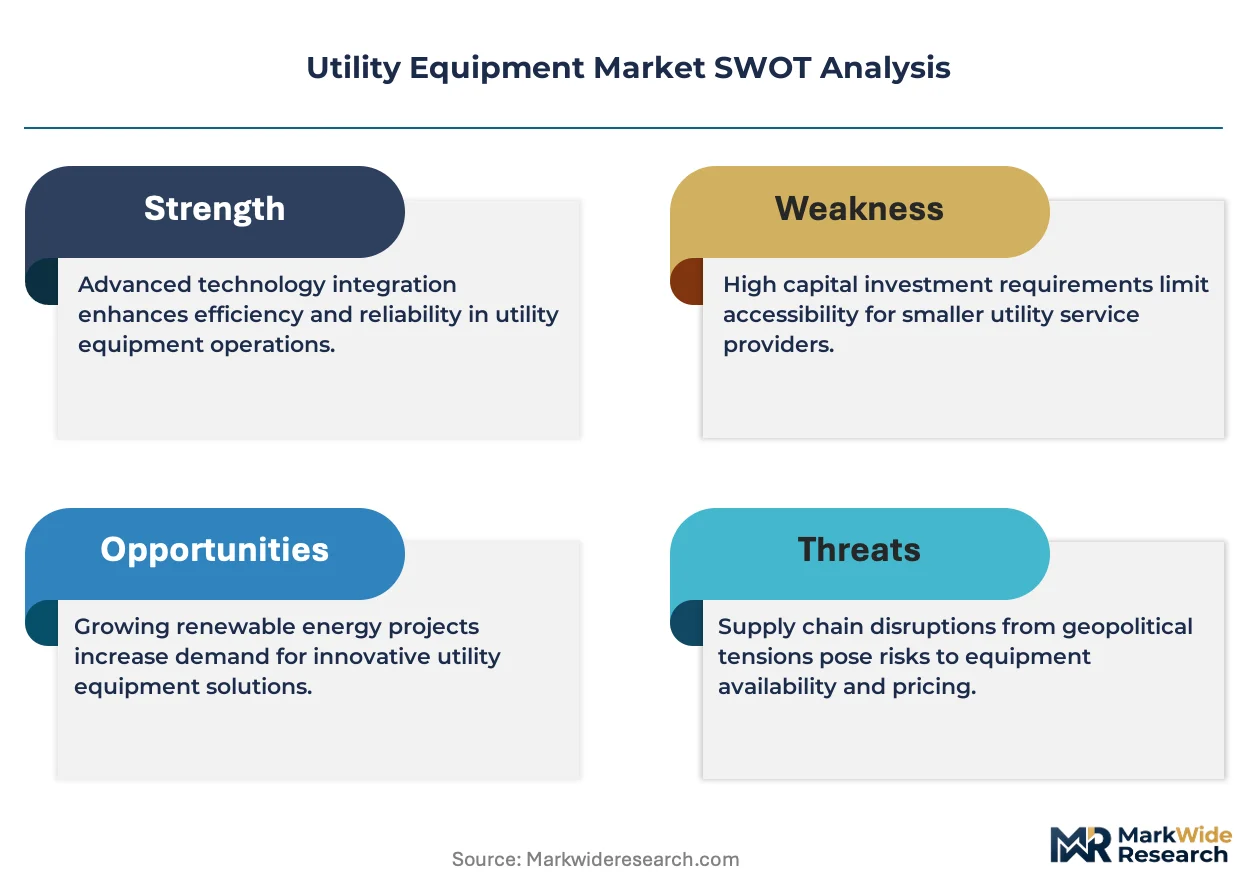
FERC Order 2222 in the United States enables distributed energy resource aggregation, compelling utilities to upgrade interoperability-certified control equipment. The EU F-Gas Regulation and REACH chemical restrictions are phasing SF6-insulated switchgear toward fluoronitrile alternatives, redirecting R&D budgets across European manufacturers. China's GB standards and dual carbon goals mandate efficiency tiers for distribution transformers, accelerating replacement cycles. Stakeholders must monitor how divergent regional decarbonization timelines reshape equipment qualification requirements and supplier qualification costs.
Market Dynamics
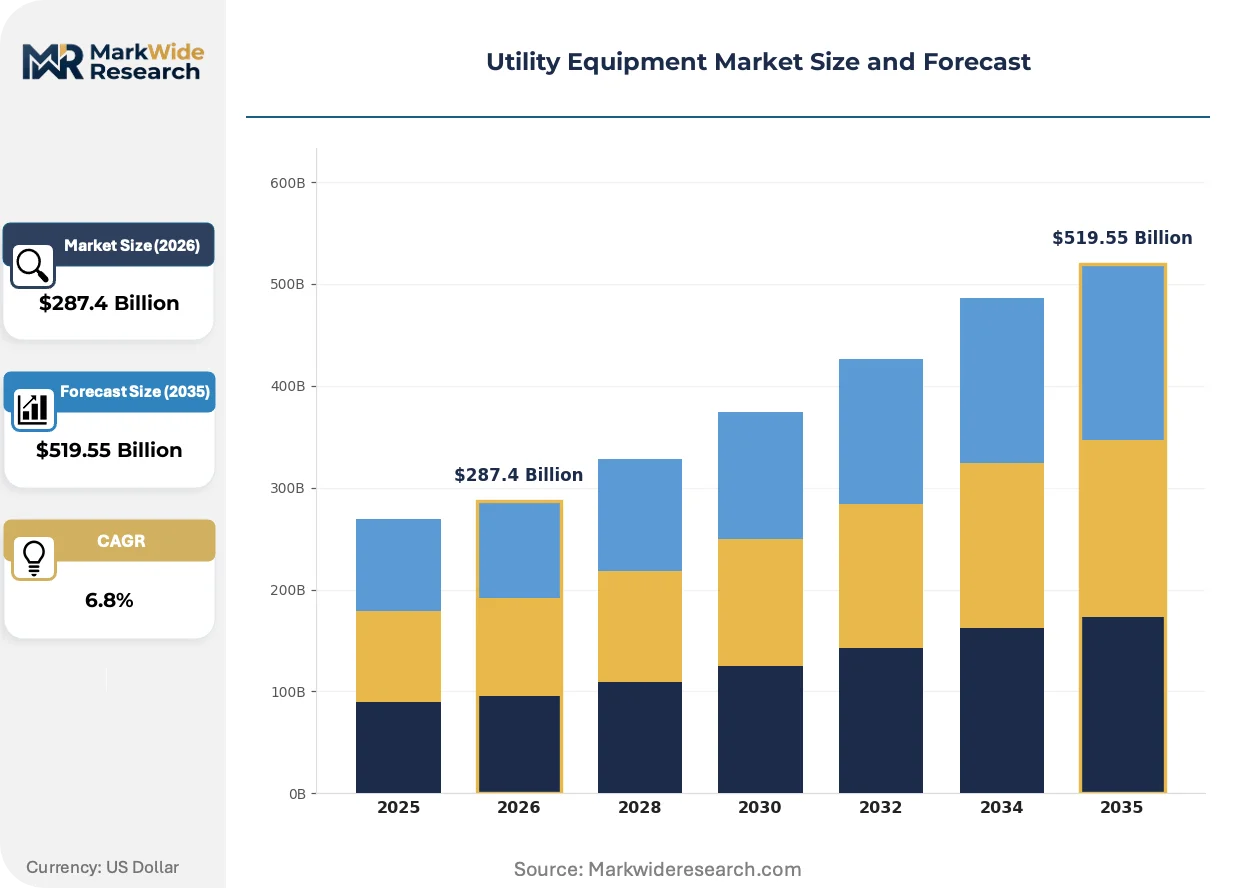
Grid hardening mandates and renewable interconnection queues are compressing equipment procurement cycles while simultaneously elevating technical qualification thresholds for transformer and switchgear suppliers.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules in the United States compel utilities to deploy interoperability-certified control systems and advanced metering infrastructure.
- China's dual carbon goals:State Grid Corporation of China and China Southern Power Grid execute massive transmission and distribution upgrade programs mandating higher-efficiency distribution transformers.
- Offshore wind interconnection:Marine-grade transformer demand accelerates as North Sea and East Asian offshore wind capacity targets require specialized subsea and platform-mounted equipment.
Market Restraints
- Grain-oriented electrical steel concentration:Cold-rolled magnetic steel supply concentrates among Japanese and South Korean mills, exposing transformer manufacturers to input cost volatility and allocation constraints.
- SF6 phase-out friction:The EU F-Gas Regulation and REACH chemical restrictions force premature retirement of gas-insulated switchgear before fluoronitrile alternatives achieve cost parity.
- Technical certification barriers:IEC 61850 compliance and IEEE 1547 interconnection standards limit supplier entry into smart grid automation and inverter-duty transformer segments.
Strategic Opportunities
- India transmission expansion:Power Grid Corporation of India's green energy corridors and interstate transmission system upgrades create demand for 765 kV class equipment and FACTS devices.
- Hybrid renewable plants:Solar-wind hybrid installations require specialized hybrid switchgear and multi-inverter transformer configurations that incumbent suppliers have not fully addressed.
- US IRA manufacturing credits:Domestic content bonuses for clean energy projects incentivize reshoring of transformer core lamination and switchgear assembly operations.
Industry Challenges
- Power systems engineering talent scarcity:Specialized skills in electromagnetic transient modeling and insulation coordination for extra-high-voltage designs concentrate among aging workforces in Germany and Japan.
- Legacy SCADA integration complexity:Utilities face protracted commissioning timelines when merging IEC 61850-compliant intelligent electronic devices with existing DNP3-based control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Equipment Market |
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $519.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Transformers, Switchgear, Circuit Breakers Technology: Smart Grid, Renewable Energy Solutions, Automation Systems, Traditional Power Systems End User: Utilities, Contractors, Municipalities, Industrial Facilities Installation: Onsite, Offsite, Indoor, Outdoor |
| Companies Covered | Schneider Electric, ABB, Siemens, General Electric, Eaton, Mitsubishi Electric, Emerson Electric, Rockwell Automation, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Equipment Market Trends and Innovations
Digital twin deployment and predictive maintenance algorithms are reconfiguring how utilities evaluate total cost of ownership across transformer and switchgear lifecycles.
Digital substation architectures are modularizing protection and control functions into software-defined intelligent electronic devices. European transmission system operators adopt these configurations fastest, with TenneT and National Grid piloting vendor-agnostic interoperability. This modularizing trend compresses hardware refresh cycles while elevating cybersecurity certification requirements.
The EU F-Gas Regulation accelerates SF6 phase-out timelines for medium-voltage switchgear. Manufacturers redirect R&D budgets toward fluoronitrile and vacuum interrupter alternatives. German and French utilities now specify SF6-free equipment for new 145 kV installations, forcing incumbent suppliers to requalify product lines.
Power purchase agreement structures now embed equipment performance guarantees. Renewable developers negotiate transformer loss warranties and availability commitments directly with manufacturers, displacing traditional distributor-mediated transactions. This contractual evolution is most visible in Texas and California solar-wind hybrid procurements.
Utility Equipment Market Segmentation
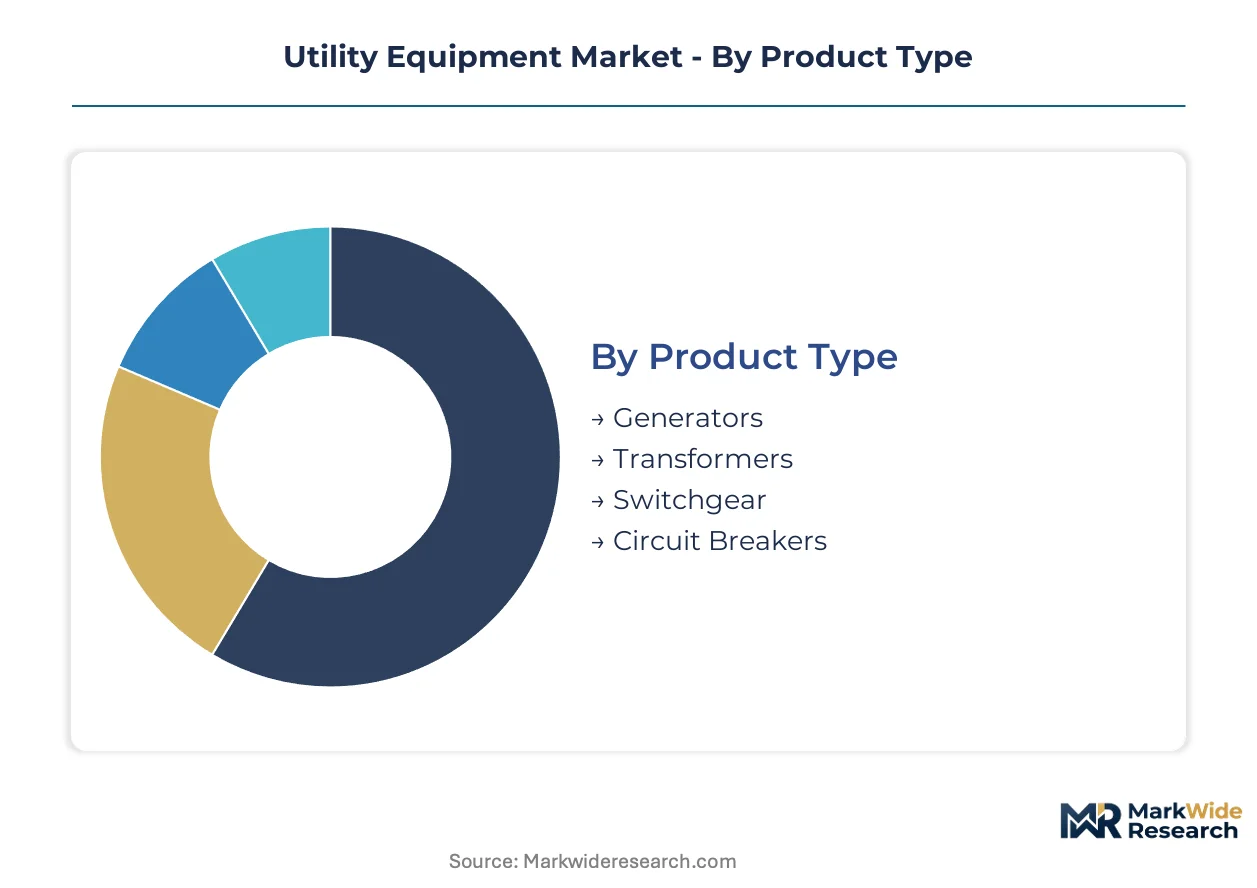
Utility equipment procurement cycles diverge sharply across segment boundaries, with certification requirements and technical qualification thresholds determining supplier eligibility and margin capture. Understanding these structural divisions reveals where standardization pressures concentrate versus where customization premiums persist.
Product Type:
Product type segmentation carries the heaviest certification burden, with IEC 61850 compliance for switchgear and IEEE C57 standards for transformers creating tiered supplier barriers.
- Generators:Synchronous and induction units rated from kilowatt-scale backup systems to multi-hundred-megawatt prime movers dominate procurement volume. Demand concentrates in gas turbine and reciprocating engine configurations for grid stabilization services, driven by utility peaking capacity mandates and data center reliability requirements.
- Transformers:Liquid-immersed and dry-type units span distribution through extra-high-voltage classes with grain-oriented electrical steel cores and mineral oil or ester-based insulation. Procurement is accelerating for inverter-duty designs serving solar and wind interconnection queues in Texas and California.
- Switchgear:Metal-clad and gas-insulated assemblies with vacuum or SF6 interruption mechanisms.
- Circuit Breakers:Air, vacuum, and SF6 interruption technologies across medium and high-voltage ratings.
Leading the category by volume: Generators. Growing fastest: Transformers.
Technology:
Technology segmentation stratifies by digital maturity, with two-way communication architectures commanding premium positioning against electromechanical legacy systems.
- Smart Grid:Two-way communication-enabled substation automation with intelligent electronic devices and advanced metering infrastructure reduces outage duration through self-healing network topologies. State Grid Corporation of China deploys these configurations most aggressively, integrating phasor measurement units across ultra-high-voltage transmission corridors.
- Renewable Energy Solutions:Inverter-duty transformers, hybrid switchgear, and power conditioning systems engineered for variable renewable output profiles. This segment climbs the fastest as solar-wind hybrid plants proliferate and interconnection standards tighten.
- Automation Systems:SCADA-integrated protection and control platforms with remote monitoring capabilities.
- Traditional Power Systems:Electromechanical relaying and manually operated switchgear in legacy infrastructure.
Smart Grid commands the highest average selling prices. Renewable Energy Solutions shows steepest expansion trajectory.
End User:
End user segmentation maps to procurement sophistication, with utilities leveraging technical specification authority that contractors and municipalities rarely match.
- Utilities:Investor-owned and public power entities with in-house engineering staffs specifying equipment through competitive bidding and long-term framework agreements. Procurement concentrates among vertically integrated utilities in the United States and state grid corporations in China, driven by grid hardening mandates and renewable portfolio standards.
- Contractors:Engineering-procurement-construction firms executing turnkey substation and generation projects.
- Municipalities:City-owned electric departments with limited technical staffing and reliance on distributor relationships.
- Industrial Facilities:Self-generating manufacturers and data center operators procuring captive power equipment.
Utilities dominate absolute spend. Industrial Facilities expand procurement most quickly.
Installation:
Installation modality determines environmental protection requirements and commissioning complexity, with outdoor and offshore specifications demanding specialized enclosures.
- Onsite:Equipment assembled and tested at final operational locations, requiring heavy-lift logistics and civil foundation work. Demand concentrates in greenfield substation construction across India's green energy corridors and offshore wind platform installations in the North Sea.
- Offsite:Factory-built modular substations and skid-mounted generator packages reducing field construction duration.
- Indoor:Metal-enclosed switchgear and dry-type transformers in controlled environments.
- Outdoor:Weather-resistant enclosures for distribution transformers and circuit breakers.
Onsite installation represents the largest addressable base. Offsite modular solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-oriented electrical steel from Japanese and South Korean mills anchors transformer manufacturing across multiple geographies, creating supply dependencies that shape procurement patterns from North America to Southeast Asia.
United States
FERC Order 2222 drives distributed energy resource aggregation upgrades, compelling utilities to deploy interoperability-certified control systems. EPA carbon emission rules and state renewable portfolio standards reshape equipment specifications toward higher-efficiency transformers. Procurement concentrates in Texas and California solar-wind hybrid corridors where interconnection queues compress delivery timelines.
China
State Grid Corporation and China Southern Power Grid execute massive transmission and distribution upgrade programs. GB standards and dual carbon goals mandate efficiency tiers for distribution transformers, accelerating replacement cycles. Manufacturing clusters in the Yangtze River Delta produce ultra-high-voltage transformer cores for domestic deployment and export markets.
Germany
TenneT and other transmission system operators pilot vendor-agnostic digital substation architectures with IEC 61850 compliance. EU F-Gas Regulation and REACH chemical restrictions phase SF6-insulated switchgear toward fluoronitrile alternatives. Industrial concentration in Bavaria and North Rhine-Westphalia hosts R&D facilities for SF6-free medium-voltage equipment.
India
Power Grid Corporation's green energy corridors and interstate transmission system upgrades create demand for 765 kV class equipment. CEA regulations and national grid codes tighten technical qualification thresholds for extra-high-voltage designs. Manufacturing activity clusters in Gujarat and Maharashtra where domestic fabrication capacity expands for distribution transformers.
Japan
METI efficiency standards and grid stability requirements sustain demand for advanced switchgear and gas turbine generators. Specialized electromagnetic transient modeling capabilities concentrate among aging engineering workforces in Nagoya and Osaka industrial zones. Domestic mills supply premium grain-oriented electrical steel to regional transformer manufacturers.
Utility Equipment Market Competitive Landscape
Global majors compete with regional champions across certification-intensive product segments, with IEC 61850 compliance and IEEE interconnection standards creating tiered supplier barriers. The vendor base stratifies between full-line electromechanical conglomerates, digital automation specialists, and component-focused niche manufacturers. Three archetypes dominate: vertically integrated European-Japanese majors with marine-grade and ultra-high-voltage capabilities; North American industrial conglomerates leveraging domestic content incentives; and Asian state-affiliated grid equipment suppliers with captive utility relationships. Competitive moves concentrate on backward integration into medium-voltage switchgear components and reshoring of transformer core lamination operations.
Among the European majors, Schneider Electric, ABB, and Siemens occupy positions spanning the premium automation and specialized transformer tiers. Schneider Electric exemplifies the backward-integrated archetype through captive medium-voltage switchgear component production. ABB anchors the marine-grade specialization vector for offshore wind interconnection applications. Siemens represents the digital automation leadership position through IEC 61850-compliant substation architectures.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens |
| General Electric |
| Eaton |
| Mitsubishi Electric |
| Emerson Electric |
| Rockwell Automation |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap transformer specialists in Germany and Japan anchor premium pricing through captive grain-oriented electrical steel relationships, while private-equity-rolled-up switchgear portfolios in North America compress margins via volume-driven procurement consolidation. Sovereign-backed Chinese producers leverage state grid corporation offtake guarantees to undercut IEC-certified competitors on price while maintaining supply security.
Pricing Analysis
Warranty and service bundling separates premium transformer suppliers from commodity competitors, with loss warranties and availability commitments now standard in renewable developer contracts. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 61850 certification grade and grain-oriented electrical steel core quality. Pricing pressure stems from raw material volatility in Japanese and South Korean steel mills. Municipalities exhibit highest price sensitivity due to limited technical staffing and distributor reliance, while offshore wind developers accept premium positioning for marine-grade specialization.
Supply Chain Analysis
Dual-sourcing mandates from European transmission system operators and US investor-owned utilities force qualification of Japanese and South Korean grain-oriented electrical steel mills alongside domestic alternatives. Cold-rolled magnetic steel cores, mineral oil insulation, and SF6 or fluoronitrile interruption media anchor transformer and switchgear production. Single-source vulnerability concentrates in premium electrical steel supply from Nippon Steel and POSCO. Distribution runs through EPC contractors for turnkey substation projects and direct framework agreements for utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into medium-voltage switchgear components and transformer core lamination operations defines competitive positioning as margin pools concentrate in certification-intensive segments. Players securing captive supply of grain-oriented electrical steel or fluoronitrile alternatives capture pricing power unavailable to assembly-only competitors.
For Market Incumbents: Anchor defensive positioning through marine-grade transformer specialization for North Sea and East Asian offshore wind interconnection queues. Deepen backward integration into intelligent electronic device manufacturing to protect margin pools from digital automation specialists. State Grid Corporation of China's dual carbon procurement mandates and FERC Order 2222 interoperability requirements threaten non-compliant suppliers with disqualification from framework agreements.
For New Entrants and Emerging Players: Launch via factory-built modular substation configurations targeting India's green energy corridor EPC contractors facing compressed commissioning timelines. Hybrid renewable plant switchgear and multi-inverter transformer configurations represent the most penetrable white space, as incumbent suppliers have underinvested in solar-wind integration engineering. Direct power purchase agreement performance guarantee negotiations with Texas and California developers bypass traditional distributor-mediated channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electromagnetic transient modeling specialists in Germany and Japan where aging workforces concentrate capabilities unavailable elsewhere. Long-term viability hinges on IEC 61850 software architecture and SF6-free switchgear R&D pipelines rather than legacy electromechanical manufacturing assets. Watch for fluoronitrile cost parity achievement as the inflection signal for SF6 phase-out acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel | Captive grain-oriented steel supply from Japanese mills insulates transformer margins from allocation constraints. |
| SF6-Free Switchgear R&D Program | Fluoronitrile and vacuum interrupter development responds to EU F-Gas Regulation phase-out mandates. |
| IEC 61850 Software Architecture Investment | Digital substation compliance secures TenneT and National Grid pilot procurement for intelligent electronic devices. |
| Marine-Grade Transformer Specialization | Offshore wind platform equipment captures premium positioning in North Sea and East Asian interconnection queues. |
| Modular Substation Factory Buildout | Skid-mounted configurations reduce field construction duration for India's Power Grid Corporation green energy corridors. |
Research Methodology
Utility regulatory filings, FERC interconnection queue databases, and State Grid Corporation procurement announcements formed the secondary backbone, supplemented by customs data on grain-oriented electrical steel trade flows and EIA generation capacity additions. Primary interviews with utility planning officers, EPC contractor procurement leads, transformer manufacturing plant managers, and grid operator protection engineers validated demand assumptions and technical qualification thresholds. Bottom-up equipment unit forecasts triangulated against top-down utility capital expenditure projections across the analysis window.
Bottom-up modeling aggregated unit shipments by product type, technology tier, and installation modality, while top-down validation anchored on transmission and distribution investment flows from regulatory filings. Segmentation dimensions spanned voltage class, digital maturity, end-user procurement sophistication, and regional decarbonization timeline. CAGRs derived from regression analysis of historical replacement cycles against renewable interconnection queue growth and grid hardening mandate intensity. Forecast inputs incorporated SF6 phase-out regulatory schedules and dual carbon goal efficiency tier implementation.
The model assumes a particular technology adoption path; alternative pathways for fluoronitrile switchgear commercialization or vacuum interrupter scaling would alter the outlook for gas-insulated equipment replacement cycles. Forecasts reflect documented assumptions on raw material allocation constraints and certification timeline standardization. Deviation in grain-oriented electrical steel mill capacity expansion or IEC 61850 interoperability testing backlog would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
AC-DC Controller Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Power Over Ethernet Lighting Market