
 Industrial Steam Peeler Market | 2026-2036
Industrial Steam Peeler Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Steam Peeler Market Outlook
After-sales service contracts for steam pressure calibration and blade refurbishment is hardening into a primary revenue stream for original equipment manufacturers. Andritz AG leverages its Austrian engineering base to sustain long-term maintenance partnerships with starch processors across Central Europe. Tomra Systems ASA anchors its competitive stance through optical sorting integration with steam peeling lines, while Kiremko BV dominates in retrofit automation for legacy batch systems in the Benelux region.
An industrial steam peeler subjects root vegetables and fruits to high-pressure saturated steam, typically operating at 150–180°C for 15–45 seconds to loosen skins before mechanical removal, primarily serving food processors seeking yield maximization and reduced water consumption versus abrasive methods. Continuous peeling systems lead capital expenditure flows due to their throughput alignment with large-scale french fry and dehydrated potato operations, while vacuum-assisted technology segments attract premium positioning from processors targeting energy recovery and lower thermal degradation of sensitive produce. Specialty peeling configurations for irregular-shaped tubers occupy narrower but higher-margin niches where standard drum designs generate unacceptable waste.
EU Green Deal emissions benchmarks and REACH chemical safety standards shape equipment specifications, with EFSA hygiene mandates further dictating stainless steel grades and clean-in-place protocol integration for cross-border market access. FDA food contact substance regulations and USDA facility sanitation requirements govern export-bound equipment from European manufacturers serving North American potato processors. Stakeholders must monitor how carbon border adjustment mechanisms and evolving water reuse standards recalibrate total cost-of-ownership calculations against upfront capital expenditure.
Market Dynamics
EU Green Deal emissions benchmarks and REACH chemical safety standards are compressing equipment replacement cycles across European food processing plants, forcing capital allocation toward continuous peeling systems with integrated energy recovery.
Growth Catalysts
- EU Green Deal compliance mandates:Food processors in Germany and the Netherlands face binding emissions reduction targets that favor steam peeling over water-intensive abrasive methods. Retrofit orders for automated lines are accelerating as 2025 benchmarks approach.
- Yield maximization technology:Vacuum-assisted steam peeling configurations recover thermal energy while reducing skin losses on irregular tubers. Starch processors and dehydrated potato operations are prioritizing these systems for margin protection.
- Water scarcity pressures:Southern European processing clusters face irrigation and industrial water restrictions that make closed-loop steam systems economically decisive versus conventional wet peeling.
Market Restraints
- Stainless steel input volatility:316L and 304 grade stainless steel price swings directly impact equipment manufacturing costs. Austrian and German fabricators pass through surcharges with 90-day lags, compressing project feasibility windows.
- Specialized maintenance concentration:Steam pressure calibration and blade refurbishment expertise clusters in Central European engineering bases. Remote processing facilities in Iberia and Eastern Europe face extended service response times.
- Abrasive peeling substitution in cost-sensitive segments:Small-scale root vegetable processors in emerging markets continue selecting mechanical abrasion systems despite higher water consumption. Capital constraints block steam technology uptake.
Strategic Opportunities
- Benelux retrofit automation:Legacy batch peeling systems in Belgian and Dutch potato processing plants offer substantial installed base conversion potential. Automation retrofit packages capture margin without full line replacement.
- Optical sorting convergence:Integration of vision systems with steam peeling lines enables real-time yield optimization and defect routing. French fry operations are piloting combined installations for quality consistency.
- Carbon border adjustment preparation:EU carbon border adjustment mechanisms scheduled for full phase-in create competitive advantage for European-manufactured equipment with documented lifecycle emissions. North American export-bound processors are pre-qualifying compliant suppliers.
Industry Challenges
- Cross-functional commissioning expertise:Steam pressure engineering, hygienic design, and automation integration require overlapping skill sets that remain scarce in regional labor markets. Project delays average 8-12 weeks for complex installations.
- Clean-in-place protocol validation:EFSA hygiene mandates demand stainless steel surface finish specifications and CIP integration that extend factory acceptance testing timelines. Small fabricators struggle with documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Steam Peeler Market |
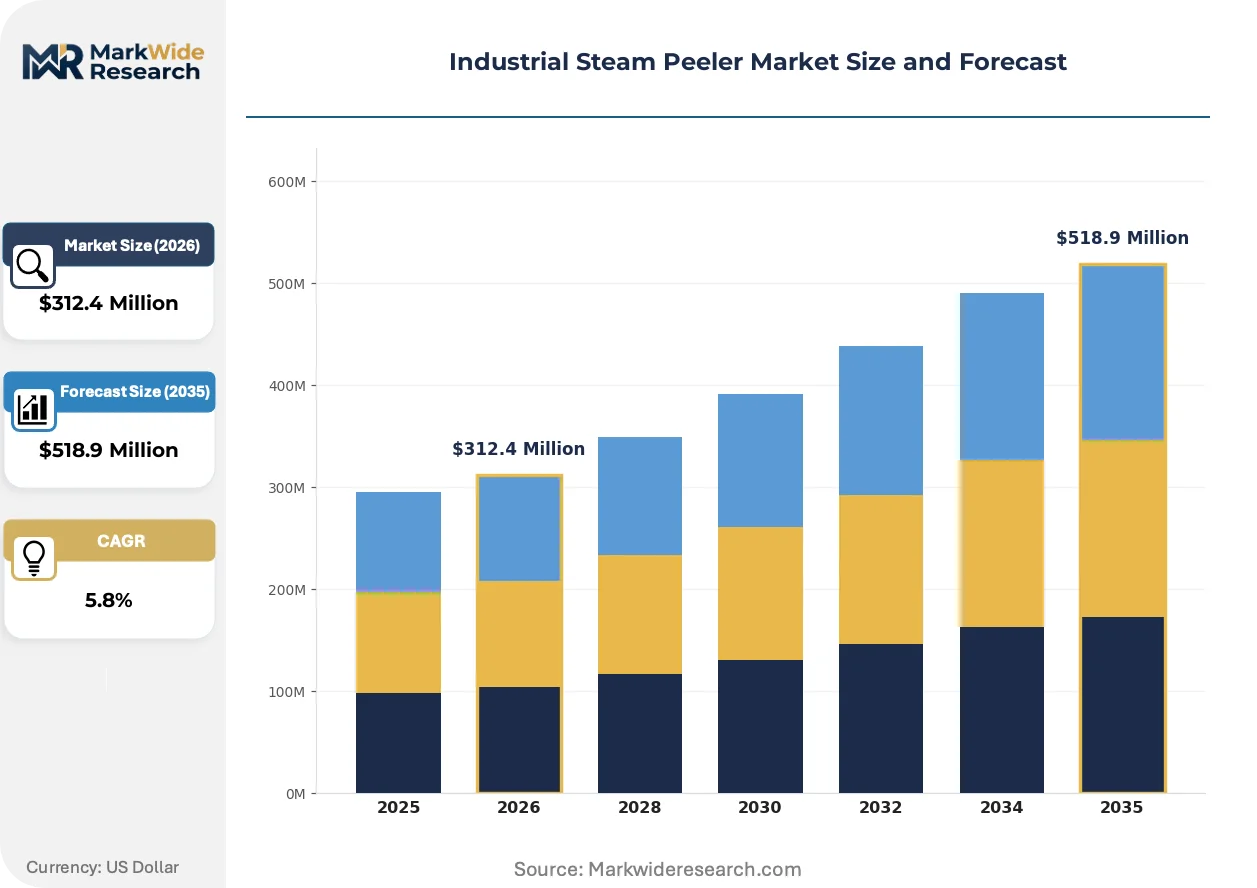
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Peeling, Continuous Peeling, Specialty Peeling, Automated Peeling End User: Food Processing, Beverage Production, Agro-processing, Pharmaceutical Technology: Steam Heating, Water Heating, Mechanical Peeling, Vacuum Technology Application: Vegetable Processing, Fruit Processing, Starch Extraction, Food Waste Management |
| Companies Covered | Andritz AG, Tomra Systems ASA, John Bean Technologies Corp., Kiremko BV, CFT Spa, Boema Spa, Turatti Srl, FENCO Food Machinery Srl, Idaho Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Steam Peeler Market Strategic Shifts
Equipment intelligence and energy recovery architectures are converging to redefine operational economics in vegetable processing. Steam peeling technology is evolving from standalone mechanical systems toward integrated production nodes.
Vacuum-assisted steam recovery systems capture latent heat from exhaust steam for pre-heating incoming product streams. Large-scale french fry processors in the Netherlands and Germany are deploying these configurations at greenfield sites. The technology is unifying thermal efficiency targets with yield optimization metrics in capital expenditure decisions.
REACH chemical safety standards and EFSA hygiene mandates are tightening material specifications for food contact surfaces. Equipment fabricators must certify 316L stainless steel grades and welded seam integrity under expanded testing protocols. Export-bound manufacturers serving North American processors face parallel FDA food contact substance and USDA facility sanitation requirements that extend design validation cycles.
Service contract unbundling is separating equipment procurement from long-term maintenance relationships. Original equipment manufacturers now compete on aftermarket calibration and blade refurbishment terms rather than upfront pricing alone. French and Belgian starch processors are negotiating outcome-based availability guarantees that shift operational risk to vendors.
Industrial Steam Peeler Market Segmentation
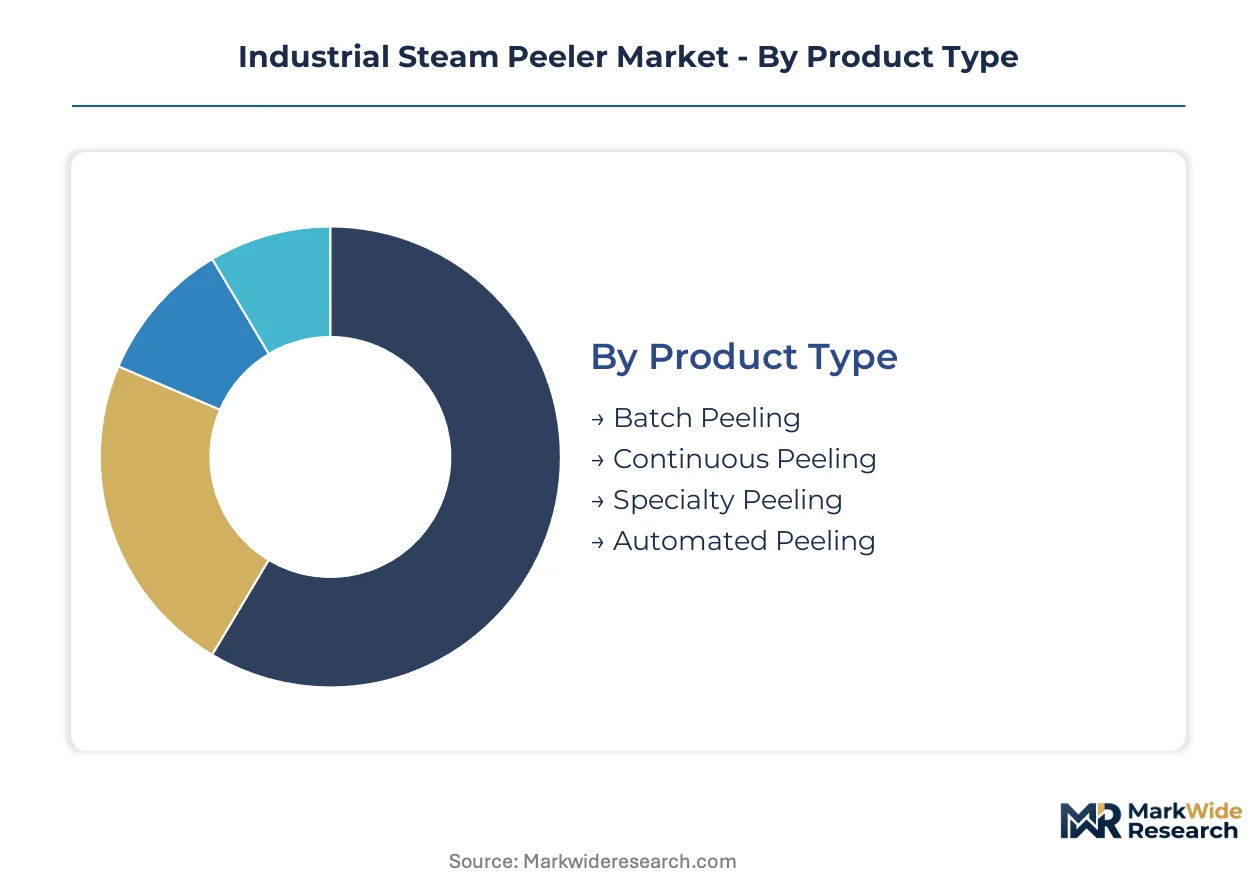
Segmentation in the industrial steam peeler market reveals how equipment specifications diverge based on throughput requirements, regulatory exposure, and thermal efficiency priorities. Processors select configurations that balance capital intensity against operational cost structures shaped by energy pricing and water availability.
Product Type:
Supply concentration among large-scale french fry and dehydrated potato operations favors continuous configurations, while batch systems retain footholds in smaller processing clusters.
- Continuous Peeling:Drum or screw-conveyor designs process 10-50 tonnes per hour with integrated steam recovery. Dutch and German processors deploying these systems at greenfield sites cite EU Green Deal emissions benchmarks as decisive factors in vendor selection.
- Batch Peeling:Vessel-based systems accommodate 500-2000 kg cycles with lower capital outlay. Belgian starch processors operate substantial installed bases requiring automation retrofit rather than full replacement.
- Specialty Peeling:Configurations for irregular tubers and delicate fruits command premium positioning through reduced mechanical damage.
- Automated Peeling:Robotic loading and vision-guided sorting integration reduces labor dependency in high-wage European markets.
Today's leader: Continuous Peeling. Tomorrow's challenger: Automated Peeling.
End User:
Cost tier differentiation separates capital-intensive food processors from price-sensitive agro-processing cooperatives.
- Food Processing:Large-scale potato and vegetable processors dominate equipment procurement volumes. French fry operations in the Netherlands prioritize vacuum-assisted thermal recovery for margin protection against volatile energy input costs.
- Agro-processing:Root vegetable cooperatives and regional starch extractors favor refurbished batch systems. Iberian processing clusters face extended service response times from Central European engineering bases.
- Beverage Production:Citrus and tropical fruit processors apply steam peeling for essential oil recovery prior to juice extraction.
- Pharmaceutical:Botanical extraction operations require validated clean-in-place protocols and surface finish certifications under EFSA hygiene mandates.
Food Processing commands current procurement volumes. Agro-processing offers the steepest expansion trajectory as irrigation restrictions spread across Southern Europe.
Technology:
Application-specific thermal requirements segment the vendor landscape between saturated steam specialists and hybrid system providers.
- Steam Heating:High-pressure saturated steam at 150-180°C remains the dominant thermal medium. Vacuum-assisted variants recover latent heat for pre-heating incoming product streams at large-scale Dutch installations.
- Vacuum Technology:Reduced-pressure configurations lower boiling points to minimize thermal degradation of sensitive produce. Premium positioning targets processors seeking energy recovery and yield maximization on irregular tubers.
- Water Heating:Low-temperature wet peeling persists in cost-sensitive segments despite higher consumption profiles.
- Mechanical Peeling:Abrasive drum systems retain market share where water scarcity pressures remain absent and capital constraints block steam technology uptake.
Steam Heating anchors current technology selection. Vacuum Technology is gaining share fastest as energy recovery economics improve.
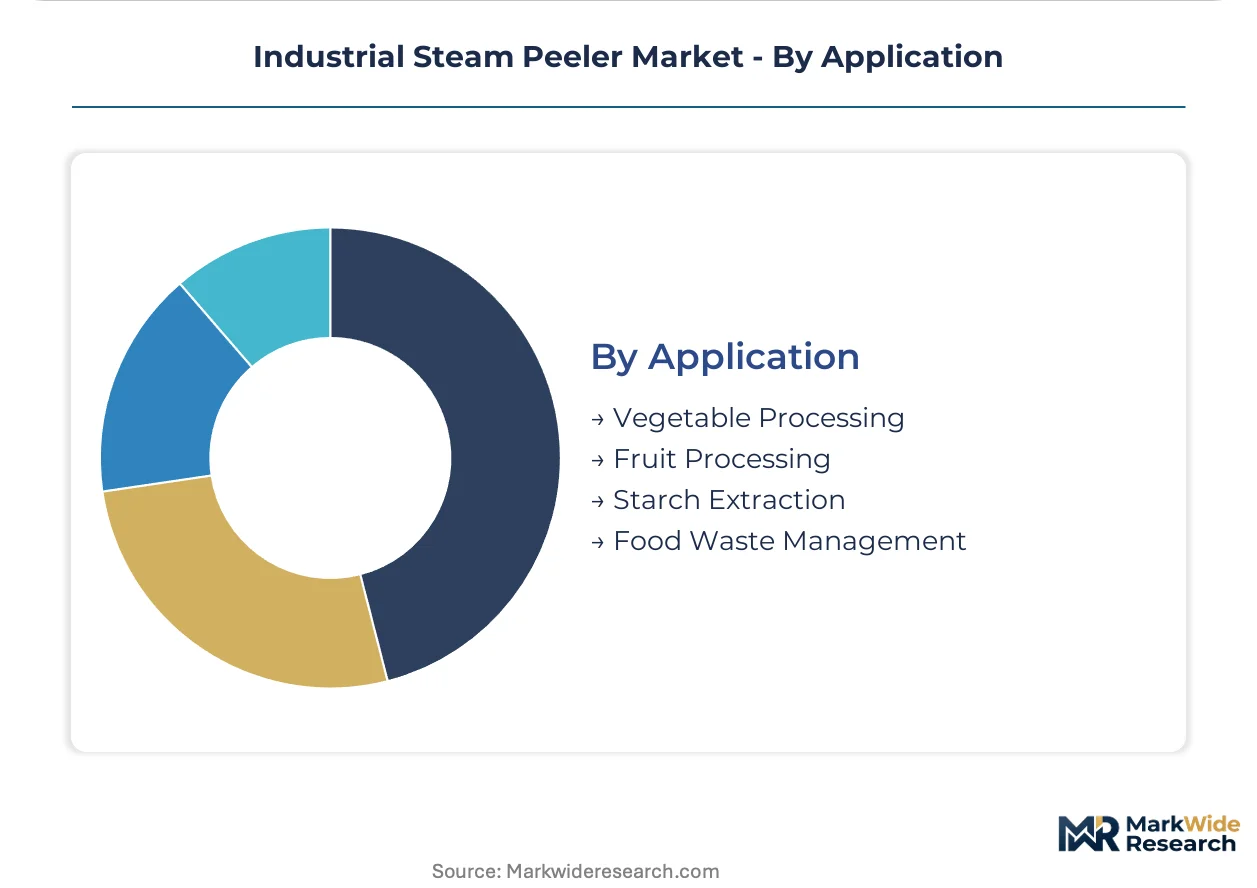
Application:
Customer type concentration varies by produce category, with vegetable processors driving standardization and starch extractors demanding specialized configurations.
- Vegetable Processing:Potato, carrot, and beet operations constitute the core demand base. German processors expanding automated lines cite binding emissions reduction targets approaching.
- Starch Extraction:Root-to-starch operations require gentle skin removal to preserve tuber integrity prior to milling. Austrian engineering bases sustain long-term maintenance partnerships with Central European starch processors.
- Fruit Processing:Peach, tomato, and citrus applications demand shorter exposure cycles to prevent thermal degradation.
- Food Waste Management:Peel valorization for animal feed and biochemical feedstocks creates secondary equipment demand from circular economy investments.
Vegetable Processing dominates current deployment. Starch Extraction represents the most defensible niche for specialized equipment margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands outpace neighboring markets in continuous steam peeler deployment, while Belgian processors favor retrofit automation over greenfield investments. Divergent capital strategies across these three Benelux-adjacent markets illustrate how EU Green Deal compliance timelines reshape equipment procurement geography.
Germany
Large-scale french fry operations in Lower Saxony and Bavaria drive demand for vacuum-assisted thermal recovery systems. The EU Green Deal's binding emissions benchmarks for 2025 accelerate replacement of water-intensive abrasive lines. Stuttgart-based engineering consultancies coordinate turnkey installations for potato processors seeking integrated energy recovery.
Netherlands
Starch extraction facilities and dehydrated potato plants prioritize closed-loop steam systems amid irrigation restrictions on agricultural water use. REACH chemical safety standards and EFSA hygiene mandates dictate 316L stainless steel specifications for cross-border export equipment. Eindhoven-region fabricators supply greenfield installations with documented lifecycle emissions for carbon border adjustment preparation.
Belgium
Legacy batch peeling systems in Flemish potato processing clusters create substantial retrofit automation opportunities. Capital constraints at mid-scale starch cooperatives favor automation packages over full line replacement. Antwerp-area engineering firms specialize in blade refurbishment and steam pressure calibration for installed base extensions.
United States
Idaho and Washington state potato processors import European-manufactured equipment subject to FDA food contact substance and USDA facility sanitation requirements. North American operations pre-qualify suppliers with documented EU emissions compliance to anticipate carbon border adjustment mechanisms. Pacific Northwest processing clusters pilot optical sorting integration with steam peeling lines.
France
Specialty peeling configurations for irregular tubers serve niche demand from regional starch extractors in Picardy and Hauts-de-France. EFSA hygiene mandates extend factory acceptance testing timelines for clean-in-place protocol validation. Lyon-based equipment distributors coordinate aftermarket service contracts for Central European OEMs serving French processors.
Industrial Steam Peeler Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with Austrian and Dutch engineering bases sustaining premium positioning through long-term maintenance partnerships. The vendor landscape concentrates around three strategic archetypes: integrated automation providers bundling optical sorting with thermal processing, retrofit specialists converting legacy batch systems, and stainless steel fabricators serving cost-sensitive emerging markets. Competitive moves center on geographic expansion through regional service hubs and technology licensing agreements that transfer vacuum-assisted thermal recovery designs to qualified fabricators.
Within the integrated automation tier, Andritz AG and Tomra Systems ASA exemplify divergent approaches to equipment intelligence convergence. Andritz leverages its Austrian engineering base to anchor maintenance partnerships with Central European starch processors, while Tomra represents the optical sorting integration archetype for yield optimization in french fry operations. Kiremko BV occupies the retrofit specialization position, serving Benelux legacy installed bases with automation packages that extend batch system lifecycles without full replacement capital outlay.
| Leading Market Players |
|---|
| Andritz AG |
| Tomra Systems ASA |
| John Bean Technologies Corp. |
| Kiremko BV |
| CFT Spa |
| Boema Spa |
| Turatti Srl |
| FENCO Food Machinery Srl |
| Idaho Steel |
| Others |
Value Chain & Pricing Dynamics
316L stainless steel price volatility cascades from Austrian and German fabricators through to equipment procurement decisions, with 90-day surcharge lags compressing project feasibility windows for processors balancing capital intensity against EU Green Deal compliance timelines.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for continuous peeling systems as vacuum-assisted thermal recovery configurations command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates integrated automation providers from retrofit specialists and stainless steel fabricators. Cost compression in standard-grade equipment is intensifying because abrasive peeling substitution persists in cost-sensitive segments. Small-scale root vegetable processors exhibit highest price sensitivity, while large-scale french fry operations prioritize yield optimization metrics over upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Central European engineering bases for steam pressure calibration and blade refurbishment expertise. Manufacturing concentration in Austria, Germany, and the Netherlands draws from 316L and 304 grade stainless steel inputs, precision-machined pressure vessels, and optical sorting components. Logistics chokepoints emerge from extended service response times to remote Iberian and Eastern European processing facilities. Distribution runs through regional service hubs anchored by Eindhoven-region fabricators and Antwerp-area engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service contracts and vacuum-assisted thermal recovery configurations, as energy recovery economics displace capital-only procurement models across EU Green Deal-compliant processing clusters.
For Market Incumbents: Deepen long-term maintenance partnerships with starch processors through outcome-based availability guarantees that shift operational risk from buyers. Extend automation retrofit capabilities for legacy batch systems in Belgian and Dutch installed bases to capture margin without full line replacement capital outlay. Counter abrasive peeling substitution in emerging markets by bundling after-sales service contracts into equipment financing structures. For New Entrants and Emerging Players: Begin with Benelux retrofit automation packages for mid-scale starch cooperatives facing capital constraints against greenfield investments. Target Iberian processing clusters where water scarcity pressures create decisive economic advantage for closed-loop steam systems over wet peeling. Pursue technology licensing agreements that transfer vacuum-assisted thermal recovery designs to qualified regional fabricators lacking in-house R&D capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized maintenance expertise clusters in Central European engineering bases with limited geographic replication. Favor acquisition targets with documented EU emissions compliance for carbon border adjustment preparation and established aftermarket revenue streams. Watch optical sorting integration pilots in Pacific Northwest processing clusters as inflection indicator for yield optimization technology convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Contract Unbundling | Separates equipment procurement from long-term calibration partnerships, shifting vendor competition to availability guarantees. |
| Vacuum-Assisted Thermal Recovery Deployment | Captures latent heat from exhaust steam for pre-heating at Dutch greenfield sites, unifying efficiency with yield metrics. |
| Optical Sorting Integration | Enables real-time yield optimization and defect routing for french fry operations piloting combined installations. |
| Retrofit Automation Packaging | Extends batch system lifecycles in Belgian starch cooperatives without full replacement capital outlay. |
| Carbon Border Adjustment Preparation | Documents lifecycle emissions for European-manufactured equipment serving North American export-bound processors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation from customs and trade data, SEC filings, food processing industry association reports, and equipment registration databases. Bottom-up equipment shipment tracking and top-down processing capacity expansion analysis were triangulated against capital expenditure disclosures from major potato and starch processors.
Historical reference periods anchored the projection framework to established replacement cycle patterns and regulatory compliance timelines across the analysis window. Segmentation modeling incorporated product type, end user category, technology variant, and application-specific thermal requirements. CAGRs were derived from equipment order flow analysis and installed base depreciation schedules, with forecast inputs including EU Green Deal emissions benchmark phasing, stainless steel price indices, and irrigation restriction severity across Southern European processing clusters.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting stainless steel input costs, unanticipated REACH chemical safety standard amendments, and disruptive peeling technology substitutions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Global Shawarma Machines Market