
 Walk-In Refrigerator Market | 2026-2036
Walk-In Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Walk-In Refrigerator Market Analysis
ENERGY STAR certification for commercial refrigeration equipment is reorganizing competitive positioning among walk-in refrigerator suppliers. Carrier Global Corporation leverages its scale in refrigerant-based systems to serve national grocery chains. Panasonic Corporation anchors its position through compressor technology leadership and direct expansion system integration. Hussmann Corporation specializes in custom designs for food distributors requiring precise temperature zoning.
A walk-in refrigerator is an enclosed refrigerated storage space with floor area typically exceeding 15 square feet, constructed with insulated wall panels containing polyurethane foam cores between metal skins, designed to maintain temperatures between 28°F and 55°F depending on stored product requirements. Modular units dominate new installations due to faster deployment timelines and lower site preparation costs. Energy-efficient options command premium positioning as utility rebate programs and operating cost scrutiny intensify among restaurants and grocery stores. Eco-friendly refrigerants represent the fastest-growing technology dimension as operators phase down hydrofluorocarbon dependence.
The US Department of Energy sets minimum efficiency standards for walk-in cooler equipment under federal appliance regulations, while the EPA enforces refrigerant management requirements through Section 608 of the Clean Air Act. California's Title 24 building energy code imposes additional constraints on commercial refrigeration installations in the nation's largest state economy. Stakeholders must monitor evolving refrigerant phase-down schedules and regional efficiency mandates when planning fleet replacement cycles and capital allocation across installation types.
Market Dynamics
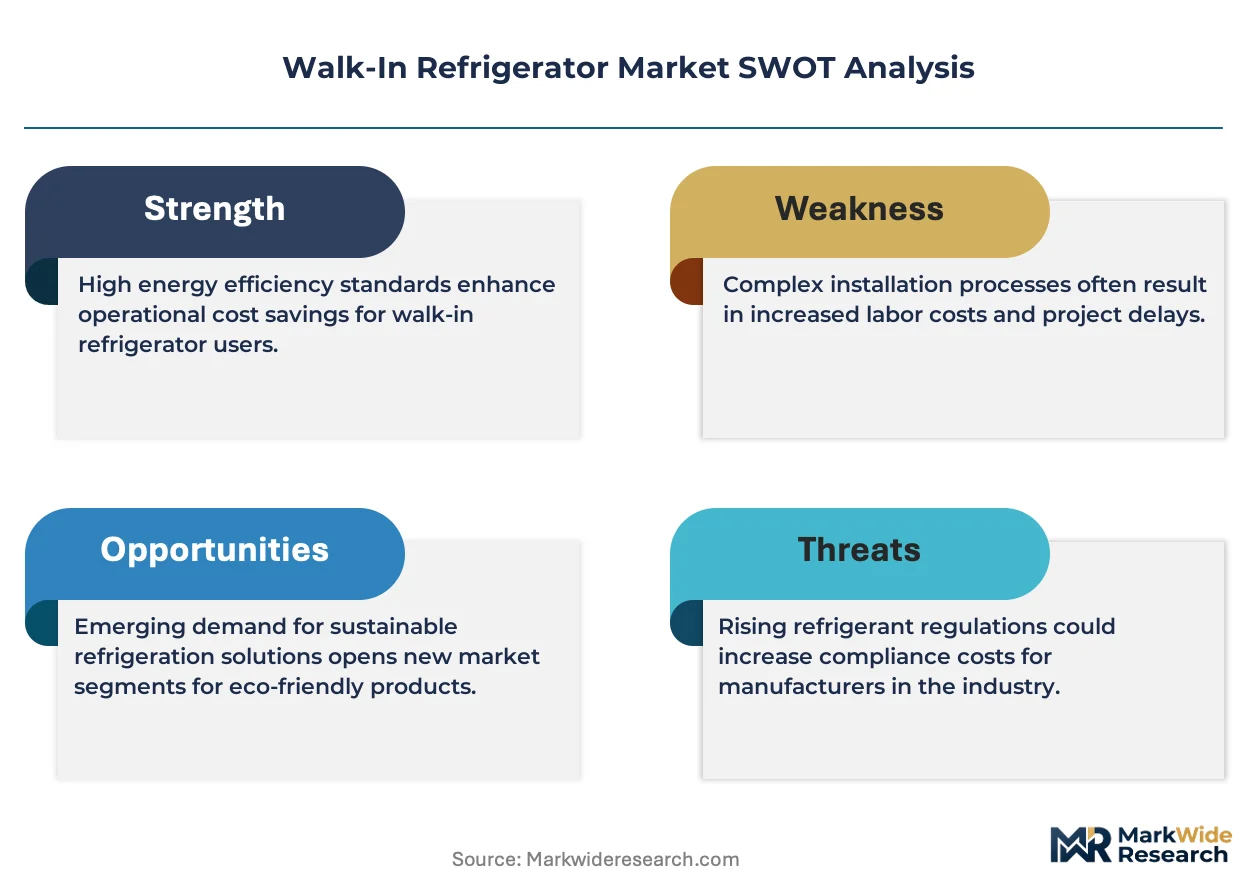
The US Department of Energy's commercial refrigeration efficiency standards are forcing operators toward energy-efficient equipment and eco-friendly refrigerants, restructuring capital allocation across restaurant and grocery installations.
Growth Catalysts
- California Title 24 building energy code:Stringent constraints on commercial refrigeration installations in the nation's largest state economy accelerate replacement cycles toward compliant systems.
- Ghost kitchen proliferation:Delivery-only food preparation facilities require expanded cold storage footprints, generating demand for modular walk-in units with rapid deployment timelines.
- Polyurethane foam insulation advances:Improved thermal performance in panel cores reduces energy consumption and qualifies operators for utility rebate programs.
Market Restraints
- Steel and aluminum input volatility:Metal skin materials for insulated panels face price instability, compressing margins for manufacturers without long-term supply agreements.
- Refrigerant supply concentration:Hydrofluorocarbon alternatives depend on limited production facilities in China and India, creating procurement bottlenecks during phase-down transitions.
- Site preparation complexity:Existing building infrastructure often requires costly electrical and drainage upgrades before walk-in installation, delaying project timelines.
Strategic Opportunities
- Texas food service corridor expansion:Dallas, Houston, and Austin metro areas exhibit elevated warehouse construction activity and restaurant density, creating concentrated demand pockets.
- Remote temperature monitoring convergence:Integration of IoT sensors with compressor systems enables predictive maintenance contracts and recurring revenue streams.
- Inflation Reduction Act commercial deductions:Section 179D energy-efficient building provisions incentivize grocery chains to accelerate cooler fleet replacement.
Industry Challenges
- EPA Section 608 technician certification:Refrigerant handling compliance requires specialized workforce credentials that lag current installation demand, extending project lead times.
- Legacy control system integration:New energy-efficient units must interface with existing building management systems, complicating commissioning and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walk-In Refrigerator Market |
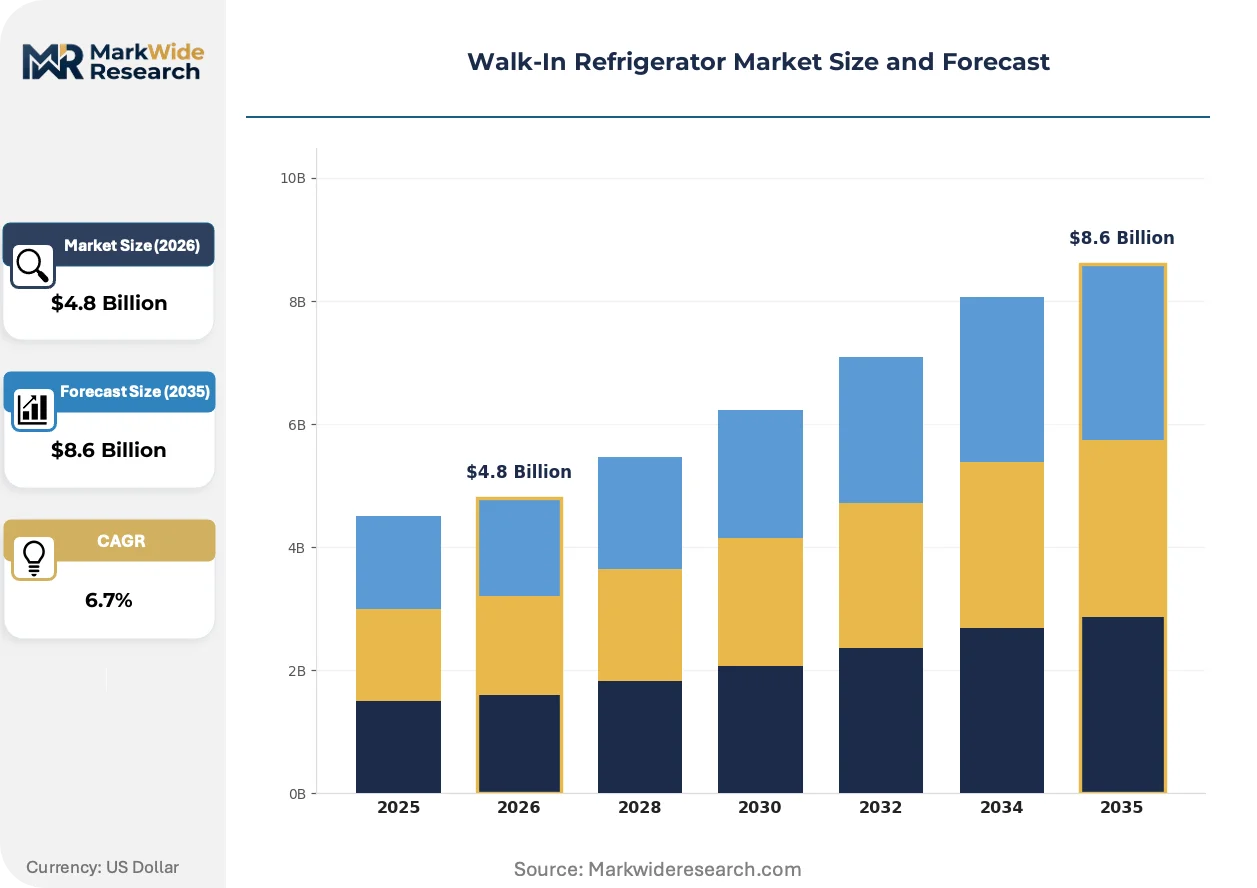
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Custom Designs, Standard Models, Energy-Efficient Options End User: Restaurants, Grocery Stores, Catering Services, Food Distributors Technology: Direct Expansion, Refrigerant-Based, Hybrid Systems, Eco-Friendly Refrigerants Installation: Indoor Installation, Outdoor Installation, Custom Build-Outs, Pre-Fabricated Units |
| Companies Covered | Hussmann Corporation, Panasonic Corporation, Carrier Global Corporation, Kolpak, Norlake, Inc., Master-Bilt Products LLC, Danfoss A/S, Amerikooler LLC, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walk-In Refrigerator Market Emerging Trajectories
Refrigeration technology is fragmenting across multiple performance tiers as operators balance first-cost constraints against lifetime operating expense reduction mandates.
Natural refrigerant adoption is fragmenting the compressor technology landscape as carbon dioxide and propane systems gain traction in supermarket applications. Regional grocery chains in California and Washington are piloting transcritical CO2 installations despite higher upfront capital requirements. Equipment suppliers must now support three parallel refrigerant architectures, complicating inventory and service training programs.
EPA enforcement of hydrofluorocarbon phase-down schedules under the AIM Act is compressing equipment procurement timelines for national restaurant chains. Operators face accelerated depreciation of existing assets as 2027 production limits approach for high-global-warming-potential refrigerants. Cold storage facilities in Florida and Arizona are front-loading replacement investments to secure available equipment before supply constraints materialize.
Prepared meal delivery operators are consolidating procurement authority at the corporate level, displacing franchisee-directed equipment purchasing. Ghost kitchen developers now specify standardized cooler configurations across multi-state footprints, reducing customization revenue for regional fabricators. This concentration is most visible in Texas and Georgia, where cloud kitchen operators negotiate national supply agreements with Hussmann and Carrier.
Walk-In Refrigerator Market Segmentation
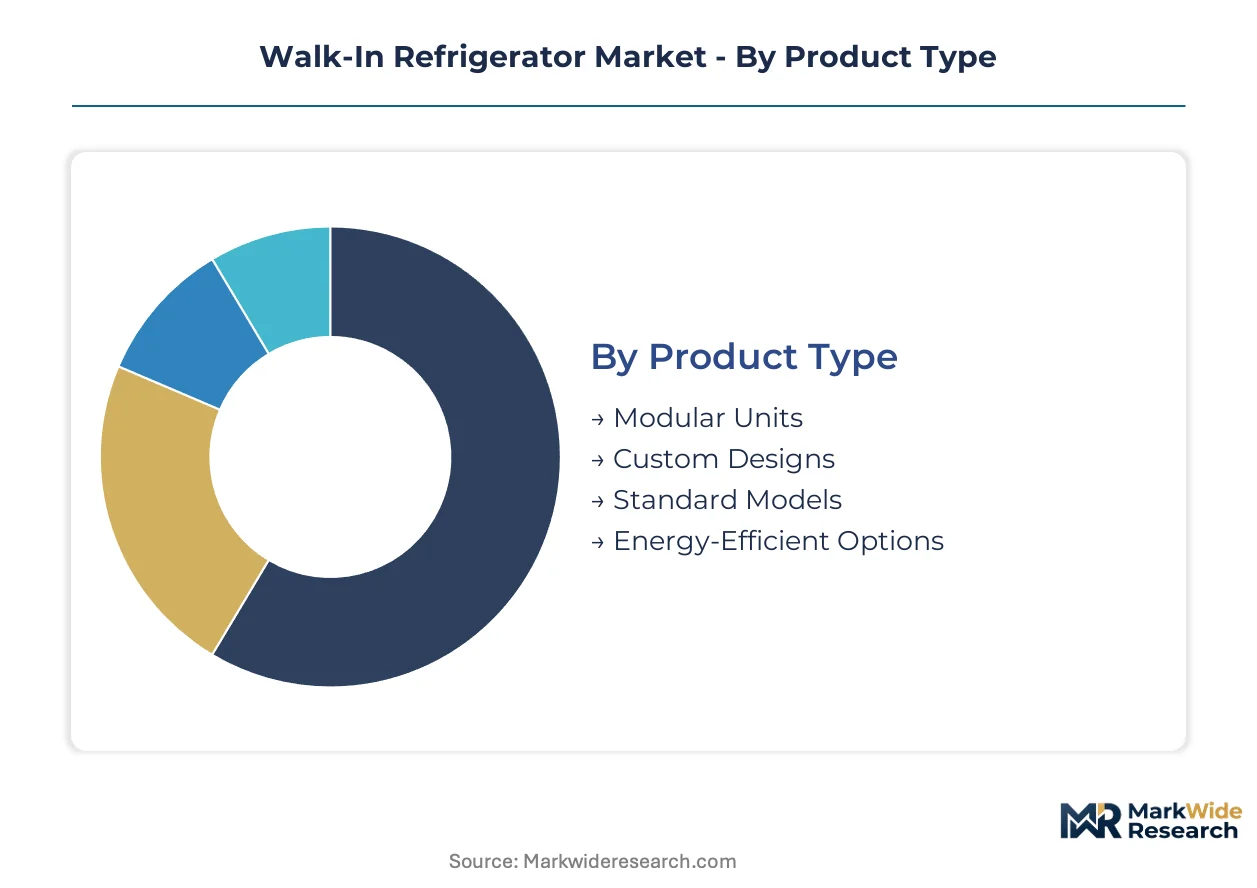
Walk-in refrigerator procurement patterns diverge sharply across product architectures and operational contexts. Regulatory pressure on refrigerant chemistry and installation site constraints reshape how operators evaluate segment trade-offs.
Product Type:
EPA efficiency mandates and utility rebate eligibility criteria create divergent compliance pathways across construction formats.
- Modular Units:Factory-assembled polyurethane foam panels with metal skins enable rapid field installation without specialized fabrication. Ghost kitchen operators in Texas and Florida prioritize these configurations to compress deployment timelines for delivery-only facilities.
- Custom Designs:Site-specific dimensional engineering accommodates irregular building envelopes and precise temperature zoning requirements. Food distributors in California leverage these systems to satisfy Title 24 energy code constraints while maintaining multi-temperature corridors.
- Standard Models:Fixed-dimension catalog offerings suit budget-constrained independent restaurants with predictable storage volumes.
- Energy-Efficient Options:High-performance insulation cores and variable-speed compressor systems qualify operators for Section 179D commercial deductions.
Modular units handle the majority of throughput; energy-efficient options are gaining share fastest as rebate programs expand.
End User:
Capital allocation discipline varies dramatically across operator scale and refrigeration intensity.
- Restaurants:Full-service and quick-service establishments balance first-cost constraints against lifetime operating expense reduction. National chains in California and Texas front-load replacement investments ahead of refrigerant phase-down deadlines.
- Grocery Stores:Supermarket operators face the most stringent efficiency mandates and largest contiguous cold storage footprints. Regional chains pilot transcritical CO2 installations despite elevated upfront capital requirements.
- Catering Services:Event-driven volume fluctuations demand flexible capacity scaling through modular additions.
- Food Distributors:Temperature-sensitive logistics operations require precise zone control for mixed product categories.
Grocery stores command the largest average transaction sizes; ghost kitchen proliferation is expanding the restaurant segment most quickly.
Technology:
Refrigerant architecture selection now determines long-term serviceability and regulatory risk exposure.
- Eco-Friendly Refrigerants:Propane and carbon dioxide systems eliminate hydrofluorocarbon dependence ahead of AIM Act production limits. California and Washington supermarket operators lead adoption despite inventory complexity for equipment suppliers.
- Direct Expansion:Compressor-integrated systems dominate legacy installations and remain prevalent in retrofit scenarios.
- Refrigerant-Based:Traditional hydrofluorocarbon architectures face accelerated depreciation as 2027 phase-down milestones approach.
- Hybrid Systems:Dual-technology configurations optimize energy consumption across variable load conditions.
Direct expansion retains installed base dominance; eco-friendly refrigerants show the steepest expansion trajectory as procurement timelines compress.
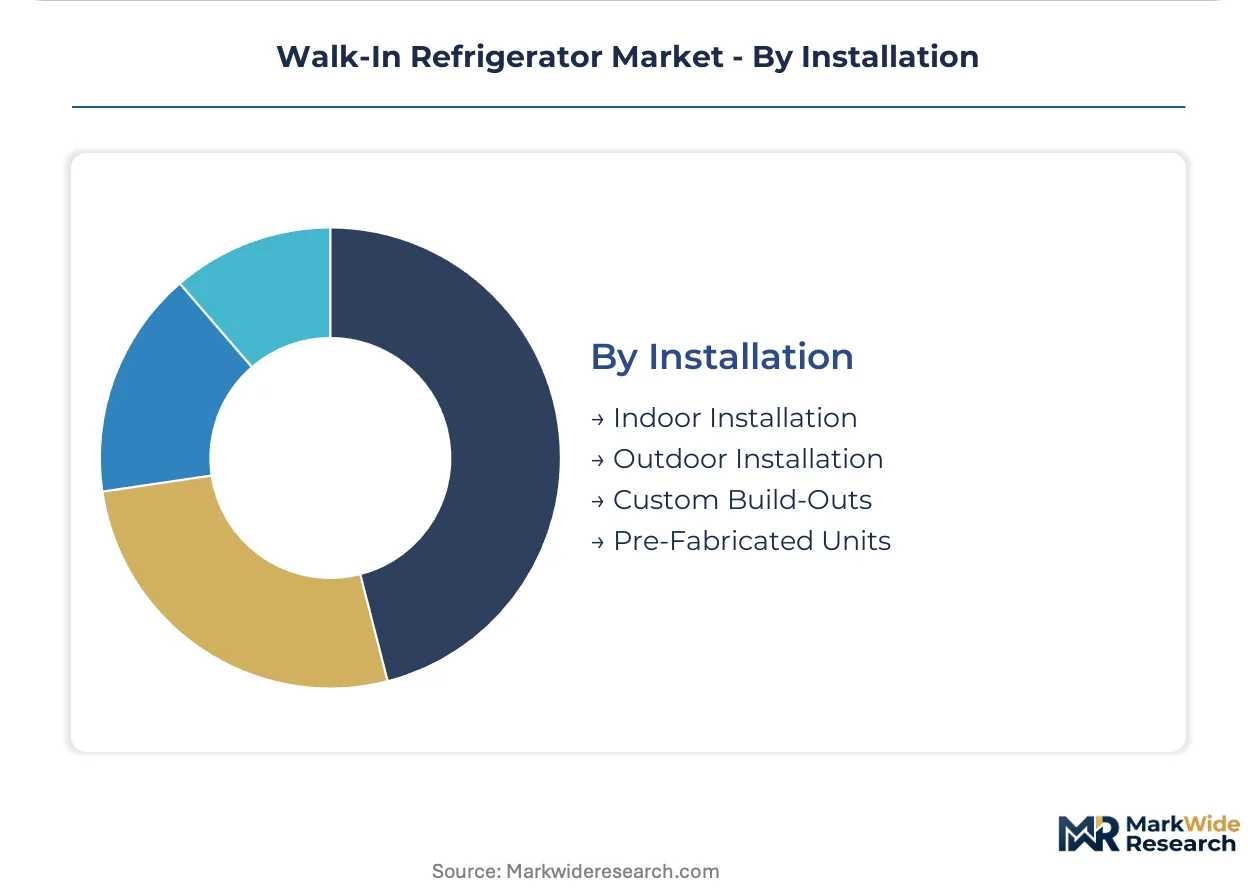
Installation:
Site constraints and building envelope characteristics dictate feasible deployment pathways.
- Indoor Installation:Climate-controlled environments protect compressor performance and reduce insulation demands. Urban restaurants in dense California markets favor these configurations where outdoor setbacks are impractical.
- Outdoor Installation:Remote condensing units free interior floor space for revenue-generating operations. Texas and Florida operators accept higher ambient temperature penalties to maximize kitchen productivity.
- Custom Build-Outs:Integrated architectural solutions address unique structural conditions and aesthetic requirements.
- Pre-Fabricated Units:Complete factory assembly minimizes field labor and commissioning complexity.
Indoor installation captures the greatest deployment volume; outdoor installation is climbing fastest in high-density metropolitan construction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal efficiency mandates and utility rebate programs are redistributing walk-in refrigerator procurement across major economies, with regulatory pressure accelerating replacement cycles in North America and Europe while Asia-Pacific expansion centers on cold chain infrastructure buildouts.
United States
Texas, Florida, and California metro areas exhibit concentrated food service density and warehouse construction activity. The US Department of Energy's updated commercial refrigeration efficiency standards push operators toward energy-efficient options and eco-friendly refrigerants. Ghost kitchen proliferation in Dallas, Houston, and Austin generates demand for modular units with rapid deployment timelines.
Germany
Supermarket operators face stringent efficiency mandates under the EU F-Gas Regulation, accelerating transcritical CO2 system adoption. The country's national energy regulator enforces building energy codes that constrain commercial refrigeration installations. Industrial clusters in Bavaria and North Rhine-Westphalia anchor regional distribution network cold storage expansion.
China
Prepared meal delivery operators and cloud kitchen developers drive modular walk-in unit demand in tier-one cities. The Ministry of Ecology and Environment enforces dual carbon goals that pressure operators toward lower-global-warming-potential refrigerants. Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate production capacity for insulated panel exports.
Japan
Convenience store chains and compact urban restaurants prioritize space-efficient indoor installations. METI efficiency standards and JIS certification requirements structure equipment procurement decisions. Kanto and Kansai metropolitan areas concentrate retrofit activity as 2027 refrigerant phase-down deadlines approach.
India
Cold chain infrastructure gaps and organized retail expansion generate walk-in cooler demand in food distribution. The Bureau of Indian Standards and state-level energy efficiency programs shape equipment specifications. Maharashtra and Gujarat industrial corridors anchor manufacturing investments serving domestic and export markets.
Walk-In Refrigerator Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with refrigerant system expertise, producing a tiered structure where scale-driven manufacturers compete against regional fabrication specialists. Strategic archetypes include integrated HVAC-refrigeration platforms, compressor technology specialists, and custom panel fabricators serving niche temperature zoning requirements. Dominant competitive moves center on refrigerant architecture diversification and predictive maintenance service bundling.
Among diversified industrial platforms, Carrier Global Corporation and Panasonic Corporation exemplify scale-driven archetypes with refrigerant system integration capabilities, while Hussmann Corporation occupies a position within the custom fabrication tier. These three anchors represent distinct strategic vectors: conglomerate-scale platform breadth, compressor technology leadership, and application-specific engineering depth.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Panasonic Corporation |
| Carrier Global Corporation |
| Kolpak |
| Norlake, Inc. |
| Master-Bilt Products LLC |
| Danfoss A/S |
| Amerikooler LLC |
| Emerson Electric Co. |
| Others |
Supply Flow & Price Mechanics
Long-term panel supply contracts with steel price indexation lock in both insulated metal skin access and cost visibility for walk-in refrigerator manufacturers facing volatile aluminum and polyurethane foam input markets. These agreements concentrate procurement leverage among national grocery chains and ghost kitchen developers in Texas and California who can commit to multi-year volume floors.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate insulated panel transactions, anchoring price adjustments to aluminum and steel spot movements. Three-tier pricing structure across premium ENERGY STAR-certified, standard efficiency, and economy-grade units differentiates transactions, with certification tier and customization depth as primary price drivers. Cost compression in economy-grade configurations is intensifying because independent restaurants face margin pressure from prepared meal delivery competition. National grocery chains exhibit lowest price sensitivity due to Section 179D tax deduction eligibility, while independent operators in Florida and Arizona remain most exposed to first-cost constraints.
Supply Chain Analysis
China and India anchor hydrofluorocarbon alternative production, while the United States and Germany concentrate compressor manufacturing and polyurethane foam core fabrication. Insulated panel assembly draws from steel and aluminum metal skins, polyurethane foam insulation cores, and refrigerant gases as critical inputs. Single-source vulnerability in hydrofluorocarbon alternative supply creates procurement bottlenecks during EPA phase-down transitions. Distribution runs through national equipment distributors serving regional fabrication shops, with direct OEM relationships capturing grocery chain and national restaurant accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from modular cold room rental services and refrigeration-as-a-service platforms that displace capital equipment purchases among ghost kitchen operators and seasonal catering services.
For Market Incumbents: Fortify refrigerant architecture diversification across carbon dioxide, propane, and hydrofluorocarbon systems to maintain service coverage regardless of regulatory phase-down trajectory. Secure backward integration into polyurethane foam core production to defend margin position against petrochemical feedstock volatility. Prioritize predictive maintenance service bundling with compressor systems to create recurring revenue streams that rental substitutes cannot replicate. For New Entrants and Emerging Players: Lead with remote temperature monitoring and IoT-enabled predictive maintenance platforms targeting independent restaurants in Texas and Florida where technical workforce gaps extend project lead times. White-space opportunity concentrates in aftermarket service contracts for legacy direct expansion installations facing EPA Section 608 technician certification constraints. Go-to-market angle should emphasize rapid deployment timelines and utility rebate program navigation support. For Investors and Strategic Acquirers: Regional custom fabricators with Title 24 compliance expertise and established relationships with California food distributors represent priority acquisition targets. Long-term viability hinges on positioning for refrigerant transition service intensity rather than equipment shipment volume. Signal to watch is acceleration of national supply agreement consolidation among ghost kitchen developers displacing franchisee-directed procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Architecture Diversification | EPA AIM Act phase-down schedules force multi-system service capability investments. |
| Backward Integration into Panel Cores | Captive polyurethane foam production hedges petrochemical feedstock price volatility exposure. |
| Predictive Maintenance Platform Launch | IoT sensor integration enables recurring revenue streams beyond equipment shipment economics. |
| Utility Rebate Program Navigation Services | Section 179D and state-level incentive expertise differentiates procurement support offerings. |
| Technician Certification Training Programs | EPA Section 608 credential pipelines address workforce scarcity extending project timelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association datasets, and equipment manufacturer disclosures. Primary interviews captured perspectives from food service facility managers, commercial refrigeration contractors, grocery chain procurement directors, and utility rebate program administrators. Secondary validation drew from EPA Section 608 enforcement data, DOE appliance efficiency standards documentation, and California Energy Commission Title 24 compliance records. Bottom-up installation volume estimates triangulated against top-down construction spending allocations across restaurant and warehouse categories.
Segmentation dimensions modeled include product architecture, end-user category, refrigerant technology, and installation configuration across the analysis window. CAGRs were derived from regression analysis of historical shipment data against construction activity indices and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated refrigerant phase-down schedule acceleration scenarios and ghost kitchen development pipeline tracking in Texas, Florida, and California metro areas.
Forecasts assume regulatory continuity in EPA AIM Act implementation and DOE efficiency standard enforcement; material policy shifts would require re-modeling. Specific risk factors include hydrofluorocarbon alternative supply disruption, steel and aluminum tariff volatility, and utility rebate program funding exhaustion. Recalibration cycles align with material shifts in construction activity indices and refrigerant phase-down milestone revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
North America Ginger Processing Market