
 Canning Equipment Market | 2026-2036
Canning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canning Equipment Market Outlook
Market Context
Multi-source procurement for seaming and filling subsystems is hardening among mid-tier beverage producers. Krones AG dominates turnkey line integration across European dairy and beer canning facilities. Ball Corporation leverages captive aluminum supply to anchor North American beverage can capacity expansions. Comac Group specializes in rotary seamer retrofits that extend legacy line throughput without full replacement.
Technical Definition and Segments
Canning equipment encompasses mechanical systems that hermetically seal prepared products into metal, composite, or glass containers using controlled atmosphere flushing, double-seam formation, and pasteurization-compatible closure integrity. Filling machines achieve volumetric accuracy within plus-or-minus 0.5 percent for carbonated beverages, while seaming machines apply first and second operation rolls at speeds exceeding 2,000 cans per minute in high-volume breweries. Automatic technology leads capital deployment due to labor cost arbitrage in emerging manufacturing clusters, though semi-automatic systems retain margin pools in craft beverage and small-batch sauce segments where changeover flexibility outweighs throughput maximization. Robotics is displacing manual capping in pharmaceutical aerosol and sterile liquid applications where glove-box isolation demands precision placement.
Regulatory Frame
FDA 21 CFR Part 129 governs finished product container integrity for low-acid canned foods, while EU Regulation 1935/2004 mandates migration testing for food-contact metal coatings. ISO 9001 and BRCGS packaging certification shape OEM qualification criteria for multinational food manufacturers. Stakeholders must monitor how extended producer responsibility frameworks in Germany and France reshape aluminum can recovery targets and thus seamer material compatibility specifications.
Market Dynamics
Automated seaming systems are compressing changeover times while FDA and EU traceability mandates force retrofit cycles across legacy filling lines. Aluminum supply concentration and contract packaging expansion in Latin America and Southeast Asia are redrawing procurement geography.
Growth Catalysts
- EU food-contact migration testing:EU Regulation 1935/2004 mandates coating verification that accelerates seamer replacement cycles as packagers pre-empt compliance failures.
- Carbonated beverage volumetric precision:Filling accuracy within plus-or-minus 0.5 percent for CSDs drives capital deployment toward servo-driven volumetric systems in high-speed breweries.
- Vietnam contract packaging hubs:Regional canning center buildouts concentrate demand for integrated filling-seaming-pasteurization lines serving ASEAN export markets.
Market Restraints
- Aluminum ingot price volatility:Ball Corporation's captive supply advantage locks mid-tier beverage producers into long-term raw material contracts with limited hedge flexibility.
- Seamer subsystem supply concentration:European turnkey integrators dominate high-speed rotary seamer technology, creating single-source risk for Latin American capacity expansions.
- Double-seam integrity validation:FDA 21 CFR Part 129 documentation requirements extend qualification timelines for low-acid canned food line startups.
Strategic Opportunities
- Brazil craft beverage retrofit demand:Semi-automatic seaming systems with rapid changeover capability address small-batch flexibility gaps that automated lines cannot serve.
- Robotic capping in pharmaceutical aerosols:Glove-box isolation requirements in sterile liquid packaging create precision placement demand that manual operations cannot satisfy.
- Germany extended producer responsibility:Aluminum recovery targets under national EPR frameworks reshape seamer material compatibility specifications toward mono-material designs.
Industry Challenges
- Servo-mechanics technician scarcity:High-speed seamer maintenance requires electromechanical skill sets that vocational pipelines in Mexico and Vietnam have not scaled.
- Legacy line integration complexity:Comac Group rotary seamer retrofits demand mechanical-electrical interface engineering that extends commissioning timelines.
- BRCGS packaging certification timelines:OEM qualification for multinational food manufacturers requires audit cycles that delay equipment acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canning Equipment Market |
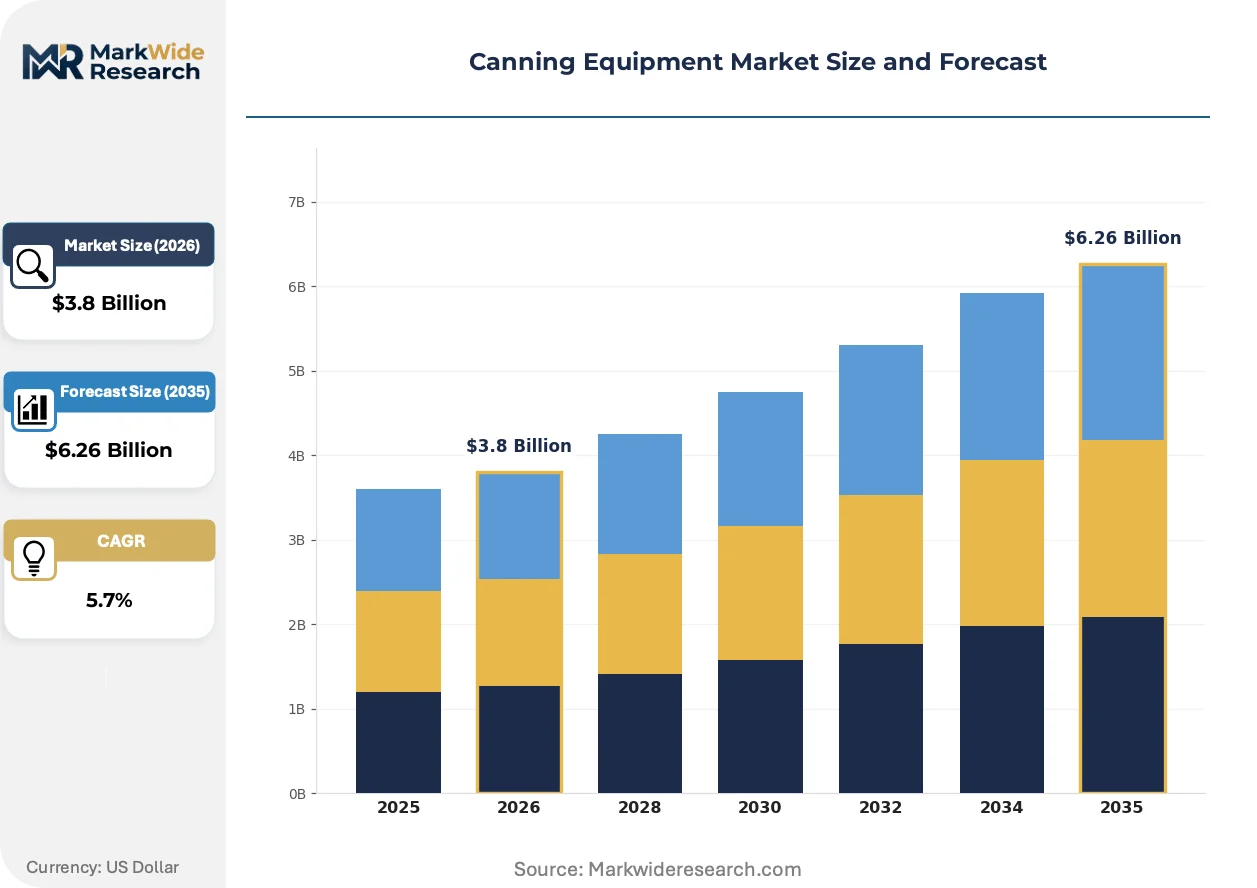
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seaming Machines, Filling Machines, Labeling Machines, Cappers End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Contract Packagers Technology: Automatic, Semi-Automatic, Manual, Robotics Application: Preserved Foods, Beverages, Sauces, Others |
| Companies Covered | Comac Group, HOR YANG Machinery, Ball Corporation, Shin-I Machinery Works, Krones AG, American Canning Machines, Dixie Canner, Codi Manufacturing, Cask Global Canning Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canning Equipment Market Strategic Shifts
Digital thread technologies are threading through canning lines while regulatory migration testing tightens and procurement models fragment between turnkey and subsystem sourcing.
Machine vision inspection is integrating defect detection directly into seaming operations, replacing manual sampling protocols. Mid-tier beverage producers in Mexico and Brazil are adopting these systems at retrofit pace rather than greenfield scale. This integration is compressing quality assurance labor costs while raising capital intensity thresholds for line upgrades.
REACH compliance deadlines for food-contact metal coatings are forcing reformulation of internal lacquers and external printing inks across European canning facilities. Industrial consequence includes accelerated validation cycles for seamer tooling compatibility with new coating chemistries. Aerosol and preserved food segments face the steepest retooling costs as migration limits tighten for acid and sulfur-containing products.
Subsystem unbundling is fragmenting procurement as beverage producers source filling machines from Krones AG specialists and seamers from Comac Group retrofit providers rather than accepting single-source turnkey lines. This pattern concentrates in Latin American contract packaging where capital constraints favor staged investment. Brazil and Vietnam display the most visible unbundling as regional hubs prioritize changeover flexibility over throughput maximization.
Canning Equipment Market Segmentation
Canning equipment procurement fragments across standalone subsystem purchases versus integrated turnkey lines, with technology choice and end-use scale determining integration depth. Equipment buyers weigh changeover flexibility against throughput maximization when selecting across these dimensions.
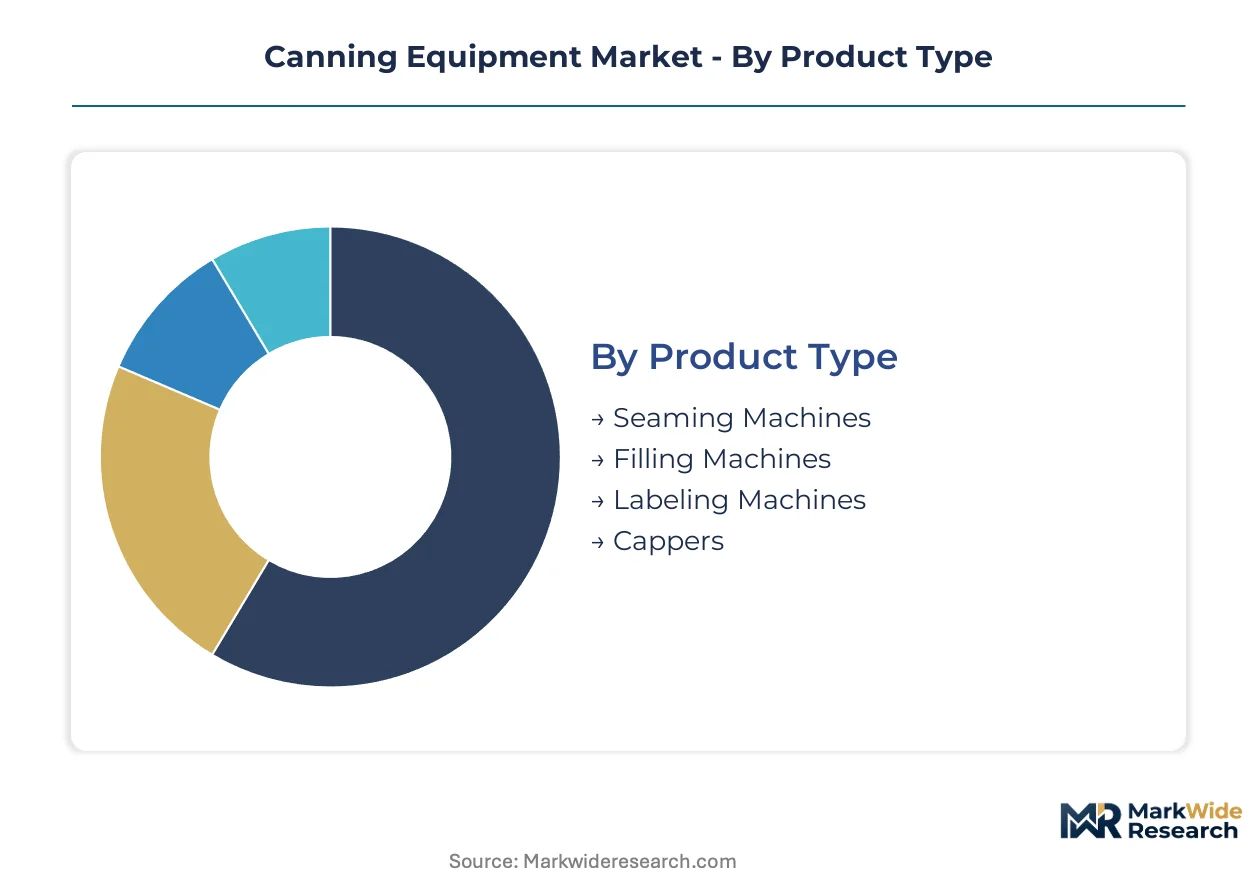
Product Type:
Standalone seaming and filling subsystems dominate mid-tier procurement, while integrated lines concentrate among high-volume breweries and dairy processors.
- Seaming Machines:Rotary double-seam systems apply first and second operation rolls at speeds exceeding 2,000 cans per minute. Demand concentrates in Mexico and Brazil as contract packagers build regional beverage canning hubs requiring FDA 21 CFR Part 129 compliance documentation.
- Filling Machines:Servo-driven volumetric systems achieve plus-or-minus 0.5 percent accuracy for carbonated beverages. European dairy and beer facilities drive capital deployment toward Krones AG turnkey integrations where pasteurization-compatible closure integrity is mandatory.
- Labeling Machines:Pressure-sensitive and sleeve application systems complete container decoration workflows.
- Cappers:Screw, crown, and lug capping mechanisms secure closure integrity across container formats.
Volume placements concentrate in Seaming Machines; the faster expansion belongs to Filling Machines as servo-mechanics displace pneumatic controls.
End User:
Capital intensity thresholds separate multinational food manufacturers from craft beverage operators, with contract packagers occupying a hybrid procurement position.
- Food Manufacturers:Low-acid canned food processors deploy automated seaming lines under FDA migration testing mandates. BRCGS packaging certification requirements extend OEM qualification timelines for multinational accounts sourcing from European turnkey integrators.
- Beverage Producers:Carbonated soft drink and beer canning drives the fastest technology refresh cycles. Vietnam and Brazil anchor regional capacity buildouts as ASEAN and Latin American export markets expand.
- Pharmaceutical Companies:Sterile liquid and aerosol applications demand glove-box isolation precision.
- Contract Packagers:Regional hub buildouts in Mexico and Vietnam concentrate demand for flexible changeover capability.
Equipment shipments tilt toward Beverage Producers; Contract Packagers are climbing the fastest as third-party canning displaces in-house production.
Technology:
Labor cost arbitrage in emerging manufacturing clusters favors automatic deployment, though semi-automatic systems retain margin pools where batch flexibility outweighs speed.
- Automatic:Programmable logic controllers coordinate filling-seaming-pasteurization sequences without operator intervention. Brazil and Vietnam contract packaging hubs prioritize these systems for export-scale throughput despite higher capital thresholds.
- Semi-Automatic:Operator-assisted changeover mechanisms address small-batch sauce and craft beverage segments. Brazil craft retrofit demand concentrates here where rapid format switching compensates for lower line speeds.
- Manual:Hand-fed systems serve micro-scale operations and pilot production lines.
- Robotics:Precision placement systems displace manual capping in pharmaceutical aerosol applications.
Automatic systems capture the dominant placement share; Robotics is gaining share fastest as glove-box isolation requirements tighten.
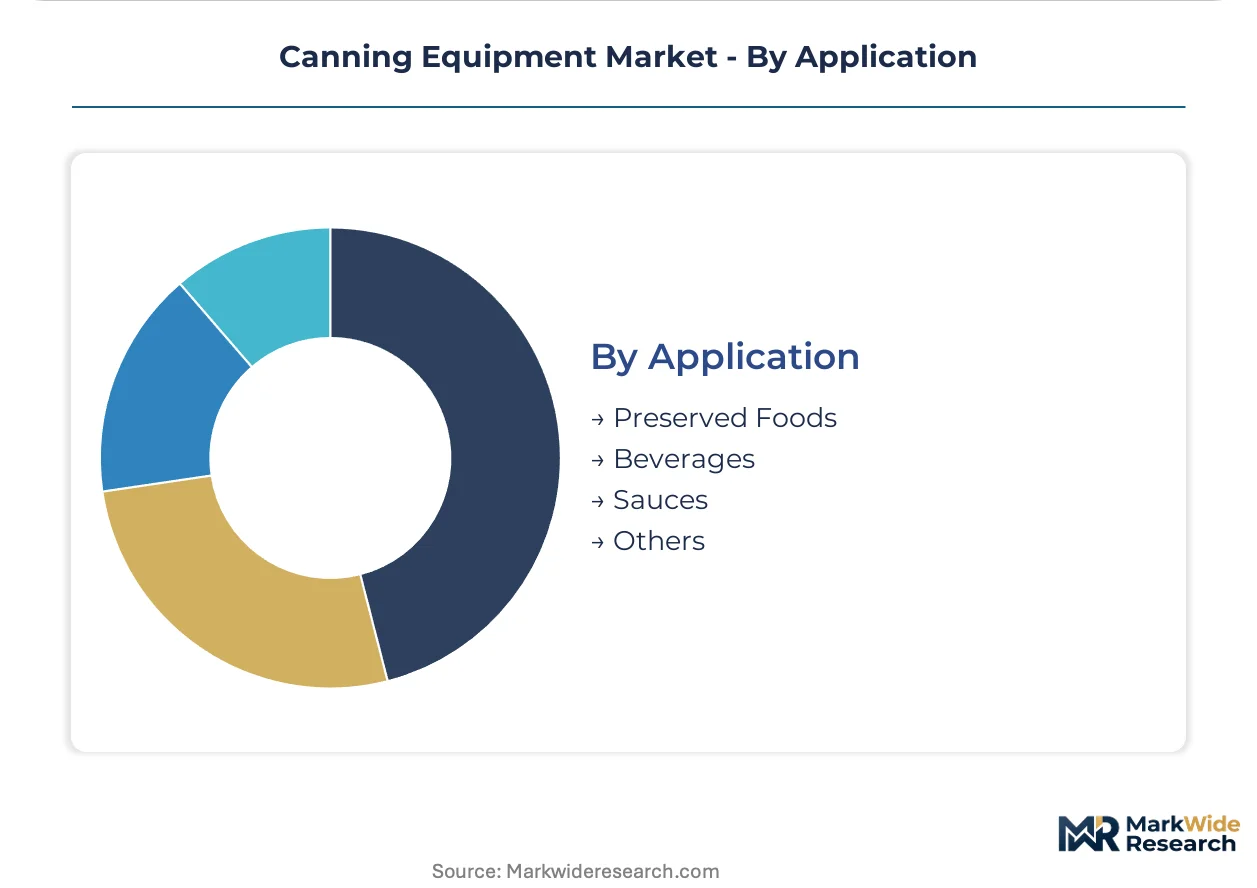
Application:
Acid content and thermal processing requirements differentiate equipment specifications across food and beverage categories.
- Preserved Foods:Low-acid canned vegetables and proteins demand double-seam integrity validation under FDA 21 CFR Part 129. Migration testing for sulfur-containing products drives coating reformulation and seamer tooling compatibility checks across European facilities.
- Beverages:Carbonated and still drinks require volumetric precision and atmospheric control during filling. Mexico and Brazil beverage canning expansions concentrate procurement for integrated lines serving aluminum can formats.
- Sauces:Viscous product handling necessitates specialized pump and valve configurations.
- Others:Pet food, nutritional supplements, and industrial chemicals occupy niche specification bands.
Beverages command the largest equipment volume; Preserved Foods faces the steepest retooling intensity as REACH compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting corridors in Canada and Brazil anchor raw material flows for canning equipment deployment. Regional procurement patterns diverge between North American captive supply models and Latin American contract packaging buildouts.
United States
Beverage canning capacity expansions concentrate in Texas and the Southeast where Ball Corporation leverages captive aluminum supply chains. FDA 21 CFR Part 129 enforcement tightens documentation requirements for low-acid canned food startups. Chicago and Milwaukee anchor dairy and beer canning line retrofits serving Midwest distribution networks.
Germany
Extended producer responsibility frameworks under national packaging law reshape aluminum recovery targets and seamer material specifications. REACH compliance deadlines for food-contact coatings accelerate validation cycles across Bavarian and North Rhine-Westphalian facilities. Stuttgart industrial clusters specialize in servo-driven volumetric filling systems for carbonated beverages.
Mexico
Contract packaging hub development in Mexico City Metro and Nuevo León concentrates demand for integrated filling-seaming-pasteurization lines. ANVISA alignment with FDA migration testing standards extends qualification timelines for export-oriented facilities. Guadalajara anchors craft beverage retrofit demand for semi-automatic seaming flexibility.
Brazil
São Paulo and Minas Gerais beverage producers drive automated line deployment despite servo-mechanics technician scarcity in regional vocational pipelines. ANVISA pharmaceutical aerosol regulations create precision capping demand that robotic systems address. Regional canning centers prioritize changeover capability over throughput maximization.
Vietnam
ASEAN export market expansion concentrates contract packaging investment in Ho Chi Minh City and Hanoi industrial zones. The country's national food safety regulator tightens traceability requirements for metal packaging serving European and North American buyers. Da Nang emerges as a secondary hub for mid-tier beverage canning capacity.
Canning Equipment Market Competitive Environment
Global majors compete with regional champions across subsystem specialization versus turnkey integration. European fabricators dominate high-speed rotary seamer technology while North American and Asian players anchor aluminum supply and craft-scale flexibility segments. Two strategic archetypes define competitive positioning: captive supply-integrated multinationals and retrofit-specialized subsystem providers. Dominant competitive moves include geographic expansion into Latin American contract packaging hubs and technology licensing for servo-mechanics integration.
Among European turnkey integrators, Krones AG exemplifies the scale-driven archetype through beverage and dairy line integration. Ball Corporation occupies a position linking captive aluminum supply to North American capacity expansion. Comac Group represents the retrofit-specialist tier with rotary seamer upgrades that extend legacy line throughput without full replacement.
| Leading Market Players |
|---|
| Comac Group |
| HOR YANG Machinery |
| Ball Corporation |
| Shin-I Machinery Works |
| Krones AG |
| American Canning Machines |
| Dixie Canner |
| Codi Manufacturing |
| Cask Global Canning Solutions |
| Others |
Value Chain & Pricing Dynamics
Aluminum ingot cost volatility cascades through canning equipment tiers as captive supply advantages at Ball Corporation compress margins for mid-tier buyers sourcing from spot-market dependent fabricators in Mexico and Brazil.
Pricing Analysis
Warranty and service bundling separates premium-tier Krones AG turnkey integrations from economy-positioned semi-automatic subsystem providers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales coverage scope. Cost compression in standard-tier rotary seamer retrofits is intensifying because European OEMs face REACH-driven coating reformulation expenses. Contract packagers in Vietnam display highest price sensitivity due to capital constraint staging; multinational food manufacturers anchored by BRCGS certification requirements show lowest sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale brewery demand for integrated filling-seaming lines, while distributor networks serve craft-scale retrofit segments across Latin America. Manufacturing concentrates in Germany, Italy, and China for high-speed rotary seamer subsystems. Critical inputs draw from aluminum smelting corridors in Canada and Brazil, servo-motor drives from Japanese industrial automation suppliers, and food-contact coatings from specialty chemical producers in Belgium and Switzerland. Single-source vulnerability concentrates in European high-speed seamer technology for Latin American capacity expansions. Distribution runs through regional equipment dealers serving contract packaging hubs in Mexico City Metro and Ho Chi Minh City industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 129 documentation requirements for low-acid canned food lines erect compliance moats that favor incumbent OEMs with established validation track records over unproven entrants.
For Market Incumbents: Deploy certification investment as the primary lever. Accelerate BRCGS packaging certification pre-qualification for multinational food manufacturer accounts to preempt subsystem unbundling threats from Comac Group retrofit specialists. Expand captive aluminum supply integration into Brazilian smelting corridors to neutralize raw material price volatility exposure for Latin American contract packaging customers. For New Entrants and Emerging Players: Mid-tier price-point gaps between Krones AG premium turnkey lines and economy semi-automatic craft systems create viable entry corridors. Concentrate white-space capture on Brazil craft beverage retrofit demand and Vietnam contract packaging hub buildouts where rapid changeover capability outweighs throughput maximization. Pursue staged subsystem sales with ANVISA-aligned documentation support as the go-to-market anchor. For Investors and Strategic Acquirers: Extended producer responsibility framework adoption in Germany is the leading indicator that mono-material seamer design capabilities will command acquisition premiums. Position for five-to-ten year viability windows favoring retrofit-specialist subsystem providers with servo-mechanics integration expertise over pure-play turnkey integrators. Monitor ANVISA-FDA alignment progress in Mexico as the inflection signal for export-oriented facility qualification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Supply | Captive ingot access locks margin protection for North American beverage canning expansions. |
| Subsystem Specialization Licensing | Technology transfer agreements enable regional champions to compete with European turnkey integrators. |
| Robotic Capping Platform Development | Precision placement systems address pharmaceutical aerosol glove-box isolation requirements. |
| Regional Hub Certification Pre-Qualification | ANVISA-aligned documentation accelerates Mexico and Brazil contract packaging line acceptance. |
| Servo-Mechanics Training Pipeline Investment | Vocational partnerships in São Paulo and Hanoi address technician scarcity constraining line uptime. |
Study Parameters
Document review covered FDA 21 CFR Part 129 guidance documents, EU Regulation 1935/2004 migration testing protocols, and ANVISA pharmaceutical packaging regulations, complemented by interviews with plant engineers at beverage canning facilities, procurement leads at contract packaging hubs, aftermarket service heads at European OEMs, and regulatory affairs specialists at multinational food manufacturers. Secondary validation drew from SEC filings of aluminum packaging suppliers, ISO 9001 certification databases, and BRCGS audit records. Bottom-up equipment shipment tallies across Mexico, Brazil, and Vietnam were triangulated against top-down market sizing derived from capital expenditure disclosures.
Historical capacity installation patterns were cross-referenced against panel input from regional equipment distributors to anchor growth trajectory assumptions across the analysis window. Segmentation modeling tracked product type, end-user category, technology tier, and application requirements. CAGRs were derived from curve-fitting approaches applied to validated baseline data points. Industry-specific forecast inputs incorporated aluminum price elasticity coefficients and regulatory compliance cycle timelines.
Inputs from OEM technical documentation and national regulator guidance repositories were available through the study window; gaps in real-time contract packaging capital commitment disclosures introduce uncertainty bands around Vietnam and Brazil demand projections. Forecasts reflect assumptions regarding REACH compliance deadline adherence and servo-mechanics technician pipeline scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Global High Pressure Processing (HPP) Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Vee Bee Consistometer Market