
 Countertop Blast Chiller Market | 2026-2036
Countertop Blast Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Blast Chiller Market Outlook
Quick-service restaurant chains is decoupling from traditional full-service kitchen layouts as speed-of-service mandates reshape equipment procurement. Electrolux Professional leverages its European manufacturing footprint to anchor supply relationships with high-volume bakery-cafe operators. Irinox differentiates through specialized R&D intensity in compact blast chilling architectures. Williams Refrigeration competes on channel control within the UK institutional catering segment.
A countertop blast chiller is a compact thermal processing unit that reduces cooked food temperatures from above 140°F to below 40°F within 90 minutes using forced air convection at velocities exceeding 5 meters per second, preventing bacterial proliferation and preserving food texture. Its primary commercial purpose centers on HACCP compliance and batch-cook production efficiency in space-constrained foodservice environments. Multi-chamber configurations are capturing margin pools by enabling simultaneous processing of allergen-segregated loads, while air blast technology dominates installed base economics due to lower capital requirements versus cryogenic alternatives. Small-format units are gaining fastest among ghost kitchen operators and micro-bakery startups.
The U.S. FDA Food Code and EU hygiene package regulations under EFSA frameworks mandate documented cooling logs, which equipment suppliers must address through integrated data-logging interfaces. NSF International certification and CE marking under EU MDR-equivalent machinery directives govern market access for North American and European deployments respectively. Stakeholders should monitor evolving energy efficiency standards from the U.S. Department of Energy and the EU Ecodesign framework, as these will reshape compressor technology roadmaps and refrigerant selection criteria.
Market Dynamics
Quick-service restaurant chains are compressing kitchen footprints while FDA Food Code cooling mandates tighten, forcing operators to prioritize compact thermal processing units that deliver HACCP compliance without floor space expansion.
Growth Catalysts
- EU Ecodesign Framework:Energy efficiency mandates are accelerating compressor technology upgrades across European commercial kitchens, driving replacement demand for compliant blast chiller units.
- Ghost Kitchen Proliferation:Delivery-only foodservice operators in dense urban cores require space-constrained rapid cooling solutions to support batch-cook production models.
- Allergen Segregation Protocols:Multi-chamber configurations are capturing institutional catering contracts by enabling simultaneous processing of allergen-isolated loads without cross-contamination risk.
Market Restraints
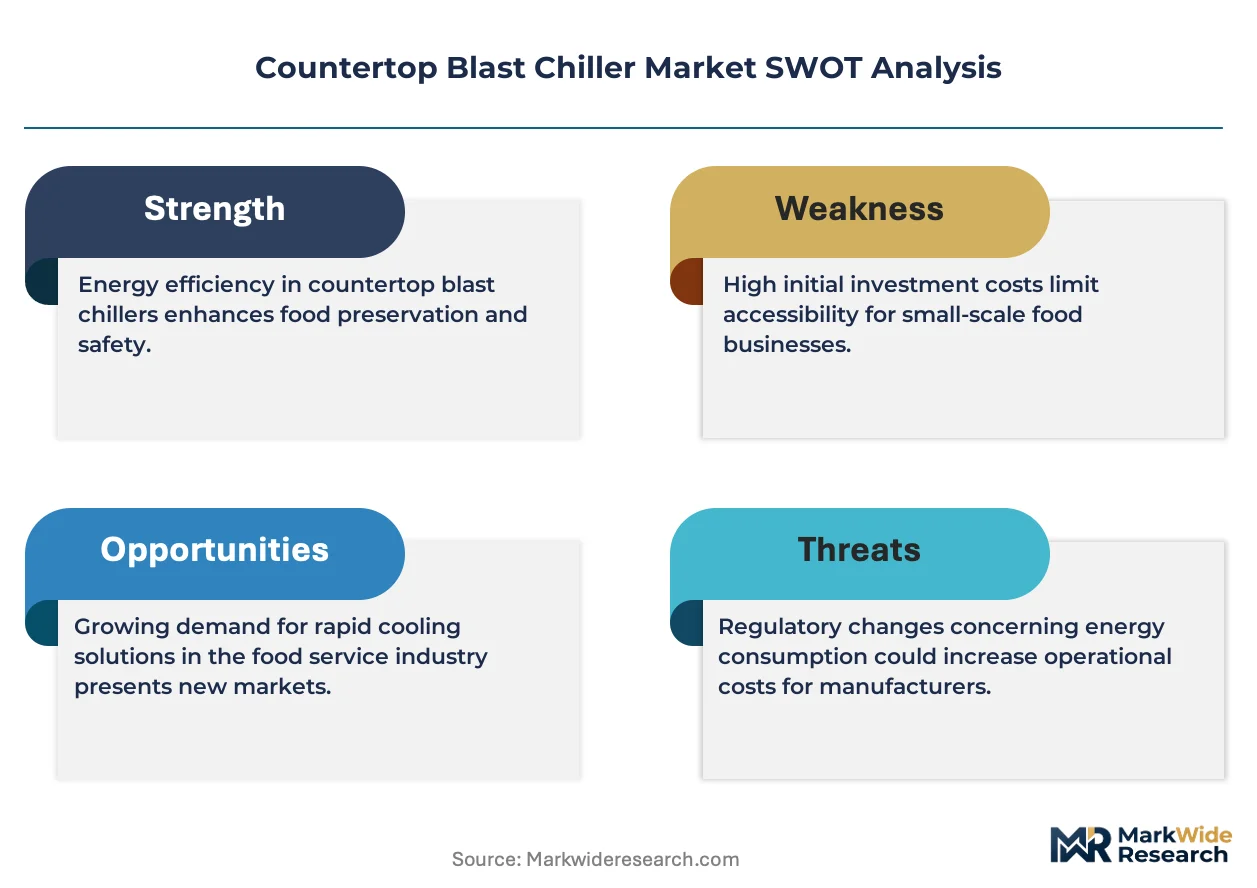
- Refrigerant Cost Volatility:Hydrofluorocarbon phase-down schedules under EU F-Gas Regulation are compressing margins for manufacturers reliant on conventional cooling circuits.
- Supply Concentration in Compressor Manufacturing:Sourcing dependencies for high-velocity fan motors and precision temperature controllers cluster in East Asian component hubs.
- Cryogenic Substitution Threat:Liquid nitrogen injection systems for ultra-rapid cooling are displacing air blast units in premium protein processing segments where texture preservation commands priority.
Strategic Opportunities
- Micro-Bakery Segment:Small-format countertop units are penetrating artisanal baking operations in Germany where equipment replacement cycles are accelerating.
- Integrated Data Logging:NSF International certification requirements for documented cooling logs are creating attach-rate opportunities for cloud-connected monitoring interfaces.
- CE Marking Harmonization:EU machinery directive convergence is streamlining cross-border deployment for manufacturers targeting pan-European bakery-cafe chains.
Industry Challenges
- HVAC Technician Shortspecialization:Installation and maintenance of forced-air convection systems at velocities exceeding 5 meters per second requires scarce certified service capacity.
- NSF Certification Timelines:Third-party validation protocols for food equipment sanitation standards are extending product launch windows for North American market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Blast Chiller Market |
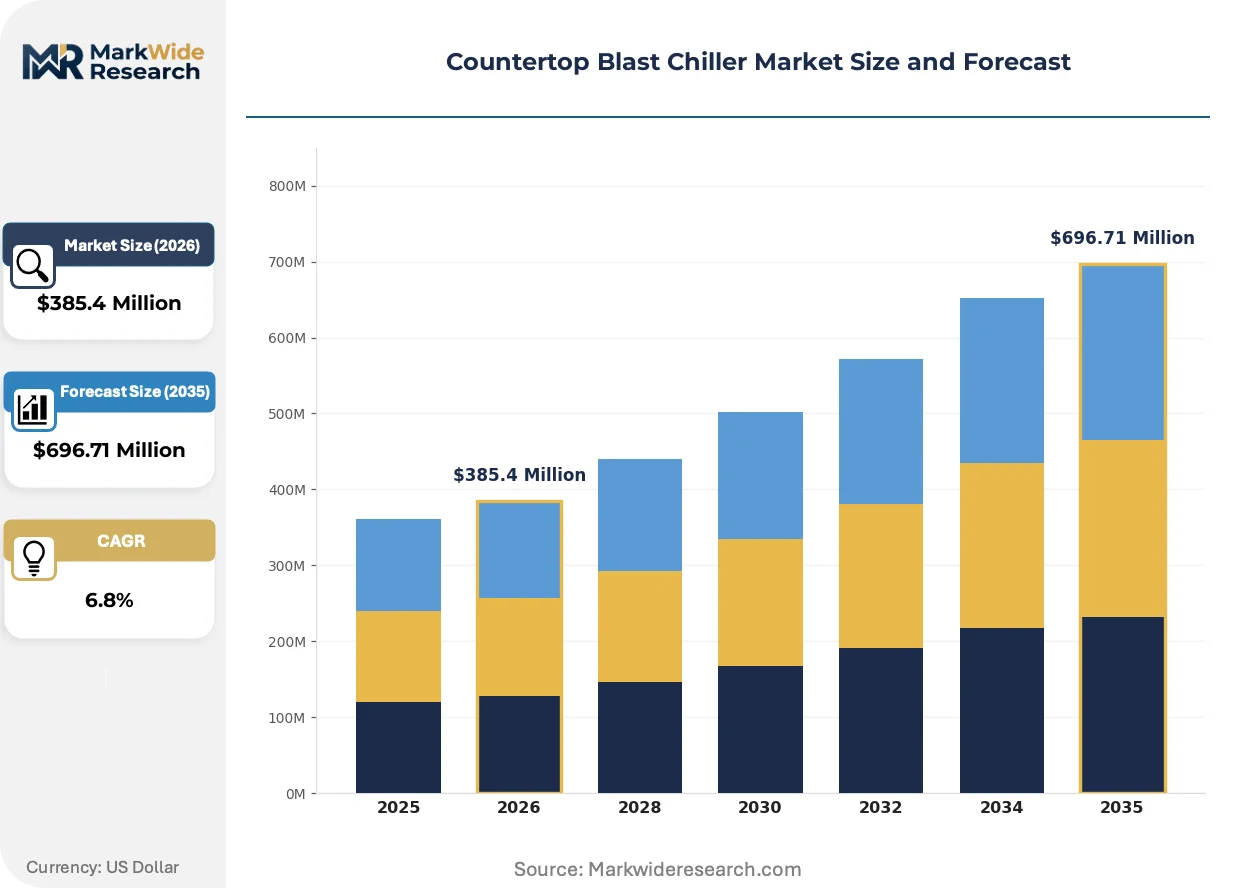
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Multi Chamber, Portable, Built-in End User: Restaurants, Catering Services, Bakeries, Food Processing Technology: Air Blast, Plate Freezer, Liquid Nitrogen, Cryogenic Size: Small, Medium, Large, Extra Large |
| Companies Covered | Electrolux Professional, Irinox, Williams Refrigeration, Alto Shaam, Friginox, SMEG, Master-Bilt Products, Infrico, Traulsen & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Blast Chiller Market Strategic Shifts
Equipment architecture is pivoting toward connectivity-enabled compliance documentation as regulatory audit requirements harden, while thermal engineering advances compress cooling cycle durations without sacrificing food quality outcomes.
Variable-speed compressor technology paired with precision airflow management is decentralizing blast chiller deployment from centralized commissary kitchens to individual restaurant sites. Ghost kitchen operators in London and New York are adopting these compact units at accelerated pace. The technology is decentralizing capital allocation patterns across foodservice real estate portfolios by eliminating dedicated cooling room construction.
EU F-Gas Regulation refrigerant phase-down schedules are forcing compressor redesigns toward lower global-warming-potential alternatives. Equipment suppliers are requalifying thermal performance specifications under revised charge constraints. German and French commercial kitchen operators face the most acute compliance deadlines, accelerating procurement of next-generation units ahead of regulatory enforcement windows.
Service contract unbundling is fragmenting traditional bundled procurement relationships between equipment dealers and multi-unit restaurant chains. Ghost kitchen operators and micro-bakeries are sourcing direct from manufacturers via digital channels, bypassing regional distributor networks. This pattern is most visible in UK urban cores where institutional catering procurement teams are experimenting with outcome-based equipment leasing models tied to compliance performance metrics.
Countertop Blast Chiller Market Segmentation
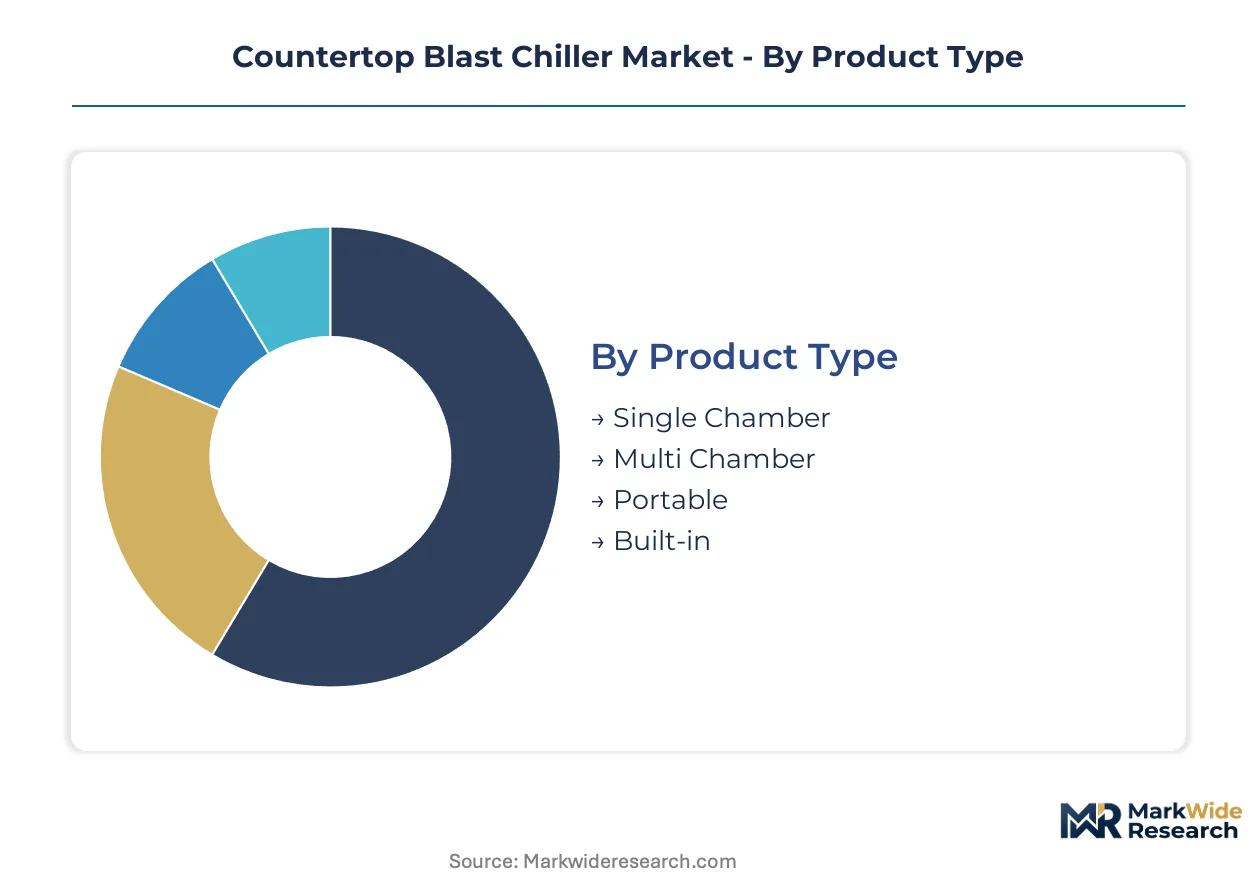
Segmentation in the countertop blast chiller market reveals how regulatory compliance burdens, spatial constraints, and cooling velocity requirements fragment procurement patterns across foodservice verticals. Equipment specifications diverge sharply between HACCP-driven institutional buyers and speed-focused quick-service operators.
Product Type:
NSF International certification applies universally across all configurations, while CE marking complexity escalates with chamber count and integrated data-logging capabilities required by EU hygiene regulations.
- Single Chamber:Compact units dominate quick-service restaurant deployments where kitchen footprints compress below industry averages. Operators in the United States prioritize these configurations to meet FDA Food Code cooling mandates without floor space expansion.
- Multi Chamber:Segregated thermal zones enable simultaneous processing of allergen-isolated loads, a capability capturing institutional catering contracts in Germany where replacement cycles accelerate. EU Ecodesign Framework compliance costs concentrate here due to redundant compressor architectures.
- Portable:Castor-mounted units serve ghost kitchen operators requiring equipment mobility across leased commercial kitchen spaces.
- Built-in:Undercounter integration targets bakery-cafe chains standardizing kitchen layouts across multiple locations.
Leading the category by volume: Single Chamber. Growing fastest: Multi Chamber.
End User:
Procurement authority patterns split between centralized equipment buyers at chain headquarters and decentralized purchasing by independent operators.
- Restaurants:Full-service establishments deploy blast chillers for batch-cook production efficiency, though adoption lags quick-service penetration due to lower throughput requirements. Ghost kitchen operators in London and New York represent the fastest-expanding sub-segment within this category.
- Catering Services:Institutional caterers in the United Kingdom face stringent audit documentation requirements, driving attach rates for cloud-connected monitoring interfaces. Multi-chamber configurations capture disproportionate share here.
- Bakeries:Artisanal micro-bakeries in Germany source small-format units direct from manufacturers via digital channels.
- Food Processing:Protein processors evaluate cryogenic substitution threats where texture preservation commands premium positioning.
Restaurants command the largest installed base. Catering Services are expanding most quickly on allergen segregation protocols.
Technology:
Capital intensity and operating cost structures diverge by orders of magnitude across cooling methodologies.
- Air Blast:Forced convection at velocities exceeding 5 meters per second dominates installed base economics due to lower capital requirements versus alternatives. Compressor redesigns under EU F-Gas Regulation phase-down schedules are forcing thermal performance requalification across European deployments.
- Plate Freezer:Direct contact cooling serves high-volume protein processors where surface-area-to-mass ratios favor conductive heat transfer.
- Liquid Nitrogen:Injection systems command premium segments where ultra-rapid cooling preserves cellular structure in high-value proteins.
- Cryogenic:Carbon dioxide-based systems occupy niche positions in specialized food processing applications.
Air Blast leads by installed units. Liquid Nitrogen is gaining share fastest in premium protein processing.
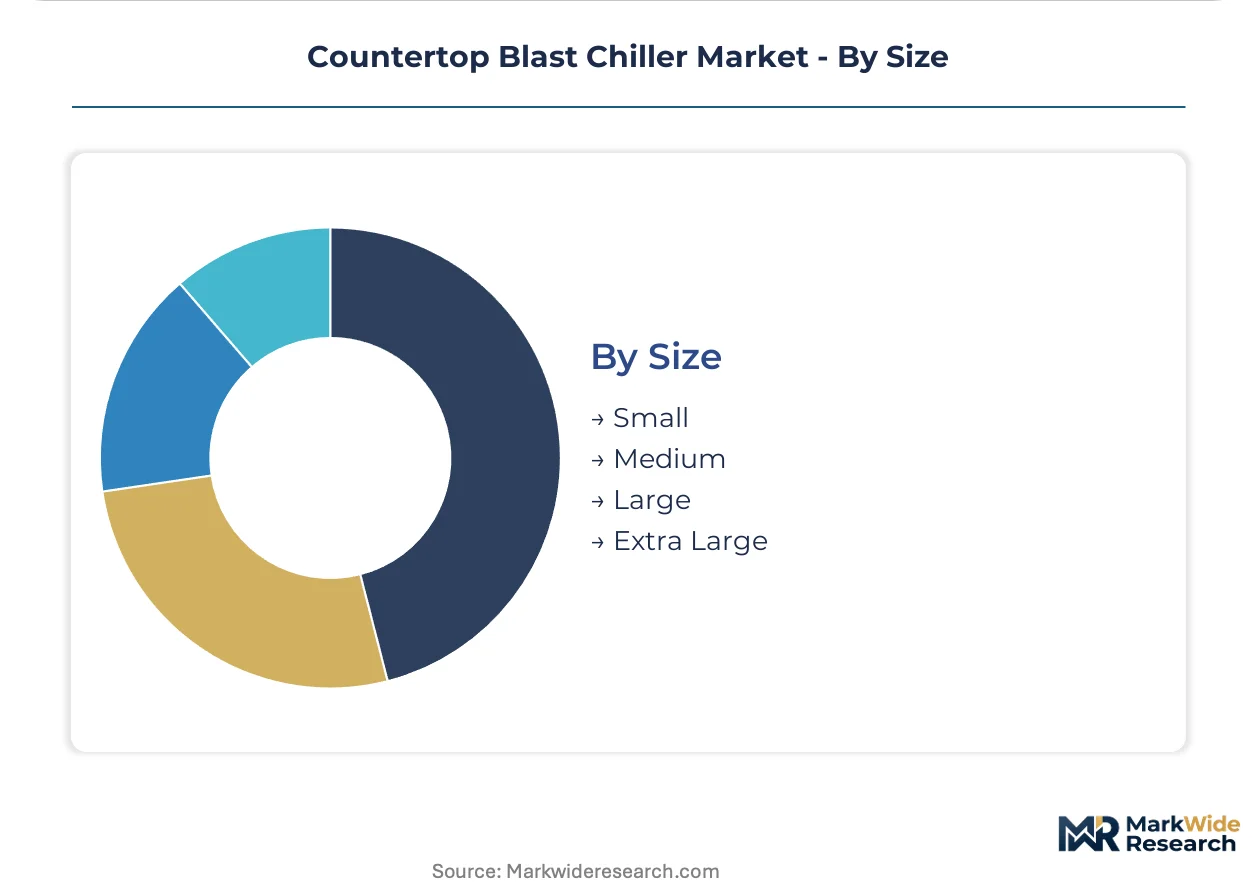
Size:
Physical dimensions directly correlate with cooling capacity, energy consumption profiles, and regulatory documentation requirements.
- Small:Countertop units under 24 inches wide penetrate ghost kitchen and micro-bakery segments where real estate costs per square meter exceed metropolitan averages. These configurations face compressed margins from refrigerant cost volatility under EU F-Gas Regulation.
- Medium:Standard commercial kitchen deployments balance throughput requirements against spatial constraints in renovated facilities.
- Large:Commissary kitchen operators require centralized cooling capacity serving multiple downstream locations.
- Extra Large:Industrial-scale configurations approach floor-standing blast chiller territory, blurring segmentation boundaries.
Medium units dominate current procurement. Small formats are climbing the fastest on urban kitchen footprint compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Dubai and Jebel Ali concentrate Middle Eastern distribution for commercial kitchen equipment, while Germany's accelerated equipment replacement cycles anchor European demand concentration.
United States
Quick-service restaurant chains compress kitchen footprints in Manhattan and Los Angeles while FDA Food Code cooling mandates tighten compliance timelines. The FDA updates rapid cooling documentation requirements annually, pressuring operators toward integrated data-logging interfaces. Ghost kitchen clusters in Brooklyn and Chicago source small-format units direct from manufacturers.
Germany
Commercial kitchen equipment replacement cycles accelerate in Bavaria and North Rhine-Westphalia as EU Ecodesign Framework deadlines approach. The F-Gas Regulation refrigerant phase-down compresses margins for conventional cooling circuits, forcing compressor redesigns. Artisanal micro-bakeries in Berlin source countertop units via digital channels bypassing traditional distributors.
United Kingdom
Institutional catering procurement teams in London experiment with outcome-based equipment leasing tied to compliance performance metrics. NSF International certification requirements extend product launch windows for North American suppliers entering British markets. Birmingham and Manchester hospital catering contracts drive multi-chamber configuration attach rates.
France
Bakery-cafe chains standardize kitchen layouts across Paris and Lyon locations, prioritizing undercounter built-in configurations. ANSM hygiene audit protocols mandate documented cooling logs, creating demand for cloud-connected monitoring. Electrolux Professional leverages its European manufacturing footprint to anchor supply relationships with high-volume operators in Île-de-France.
United Arab Emirates
Jebel Ali Free Zone concentration streamlines import logistics for Gulf Cooperation Council distribution. Dubai Health Authority food safety protocols align with EU hygiene package standards, easing CE-marked equipment deployment. Hotel kitchen renovations in Abu Dhabi and Sharjah prioritize compact thermal processing units for HACCP compliance in space-constrained environments.
Countertop Blast Chiller Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in premium institutional catering and fragmented competition in small-format ghost kitchen supply. The vendor base organizes around three strategic archetypes: European manufacturing anchors with pan-regional service networks, compact-specialization R&D houses, and regional channel controllers with institutional relationships. Dominant competitive moves include backward integration into compressor technology and geographic expansion via digital direct-to-operator channels.
Among European manufacturing anchors, Electrolux Professional exemplifies the scale-driven archetype with manufacturing footprint leverage, while Irinox occupies a position within the compact-specialization tier focused on R&D intensity. Williams Refrigeration represents the regional channel control model with UK institutional catering concentration. These three companies anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Electrolux Professional |
| Irinox |
| Williams Refrigeration |
| Alto Shaam |
| Friginox |
| SMEG |
| Master-Bilt Products |
| Infrico |
| Traulsen & Co. |
| Others |
Value Chain & Pricing Dynamics
HVAC technician scarcity in Germany and the UK widens pricing-tier spreads between premium certified-installation bundles and economy self-service models. Labor-cost differentials across these markets force manufacturers to stratify service-included pricing from stripped-down direct-channel alternatives.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with spot-inventory discounts available for standard single-chamber configurations held in regional distribution centers. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified data-logging units from basic CE-marked alternatives and refurbished legacy equipment. Cost compression in economy tiers is intensifying because refrigerant cost volatility under EU F-Gas Regulation squeezes margin on conventional cooling circuits. Ghost kitchen operators exhibit highest price sensitivity, while institutional catering buyers prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
EU local-content thresholds under machinery directive harmonization are reshaping sourcing patterns for compressor assemblies and precision temperature controllers. Manufacturing concentration clusters in Italy, Germany, and China, with high-velocity fan motors and refrigeration compressors drawing from East Asian component hubs. Single-source vulnerability concentrates in precision temperature controller supply, where qualified suppliers remain limited. Distribution runs through regional equipment dealers serving multi-unit restaurant chains, though direct-to-operator digital channels are fragmenting traditional bundled procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as compressor technology redesigns under refrigerant phase-down schedules force upstream control over thermal engineering capabilities.
For Market Incumbents: Anchor service network density in Germany and the UK to defend against cryogenic substitution threats in premium protein processing. Deepen backward integration into variable-speed compressor technology to capture margin from EU Ecodesign Framework compliance upgrades. Prioritize certification investment for integrated data-logging interfaces ahead of FDA Food Code documentation tightening. For New Entrants and Emerging Players: Launch via direct digital channels targeting micro-bakery segments in Berlin and London where equipment replacement cycles accelerate and distributor relationships remain underdeveloped. The most penetrable white-space sits in small-format portable units for ghost kitchen operators requiring mobility across leased commercial kitchen spaces. Differentiate through outcome-based equipment leasing models tied to HACCP compliance performance metrics. For Investors and Strategic Acquirers: Re-rating potential sits with compact-specialization R&D houses given ghost kitchen proliferation and urban kitchen footprint compression. Long-term viability favors manufacturers with captive compressor technology and pan-European service infrastructure. Monitor EU F-Gas Regulation enforcement windows as inflection indicator for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Technology | Captures margin from EU Ecodesign Framework refrigerant redesigns and secures supply continuity. |
| Direct-to-Operator Digital Channel Launch | Bypasses regional dealer networks to serve ghost kitchen and micro-bakery procurement patterns. |
| Integrated Data-Logging Interface Development | Addresses FDA Food Code and ANSM hygiene audit documentation mandates for cloud-connected compliance. |
| Multi-Chamber Configuration Expansion | Captures institutional catering contracts through allergen-segregation capabilities in Germany and UK. |
| Outcome-Based Equipment Leasing Model | Aligns revenue with HACCP compliance performance metrics for risk-averse institutional buyers. |
Study Parameters
Trade association filings, EU regulatory databases, and commercial kitchen equipment customs records formed the secondary backbone, supplemented by primary interviews with foodservice equipment procurement directors, HVAC installation contractors, and ghost kitchen operations managers. Bottom-up unit shipment estimates triangulated against top-down spending analysis across quick-service restaurant chains and institutional catering operators.
Historical trendline analysis of replacement cycle patterns and regulatory compliance deadlines anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, cooling technology, and physical size tier, with compressor technology roadmaps and refrigerant transition schedules informing thermal performance assumptions.
EU F-Gas Regulation enforcement timing, FDA Food Code revision schedules, and cryogenic cooling technology cost curves are the dominant revision risks to installed base and replacement demand estimates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Food Processor Market