
 Industrial Food Milling Machine Market | 2026-2036
Industrial Food Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Food Milling Machine Market Foresight
REACH compliance is rebalancing capital deployment toward stainless-steel construction and sealed bearing systems that reduce lubricant contamination risk. Bühler Group leverages its Swiss manufacturing base to sustain integrated supply chains from foundry to final assembly. Hosokawa Micron Group anchors its competitive position through air-classifier integration that extends particle-size precision below 50 microns. Satake Corporation dominates optical sorting adjacencies, using color-recognition technology to differentiate its milling system offerings.
Industrial food milling machines reduce solid food materials through mechanical shear, impact, or compression to specified particle distributions ranging from coarse granulation to sub-100-micron powders. These systems serve commercial-scale operations requiring consistent throughput, thermal stability, and hygienic design for downstream processing of flours, spices, and feed ingredients. Roller mill configurations command the largest installed base in flour production due to established starch damage control and extraction efficiency. Hammer mill demand is accelerating fastest within spice processing, where fibrous and oil-bearing substrates require aggressive impact reduction without temperature degradation. Electrical drive technology leads technology adoption, though pneumatic conveying integration is gaining share in facilities prioritizing dust containment and explosion mitigation per ATEX directives.
EMA guidelines on pharmaceutical-grade food contact materials and FDA Food Safety Modernization Act preventive controls are converging to mandate hygienic design certifications for new milling installations. BIS marking requirements in India and China's GB standards on food machinery safety are fragmenting market access protocols across manufacturing jurisdictions. Stakeholders must monitor evolving national implementation timelines for ISO 22000-aligned equipment specifications before committing to regional production footprints.
Market Dynamics
The EU Green Deal's tightening energy-efficiency benchmarks are compressing capital deployment timelines for food processors, forcing equipment refresh cycles ahead of historical replacement schedules while simultaneously elevating stainless-steel construction and sealed bearing architectures as baseline procurement criteria.
Growth Catalysts
- Plant-based protein expansion:Reformulated product specifications in alternative meat and dairy categories are driving capacity additions at specialized milling facilities. Precision particle-size control below 100 microns has become mandatory for texture replication.
- REACH compliance rebalancing:Lubricant contamination risk reduction requirements are redirecting capital toward sealed bearing systems and hygienic design certifications. ECHA enforcement timelines are accelerating pre-2027 equipment procurement.
- German precision engineering clusters:Advanced roller mill deployments concentrate in Baden-Württemberg and Bavaria, where localized supplier networks reduce commissioning lead times for flour mill modernizations.
Market Restraints
- Specialized alloy input volatility:Food-grade stainless-steel pricing fluctuations compress margin visibility for equipment fabricators. Nickel and chromium supply concentration in specific mining jurisdictions amplifies cost forecasting uncertainty.
- Technical limitation in thermal management:Hammer mill operations on oil-bearing spice substrates face hard boundaries in temperature control. Fibrous material processing without degradation remains unresolved below certain throughput thresholds.
- Regulatory friction from fragmented certification:BIS marking requirements in India, China's GB standards, and FDA Food Safety Modernization Act preventive controls create parallel compliance burdens. ISO 22000-aligned equipment specifications lack synchronized implementation timelines.
Strategic Opportunities
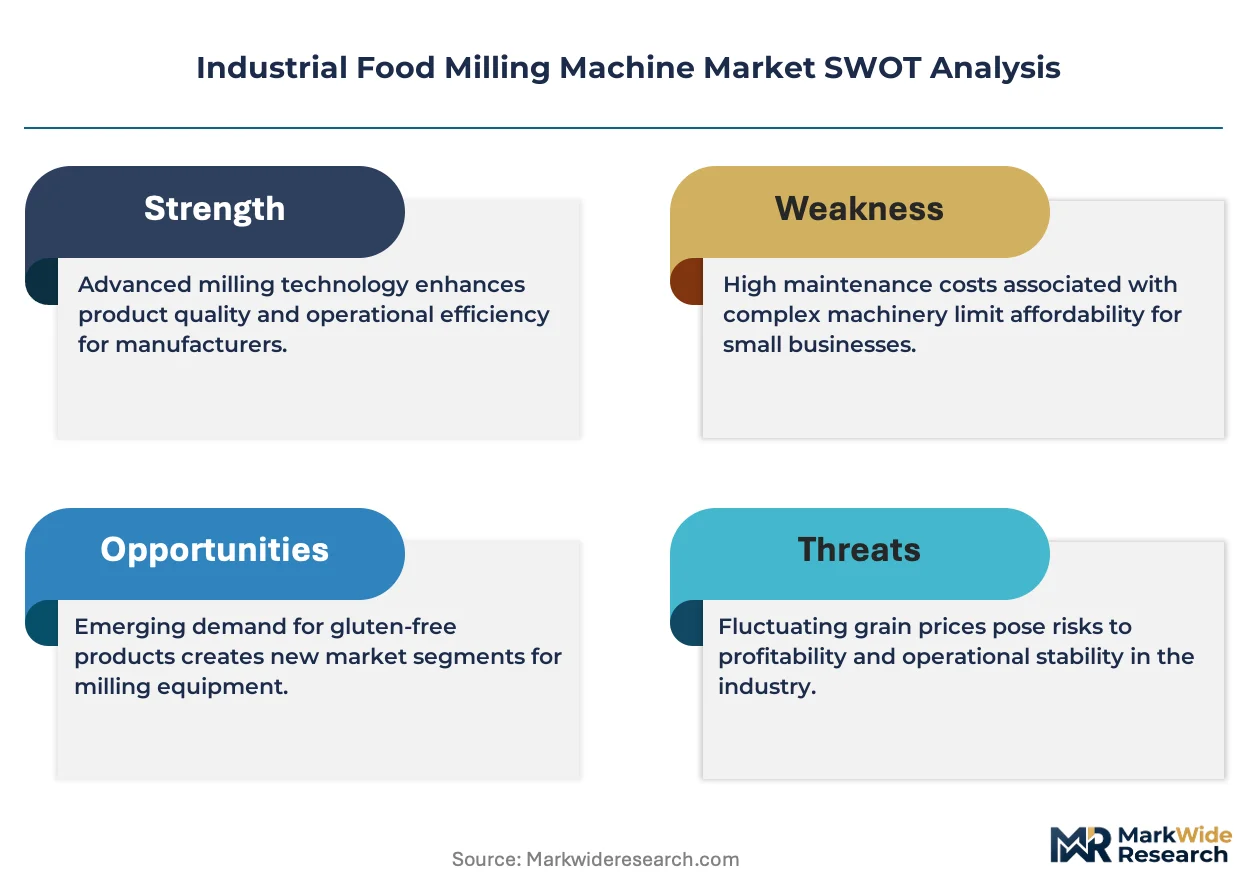
- Underpenetrated precision spice processing:Indian subcontinent facilities serving export markets remain below 30% adoption of sub-50-micron air-classifier integration. FSSAI enforcement of hygienic design standards is accelerating replacement demand.
- Technology convergence of optical sorting and milling:Color-recognition integration into continuous processing lines enables real-time contamination rejection. Combined capital expenditure packages reduce floor space requirements versus sequential installations.
- Distribution innovation through pneumatic conveying integration:ATEX-compliant dust containment systems are opening retrofit opportunities in legacy European flour mills. Explosion mitigation specifications are becoming procurement gatekeepers rather than optional upgrades.
Industry Challenges
- Skill gap in mechatronics maintenance:Electrical drive technology adoption outpaces technician training programs. Facilities struggle to staff predictive maintenance capabilities for integrated air-classifier and roller mill configurations.
- Certification timeline compression:EMA pharmaceutical-grade food contact material guidelines and FDA preventive controls are converging on overlapping implementation windows. Equipment validation documentation requirements are extending order-to-commissioning intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Food Milling Machine Market |
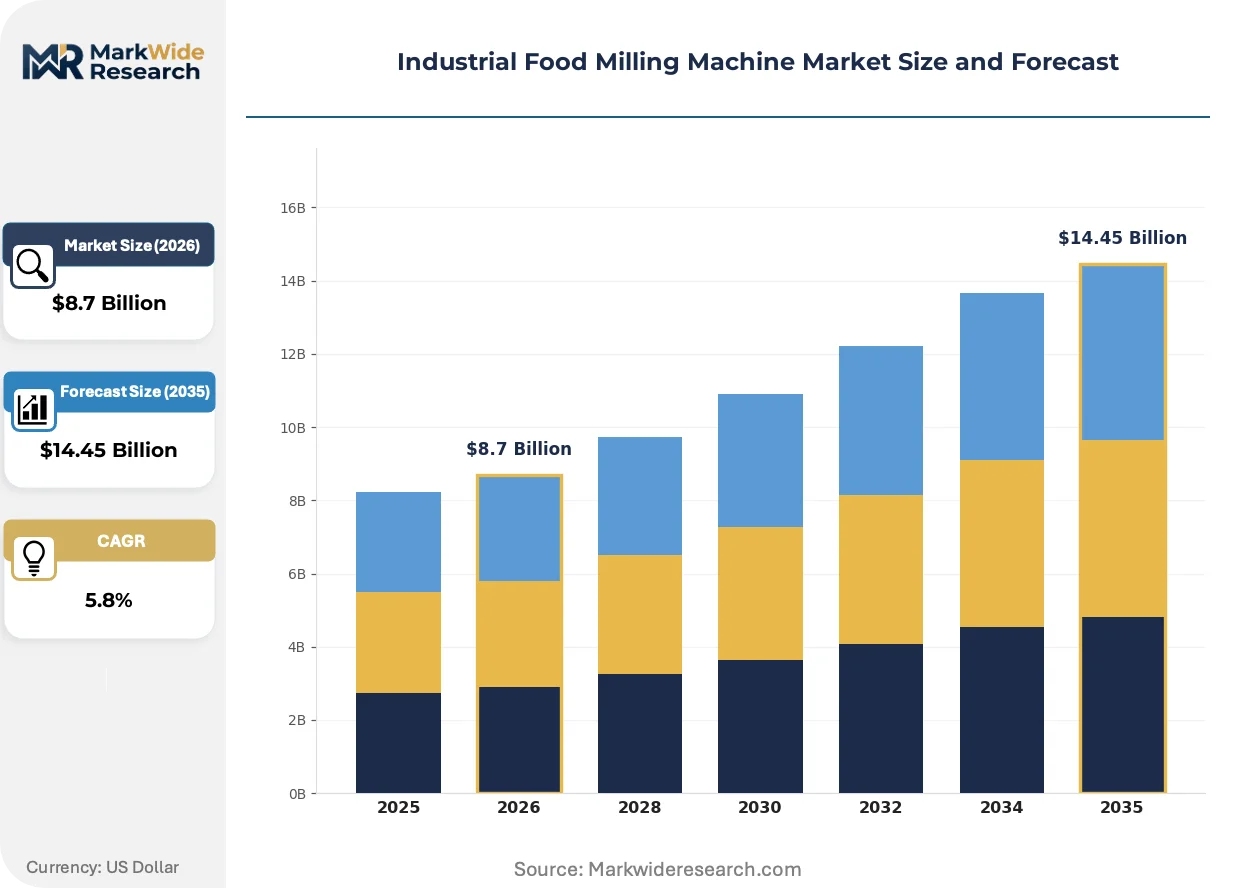
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammer Mill, Roller Mill, Pin Mill, Disc Mill Application: Flour Production, Spice Processing, Grain Milling, Feed Manufacturing Technology: Mechanical, Electrical, Pneumatic, Hydraulic End User: Food Processors, Bakeries, Agriculture, Beverage Industry |
| Companies Covered | Bühler Group, Hosokawa Micron Group, Satake Corporation, Alapala Machine Industry & Trade Inc., Brabender GmbH & Co. KG, IKA Werke GmbH & Co. KG, The Fitzpatrick Company, Prater Industries, Kemutec Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Food Milling Machine Market Shifts & Advancements
Active thermal management architectures and real-time particle-size feedback loops are compressing the performance gap between established roller mill configurations and emerging impact-based alternatives. Equipment specifications now prioritize continuous monitoring over batch-end quality verification.
Air-classifier integration is overtaking standalone mechanical screening in premium flour and specialty powder applications. German and Swiss millers are adopting these systems at replacement-cycle velocity rather than greenfield-only deployment. The technology is overtaking conventional sieve-based classification by enabling real-time particle distribution adjustment without line stoppage.
REACH substance restrictions on legacy lubricant formulations are forcing bearing system redesigns across European manufacturing bases. Industrial consequence includes accelerated R&D allocation toward solid lubricant and sealed-for-life architectures. Flour milling operations in France and Germany are responding with pre-regulation equipment procurement to lock in compliant supply chains.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into component-specific subscription tiers. Spice processors in India and Southeast Asia are purchasing predictive analytics modules separately from physical spare parts programs. This pattern is most visible in facilities with multi-brand installed bases seeking interoperability rather than single-vendor lock-in.
Industrial Food Milling Machine Market Segmentation
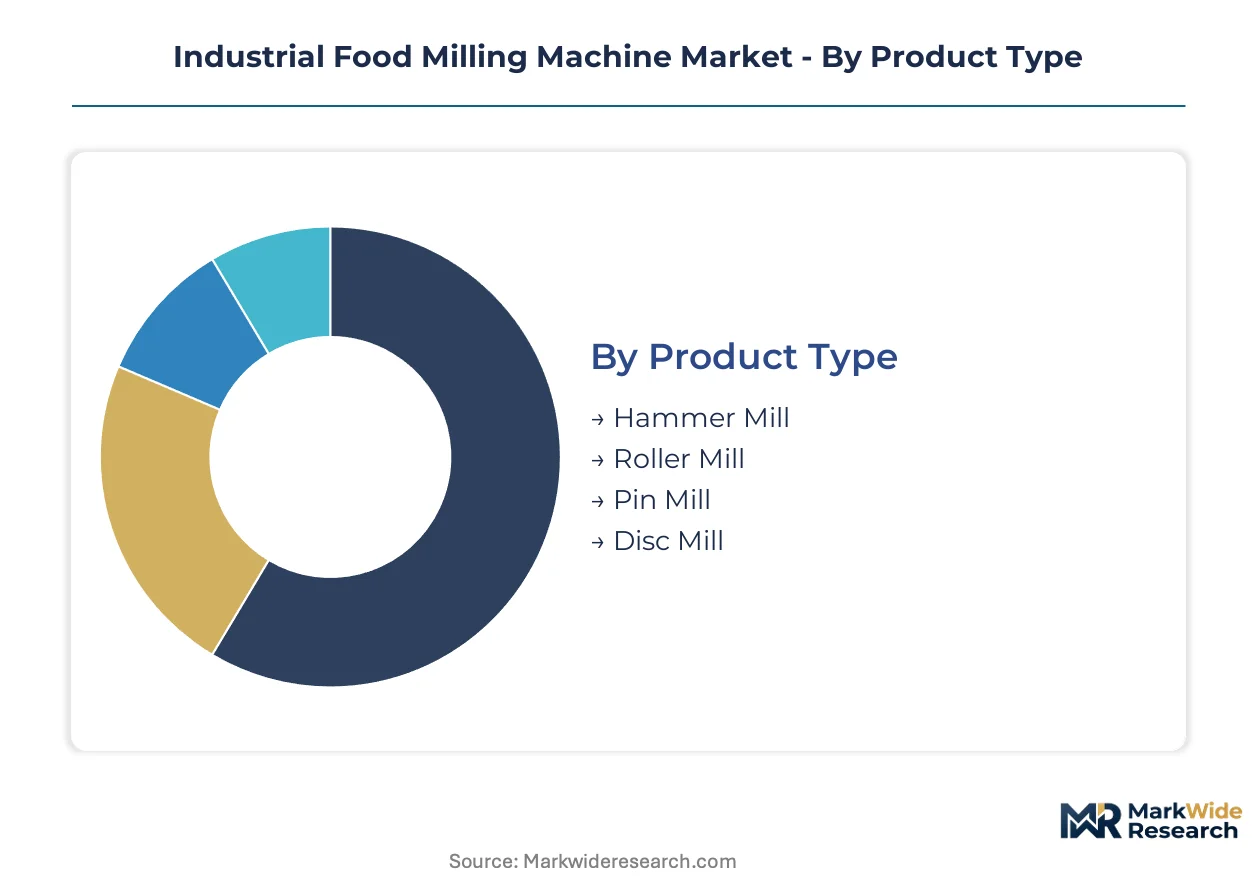
Industrial food milling machine procurement patterns diverge sharply by operational scale and substrate characteristics. Capital allocation decisions hinge on particle-size precision requirements, thermal sensitivity of processed materials, and integration complexity with downstream conveying systems.
Product Type:
Capital intensity peaks with roller mill configurations requiring precision-ground castings and multi-stage calibration infrastructure. Hammer mills demand lower upfront outlay but impose higher lifecycle maintenance burdens on aggressive-impact applications.
- Roller Mill:Multi-pair corrugated cast-iron cylinders operating under controlled differential speeds achieve starch damage rates below 8% in wheat flour extraction. German precision engineering clusters in Baden-Württemberg concentrate demand for these systems as flour millers modernize capacity ahead of EU Green Deal efficiency mandates.
- Hammer Mill:High-rotor-speed impact reduction using hardened steel beaters addresses fibrous spice substrates and oil-bearing materials. Indian subcontinent export-oriented processors are expanding installations for turmeric and chili powder production where FSSAI hygienic design enforcement is accelerating replacement cycles.
- Pin Mill:Counter-rotating pin discs deliver sub-50-micron precision for specialty flour and pharmaceutical-adjacent food ingredients.
- Disc Mill:Abrasive grinding plates handle high-moisture grains and coarse feed manufacturing with simpler mechanical architecture.
Roller mill infrastructure absorbs the bulk of installed capacity in mature flour markets; hammer mill deployment is expanding most quickly in spice processing corridors.
Application:
Volume concentration and margin structure vary substantially across end-use categories, with commodity flour operations prioritizing throughput over customization while specialty segments command premium pricing for precision specifications.
- Flour Production:Continuous roller mill trains processing 200+ tonnes daily serve industrial bakeries and packaged food manufacturers. Extraction efficiency above 75% remains the critical performance metric driving equipment selection in European and North American facilities.
- Spice Processing:Cryogenic and ambient hammer mill configurations address heat-sensitive volatile oil retention in cardamom, pepper, and cinnamon processing. REACH-compliant sealed bearing systems are becoming procurement prerequisites for EU-destined export facilities in India and Vietnam.
- Grain Milling:Coarse grinding for breakfast cereals and brewing adjuncts employs disc and pin mill combinations with lower capital barriers.
- Feed Manufacturing:Pellet mill preparation grinding prioritizes durability over particle-size distribution uniformity in livestock and aquaculture applications.
Flour production retains the largest operational footprint; spice processing is climbing the fastest as export quality standards tighten across Asian supply bases.
Technology:
Energy efficiency benchmarking and ATEX compliance requirements are reconfiguring technology adoption curves, with electrical architectures displacing legacy mechanical drives in greenfield installations.
- Electrical:Variable frequency drive integration enables real-time throughput adjustment and predictive maintenance telemetry. German and Swiss millers are standardizing these systems to meet compressed EU Green Deal implementation timelines.
- Pneumatic:Vacuum conveying integration with milling chambers addresses dust containment and explosion mitigation per ATEX directives. Retrofit demand is concentrating in legacy European flour mills where sequential equipment replacement outpaces full line reconstruction.
- Mechanical:Direct-coupled drive trains persist in cost-sensitive feed manufacturing and developing market installations.
- Hydraulic:High-torque applications in oilseed preprocessing retain niche deployment despite efficiency disadvantages.
Electrical drive systems dominate new capacity additions; pneumatic integration is gaining share fastest in regulatory-intensive European retrofit environments.
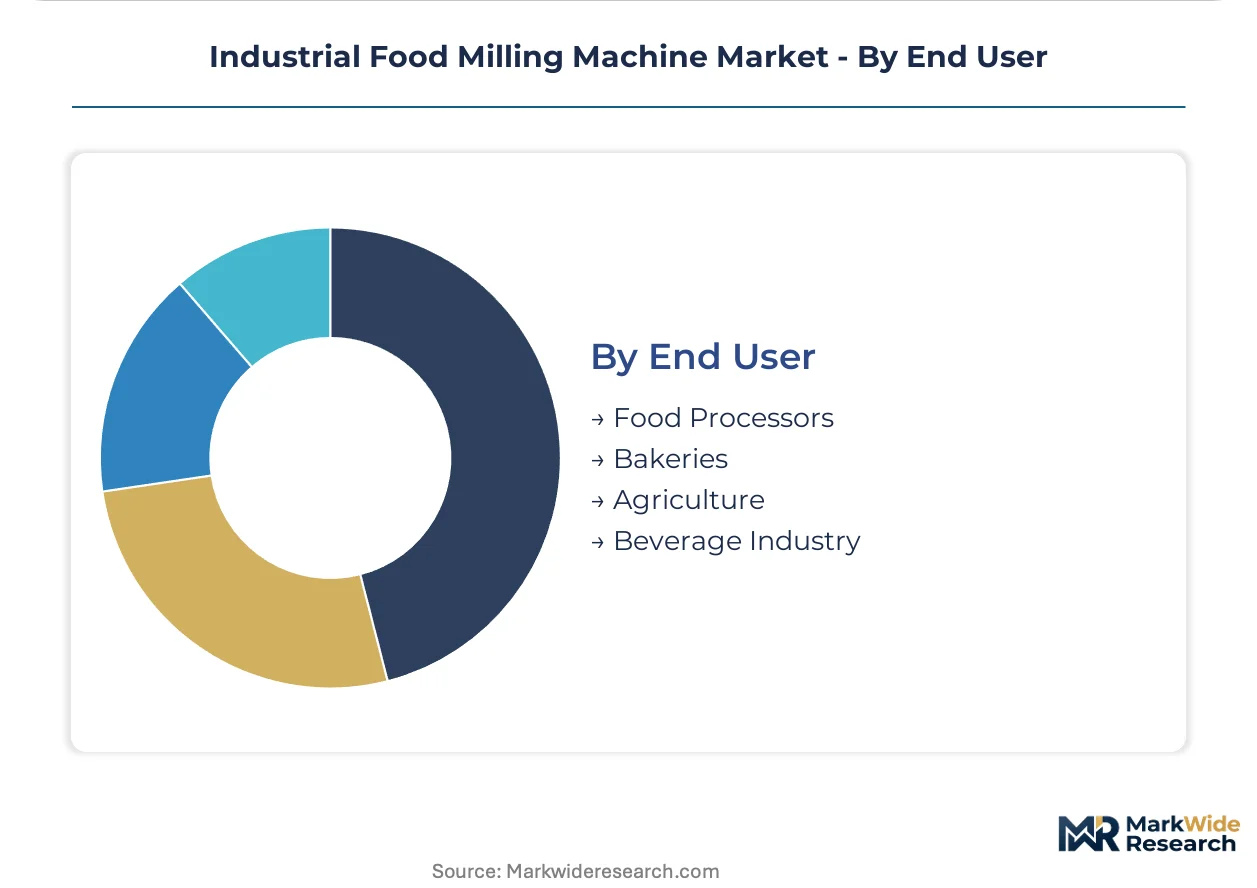
End User:
Procurement sophistication and specification stringency escalate through the value chain, with integrated food processors imposing hygienic design certifications that fragmented agricultural operators rarely demand.
- Food Processors:Multi-product facilities require rapid changeover capabilities and CIP-compatible construction for allergen management. FDA Food Safety Modernization Act preventive controls and EMA pharmaceutical-grade material guidelines are converging on overlapping validation documentation requirements.
- Bakeries:Mid-scale artisan and industrial operations prioritize consistent flour rheology over maximum extraction rates. German craft bakeries are clustering procurement through regional miller cooperatives to access precision roller mill output.
- Agriculture:On-farm and cooperative feed grinding accepts broader particle-size variance for livestock nutrition applications.
- Beverage Industry:Brewing malt milling and alternative protein base preparation require specialized gap-adjustable roller configurations.
Food processors command the most stringent specification regimes; bakeries are expanding equipment procurement most rapidly as craft segment consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Tamil Nadu are concentrating food processing equipment manufacturing capacity through tax incentives and duty exemptions on stainless-steel imports. These zones are pulling milling machinery deployment toward export-oriented spice processing corridors.
Germany
Baden-Württemberg and Bavaria host precision engineering clusters supplying advanced roller mill configurations for flour mill modernizations. The EU Green Deal's energy-efficiency benchmarks are compressing equipment refresh cycles ahead of historical replacement schedules. Stuttgart-based fabricators are scaling sealed bearing system production to meet REACH compliance deadlines.
India
FSSAI enforcement of hygienic design standards is accelerating replacement demand in turmeric and chili powder processing facilities. The PLI scheme for food processing machinery offers capital subsidy incentives for domestic equipment procurement. Gujarat's special economic zones are concentrating export-oriented hammer mill manufacturing for Southeast Asian markets.
China
GB standards on food machinery safety are fragmenting market access protocols for imported milling equipment. Dual carbon goals are elevating electrical drive technology adoption in greenfield flour installations. Shandong Peninsula fabricators are scaling domestic air-classifier production to reduce reliance on European component imports.
United States
FDA Food Safety Modernization Act preventive controls are mandating hygienic design certifications for new milling installations in multi-product food processing facilities. Midwest grain milling corridors are retrofitting pneumatic conveying integration to address dust containment requirements. Minnesota-based cooperatives are clustering procurement for precision roller mill output serving artisan bakery consolidation.
Switzerland
Swissmedic-aligned pharmaceutical-grade food contact material guidelines are converging with EMA requirements for premium powder processing equipment. Integrated supply chains from foundry to final assembly sustain competitive positioning in precision milling systems. Zurich-region engineering groups are licensing thermal management architectures to German mill fabricators.
Industrial Food Milling Machine Market Competitive Landscape
German and Swiss producers anchor the premium-tier precision segment; Chinese and Turkish specialists hold cost-competitive positions in hammer mill and standard roller configurations. The vendor base splits between consolidated integrated solution providers and fragmented component specialists. Three archetypes dominate: vertically integrated European engineering groups, Asian scale fabricators serving export markets, and niche precision specialists in optical sorting adjacencies. Competitive dynamics center on strategic partnerships for air-classifier integration and geographic expansion through localized assembly licensing.
Among Swiss-based integrated engineering groups, Bühler Group exemplifies the vertically integrated archetype with captive foundry-to-assembly supply chain control. Hosokawa Micron Group and Satake Corporation represent the precision-technology tier, with the former anchoring air-classifier integration capabilities and the latter occupying optical sorting convergence positions. These three companies illustrate the strategic divergence between European integrated manufacturing and Japanese precision-engineering specializations.
| Leading Market Players |
|---|
| Bühler Group |
| Hosokawa Micron Group |
| Satake Corporation |
| Alapala Machine Industry & Trade Inc. |
| Brabender GmbH & Co. KG |
| IKA Werke GmbH & Co. KG |
| The Fitzpatrick Company |
| Prater Industries |
| Kemutec Group Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal energy-efficiency benchmarks gate qualified supply and premium-tier pricing access, compressing equipment refresh cycles while elevating stainless-steel construction and sealed bearing systems as baseline procurement criteria for flour millers and spice processors.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with German precision engineering clusters commanding 15-20% premiums for sub-12-week commissioning against Turkish and Chinese spot inventory discounts. Price differentiation hinges on REACH-compliant certification grade and after-sales service bundling, with predictive maintenance telemetry packages separating premium vendors. Cost compression in mid-tier hammer mill configurations is intensifying due to nickel and chromium input volatility. Small-scale spice processors in India and Vietnam exhibit highest price sensitivity, while integrated European food processors prioritize hygienic design certifications over unit economics.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for critical bearing and drive components, with food processors refusing single-source dependencies on German or Swiss precision subassemblies. Manufacturing concentration centers on Germany, Switzerland, and China, with Baden-Württemberg fabricators captive-producing precision castings and Shandong Peninsula scaling domestic air-classifier production. Raw material dependencies rest on food-grade stainless steel, specialized alloy inputs, and electrical drive systems. Single-source vulnerability in precision-ground roller cylinders creates structural risk. Distribution runs through OEM-direct commissioning for large flour installations and regional distributor networks for aftermarket spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrical drive technology with integrated predictive maintenance telemetry is displacing legacy mechanical configurations, compressing the performance gap between established roller mills and emerging impact-based alternatives across flour and spice processing corridors.
For Market Incumbents: Deepen captive supply chain control over precision casting and air-classifier component production to defend margin position against Turkish and Chinese cost competitors. Prioritize sealed bearing system R&D allocation ahead of REACH enforcement timelines. Lock in multi-year service contracts with German and Swiss flour millers to secure replacement-cycle revenue visibility.
For New Entrants and Emerging Players: Enter via underpenetrated precision spice processing facilities in Gujarat and Tamil Nadu special economic zones, where FSSAI hygienic design enforcement accelerates replacement demand below 30% air-classifier adoption rates. Target export-oriented turmeric and chili powder processors with REACH-compliant hammer mill configurations. Pursue licensing partnerships with established pneumatic conveying integrators to bypass ATEX certification barriers.
For Investors and Strategic Acquirers: ECHA acceleration of pre-2027 equipment procurement is the leading indicator that sealed bearing and solid lubricant technology specialists will command acquisition premiums. Position for 5-10 year viability in vendors with integrated foundry-to-assembly supply chains and pharmaceutical-grade certification pathways. Watch for FSSAI enforcement timeline announcements as the signal for Indian subcontinent replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive supply of roller mill cylinders reduces commissioning lead times for German flour mill modernizations. |
| Air-Classifier Technology Licensing | Swiss thermal management architectures extend particle-size precision below 50 microns for pharmaceutical-adjacent applications. |
| Pneumatic Conveying Retrofit Programs | ATEX-compliant dust containment opens legacy European flour mill upgrade revenue streams. |
| Predictive Maintenance Subscription Unbundling | Component-specific service tiers capture multi-brand installed base interoperability demand in India. |
| Optical Sorting Convergence Development | Color-recognition integration enables real-time contamination rejection in continuous spice processing lines. |
Research Methodology
Independent corroboration across plant engineering directors, OEM procurement teams, aftermarket service heads, and food safety compliance officers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from SEC filings of listed equipment manufacturers, EU ECHA regulatory enforcement notices, and FSSAI hygienic design standard publications. Customs trade data on stainless-steel alloy imports and food machinery export registrations provided demand-side triangulation. Bottom-up installation tracking across German Baden-Württemberg precision clusters and Indian Gujarat special economic zones was cross-referenced against top-down capacity estimates from industry associations.
Comparable-period anchoring to historical replacement cycle data informed the projection horizon, with segmentation modeling across product type, application substrate, drive technology, and end-user sophistication. CAGRs were derived from equipment shipment volumes, capacity utilization rates, and capital expenditure pipeline visibility. Industry-specific forecast inputs included EU Green Deal implementation timeline compression and FSSAI enforcement acceleration signals.
Revisions become necessary when REACH substance restriction amendments, nickel supply disruptions, or FSSAI hygienic design deadline shifts materialize. Deviation in German precision cluster capacity expansion or Indian PLI scheme subsidy allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Nut Processing Machine Market