
 UHT Systems Market | 2026-2036
UHT Systems Market Size, Share, and Industry Trends Forecast 2026-2036
UHT Systems Market Analytics
Aftermarket service revenue is narrowing as a margin pool toward continuous system retrofits and plate heat exchanger refurbishment. Tetra Pak leverages its installed base of aseptic filling lines to capture recurring service contracts across dairy cooperatives. GEA Group anchors its position through backward integration into heat exchanger plate manufacturing, reducing lead times for spare parts. Alfa Laval competes by specializing in scraped surface heat exchanger technology for viscous food applications.
UHT systems employ thermal processing equipment that heats liquid products to 135-150°C for 2-8 seconds before aseptic cooling, eliminating spoilage microorganisms while preserving nutritional content for shelf-stable distribution. Continuous systems dominate capital expenditure flows due to their throughput advantages in high-volume milk processing operations. Tubular heat exchanger technology leads installed capacity in juice processing lines where fiber content demands wider bore configurations. Hybrid systems represent the fastest-growing product category as processors seek flexibility across seasonal product rotations.
FDA enforces 21 CFR Part 113 for low-acid foods and aseptic processing systems, while EFSA's hygiene package mandates HACCP-integrated equipment design across EU dairy operations. China's NMPA and SAMR impose GB standards on imported UHT equipment, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor regulatory divergence between FDA pasteurization-equipment guidelines and emerging MEE environmental standards in China that affect cooling water discharge from thermal processing plants.
Market Dynamics
Hybrid UHT system architectures are forcing capital allocation shifts as dairy processors prioritize production flexibility over single-product line efficiency. Equipment suppliers must now engineer modular thermal processing platforms capable of rapid reconfiguration between fluid milk, plant-based beverages, and extended-shelf-life cream products.
Growth Catalysts
- EFSA Hygiene Package mandates:European dairy cooperatives face equipment replacement deadlines that accelerate orders for HACCP-integrated continuous systems with automated CIP validation.
- Indonesia's fluid milk corridor expansion:State-backed cold chain infrastructure investments in Java and Sumatra create concentrated demand for high-throughput tubular heat exchanger installations.
- Scraped surface technology advances:Viscous product processors in confectionery and sauces adopt specialized heat exchanger configurations previously confined to dairy applications.
Market Restraints
- Stainless steel price volatility:316L grade alloy fluctuations compress margins on heat exchanger plate manufacturing and extend quotation validity periods.
- Spare parts supply concentration:Precision gasket and plate stamping capabilities cluster in German and Italian industrial zones, exposing buyers to extended lead times during regional disruptions.
- GB standards compliance burden:China's NMPA and SAMR impose testing protocols on imported UHT equipment that add certification cycles without equivalent domestic reciprocity.
Strategic Opportunities
- Vietnam dairy processing emergence:Greenfield investments by regional dairy cooperatives seek first-mover equipment suppliers for aseptic filling and thermal processing integration.
- Plant-based beverage retrofit demand:Oat and almond milk processors require heat exchanger reconfiguration services that legacy dairy equipment vendors are positioned to capture.
- MEE environmental standards alignment:China's cooling water discharge regulations create aftermarket service contracts for thermal plant water recycling system upgrades.
Industry Challenges
- ASEAN commissioning engineer scarcity:Specialized technicians capable of validating aseptic system performance across Tetra Pak, GEA, and Alfa Laval platforms command premium compensation in Indonesia and Vietnam.
- Legacy control system integration:Brownfield dairy plants in Southeast Asia operate 1990s-era SCADA architectures that resist seamless connection to modern continuous UHT monitoring suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHT Systems Market |
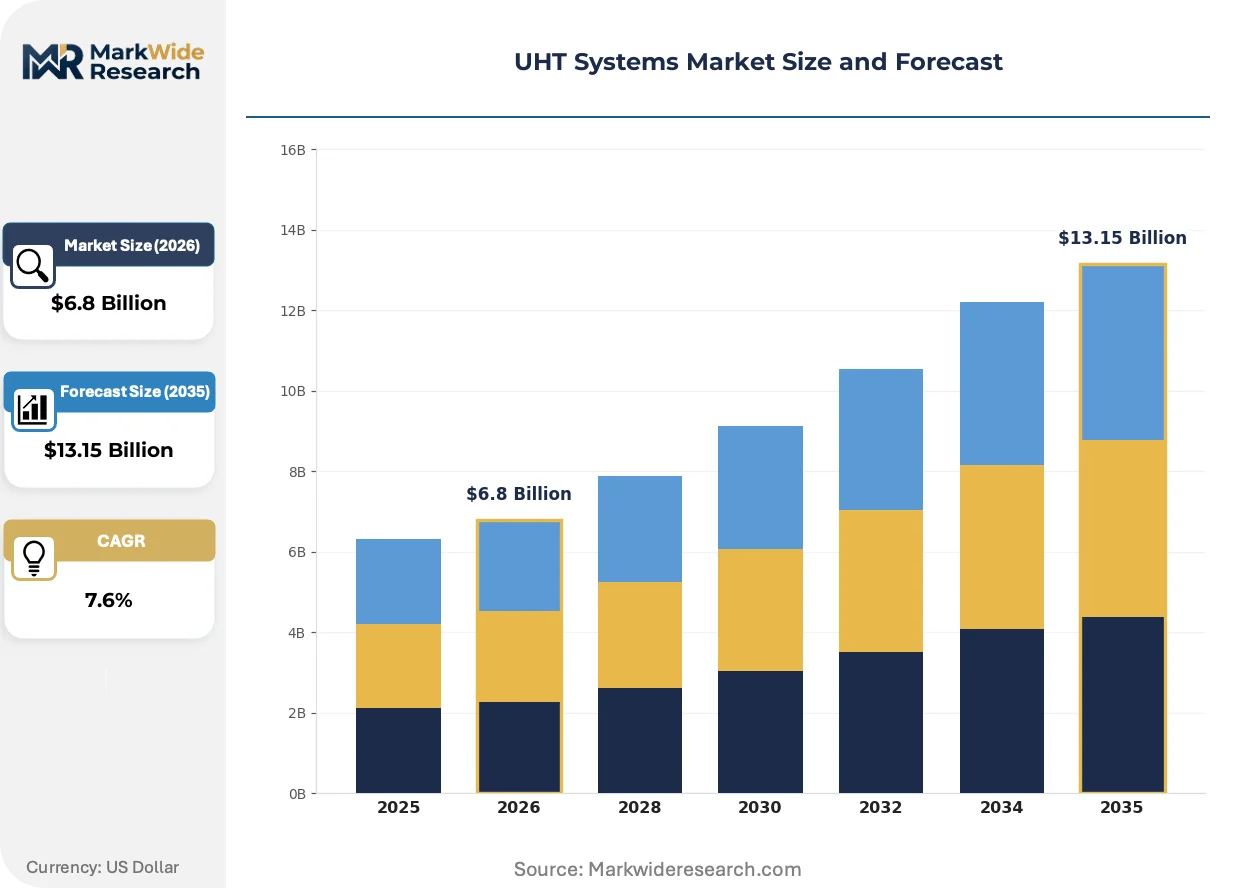
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Hybrid Systems, Compact Systems Technology: Plate Heat Exchanger, Tubular Heat Exchanger, Scraped Surface Heat Exchanger, Others End User: Dairy Industry, Beverage Industry, Food Industry, Pharmaceutical Industry Application: Milk Processing, Juice Processing, Soup Processing, Sauces Processing |
| Companies Covered | Tetra Pak, GEA Group, Alfa Laval, SPX FLOW, JBT Corporation, Krones AG, MicroThermics, Iwai Kikai Kogyo, Elecster Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHT Systems Market Evolving Landscape
Digital twin deployment is compressing commissioning timelines and enabling predictive maintenance contracts that reshape supplier-customer relationships. Equipment vendors now compete on software-enabled uptime guarantees rather than hardware specifications alone.
Pulse electric field sterilization is rendering obsolete conventional thermal processing for sensitive nutritional applications. Premium juice processors in California and Bavaria pilot hybrid systems combining minimal heat treatment with electroporation. This convergence is rendering obsolete the throughput-versus-quality trade-off that previously segmented equipment categories.
FDA's 21 CFR Part 113 enforcement priorities are tightening validation documentation requirements for low-acid aseptic systems. Third-party certification bodies now embed directly in equipment procurement workflows. Small and mid-sized dairy processors in Wisconsin and New York face disproportionate compliance cost absorption.
Service contract unbundling is fragmenting traditional full-service maintenance agreements. Dairy cooperatives in the Netherlands and Denmark now separately procure heat exchanger plate refurbishment, automation software updates, and regulatory audit preparation. This disaggregation favors specialized regional service providers over integrated OEM service arms.
UHT Systems Market Segmentation
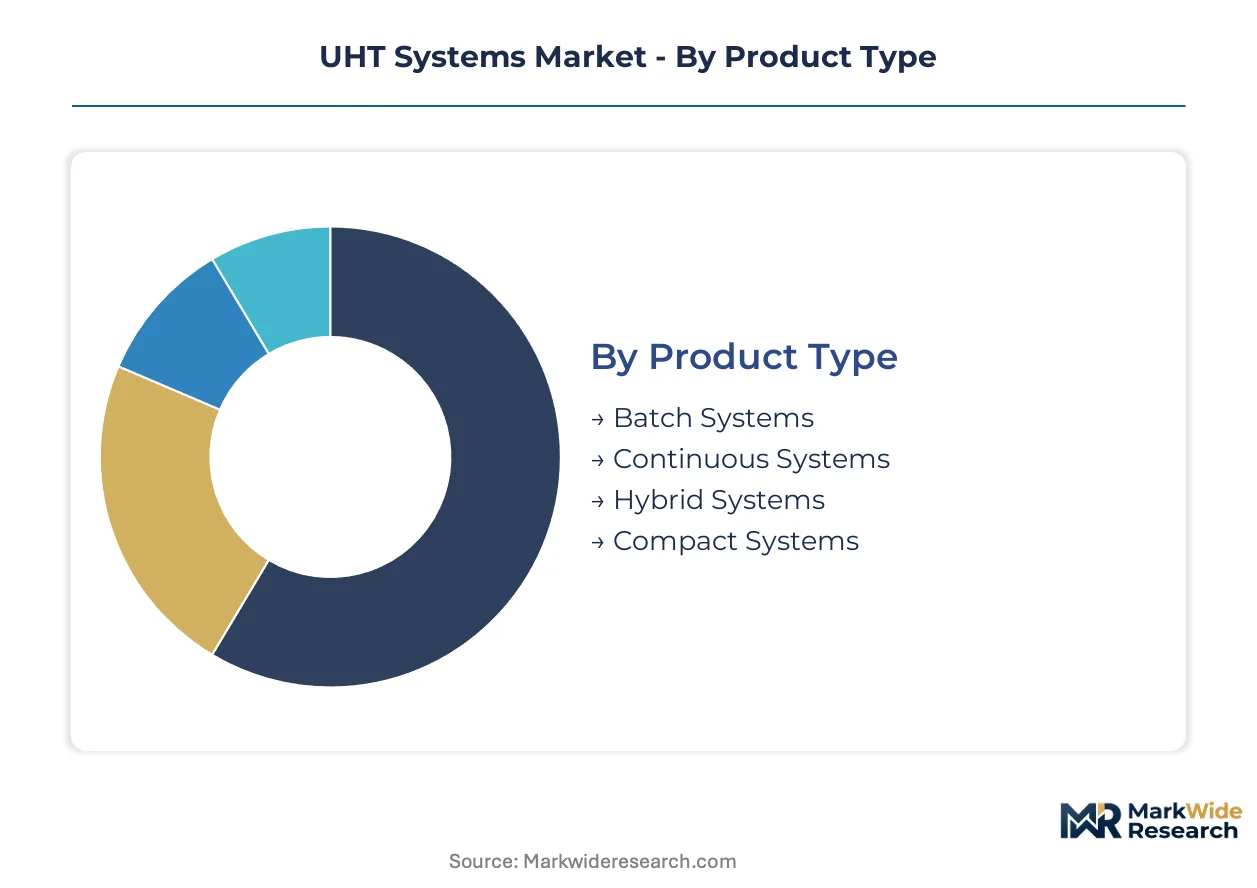
UHT system procurement decisions hinge on thermal processing intensity, product viscosity, and regulatory compliance requirements. Equipment specifications diverge sharply between high-volume dairy corridors and specialized pharmaceutical sterilization lines.
Product Type:
Processors select system architecture based on throughput requirements and product portfolio breadth, with capital allocation shifting toward flexible configurations.
- Continuous Systems:These systems sustain non-stop thermal processing for 135-150°C sterilization cycles, delivering throughput advantages in Indonesia's fluid milk packaging corridors where state-backed cold chain investments concentrate demand. FDA 21 CFR Part 113 validation requirements for low-acid foods favor continuous architectures with automated CIP documentation.
- Hybrid Systems:Modular platforms enable rapid reconfiguration between fluid milk, plant-based beverages, and extended-shelf-life cream products. Dairy processors in Vietnam and the Netherlands prioritize this flexibility over single-product line efficiency as seasonal rotations intensify.
- Batch Systems:Intermittent processing suits small-scale pharmaceutical sterilization and specialty dairy operations with variable batch sizes.
- Compact Systems:Footprint-constrained installations in urban dairy plants and beverage startups favor skid-mounted configurations with reduced utility demands.
The dominant share belongs to Continuous Systems, while Hybrid Systems is closing the gap fastest.
Technology:
Heat exchanger selection determines thermal efficiency, fouling resistance, and maintenance intervals across viscosity gradients.
- Plate Heat Exchanger:Corrugated stainless steel plates maximize surface area-to-volume ratios for low-viscosity fluids. GEA Group's backward integration into 316L plate manufacturing reduces lead times for dairy cooperatives facing EFSA hygiene package replacement deadlines.
- Tubular Heat Exchanger:Wider bore configurations accommodate fiber-laden juice processing lines where pulp content obstructs plate gaps. Installations dominate California and Bavarian premium juice corridors piloting minimal heat treatment protocols.
- Scraped Surface Heat Exchanger:Rotating blades prevent fouling in viscous confectionery and sauce applications. Alfa Laval specializes in this configuration for products previously confined to dairy processing.
- Others:Direct steam injection and infusion systems serve niche applications requiring instantaneous heating without surface contact.
Plate Heat Exchanger holds the installed base majority, though Tubular Heat Exchanger is gaining share in fiber-heavy beverage segments.
End User:
Regulatory stringency and shelf-life requirements create distinct equipment specifications across processing industries.
- Dairy Industry:Fluid milk processors in Indonesia, Vietnam, and the Netherlands drive equipment upgrades as FDA and EFSA tighten pasteurization-equipment hygiene standards. Tetra Pak captures recurring service contracts through its aseptic filling line installed base.
- Beverage Industry:Oat and almond milk processors require heat exchanger reconfiguration services that legacy dairy equipment vendors are positioned to capture.
- Food Industry:Soup and sauce manufacturers adopt scraped surface technology from dairy applications for viscous product sterilization.
- Pharmaceutical Industry:Aseptic processing for parenteral solutions demands validated sterilization assurance beyond food-grade requirements.
Dairy Industry commands the largest equipment procurement volume, while Beverage Industry is expanding most quickly on plant-based retrofit demand.
Application:
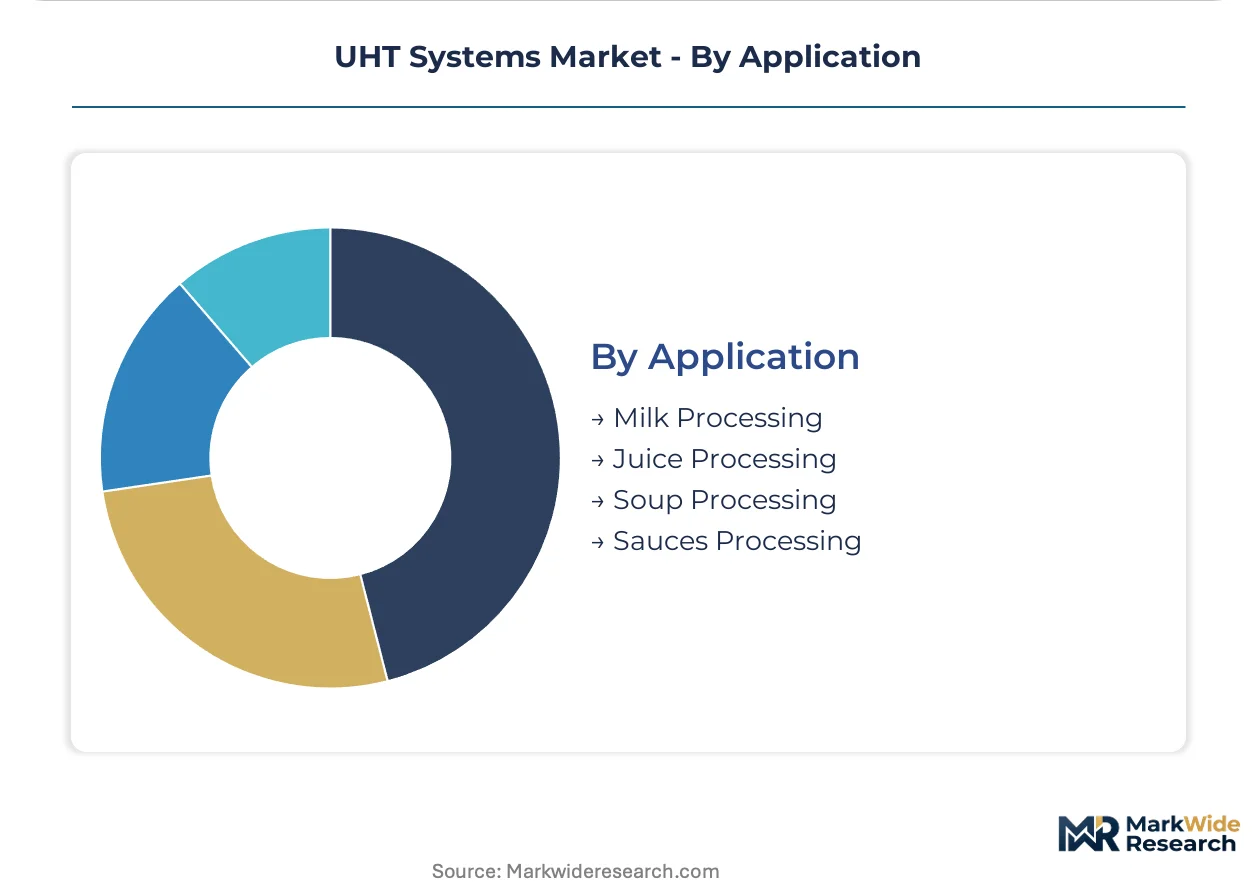
Thermal processing parameters vary by product acidity, particulate load, and nutritional sensitivity.
- Milk Processing:High-throughput continuous systems serve shelf-stable fluid milk distribution across Southeast Asian cold chain corridors. China's MEE environmental standards create aftermarket demand for cooling water recycling upgrades.
- Juice Processing:California and Bavarian premium processors pilot hybrid thermal-electric field systems combining minimal heat with pulse electric field sterilization.
- Soup Processing:Viscous formulations with suspended solids require scraped surface or tubular configurations resistant to fouling.
- Sauces Processing:Tomato and dairy-based condiments demand heat exchanger specifications balancing thermal penetration with texture preservation.
Milk Processing retains the dominant application share, with Juice Processing showing the steepest expansion trajectory on premium nutritional preservation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia exhibit acute price sensitivity to stainless steel volatility, while European dairy cooperatives absorb premium pricing for EFSA-compliant validation documentation without volume elasticity.
Indonesia
State-backed cold chain infrastructure investments in Java and Sumatra concentrate demand for high-throughput tubular heat exchanger installations. The National Agency of Drug and Food Control (BPOM) enforces sanitary equipment certification that favors established suppliers with local service presence. Dairy processing clusters in West Java's Bogor and Bandung corridors drive continuous system orders as fluid milk packaging expands.
China
NMPA and SAMR impose GB standards testing protocols on imported UHT equipment that extend certification cycles. The Ministry of Ecology and Environment (MEE) cooling water discharge regulations create aftermarket service contracts for thermal plant water recycling system upgrades. Yangtze River Delta dairy processors in Jiangsu and Zhejiang provinces prioritize compact skid-mounted configurations for urban footprint constraints.
Germany
Bavarian premium juice processors pilot hybrid thermal-electric field systems combining minimal heat with pulse electric field sterilization. EFSA's hygiene package mandates HACCP-integrated equipment design that accelerates replacement orders for continuous systems with automated CIP validation. Stuttgart and Munich industrial zones host precision gasket and plate stamping capabilities that supply spare parts across European dairy operations.
United States
FDA 21 CFR Part 113 enforcement priorities tighten validation documentation requirements for low-acid aseptic systems. Small and mid-sized dairy processors in Wisconsin and New York face disproportionate compliance cost absorption. California's Central Valley juice corridors drive tubular heat exchanger demand where fiber content demands wider bore configurations.
Vietnam
Greenfield investments by regional dairy cooperatives seek first-mover equipment suppliers for aseptic filling and thermal processing integration. The country's food safety authority imposes equipment hygiene standards that mirror ASEAN harmonization frameworks. Ho Chi Minh City and Hanoi processing corridors concentrate procurement decisions for hybrid system architectures enabling seasonal product rotations.
UHT Systems Market Competitive Landscape
Capability concentration sits with specialized heat exchanger technology developers; scale advantage sits with integrated processing line suppliers with expansive installed bases. The market structures around three tiers: full-system integrators owning aseptic filling-to-thermal processing workflows; component specialists commanding heat exchanger plate and scraped surface engineering depth; and regional fabricators serving price-sensitive brownfield retrofit demand. Dominant competitive moves include backward integration into precision component manufacturing and predictive maintenance software licensing.
Among European-based industrial equipment groups, Tetra Pak, GEA Group, and Alfa Laval occupy distinct positioning vectors. Tetra Pak exemplifies the full-system integrator archetype through its aseptic filling line installed base. GEA Group anchors the component-specialist tier with captive heat exchanger plate manufacturing capabilities. Alfa Laval represents technology depth in viscous product applications, extending scraped surface configurations beyond traditional dairy boundaries.
| Leading Market Players |
|---|
| Tetra Pak |
| GEA Group |
| Alfa Laval |
| SPX FLOW |
| JBT Corporation |
| Krones AG |
| MicroThermics |
| Iwai Kikai Kogyo |
| Elecster Oyj |
| Others |
Value Network & Pricing Analysis
Stainless steel 316L price volatility compresses margins across heat exchanger plate manufacturing and forces equipment suppliers into longer quotation validity periods, widening spreads between premium EFSA-validated systems and economy-tier regional fabricators while concentrating procurement power with buyers who can absorb inventory risk.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture as dairy cooperatives unbundle maintenance agreements into separate heat exchanger refurbishment, automation updates, and regulatory audit preparation tiers. Three-tier pricing structure across premium, standard, and economy levels separates Tetra Pak's integrated aseptic line service bundles from GEA's component-specialist spare parts pricing and regional fabricators' bare-equipment quotes. Cost compression in economy-tier skid-mounted systems is intensifying because Indonesian and Vietnamese buyers exhibit acute price sensitivity to alloy fluctuations. Dairy cooperatives in the Netherlands and Denmark show least price sensitivity, absorbing premium documentation costs without volume elasticity.
Supply Chain Analysis
Upstream 316L stainless steel feedstock draws from German, Italian, and Chinese metallurgical centers, with precision gasket stamping and plate forming capabilities clustering in Stuttgart, Munich, and northern Italian industrial zones. Heat exchanger manufacturing rests on nickel alloy supply chains, specialized stamping equipment, and FDA-grade elastomer certification programs. Single-source vulnerability concentrates in precision plate corrugation tooling held by a limited supplier set. Distribution runs through OEM direct sales for large dairy cooperatives, regional distributor networks for brownfield retrofits, and equipment-leasing channels for startup processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EFSA and FDA validation documentation creates switching costs that lock dairy processors into established supplier relationships across 10-15 year equipment lifecycles.
For Market Incumbents: Entrench position through captive heat exchanger plate manufacturing that compresses spare parts lead times below competitor thresholds, while embedding predictive maintenance software into service contracts to capture unbundled procurement flows. Pulse electric field sterilization pilots in California and Bavaria threaten thermal processing incumbency, demanding R&D investment in hybrid thermal-electric architectures. Certification investment in China's GB standards compliance creates exclusionary barriers against non-domestic entrants. For New Entrants and Emerging Players: Build out regional service capabilities in Vietnam's greenfield dairy corridors where first-mover equipment suppliers face limited incumbent installed base. Plant-based beverage retrofit demand offers the most penetrable segment, as oat and almond milk processors require heat exchanger reconfiguration services that legacy vendors underprice. Go-to-market angle: specialized scraped surface technology for viscous confectionery applications previously confined to dairy, leveraging Alfa Laval's technology extension precedent. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component-specialist acquisition targets with captive manufacturing and regulatory validation depth. Long-term viability hinges on software-enabled service revenue transformation rather than hardware shipment cyclicality. Acquisition target archetype: heat exchanger plate manufacturers with FDA-grade elastomer capabilities and Southeast Asian service presence. Signal to watch: digital twin deployment rates compressing commissioning timelines and enabling predictive maintenance contract penetration above threshold levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Plate Manufacturing | GEA Group's captive 316L plate production reduces spare parts lead times for EFSA-facing dairy cooperatives. |
| Predictive Maintenance Software Licensing | Digital twin deployment compresses commissioning timelines and reshapes supplier-customer relationships around uptime guarantees. |
| Hybrid Thermal-Electric System Development | Pulse electric field pilots in California and Bavaria threaten to obsolete conventional thermal processing for sensitive nutritional applications. |
| GB Standards Compliance Certification | China's NMPA and SAMR testing protocols create exclusionary barriers favoring suppliers with established domestic validation. |
| Regional Service Hub Establishment | Vietnam's greenfield dairy investments concentrate procurement decisions for suppliers with local commissioning engineer presence. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade databases, and equipment procurement records from Southeast Asian dairy cooperatives. Primary interviews engaged maintenance directors at fluid milk processors, plant engineers at juice manufacturing facilities, OEM procurement teams at Tetra Pak and GEA Group, and aftermarket service heads at regional distributor networks. Bottom-up equipment shipment data triangulates against top-down dairy processing capacity expansion announcements across Indonesia, Vietnam, and the Netherlands.
Forecast inputs include thermal processing intensity requirements, product viscosity gradients, and regulatory compliance tier differentiation across the projection horizon. Segmentation dimensions modeled encompass system architecture type, heat exchanger technology category, end-user industry vertical, and application-specific thermal parameters. CAGRs derive from installed base depreciation cycles, replacement demand timing, and greenfield capacity expansion pipelines. Industry-specific inputs capture EFSA hygiene package enforcement deadlines and Indonesia's state-backed cold chain infrastructure commitments.
Stress conditions across stainless steel alloy price bands, ASEAN commissioning engineer availability, and FDA validation documentation requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and dairy processor capital allocation priorities. Cross-checking against EFSA equipment replacement announcement databases and Indonesian central government infrastructure disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Automation Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Global High Pressure Processing (HPP) Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Edible Oil Extracting Machine Market