
 5G WIT120 Market | 2026-2036
5G WIT120 Market Size, Share, and Industry Trends Forecast 2026-2036
5G WIT120 Market Insights
3GPP Release 16 certification is collapsing the supplier field to vendors with proven interoperability testing. Huawei Technologies leverages its end-to-end equipment portfolio to dominate integrated network deployments. Intel Corporation sustains semiconductor leadership through baseband processor design for open RAN architectures. Nokia Corporation competes aggressively on massive MIMO antenna systems for dense urban coverage.
The 5G WIT120 encompasses wireless infrastructure terminals operating in sub-6 GHz and millimeter-wave bands, delivering peak throughput above 1 Gbps through integrated modem-router-antenna systems purpose-built for ultra-reliable low-latency communication. Massive MIMO technology leads capital deployment among hardware categories as carriers densify macro sites. Beamforming is displacing conventional sector antennas in urban corridors where spectrum efficiency determines operational economics. Network slicing is creating new margin pools for telecom operators selling differentiated enterprise connectivity to manufacturing and logistics buyers.
The FCC governs spectrum auctions and equipment authorization in the United States, while the EU AI Act and CE marking framework shape product compliance requirements across European deployments. China's MIIT enforces domestic GB standards that privilege local vendors in procurement cycles. Stakeholders must monitor evolving open RAN interoperability mandates from the O-RAN Alliance and national regulators, as these specifications determine which suppliers qualify for public infrastructure tenders without legacy lock-in.
Market Dynamics
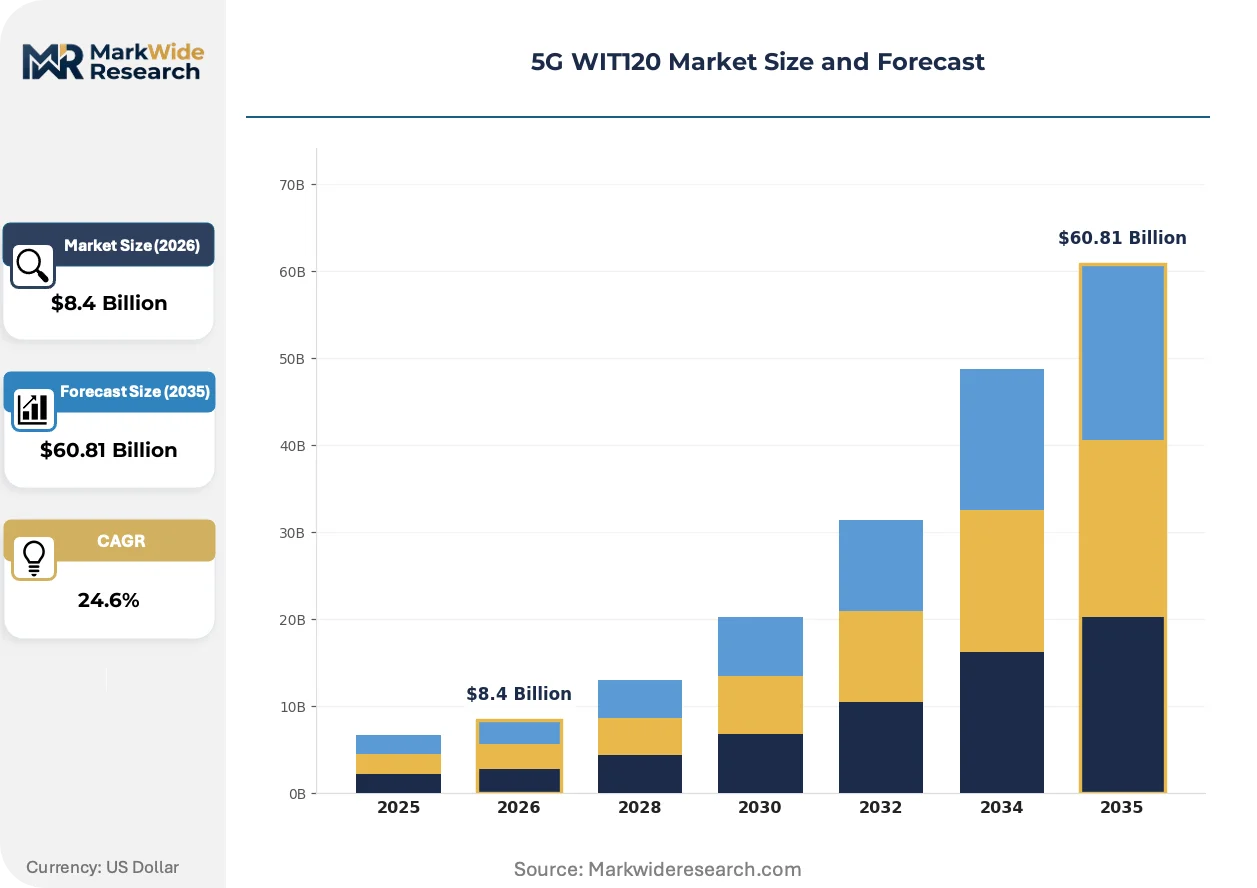
The 5G WIT120 market is being fundamentally restructured by the FCC's spectrum auction regime, which is compressing deployment timelines and forcing carriers to accelerate hardware procurement cycles ahead of license expiration deadlines.
Growth Catalysts
- Smart city infrastructure mandates:Municipal governments in the United States are embedding 5G WIT120 terminals into traffic management and public safety networks, creating recurring procurement streams.
- Open RAN interoperability standards:The O-RAN Alliance's fronthaul specifications are unlocking multi-vendor deployments and reducing equipment switching costs for tier-2 carriers.
- Millimeter-wave densification requirements:Urban spectrum congestion in sub-6 GHz bands is pushing carriers toward higher-frequency small cell rollouts.
Market Restraints
- GaN semiconductor supply concentration:Gallium nitride substrate fabrication for power amplifiers remains concentrated among a handful of East Asian foundries, creating input vulnerability.
- Site acquisition friction:Zoning boards and utility pole access disputes in dense US metropolitan areas are extending deployment timelines by 12-18 months.
- Legacy 4G infrastructure lock-in:Carriers with substantial sunk investment in LTE-Advanced equipment face elevated stranded asset risk when migrating core networks.
Strategic Opportunities
- Private 5G networks for manufacturing:Industrial campuses in Germany and South Korea are deploying campus-wide WIT120 systems for deterministic machine control.
- Network slicing for logistics:Telecom operators are packaging guaranteed latency tiers to warehouse automation buyers, creating recurring enterprise revenue.
- FCC CBRS priority access licensing:The three-tier spectrum framework is enabling neutral host deployments in stadiums and convention centers.
Industry Challenges
- RF engineer talent scarcity:The specialized skill set for millimeter-wave propagation modeling and beamforming calibration is concentrated among a shrinking pool of experienced practitioners.
- 3GPP Release 16 certification complexity:Multi-vendor interoperability testing timelines are extending product qualification cycles, delaying revenue recognition for new equipment introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G WIT120 Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modems, Routers, Antennas, Repeaters Technology: Massive MIMO, Beamforming, Network Slicing, Small Cells End User: Telecom Operators, Enterprises, Government, ISP Application: Smart Cities, IoT, Autonomous Vehicles, Remote Healthcare |
| Companies Covered | AT&T, Capsule Technologies, Huawei Technologies, Intel Corporation, Samsung Electronics, Telefonaktiebolaget LM Ericsson, Verizon Communications Inc, Nokia Corporation, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G WIT120 Market Trends and Innovations
Beamforming architectures are actively displacing conventional sector antennas across urban macro sites, while regulatory pressure on spectrum efficiency is accelerating hardware refresh cycles beyond traditional depreciation schedules.
Massive MIMO antenna arrays with 64T64R configurations are supplanting 8T8R systems in dense urban corridors. Tier-1 carriers in the United States and China are deploying these systems at scale to maximize spectral efficiency per site. The shift is compressing equipment replacement cycles from seven years to four years.
The FCC's equipment authorization process under Part 27 rules is tightening electromagnetic compatibility requirements for millimeter-wave devices. Manufacturers must now submit expanded thermal and RF exposure documentation before market entry. This regulatory tightening is most acute for small cell vendors targeting stadium and airport deployments.
Enterprise buyers are consolidating procurement decisions at the headquarters level rather than delegating to regional IT managers. Long-term managed service contracts with guaranteed uptime SLAs are replacing traditional capex-heavy equipment purchases. This pattern is most visible among logistics and automotive manufacturing verticals in Germany and the United States.
5G WIT120 Market Segmentation
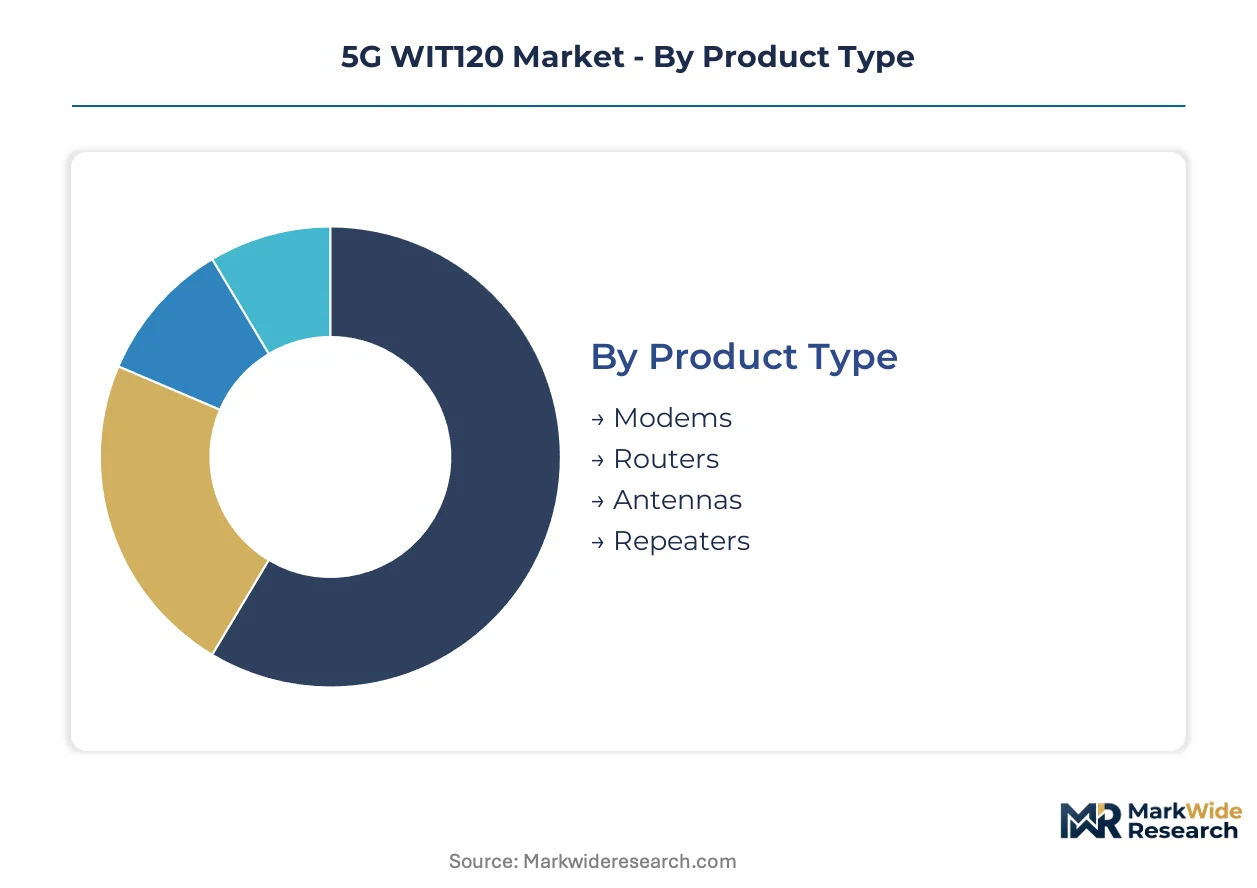
5G WIT120 procurement patterns diverge sharply across customer types, with carrier bulk orders favoring integrated systems while enterprise buyers prioritize modular configurations. Understanding these channel dynamics enables suppliers to calibrate pricing architectures and service bundling.
Product Type:
Modems and routers flow predominantly through carrier direct procurement channels, while antennas and repeaters see stronger distribution via systems integrators serving enterprise and government verticals.
- Modems:Integrated baseband-modem chipsets handle signal conversion between digital payload and RF waveforms. Telecom operators in China and the United States concentrate procurement for macro site upgrades, driven by 3GPP Release 16 certification requirements that collapse qualified supplier pools.
- Routers:Edge routing platforms aggregate traffic from multiple WIT120 terminals with sub-millisecond forwarding latency. Enterprise campuses in Germany and South Korea represent expanding demand centers, propelled by private 5G network mandates for deterministic machine control.
- Antennas:Passive and active antenna elements shape radiation patterns for specific coverage footprints.
- Repeaters:Signal amplification units extend coverage into tunnels, stadiums, and remote industrial corridors.
Modems dominate installed base. Routers are where expansion concentrates.
Technology:
Cost tier stratification separates Massive MIMO as premium infrastructure from Small Cells as economy-tier densification, with Beamforming and Network Slicing occupying mid-tier positioning based on software intensity.
- Massive MIMO:64T64R active antenna systems deploy hundreds of radiating elements with independent phase control. Dense urban corridors in the United States and China anchor deployment, compressed by FCC spectrum auction deadlines and MIIT domestic rollout mandates.
- Beamforming:Digital precoding algorithms steer energy toward user equipment rather than broadcasting uniformly. Urban macro sites across municipal governments are displacing conventional sector antennas, forced by spectrum efficiency economics in sub-6 GHz congestion.
- Network Slicing:Virtualized core partitioning enables differentiated service tiers.
- Small Cells:Low-power base stations fill coverage gaps and capacity hotspots.
Massive MIMO commands the steepest expansion trajectory. Small Cells hold the deepest installed base penetration.
End User:
Volume concentration follows a hierarchy where Telecom Operators absorb 70%+ of hardware throughput, while Enterprises and Government buyers drive margin expansion through managed service premiums.
- Telecom Operators:Tier-1 carriers deploy WIT120 systems at national scale with seven-year depreciation schedules now compressing to four. China Mobile, Verizon, and Deutsche Telekom anchor procurement volumes, reshaped by open RAN interoperability mandates from the O-RAN Alliance.
- Enterprises:Manufacturing campuses and logistics hubs procure private 5G systems for deterministic automation. Automotive assembly plants in Germany and semiconductor fabs in South Korea are expanding fastest, pulled by guaranteed latency SLAs for robotic control.
- Government:Municipal and federal agencies embed WIT120 into public safety and traffic networks.
- ISP:Fixed-wireless access providers compete with fiber in underserved regions.
Telecom Operators dominate installed base. Enterprises are where expansion concentrates.
Application:
Maturity gradients separate Smart Cities as established deployment terrain from Autonomous Vehicles as emergent demand, with IoT and Remote Healthcare occupying transitional growth phases.
- Smart Cities:Integrated traffic management, public safety, and environmental monitoring networks deploy WIT120 at municipal scale. Cities across the United States and China are embedding terminals into street furniture and utility infrastructure, accelerated by federal infrastructure grants and MIIT smart city mandates.
- IoT:Massive machine-type communications require WIT120 adaptations for low-complexity, battery-constrained endpoints. Warehouse automation and agricultural sensor networks in Germany and the United States are scaling deployments, driven by enterprise headquarters-level procurement consolidation.
- Autonomous Vehicles:V2X communication infrastructure demands ultra-reliable low-latency links.
- Remote Healthcare:Telemedicine and surgical robotics require guaranteed bandwidth tiers.
Smart Cities dominate installed base. IoT is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum auction deadlines compress carrier procurement cycles in the United States. China's MIIT mandates accelerate domestic equipment rollout. Germany's private 5G network programs reshape industrial demand patterns.
United States
Municipal smart city mandates and carrier densification requirements drive terminal procurement. The FCC's CBRS three-tier licensing framework enables neutral host deployments in stadiums and convention centers. Dense urban corridors in New York and Los Angeles anchor millimeter-wave small cell rollouts.
China
National 5G infrastructure targets and MIIT domestic standards enforcement concentrate demand among local equipment vendors. GB certification requirements privilege integrated network suppliers in public procurement cycles. The Yangtze River Delta and Pearl River Delta regions host massive macro site upgrade programs.
Germany
Automotive manufacturing automation and Industry 4.0 campus networks expand private 5G system demand. The EU AI Act and CE marking framework shape equipment compliance requirements for European deployments. Bavaria's automotive assembly plants and Baden-Württemberg's machinery clusters deploy deterministic machine control systems.
South Korea
Semiconductor fabrication automation and logistics hub modernization accelerate WIT120 terminal adoption. The country's national spectrum regulator allocates dedicated bands for enterprise private networks. The Seoul Capital Area and Busan-Ulsan industrial corridor anchor campus-wide deployment programs.
Japan
Telemedicine infrastructure and remote surgical robotics create guaranteed bandwidth tier demand. METI industrial policy supports manufacturing sector 5G adoption through targeted subsidy programs. The Kanto region around Tokyo and the Chubu industrial zone near Nagoya concentrate equipment procurement.
5G WIT120 Market Competitive Landscape
Player mix skews toward integrated equipment conglomerates with end-to-end portfolio coverage. The supplier field compresses around vendors with proven 3GPP Release 16 interoperability certification. Three archetypes dominate: telecom operators with captive infrastructure arms, diversified electronics conglomerates with semiconductor-to-systems verticality, and pure-play network equipment specialists. Competitive moves center on open RAN multi-vendor consortium formation and massive MIMO antenna array capacity expansion.
Among diversified technology conglomerates, Huawei Technologies and Samsung Electronics exemplify integrated portfolio strategies spanning baseband processors through active antenna systems. Nokia Corporation and ZTE Corporation occupy positions within the network equipment specialist tier, with the former representing European-origin supply and the latter anchoring Chinese domestic rollout programs. Intel Corporation sits within the semiconductor substrate layer, supplying baseband processor designs for open RAN architectures adopted by tier-2 carriers seeking vendor diversification.
| Leading Market Players |
|---|
| AT&T |
| Capsule Technologies |
| Huawei Technologies |
| Intel Corporation |
| Samsung Electronics |
| Telefonaktiebolaget LM Ericsson |
| Verizon Communications Inc |
| Nokia Corporation |
| ZTE Corporation |
| Others |
Pricing and Supply Chain Analysis
Massive MIMO antenna array production at 64T64R scale concentrates among vendors with captive GaN foundry relationships, compressing cost curves for tier-1 carriers while elevating entry barriers for modular suppliers serving price-sensitive enterprise buyers. Scale economies in millimeter-wave RF front-end integration simultaneously determine supply availability and price floors across carrier direct procurement channels.
Pricing Analysis
Certification level (3GPP Release 16/O-RAN Alliance compliance) creates the primary spread between premium integrated systems and economy-tier modular configurations. Three-tier pricing structure across premium, standard, and economy levels reflects volume scale and after-sales service bundling, with enterprise campuses in Germany and South Korea showing highest price sensitivity due to private network budget constraints. Cost compression in standard-tier modems intensifies because Intel Corporation and Qualcomm are licensing baseband designs to Asian ODMs. Carrier procurement teams at China Mobile and Verizon demonstrate least price sensitivity, prioritizing interoperability guarantees over per-unit costs.
Supply Chain Analysis
Strategic stockpiling of GaN substrates and millimeter-wave RF components dominates inventory strategy among tier-1 equipment vendors anticipating FCC auction-driven demand surges. Supply concentrates in Taiwan for semiconductor foundry services, South Korea for memory and display integration, and China for passive component and PCB fabrication. Raw material dependencies encompass gallium nitride wafers, high-frequency laminates, and precision die-cast housings. Single-source vulnerability in GaN epitaxy equipment creates structural risk. Distribution runs through carrier direct procurement for modems and routers, while systems integrators channel antennas and repeaters to enterprise and government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G WIT120 market represents a high-growth disruption propelled by FCC spectrum auction deadlines compressing carrier replacement cycles from seven years to four. Open RAN interoperability mandates are simultaneously fragmenting incumbent supplier lock-in and creating entry pathways for modular specialists.
For Market Incumbents: Fortify massive MIMO antenna array capacity in the United States and China ahead of carrier densification waves. Deepen backward integration into GaN power amplifier production to offset foundry concentration risk in East Asia. Prioritize O-RAN Alliance certification investment to defend position against emerging open RAN challengers targeting tier-2 carrier procurement. For New Entrants and Emerging Players: Managed service gaps in private 5G network deployment present the most penetrable white-space, particularly for automotive manufacturing campuses in Germany and semiconductor fabs in South Korea. Target neutral host deployments under FCC CBRS priority access licensing in stadiums and convention centers where incumbent carriers under-serve. Lead with guaranteed latency SLA offerings rather than equipment-only sales to bypass capital budget friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors open RAN software specialists with proven fronthaul interoperability over legacy hardware-integrated conglomerates. Long-term viability hinges on 3GPP Release 17 and beyond standard-setting influence. Acquisition target archetype: mid-cap vendors with O-RAN Alliance contributor status and established tier-2 carrier relationships. Watch for FCC spectrum auction participation rates as inflection indicator for hardware procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Alliance Certification Investment | Unlocks tier-2 carrier procurement previously captured by Ericsson and Nokia legacy lock-in. |
| GaN Power Amplifier Backward Integration | Reduces dependency on Win Semiconductors and other concentrated East Asian foundry sources. |
| Private 5G Managed Service Launch | Captures recurring revenue from German automotive and South Korean semiconductor manufacturing verticals. |
| Millimeter-Wave Small Cell Capacity Expansion | Addresses FCC-driven densification requirements in New York and Los Angeles urban corridors. |
| Strategic Partnership with Systems Integrators | Penetrates government and enterprise antenna/repeater channels outside carrier direct procurement. |
Research Methodology
Desk research of 3GPP technical specifications, FCC equipment authorization filings, and MIIT domestic standard publications preceded structured interviews with carrier network engineering directors, O-RAN Alliance technical contributors, semiconductor procurement leads at equipment vendors, and municipal smart city program managers. Secondary validation drew from SEC 10-K infrastructure capex disclosures, customs trade data for RF component flows, and O-RAN Alliance open fronthaul specifications. Bottom-up terminal deployment estimates triangulated against top-down carrier spectrum investment projections.
Variance decomposition across technology generation transitions, regulatory auction timing, and open RAN adoption curves anchored the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product type, technology tier, end-user category, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression patterns and enterprise private network penetration trajectories. Forecast inputs incorporated GaN substrate supply constraints and FCC Part 27 equipment authorization timeline assumptions.
Forecasts assume regulatory continuity in FCC spectrum allocation, MIIT domestic procurement preferences, and EU CE marking frameworks; material policy shifts would require re-modeling. Revision becomes warranted when open RAN interoperability certification timelines or GaN foundry capacity expansion crosses thresholds that alter carrier equipment procurement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Mobile and Wireless Backhaul Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Multefire Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Femtocell Market
Wireless Technologies
USA Li-Fi Market