
 Li-Fi Market | 2026-2036
Li-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Li-Fi Market Analysis
A shortage of photonics engineers with dual expertise in optical physics and networking protocols is reorganizing how vendors build technical teams. Signify Holding leverages its legacy LED manufacturing infrastructure to control component costs for Li-Fi transmitter modules. pureLiFi Ltd. anchors its competitive position through sustained university partnerships that feed specialized talent into product development. Oledcomm competes by dominating patent filings in visible light positioning algorithms for indoor navigation systems.
Li-Fi denotes bidirectional wireless communication using modulated light waves, typically in the 380–750 nanometer visible spectrum or near-infrared bands, achieving data rates exceeding one gigabit per second under line-of-sight conditions. The technology serves environments where radio frequency interference must be eliminated, including aircraft cabins, hospital operating theaters, and petrochemical processing facilities. LED Transmitters currently occupy the largest share of component value as manufacturers integrate driver electronics directly into luminaire housings. Smart Lighting applications lead deployment volumes, though Military Communications segments sustain the highest margins due to electromagnetic-pulse resilience requirements and classified procurement protocols.
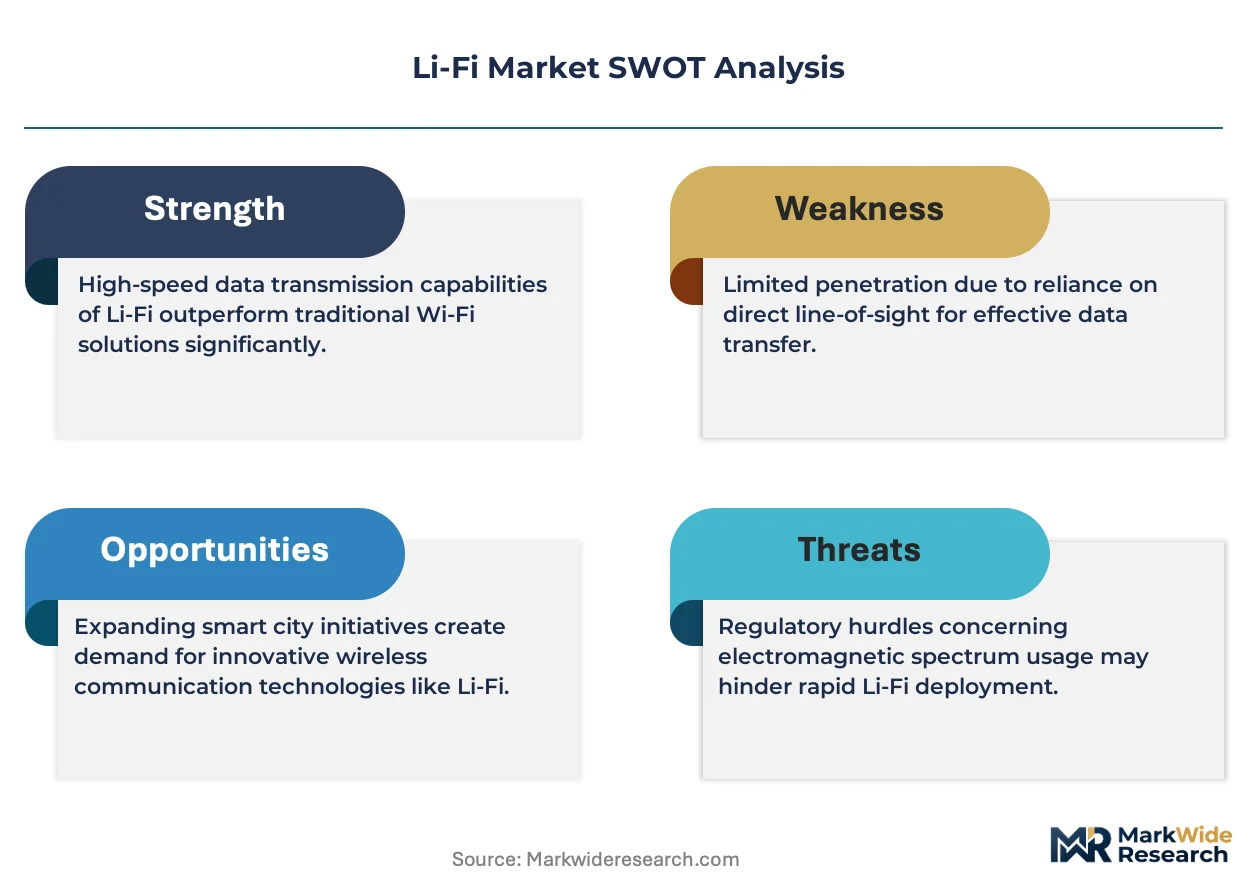
The FCC governs unlicensed optical emissions in the United States, while the EU AI Act and CE marking frameworks shape product compliance pathways for European vendors seeking cross-border market access. IEEE 802.11bb standardization is forcing interoperability investments across the supplier base, favoring firms with established protocol engineering benches. Stakeholders must monitor how spectrum allocation rulings in major economies affect the cost structure of dual-mode Wi-Fi-Li-Fi chipsets.
Market Dynamics
The IEEE 802.11bb standardization mandate is compressing vendor timelines and forcing interoperability investments across the Li-Fi supplier base, fundamentally restructuring how component manufacturers allocate R&D budgets.
Growth Catalysts
- Spectrum congestion in enterprise Wi-Fi:Dense office complexes in Germany and the United States are deploying Li-Fi to bypass saturated 2.4 GHz and 5 GHz bands. The FCC's unlicensed optical spectrum rulings accelerate pilot programs.
- REACH compliance for electromagnetic-sensitive manufacturing:Industrial automation clusters around Munich require zero-RF communication protocols for precision assembly lines. Li-Fi satisfies electromagnetic compatibility constraints that Wi-Fi cannot.
- LED transmitter cost curves:Legacy luminaire manufacturers are repurposing driver electronics infrastructure to produce integrated Li-Fi modules, collapsing per-unit transmitter costs below standalone radio chipsets.
Market Restraints
- Line-of-sight dependency:Physical obstruction sensitivity limits deployment to environments with controlled lighting geometry, excluding mobile outdoor applications and complex industrial layouts with moving equipment.
- Photonics engineer scarcity:Dual expertise in optical physics and IEEE 802.11 protocol stacks commands premium compensation, inflating product development costs for vendors without captive university pipelines.
- Wi-Fi 7 substitution threat:Multi-gigabit throughput improvements in unlicensed 6 GHz spectrum reduce the performance gap for latency-tolerant enterprise workloads, compressing Li-Fi's addressable niche.
Strategic Opportunities
- Visible light positioning for indoor navigation:Retail complexes and hospital campuses in France are piloting centimeter-accurate location services using existing LED infrastructure, creating incremental revenue streams from lighting hardware.
- EU AI Act compliance pathways:Optical wireless networks eliminate RF signature vulnerabilities that trigger AI system security audits, positioning Li-Fi as a preferred backbone for AI-enabled manufacturing.
- Aircraft cabin connectivity:FAA electromagnetic interference standards favor optical transmission for in-flight passenger services, opening a regulated vertical with long procurement cycles and high switching costs.
Industry Challenges
- Dual-mode chipset integration complexity:Wi-Fi-Li-Fi hybrid silicon requires simultaneous optimization for radio frequency and optical PHY layers, stretching validation timelines and qualification costs.
- CE marking fragmentation:Divergent national interpretations of optical emission safety limits across EU member states force redundant testing protocols, delaying cross-border product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li-Fi Market |
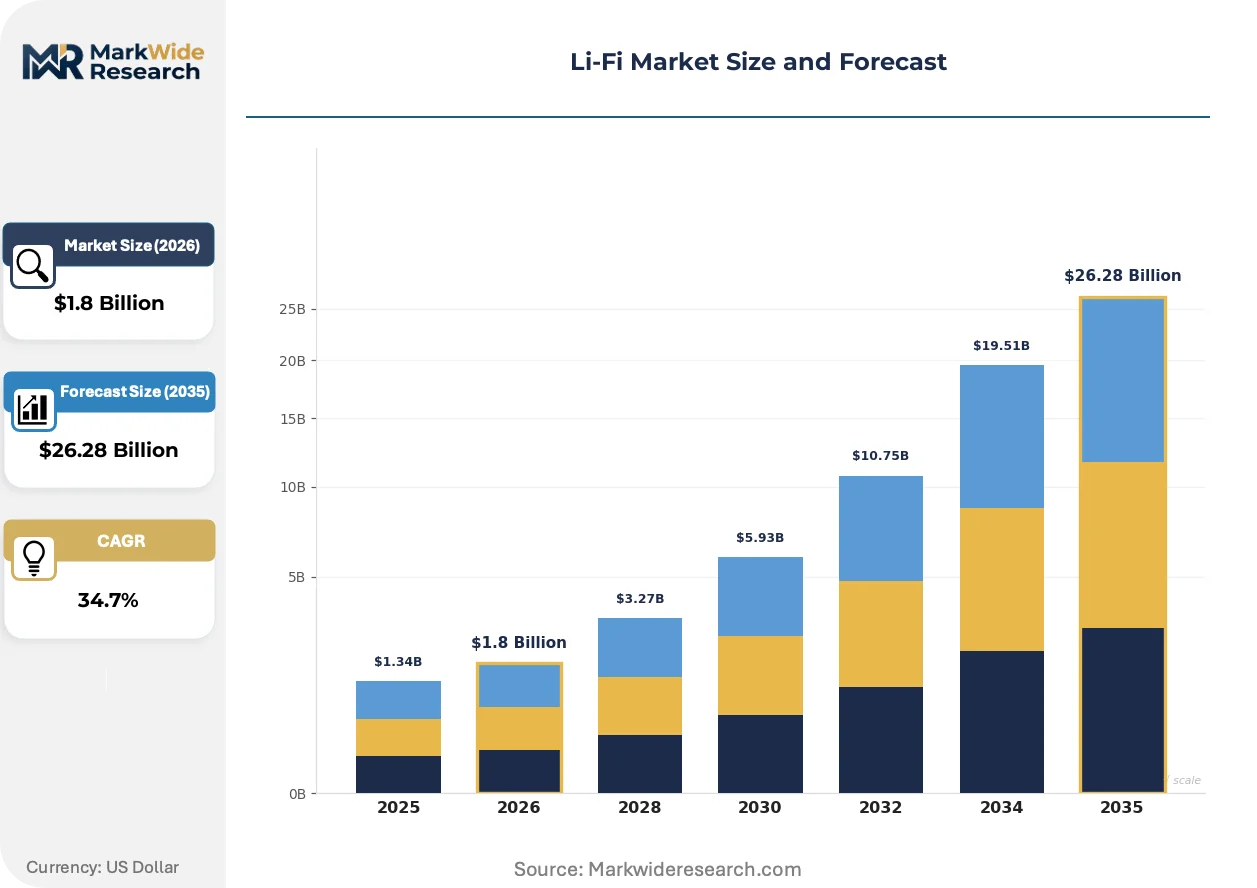
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Visible Light Communication, Optical Wireless Communication, RF Interference Management, Modulation Techniques Application: Smart Lighting, Indoor Navigation, Automotive Applications, Military Communications End User: Residential Users, Enterprises, Educational Institutions, Healthcare Facilities Component: LED Transmitters, Photodetectors, Li-Fi Routers, Optical Sensors |
| Companies Covered | Signify Holding, pureLiFi Ltd., Oledcomm, Acuity Brands, Inc., VLNComm Inc., Panasonic Corporation, Lucibel SA, LVX System Corp., Velmenni OÜ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li-Fi Market Emerging Trajectories
Standardization pressures and component miniaturization are converging to reshape how Li-Fi hardware penetrates price-sensitive enterprise segments, with interoperability emerging as the decisive competitive filter.
Micro-LED arrays is bifurcating the transmitter market between high-performance gallium nitride devices for military applications and cost-optimized silicon-backed emitters for commercial lighting retrofits. Defense procurement offices in the United States are specifying pulse-resilient optical links for command centers, while German automotive suppliers are integrating low-cost infrared transceivers into assembly line quality control systems. The technology is bifurcating vendor R&D roadmaps into divergent performance-versus-cost optimization paths that share no component suppliers.
The EU AI Act's risk classification framework is compelling industrial network architects to document electromagnetic attack surfaces in high-risk AI deployments. Vendors seeking CE marking for factory automation systems must now demonstrate optical isolation between AI inference engines and external networks. German machine builders are responding by specifying Li-Fi backbones for predictive maintenance systems that process sensitive operational data.
Hospital procurement committees are unbundling connectivity infrastructure from general IT capital budgets, creating dedicated funding streams for electromagnetic-compatible patient care environments. United Kingdom NHS trusts are establishing separate optical wireless procurement categories that bypass traditional Wi-Fi vendor relationships. This pattern is most visible in surgical suite renovations where anesthesia equipment and patient monitors require guaranteed interference-free operation.
Li-Fi Market Segmentation
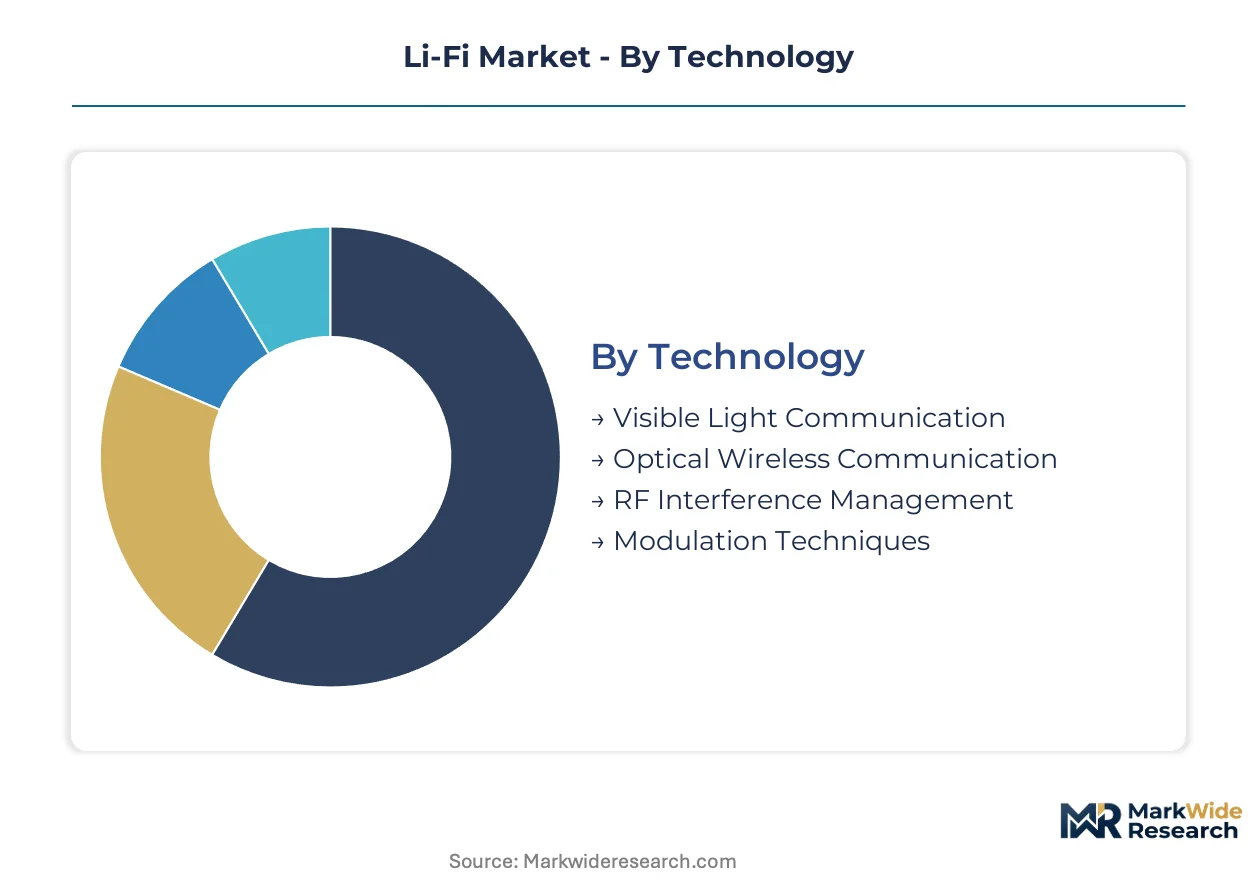
Li-Fi market segmentation reveals divergent margin structures across optical hardware, protocol layers, and deployment environments. Component manufacturers and application developers pursue fundamentally different commercial strategies based on where value concentrates in the stack.
Technology:
Visible Light Communication commands the deepest margin pools through proprietary modulation IP, while Optical Wireless Communication competes on spectral efficiency metrics.
- Visible Light Communication:Modulated LED arrays in the 380-750 nanometer spectrum deliver gigabit-class throughput under line-of-sight conditions. German automotive suppliers in Stuttgart are piloting VLC for electromagnetic-sensitive assembly line quality control, driven by REACH compliance mandates for zero-RF manufacturing zones.
- Optical Wireless Communication:Near-infrared transceivers extend Li-Fi into non-visible bands for covert military applications. United States defense procurement offices specify pulse-resilient optical links for command centers, prioritizing electromagnetic-pulse resilience over cost optimization.
- RF Interference Management:Hybrid architectures coordinate optical and radio frequency layers to eliminate spectrum congestion in dense enterprise deployments.
- Modulation Techniques:Orthogonal frequency-division multiplexing variants optimize spectral efficiency for high-data-rate video streaming in aircraft cabin environments.
Visible Light Communication holds installed capacity. Optical Wireless Communication is rotating up the share rankings.
Application:
Application segments stratify by procurement cycle length and certification burden, with defense and aviation sustaining premium pricing against commoditized lighting retrofits.
- Smart Lighting:Integrated luminaire designs embed Li-Fi drivers directly into LED housings, collapsing per-unit transmitter costs below standalone radio chipsets. United Kingdom NHS trusts are establishing separate optical wireless procurement categories for surgical suite renovations where anesthesia equipment demands guaranteed interference-free operation.
- Military Communications:Classified procurement protocols and electromagnetic-pulse resilience requirements sustain the highest margins across the application stack. United States defense specifications favor optical transmission for command center networks where RF signature elimination is mission-critical.
- Indoor Navigation:Visible light positioning algorithms deliver centimeter-accurate location services using existing LED infrastructure in French retail complexes.
- Automotive Applications:In-vehicle optical networks eliminate electromagnetic interference risks for advanced driver-assistance sensor fusion systems.
Military Communications maintains pricing power through sole-source procurement. Smart Lighting is expanding most quickly through lighting retrofit channels.
End User:
End user segments diverge by technical sophistication and integration complexity, with healthcare and enterprise buyers commanding dedicated implementation resources.
- Healthcare Facilities:Hospital procurement committees are unbundling connectivity infrastructure from general IT capital budgets, creating dedicated funding streams for electromagnetic-compatible patient care environments. United Kingdom surgical suites specify Li-Fi for guaranteed interference-free operation of anesthesia equipment and patient monitors.
- Enterprises:Dense office complexes in Germany and the United States deploy Li-Fi to bypass saturated 2.4 GHz and 5 GHz Wi-Fi bands, with FCC unlicensed optical spectrum rulings accelerating pilot programs.
- Educational Institutions:Campus networks in France are piloting visible light positioning for indoor navigation services in library and laboratory buildings.
- Residential Users:Consumer-grade Li-Fi remains limited by line-of-sight constraints and competing Wi-Fi 7 substitution in latency-tolerant home applications.
Healthcare Facilities concentrate premium deployment expertise. Enterprises are climbing the fastest in unit volume terms.
Component:
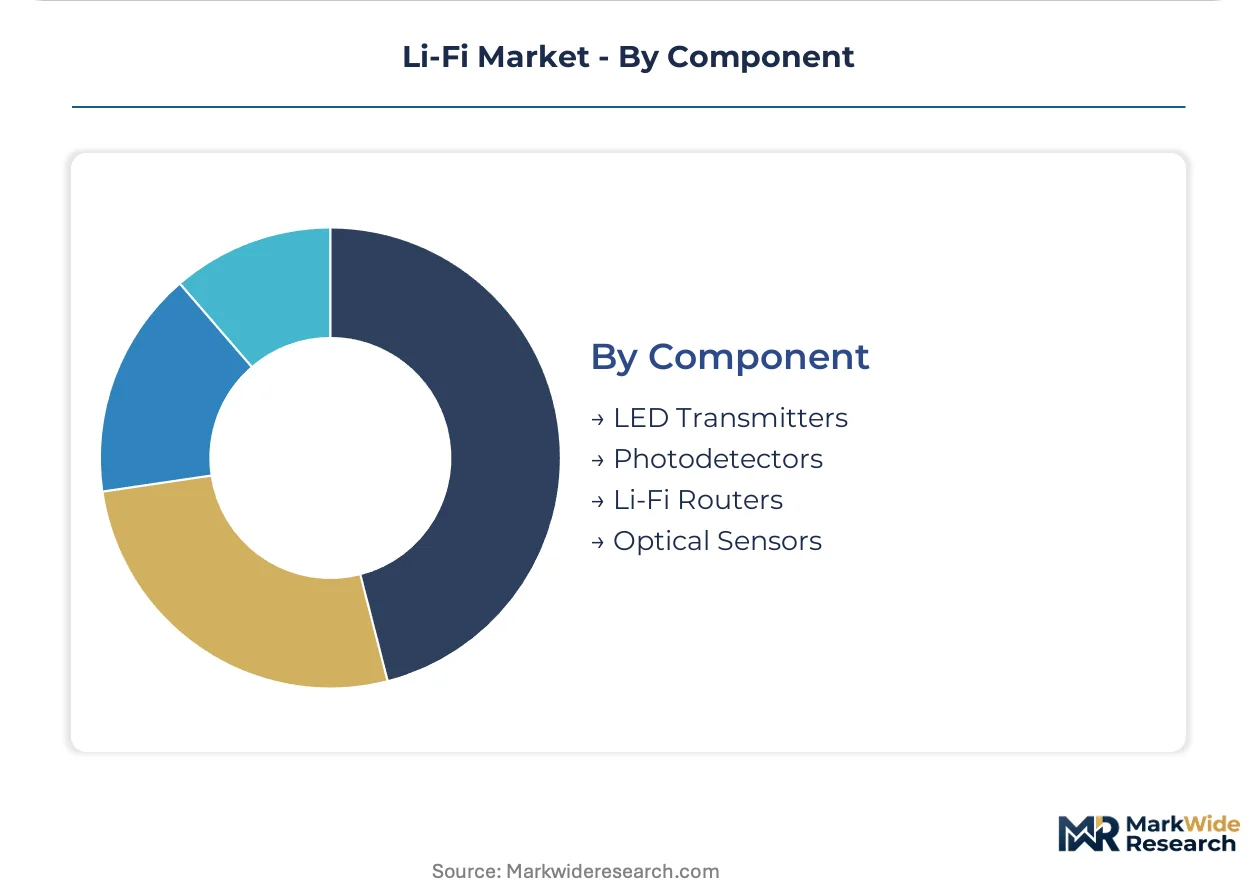
Component margins compress from transmitter modules through passive optical elements, with integrated driver electronics capturing value upstream of commoditized photodetectors.
- LED Transmitters:Legacy luminaire manufacturers repurpose driver electronics infrastructure to produce integrated Li-Fi modules, achieving cost structures competitive with radio chipsets. Signify Holding leverages captive LED manufacturing scale to control transmitter module pricing for enterprise deployments.
- Photodetectors:Silicon photodiode arrays convert modulated optical signals to electrical waveforms with nanosecond response times for gigabit-class reception.
- Li-Fi Routers:Dual-mode Wi-Fi-Li-Fi hybrid silicon requires simultaneous optimization for radio frequency and optical PHY layers, stretching validation timelines.
- Optical Sensors:Ambient light compensation circuits maintain link stability under varying illumination conditions in dynamic industrial environments.
LED Transmitters anchor supplier revenue. Li-Fi Routers face steepest expansion trajectory as IEEE 802.11bb standardization forces interoperability investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for industrial Li-Fi deployments while the United States competes on scale-driven enterprise rollouts, creating a transatlantic asymmetry in vendor margin structures.
United States
FCC unlicensed optical spectrum rulings accelerate enterprise pilot programs in dense office complexes. FAA electromagnetic interference standards favor optical transmission for aircraft cabin connectivity, opening regulated procurement channels. Defense procurement offices specify pulse-resilient optical links for command centers in the Washington DC corridor.
Germany
REACH compliance mandates for zero-RF manufacturing zones drive precision assembly line adoption in industrial automation clusters. KBA and federal economic ministries coordinate spectrum allocation for optical wireless experimentation. Munich and Stuttgart automotive suppliers pilot Li-Fi for machine-to-machine communication in electromagnetic-sensitive environments.
United Kingdom
Ofcom unlicensed spectrum openings enable hospital procurement committees to establish dedicated optical wireless categories. NHS trusts unbundle connectivity infrastructure from general IT capital budgets for surgical suite renovations. London and Manchester medical campuses specify Li-Fi for guaranteed interference-free operation of anesthesia equipment.
France
ANSM electromagnetic compatibility requirements position optical networks for high-risk AI manufacturing deployments. EU AI Act compliance pathways favor optical isolation between inference engines and external networks. Paris and Lyon retail complexes pilot centimeter-accurate visible light positioning for indoor navigation services.
Japan
METI industrial digitization programs incorporate optical wireless for electromagnetic-sensitive precision manufacturing. JIS standards frameworks shape component interoperability requirements for domestic vendors. Osaka and Nagoya electronics clusters evaluate Li-Fi for cleanroom environments where RF contamination risks quality control.
Li-Fi Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with legacy luminaire manufacturers leveraging captive LED infrastructure against pure-play innovators building protocol expertise. The supplier base stratifies into three tiers: integrated lighting conglomerates with manufacturing scale, specialized optical wireless ventures with IEEE 802.11bb engineering benches, and component suppliers repurposing driver electronics for Li-Fi module production. Dominant competitive moves include strategic partnerships with university photonics programs to secure talent pipelines, and geographic expansion into German industrial automation clusters where REACH compliance creates captive demand.
Among European-headquartered specialists, pureLiFi Ltd. and Oledcomm occupy positions within the protocol-innovation archetype, anchoring competitive dynamics around IEEE standardization investments. Signify Holding exemplifies the integrated manufacturing tier, leveraging legacy LED infrastructure to control transmitter module cost structures. These three entities represent the core strategic vectors—specialized optical engineering, university-talent pipelines, and captive component manufacturing—that define vendor positioning as interoperability mandates reshape procurement criteria.
| Leading Market Players |
|---|
| Signify Holding |
| pureLiFi Ltd. |
| Oledcomm |
| Acuity Brands, Inc. |
| VLNComm Inc. |
| Panasonic Corporation |
| Lucibel SA |
| LVX System Corp. |
| Velmenni OÜ |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day lead times for gallium nitride micro-LED arrays concentrate pricing power with legacy luminaire manufacturers who control captive LED fabrication infrastructure, while silicon-backed emitter alternatives compress margins for commercial lighting retrofit tiers. This inventory dynamic feeds directly into how vendors structure component sourcing and final assembly geography.
Pricing Analysis
German industrial automation deployments command thirty to forty percent premiums over United States enterprise rollouts due to REACH compliance certification requirements and electromagnetic-sensitivity validation protocols. The dominant pricing structure stratifies across premium-military, standard-industrial, and economy-commercial lighting tiers, with price differentiation resting on IEEE 802.11bb certification status and volume scale commitments. Cost compression in the economy tier is intensifying because Wi-Fi 7 substitution narrows the performance gap for latency-tolerant workloads. Healthcare facilities demonstrate lowest price sensitivity due to dedicated capital budget unbundling, while residential users face highest sensitivity competing against commoditized Wi-Fi infrastructure.
Supply Chain Analysis
China and Taiwan anchor LED transmitter wafer fabrication, while Germany and the United States concentrate precision photodetector assembly and protocol layer integration. Raw material dependencies draw from rare-earth phosphor substrates, silicon carbide substrates for high-frequency drivers, and specialized optical-grade polymers for lens housings. Single-source vulnerability concentrates in gallium nitride epitaxy equipment where two equipment vendors service the entire photonics industry. Distribution runs through direct OEM partnerships for military and aviation verticals, with lighting retrofit channels serving commercial segments through electrical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and United Kingdom NHS trusts who unbundle connectivity procurement from incumbent Wi-Fi vendor relationships, fragmenting traditional single-source network infrastructure decisions.
For Market Incumbents: Compound IEEE 802.11bb protocol expertise through captive university photonics pipelines to defend against Wi-Fi 7 substitution threats in enterprise segments. Deepen backward integration into gallium nitride micro-LED fabrication to control transmitter cost structures and resist margin compression from silicon-backed emitter alternatives. Prioritize certification investment for EU AI Act compliance pathways that optical-only networks satisfy. For New Entrants and Emerging Players: Anchor in French retail visible light positioning pilots and Japanese cleanroom manufacturing evaluations where incumbent lighting relationships remain underdeveloped. The most penetrable segment sits in hospital surgical suite renovations where electromagnetic compatibility requirements bypass traditional Wi-Fi procurement channels. A direct go-to-market angle targets biomedical engineering committees with guaranteed interference-free operation documentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dual-mode Wi-Fi-Li-Fi chipset development as IEEE standardization forces simultaneous RF and optical PHY layer optimization. Long-term viability over the next decade rests on protocol engineering bench depth rather than manufacturing scale. Acquisition target archetypes include specialized optical wireless ventures with university talent pipelines. The signal to monitor is FCC and Ofcom spectrum allocation rulings affecting dual-mode chipset cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| IEEE 802.11bb Certification Investment | Interoperability mandates from the FCC and Ofcom reshape procurement criteria across enterprise buyers. |
| University Photonics Partnership | Dual expertise in optical physics and networking protocols commands premium compensation, feeding specialized talent pipelines. |
| Backward Integration into LED Fabrication | Legacy luminaire infrastructure repurposing collapses per-unit transmitter costs below standalone radio chipsets. |
| EU AI Act Compliance Pathway | Optical isolation between AI inference engines and external networks satisfies risk classification documentation requirements. |
| Visible Light Positioning Launch | French retail complexes and United Kingdom hospital campuses pilot centimeter-accurate navigation using existing LED infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with photonics engineering directors, hospital procurement committee members, industrial automation plant managers, and LED luminaire product strategists. Secondary validation drew from FCC unlicensed spectrum rulings, IEEE 802.11bb standardization documents, Ofcom optical wireless consultation papers, and SEC filings from publicly traded lighting conglomerates. Bottom-up component cost modeling and top-down addressable market sizing were triangulated against deployment volume estimates from German automotive clusters and United Kingdom NHS trust capital expenditure disclosures.
Across the analysis window, the forecasting framework modeled technology segmentation by modulation technique and spectral band, application segmentation by procurement cycle length and certification burden, and component segmentation by integration complexity and margin capture position. CAGRs were derived from installed base growth trajectories in electromagnetic-sensitive manufacturing environments and aircraft cabin connectivity procurement pipelines. Industry-specific inputs included REACH compliance mandate expansion timelines and Wi-Fi 7 throughput improvement roadmaps from semiconductor vendors.
Underlying assumptions cover sustained FCC and Ofcom unlicensed spectrum availability, stable gallium nitride substrate supply, and continued German industrial automation cluster expansion, with deviation risk concentrated in Wi-Fi 7 performance improvements compressing Li-Fi's addressable niche and photonics engineer scarcity inflating product development timelines. Recalibration cycles align with material shifts in IEEE standardization implementation schedules and major economy spectrum allocation rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Wigig Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Cellular Repeater Market