
 5G Wireless Equipment Market | 2026-2036
5G Wireless Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
5G Wireless Equipment Market Insights
Software-defined network management is repositioning vendor value capture away from hardware-only sales toward recurring platform revenue. Ericsson leverages its cloud-native portfolio to anchor European operator upgrades. Nokia Corporation competes through specialized silicon-to-software integration for energy-efficient base stations. Samsung Electronics dominates mmWave antenna shipments in North American carrier buildouts.
5G wireless equipment comprises radio access network infrastructure operating across sub-6 GHz and millimeter-wave spectrum bands, with massive MIMO arrays supporting 64T64R configurations and beamforming algorithms that dynamically steer signals toward user equipment. Base stations and small cells constitute the dominant hardware investment pool, while network slicing and cloud RAN represent the fastest-expanding technology segments as operators virtualize core functions to reduce latency and improve spectral efficiency.
The Federal Communications Commission in the United States, the Ministry of Industry and Information Technology in China, and the European Electronic Communications Code collectively shape equipment demand through spectrum auction design, cybersecurity certification requirements, and infrastructure deployment mandates. The EU AI Act and GDPR impose data governance standards on edge computing nodes integrated with 5G access points. Stakeholders must monitor how national security screening regimes for foreign telecom equipment reshape supplier eligibility and procurement timelines.
Market Dynamics
Open RAN disaggregation is fragmenting vendor lock-in patterns across telecom procurement, forcing incumbents to defend installed base through software subscription models while new entrants capture radio unit contracts.
Growth Catalysts
- Enterprise IoT densification:Manufacturing campuses and logistics hubs in Germany, Japan, and South Korea are deploying private 5G networks to replace Wi-Fi for latency-critical automation.
- FCC spectrum reallocation:The Federal Communications Commission's 3.45 GHz and 2.5 GHz auction releases are accelerating mid-band buildout timelines across rural and suburban United States markets.
- Massive MIMO beamforming:64T64R antenna configurations are expanding spectral efficiency, enabling carriers to serve higher subscriber density per cell site without additional spectrum acquisition.
Market Restraints
- GaN-on-SiC substrate concentration:Gallium nitride power amplifier supply chains cluster among specialized foundries in Taiwan and Japan, creating single-source vulnerability for mmWave radio units.
- EU cybersecurity certification friction:The European Cybersecurity Act's Common Criteria evaluation timelines extend base station approval cycles by 8-14 months, delaying operator deployment schedules.
- Legacy 4G infrastructure sunk costs:Carriers with extensive LTE-M investments face stranded asset risk when accelerating 5G standalone core migration.
Strategic Opportunities
- India manufacturing incentives:The Production Linked Incentive scheme for telecom equipment is attracting radio assembly capacity to Gujarat and Tamil Nadu for export to Southeast Asian operators.
- Network slicing for healthcare:Ultra-reliable low-latency communication slices are enabling remote surgical robotics in university hospital systems across France and Switzerland.
- Cloud RAN edge convergence:Containerized baseband function deployment is collapsing the boundary between radio access and multi-access edge computing infrastructure.
Industry Challenges
- vRAN software integration complexity:Disaggregated protocol stack components from multiple vendors create interoperability failures during multi-vendor field trials.
- mmWave propagation engineering talent scarcity:Beam management algorithm development requires specialized expertise in computational electromagnetics that outstrips graduate program output.
- Supply chain reconfiguration costs:National security screening regimes in Australia, Canada, and the United Kingdom are forcing radio unit redesigns to exclude restricted component origins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Wireless Equipment Market |
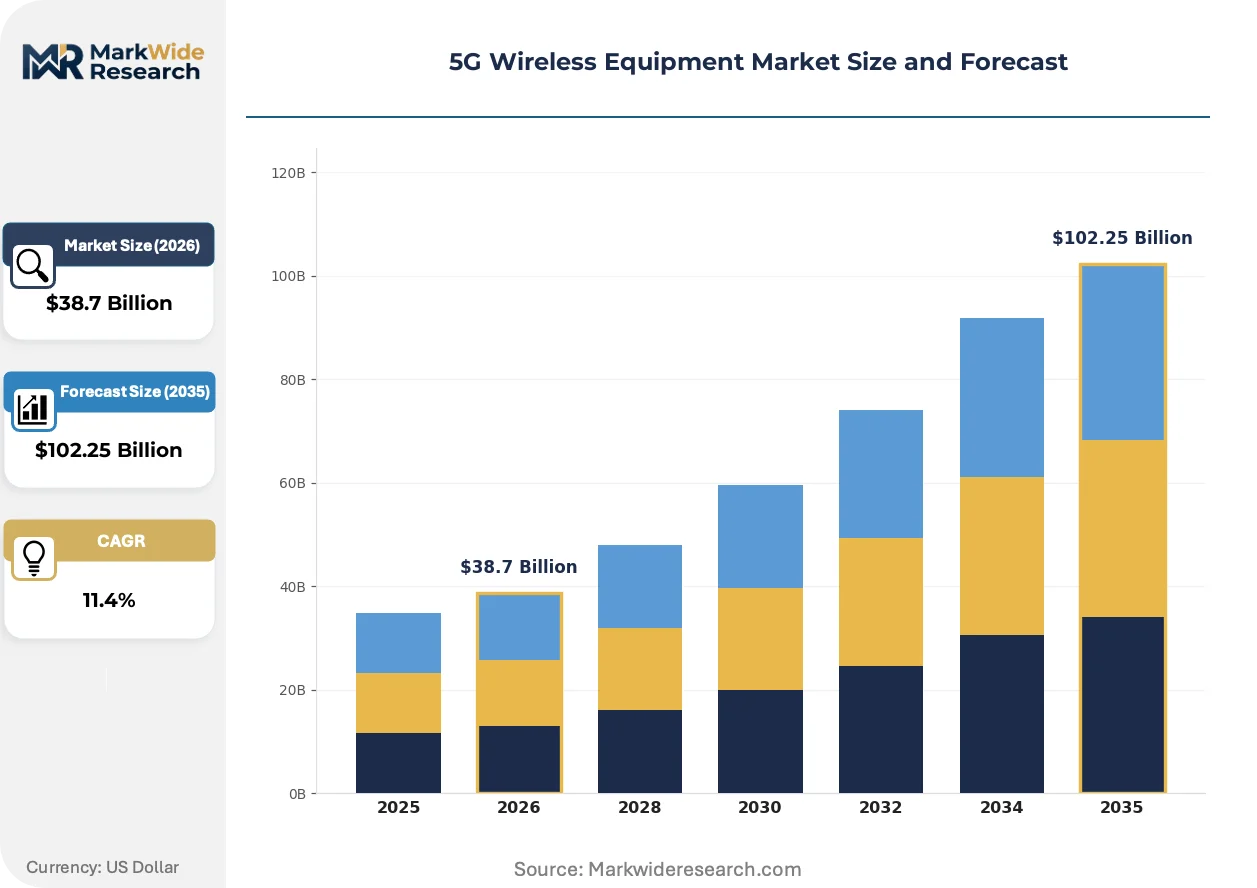
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Stations, Antennas, Small Cells, Repeaters Technology: Massive MIMO, Beamforming, Network Slicing, Cloud RAN End User: Telecom Operators, Enterprises, Government, Automotive Deployment Model: On-Premise, Cloud, Hybrid, Edge |
| Companies Covered | Huawei Technologies Co., Ltd., Ericsson, Nokia Corporation, Samsung Electronics, ZTE Corporation, Qualcomm Technologies, Cisco Systems, NEC Corporation, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Wireless Equipment Market Trends and Innovations
Virtualization of radio access network functions is collapsing the traditional hardware-software boundary, enabling operators to deploy capacity through software licenses rather than physical site visits. This shift is compressing upgrade cycles and redistributing value capture toward cloud-native platform vendors.
Massive MIMO antenna arrays are modularizing into active antenna units with pluggable radio heads, allowing operators to upgrade spectral capacity without crane-lifting entire tower installations. European and North American carriers are adopting this architecture for suburban macro sites where permitting delays constrain physical expansion. The approach is modularizing capital deployment into incremental software-defined capacity steps rather than monolithic hardware replacement cycles.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on beam management systems that use machine learning for user equipment tracking. Base station vendors must now document training data provenance and decision logic for regulatory audit. This compliance burden is concentrating procurement among vendors with established European AI governance infrastructure, disadvantaging newer market entrants.
Buying patterns among tier-one carriers are consolidating radio unit contracts into multi-year framework agreements with price-volume bands indexed to semiconductor input costs. This mechanism transfers silicon wafer volatility risk from operators to equipment vendors. The structure is most prevalent in United States and Japanese procurement, where carrier balance sheet pressures favor predictable opex profiles over lumpy capex commitments.
5G Wireless Equipment Market Segmentation
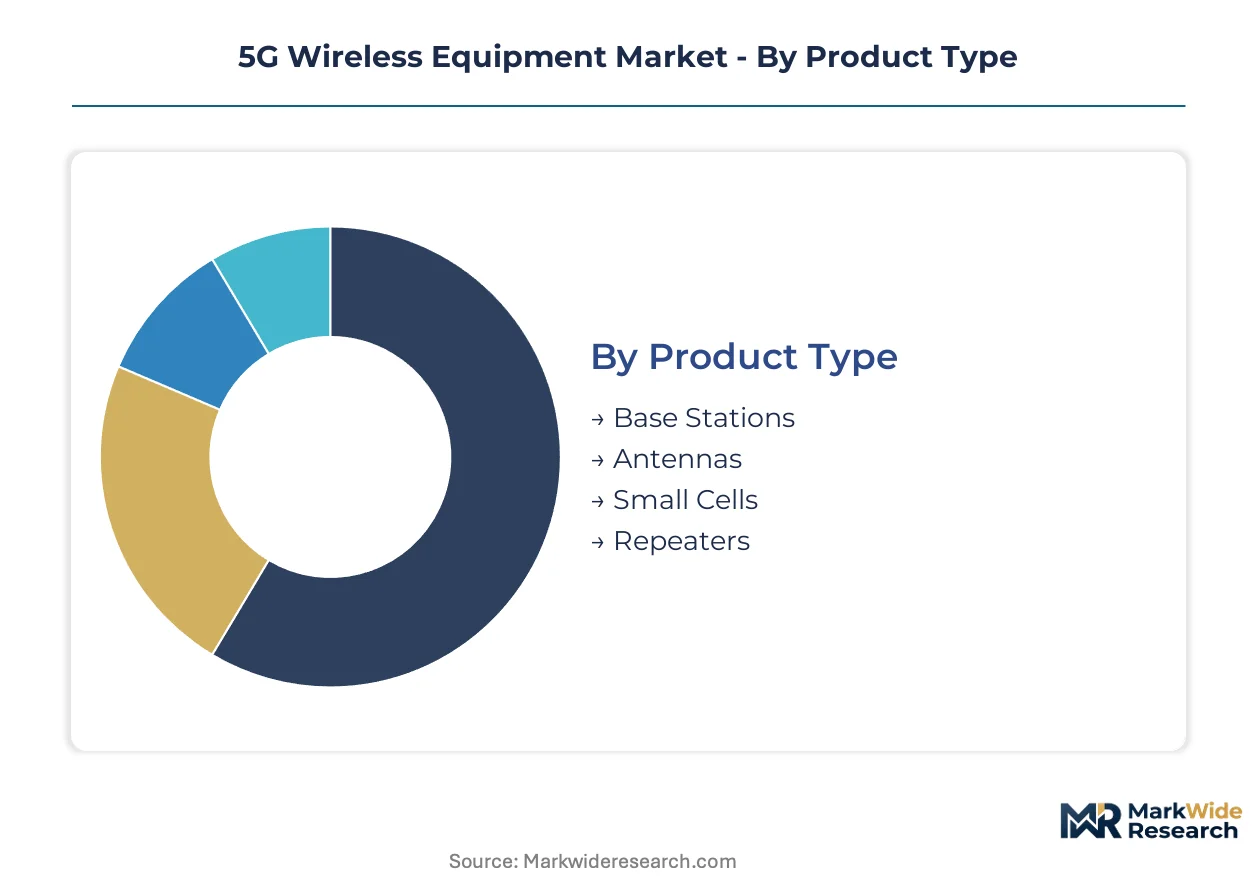
Equipment segmentation in 5G wireless infrastructure reveals divergent capital deployment profiles across hardware, software, and service layers. Procurement patterns vary sharply between macro network buildouts requiring tower-mounted assets and enterprise private deployments favoring modular, software-defined capacity.
Product Type:
Capital intensity clusters heaviest in tower-mounted macro infrastructure, while distributed assets spread investment across denser geographic footprints.
- Base Stations:Macro cell towers integrate radio units, baseband processing, and power systems into weather-hardened enclosures requiring crane installation and fiber backhaul. United States carriers concentrate procurement here for suburban coverage expansion, driven by FCC mid-band auction deadlines and rural connectivity mandates.
- Antennas:Active antenna units with integrated radio heads now dominate new deployments, enabling 64T64R massive MIMO configurations without full tower reconstruction. German operators prioritize these for urban capacity upgrades where permitting constraints block new site acquisition.
- Small Cells:Street-level micro base stations address indoor coverage gaps and dense urban hotspots with lower per-unit capex but higher site acquisition complexity.
- Repeaters:Signal amplification devices extend coverage into tunnels, stadiums, and remote industrial facilities without dedicated spectrum licensing.
Base stations absorb the bulk of installed capacity; small cells are expanding most quickly.
Technology:
Technology selection tracks operator virtualization maturity and spectrum portfolio composition rather than uniform upgrade cycles.
- Massive MIMO:64T64R antenna arrays with beamforming processors multiply spectral efficiency through spatial multiplexing, requiring specialized GaN power amplifiers and digital beamforming ASICs. Chinese operators deploy these at scale for sub-6 GHz capacity multiplication.
- Beamforming:Dynamic signal steering algorithms concentrate radiated energy toward user equipment, improving edge-of-cell throughput and reducing interference. South Korean carriers leverage this for mmWave fixed wireless access in dense apartment districts.
- Network Slicing:Virtualized core partitioning enables quality-of-service guarantees for enterprise IoT and critical communications use cases.
- Cloud RAN:Disaggregated baseband function virtualization collapses hardware boundaries between radio access and edge computing infrastructure.
Massive MIMO dominates current deployment volume; network slicing is climbing the fastest as enterprise service revenue models mature.
End User:
Customer type determines procurement scale, technical specification priority, and contract structure complexity.
- Telecom Operators:Tier-one mobile network operators procure through multi-year framework agreements with volume-indexed pricing, favoring integrated vendor ecosystems for macro network consistency. Japanese carriers emphasize energy efficiency metrics in base station selection due to grid constraints.
- Enterprises:Manufacturing and logistics campuses in Germany and South Korea deploy private 5G networks with localized spectrum licenses, prioritizing latency guarantees over wide-area mobility.
- Government:Defense and public safety agencies require hardened equipment with domestic supply chain verification and encryption certification.
- Automotive:Vehicle-to-everything communication modules demand ultra-reliable low-latency performance for collision avoidance and traffic coordination.
Telecom operators command the largest installed base; enterprises are gaining share fastest as private network licensing frameworks proliferate.
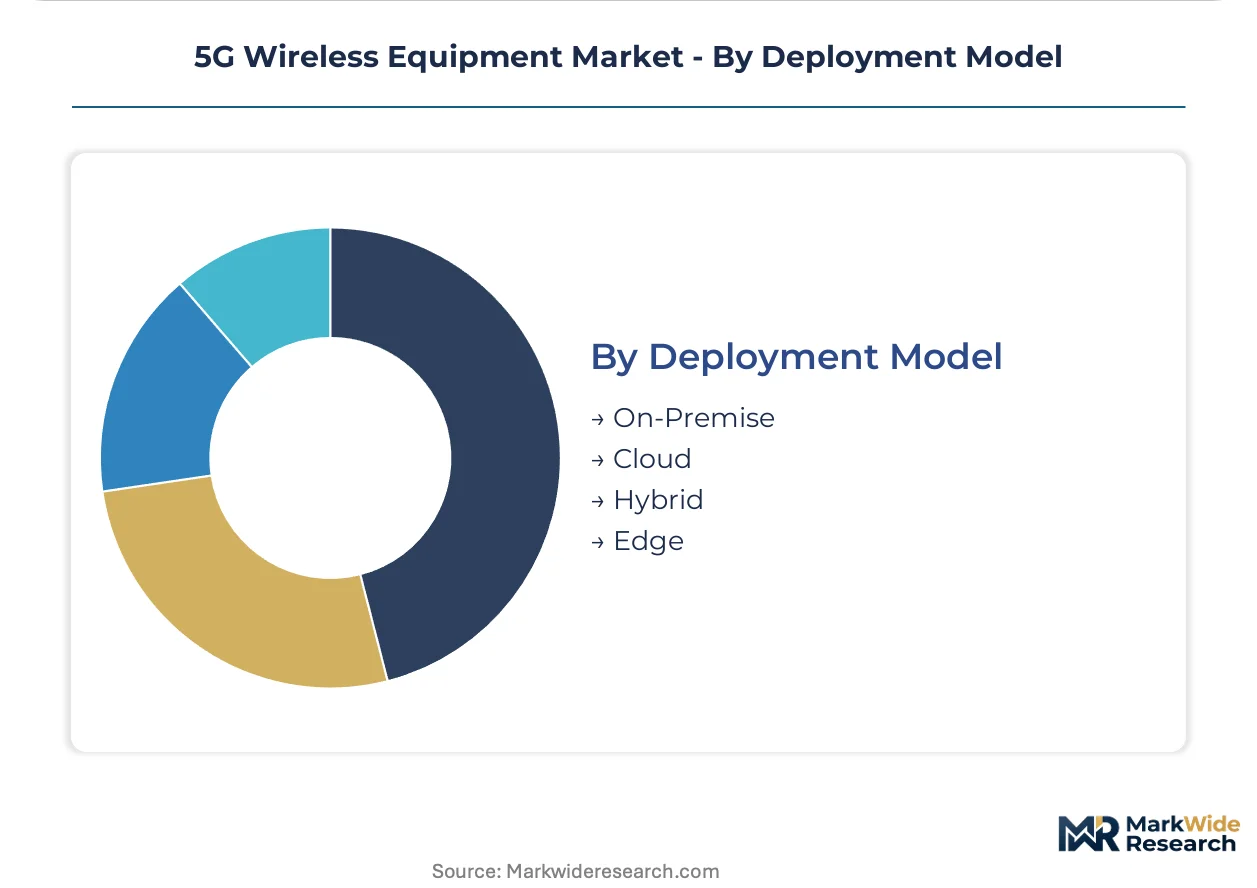
Deployment Model:
Infrastructure location and ownership structure reshape vendor value capture between hardware sales and recurring platform revenue.
- On-Premise:Dedicated hardware installations at carrier-owned facilities retain full operational control but require substantial upfront capital commitment and specialized maintenance staffing.
- Cloud:Centralized baseband processing in hyperscale data centers enables dynamic capacity scaling through software licensing, with Indian operators adopting this model aggressively to reduce tower-site real estate costs.
- Hybrid:Split architectures combine centralized processing for non-latency-critical functions with distributed radio units for coverage.
- Edge:Multi-access edge computing nodes collocated with radio access points collapse latency for industrial automation and immersive media applications.
On-premise deployments retain the majority of legacy investment; edge infrastructure is expanding most rapidly as latency requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in East Asian manufacturing clusters, while consumption patterns diverge across North American, European, and Asia-Pacific carrier deployment schedules. The FCC, MIIT, and European Electronic Communications Code collectively shape procurement timelines through spectrum auction design and cybersecurity certification mandates. National security screening regimes in multiple jurisdictions are forcing supply chain reconfigurations that alter traditional vendor eligibility.
United States
Verizon, AT&T, and T-Mobile are accelerating mid-band buildouts following the FCC's 3.45 GHz and 2.5 GHz auction releases. The FCC's supply chain security rules restrict certain foreign-origin equipment from federally funded rural broadband projects. Tower construction crews in Texas and the Southeast are installing massive MIMO arrays at suburban macro sites to meet coverage deadlines.
China
China Mobile, China Telecom, and China Unicom are deploying sub-6 GHz massive MIMO at scale across tier-one and tier-two cities. The Ministry of Industry and Information Technology coordinates spectrum allocation and domestic equipment procurement priorities. Shenzhen and Beijing host concentrated R&D facilities for active antenna unit and baseband processor development.
Germany
Deutsche Telekom, Vodafone Germany, and Telefónica Deutschland are prioritizing urban capacity upgrades where permitting constraints block new site acquisition. The European Cybersecurity Act's Common Criteria evaluation timelines extend base station approval cycles. Industrial manufacturers in Bavaria and Baden-Württemberg are deploying private 5G networks for factory automation.
South Korea
SK Telecom, KT, and LG Uplus leverage mmWave beamforming for fixed wireless access in dense Seoul apartment districts. The Korea Communications Commission manages spectrum licensing frameworks for both public networks and enterprise private deployments. Busan-Ulsan manufacturing corridors are integrating 5G-enabled robotics into shipbuilding and automotive production lines.
India
Reliance Jio and Bharti Airtel are expanding 4G-to-5G migration timelines while evaluating cloud RAN architectures to reduce tower-site real estate costs. The TRAI Production Linked Incentive scheme for telecom equipment is attracting radio assembly capacity to Gujarat and Tamil Nadu. Chennai and Ahmedabad facilities are scaling export-oriented manufacturing for Southeast Asian operators.
5G Wireless Equipment Market Competitive Landscape
Top-tier vendors anchor integrated system supply, while specialized radio unit fabricators and cloud-native software providers occupy adjacent tiers. Market structure reflects consolidation around full-stack incumbents with established carrier relationships, plus fragmentation among Open RAN disaggregation specialists. Three archetypes dominate: vertically integrated infrastructure conglomerates, semiconductor-to-software integrators, and pure-play virtualization vendors. Competitive positioning hinges on multi-year framework agreements with price-volume bands, plus geographic diversification to navigate national security screening regimes.
Within the integrated infrastructure tier, Huawei Technologies Co., Ltd., Ericsson, and Nokia Corporation exemplify contrasting geographic exposure strategies. Huawei Technologies Co., Ltd. anchors its position through captive silicon and software ecosystems despite restricted market access in certain jurisdictions. Ericsson leverages its European headquarters to capture operator upgrade cycles across Germany, France, and the Nordic region. Nokia Corporation competes through specialized energy-efficient base station portfolios that address Japanese carrier grid constraints and European sustainability mandates.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ericsson |
| Nokia Corporation |
| Samsung Electronics |
| ZTE Corporation |
| Qualcomm Technologies |
| Cisco Systems |
| NEC Corporation |
| Fujitsu |
| Others |
Pricing and Supply Chain Analysis
Carrier procurement consolidation into multi-year framework agreements with semiconductor-indexed pricing is forcing equipment vendors to absorb silicon wafer volatility and compress hardware margins. This demand-side restructuring concentrates pricing power among tier-one operators while fragmenting supplier profit pools across software subscription and radio unit contract tiers.
Pricing Analysis
Cost-down pressure on radio access hardware accelerates because tier-one carriers in the United States and Japan are converting capital expenditure into operational expenditure through software licensing models. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native platform vendors from integrated hardware incumbents and Open RAN radio specialists. Price differentiation hinges on energy efficiency certification tiers and after-sales service bundling. Telecom operators exhibit highest price sensitivity in macro base station procurement, while government and defense buyers prioritize supply chain verification over unit cost.
Supply Chain Analysis
GaN-on-SiC power amplifier supply rests on specialized foundries in Taiwan and Japan, with advanced packaging capacity concentrated in South Korea. Critical inputs include gallium nitride wafers, silicon carbide substrates, and millimeter-wave beamforming ASICs. Single-source vulnerability in compound semiconductor fabrication creates exposure to geopolitical restriction and export control disruption. Distribution runs through direct carrier framework agreements with original equipment manufacturers, bypassing traditional telecom distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN disaggregation and national security screening regimes are consolidating vendor eligibility, forcing capital-constrained specialists toward acquisition or exit. Surviving players must secure multi-year operator commitments before procurement frameworks harden.
For Market Incumbents: Anchor cloud-native platform revenue through software subscription models that offset hardware margin compression from semiconductor-indexed contracts. Deepen silicon-to-software integration in energy-efficient baseband processing to defend against emerging Open RAN radio specialists. Prioritize European AI Act compliance infrastructure to maintain procurement eligibility as algorithmic transparency mandates tighten. For New Entrants and Emerging Players: Containerized baseband virtualization offers the most penetrable wedge for specialist software vendors seeking carrier adoption outside incumbent ecosystems. Target Indian manufacturing incentives for radio assembly capacity serving Southeast Asian export demand. Pursue private 5G network deployments in German industrial corridors where latency requirements exceed public network capabilities. For Investors and Strategic Acquirers: The window for entry favors semiconductor-to-software integrators with captive GaN amplifier supply and established European cybersecurity certification. Long-term viability centers on vendors capable of spanning Open RAN radio units and cloud RAN orchestration platforms. Watch for FCC supply chain security rule expansions that further restrict foreign-origin equipment eligibility as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | Common Criteria evaluation under the European Cybersecurity Act accelerates base station approval timelines for compliant vendors. |
| GaN-on-SiC Backward Integration | Captive compound semiconductor fabrication reduces single-source dependency for mmWave radio unit production. |
| Cloud RAN Platform Launch | Containerized baseband deployment collapses latency boundaries between radio access and multi-access edge computing infrastructure. |
| Private 5G Network Partnership | Localized spectrum licensing in German manufacturing campuses replaces Wi-Fi for latency-critical industrial automation. |
| Multi-Year Framework Agreement | Price-volume bands indexed to semiconductor input costs transfer silicon wafer volatility risk from carriers to equipment vendors. |
Research Methodology
Independent corroboration across network equipment procurement executives, semiconductor supply chain managers, and regulatory affairs specialists at tier-one carriers underwrites the qualitative findings. Primary fieldwork encompassed interviews with Open RAN software architects, base station manufacturing engineers, and spectrum policy officers at national regulators including the FCC, MIIT, and European Electronic Communications Code implementing bodies. Secondary validation drew from SEC filings of listed equipment vendors, FCC auction and supply chain security rulemaking dockets, and customs trade data for radio unit component flows. Bottom-up triangulation across operator capex disclosures and top-down reconciliation against national 5G deployment targets anchored volume estimates.
Rate-of-change decomposition across the analysis window segmented growth drivers by product type, technology maturity, deployment model, and end-user procurement structure. The analytical framework modeled base station, antenna, small cell, and repeater segments separately, with cross-elasticity parameters capturing substitution between macro and densification investments. Cloud RAN and network slicing adoption curves incorporated hyperscaler edge computing capex trajectories and enterprise IoT service revenue maturation. CAGRs derived from equipment shipment volumes, average selling price erosion curves, and software attach rate progression across the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen spectrum reallocation decisions, abrupt export control expansions affecting compound semiconductor supply, and accelerated 6G research timelines that could compress 5G equipment replacement cycles. Forecasts reflect documented assumptions regarding carrier migration schedules and regulatory certification timelines. A small set of named triggers warrants ongoing watch: FCC supply chain security rule enforcement intensity, EU AI Act beam management algorithm audit implementation, and Taiwan-Japan GaN foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Fixed LTE Wireless Broadband Market