
 Freezers Market | 2026-2036
Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Freezers Market Analysis
Remote temperature monitoring subscriptions is repositioning freezer value propositions from hardware sales to outcome-based cold chain assurance. Thermo Fisher Scientific leverages its life sciences instrumentation heritage to dominate biopharmaceutical cold storage specifications. Haier Group anchors its position through manufacturing scale across Asia-Pacific production hubs. Samsung Electronics differentiates via smart appliance ecosystems that integrate freezer units with broader kitchen automation platforms.
Freezers are thermally insulated cabinets or chambers engineered to maintain temperatures at or below zero degrees Celsius, typically using vapor-compression refrigeration cycles with polyurethane foam insulation and refrigerants governed by global warming potential classifications, designed to preserve perishable goods, biological specimens, and temperature-sensitive pharmaceuticals against spoilage or degradation. Commercial freezers occupy the largest installed base due to foodservice and retail refrigeration mandates, though smart technology variants are expanding fastest as IoT-enabled predictive maintenance reduces downtime costs for fleet operators. Chest freezers sustain margin pools in emerging household segments where first-time appliance ownership intersects with frozen food retail expansion.
The EPA enforces refrigerant phase-down schedules under AIM Act authority, compelling manufacturers to redesign compressor systems for hydrofluoroolefin blends or natural refrigerants. Ecodesign requirements under EU F-Gas Regulation and CE marking directives establish minimum efficiency thresholds that filter lower-tier imports from European distribution channels. China's GB standards and NMPA cold chain guidelines for vaccine storage impose additional compliance layers on export-bound production. Stakeholders must monitor refrigerant chemistry transitions, energy label tightening trajectories, and regional cold chain infrastructure buildouts to align product roadmaps with diverging regulatory calendars.
Market Dynamics
Refrigerant chemistry transitions under the EU F-Gas Regulation and EPA AIM Act are forcing compressor redesign cycles, compressing product development timelines while opening specification windows for natural refrigerant architectures.
Growth Catalysts
- Cold chain logistics fleet expansion:Pharmaceutical distributors are scaling refrigerated transport capacity to meet vaccine and biologics distribution mandates, pulling demand for ultra-low temperature storage infrastructure.
- EU F-Gas Regulation phase-down:The regulatory schedule for hydrofluorocarbon reduction is accelerating retrofit demand across European commercial foodservice and retail installations.
- Southeast Asian food processing corridors:Vietnam and Thailand are concentrating frozen seafood and prepared food production, driving walk-in freezer installations for export-oriented cold storage.
Market Restraints
- Copper and steel input volatility:Compressor housings and coil assemblies face raw material price swings that compress margin pools for mid-tier manufacturers.
- Refrigerant supply concentration:Hydrofluoroolefin blend production clusters in Chinese chemical manufacturing zones, creating single-source dependency risks for Western OEMs.
- Natural refrigerant safety codes:Ammonia and carbon dioxide systems trigger stricter building code requirements that extend permitting timelines in urban commercial zones.
Strategic Opportunities
- Remote temperature monitoring convergence:IoT sensor networks and cloud analytics platforms are expanding into subscription-based cold chain assurance models that decouple revenue from unit sales.
- India's PLI scheme for white goods:Production-linked incentive structures are attracting component localization investments that reduce landed costs for domestic freezer assembly.
- Biopharmaceutical specimen banking:Cell therapy and precision medicine workflows are creating demand for cryogenic storage systems with chain-of-custody documentation.
Industry Challenges
- Refrigerant technician certification gaps:Hydrofluoroolefin and natural refrigerant handling protocols require retraining field service networks that were scaled for legacy chemistries.
- Legacy control system integration:Smart freezer fleets must interface with existing building management systems that lack standardized API architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezers Market |
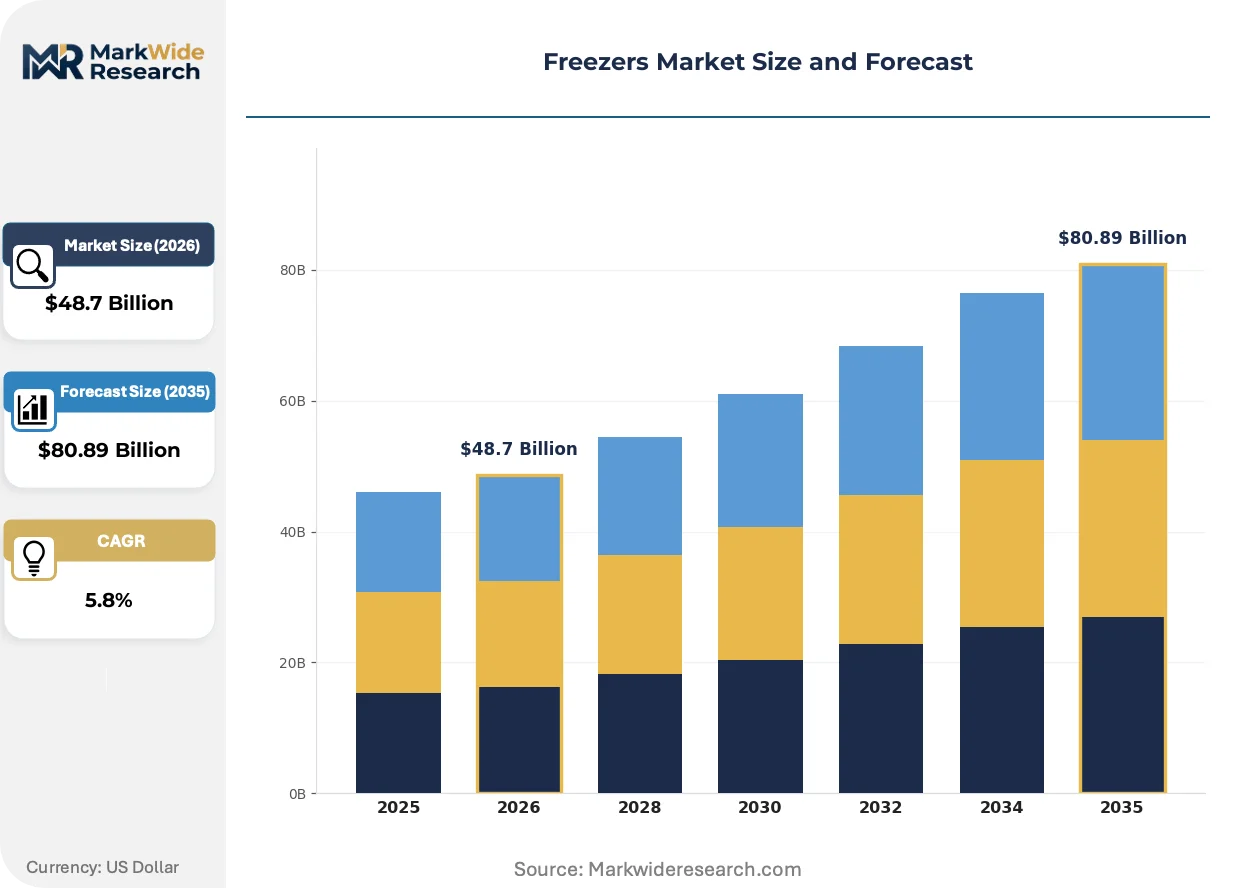
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Freezers, Chest Freezers, Upright Freezers, Display Freezers End User: Retail Chains, Restaurants, Household, Food Processing Technology: Frost Free, Manual Defrost, High Efficiency, Smart Technology Installation: Built-in, Freestanding, Under-counter, Walk-in |
| Companies Covered | Thermo Fisher Scientific Inc., Haier Group, Samsung Electronics, LG Electronics, Liebherr Group, Panasonic Holdings Corporation, Koninklijke Philips N.V., BSH Hausgeräte GmbH, Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezers Market Emerging Trajectories
Digital cold chain verification and predictive maintenance algorithms are compressing equipment lifecycle economics while opening new service revenue streams for fleet operators and facility managers.
Variable-speed compressor technology is expanding into commercial freezer segments previously served by fixed-speed units. Foodservice chains with distributed retail footprints are adopting these systems to reduce energy penalties from door-opening cycles. The technology is expanding into mid-scale grocery and convenience store formats where payback periods now align with lease renewal horizons.
The EPA's refrigerant phase-down schedule under AIM Act authority is compressing hydrofluorocarbon availability for servicing installed bases. Equipment manufacturers are redesigning compressor platforms for hydrofluoroolefin blends and hydrocarbon alternatives simultaneously. Commercial refrigeration OEMs serving the North American market are dual-certifying product lines to hedge against regulatory acceleration or delay.
Subscription-based temperature monitoring is displacing capital-intensive hardware ownership in pharmaceutical logistics. Cold chain operators are unbundling equipment procurement from compliance verification, outsourcing sensor networks and alert management to specialized service providers. This shift concentrates most visibly in vaccine distribution networks where regulatory documentation requirements exceed in-house capabilities of regional distributors.
Freezers Market Segmentation
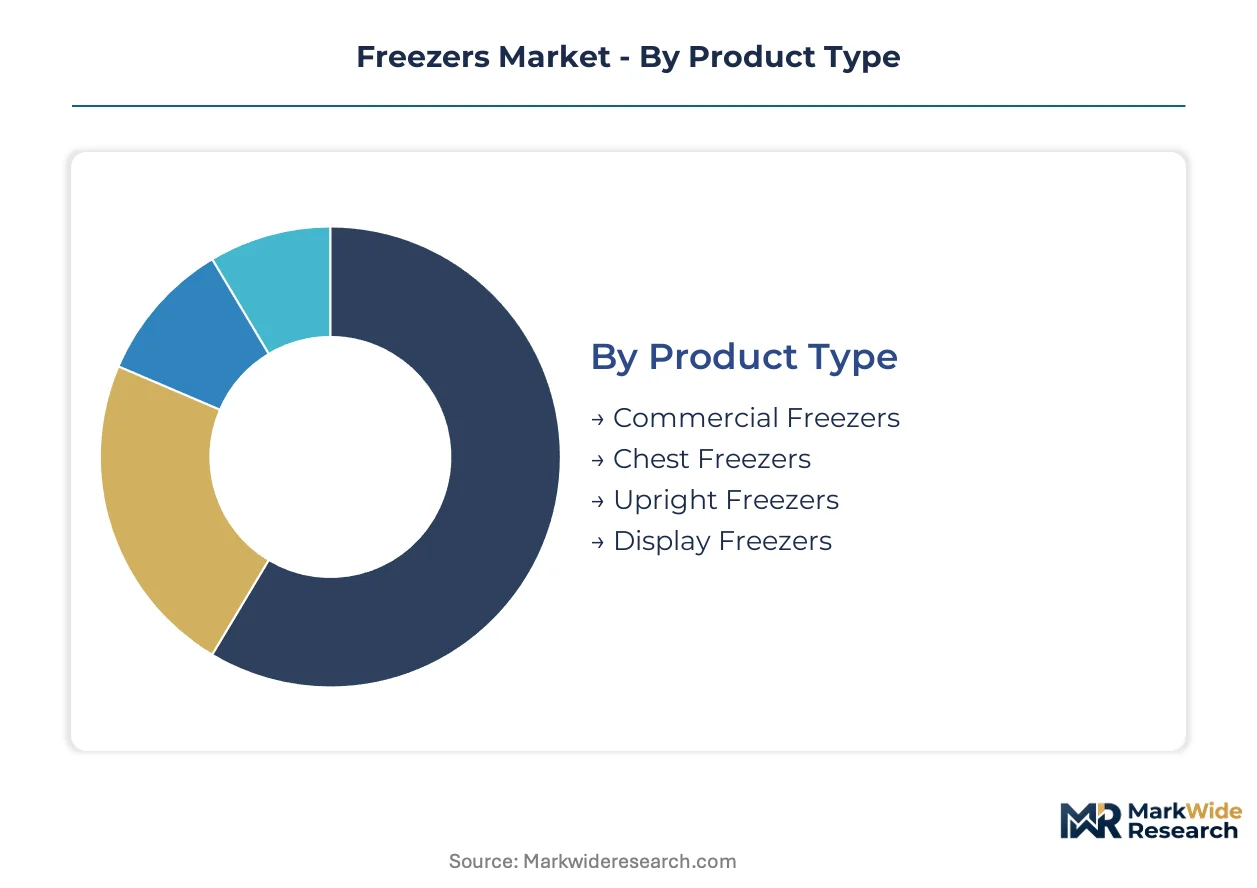
Freezer procurement patterns diverge sharply between integrated cold chain infrastructure and standalone point-of-use installations. Segmentation clarity enables suppliers to align compressor specifications, refrigerant selections, and service architectures with distinct operational intensity profiles across customer tiers.
Product Type:
Standalone units dominate residential and light commercial deployments, while integrated systems anchor industrial-scale cold storage corridors requiring centralized monitoring and redundant compressor arrays.
- Commercial Freezers:Engineered for continuous operation with reinforced door gaskets, heavy-duty shelving, and defrost cycling optimized for high-traffic foodservice environments. Demand concentrates in Vietnam and Thailand frozen seafood export facilities where EU F-Gas Regulation compliance gates market access.
- Chest Freezers:Horizontal lid configuration with top-mount compressor placement minimizes cold air loss during access cycles. First-time appliance ownership in emerging household segments intersects with frozen food retail expansion, sustaining margin pools in price-sensitive distribution channels.
- Upright Freezers:Vertical orientation enables floor-to-ceiling storage density with transparent drawer configurations for inventory visibility. Space-constrained urban retail formats favor these units for back-of-house operations.
- Display Freezers:Glass-front merchandising design integrates LED illumination and anti-fog coatings for impulse purchase environments. Convenience store chains deploy these for frozen beverage and packaged ice cream categories.
Commercial Freezers lead volumes today; Smart Technology variants are gaining share fastest.
End User:
Operational scale determines specification intensity, from household temperature stability requirements to pharmaceutical-grade chain-of-custody documentation mandates.
- Retail Chains:Multi-site operators standardize on remote monitoring platforms that aggregate fleet performance across distributed locations. EPA AIM Act refrigerant phase-down timelines accelerate replacement cycles for aging installed bases.
- Restaurants:High door-opening frequency demands rapid recovery compressors with variable-speed capability to mitigate energy penalties. Independent operators prioritize capital efficiency over premium efficiency ratings.
- Household:Energy label visibility and acoustic performance dominate purchase criteria in replacement-driven mature markets. Emerging market penetration correlates with frozen food retail network density.
- Food Processing:Walk-in and blast-freeze configurations support HACCP compliance with continuous temperature logging for audit trails. Southeast Asian export-oriented processors drive specification upgrades for EU market access.
Retail Chains deploy the largest fleet volumes; Food Processing exhibits the steepest expansion trajectory.
Technology:
Defrost methodology and connectivity architecture segment procurement decisions between maintenance-minimization and energy-optimization priorities.
- Frost Free:Forced-air circulation with timed heating elements eliminates manual defrosting labor. Premium residential and commercial segments absorb higher acquisition costs for operational convenience.
- Manual Defrost:Static cooling plates without active defrost systems reduce component complexity and failure modes. Cost-sensitive emerging markets and backup cold storage applications sustain demand.
- High Efficiency:Variable-speed compressors and enhanced polyurethane foam insulation exceed baseline energy label thresholds. Utility rebate programs and corporate sustainability mandates accelerate specification.
- Smart Technology:IoT sensor integration enables predictive maintenance algorithms and automated alert escalation. Pharmaceutical logistics operators adopt subscription-based monitoring to outsource compliance documentation.
Frost Free configurations anchor installed base volumes; Smart Technology is climbing the fastest.
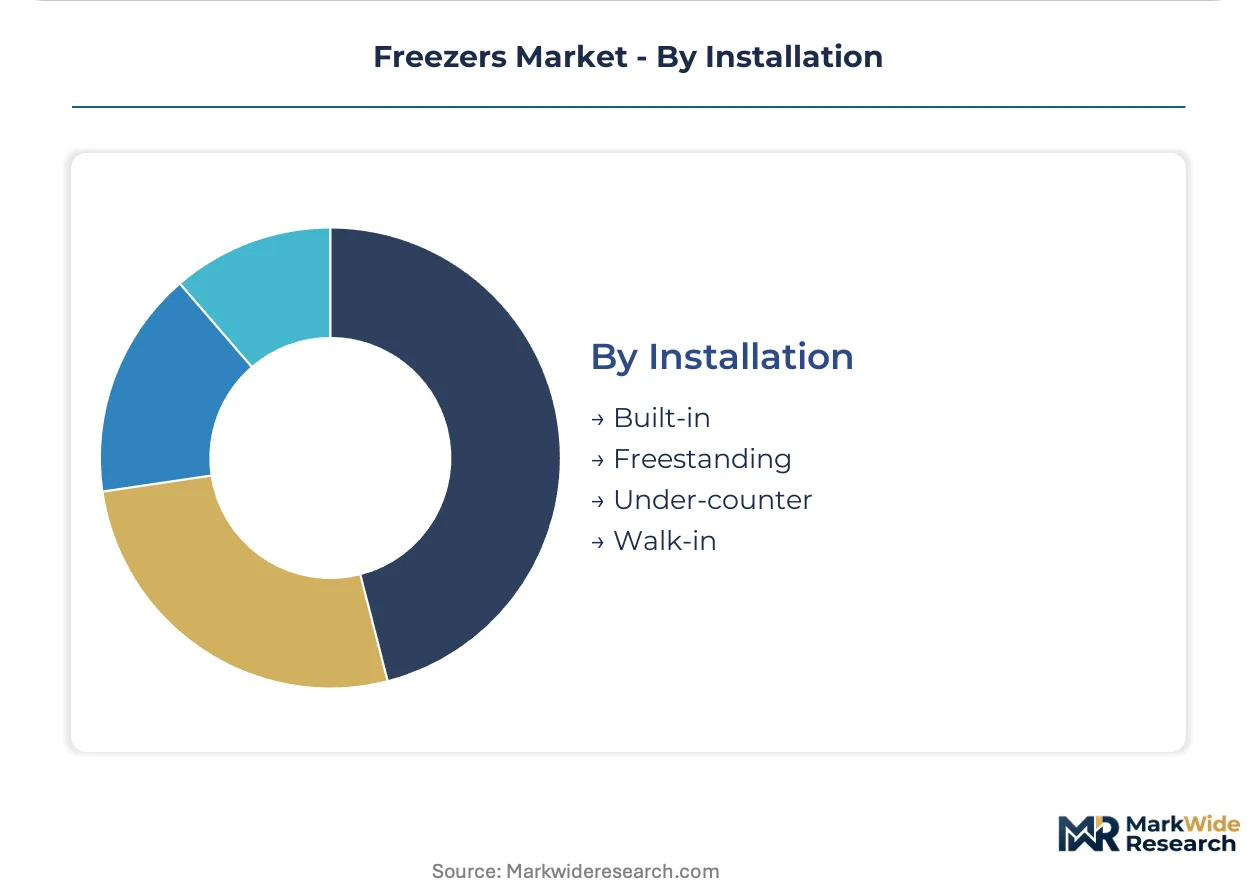
Installation:
Spatial integration requirements determine whether units operate as replaceable appliances or permanent building systems subject to construction permitting.
- Built-in:Flush-mount cabinetry integration with front-venting compressor architecture for kitchen design continuity. Residential renovation and new construction cycles drive specification timing.
- Freestanding:Self-contained mobility enables rapid deployment and relocation without facility modification. Rental properties and temporary foodservice operations favor this flexibility.
- Under-counter:Compact height profiles fit standardized commercial kitchen equipment suites. Bar and beverage service formats optimize floor space utilization.
- Walk-in:Custom-engineered insulated enclosures with remote compressor racks serving multiple temperature zones. Cold chain logistics fleet expansion for vaccine distribution pulls demand for ultra-low temperature variants.
Freestanding units dominate unit shipments; Walk-in installations command the highest value per project.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with refrigerant transition timelines that lag EU and US schedules, exploiting cost-of-compliance gaps while pre-positioning for eventual regulatory convergence.
United States
Pharmaceutical cold chain logistics operators are expanding ultra-low temperature storage fleets to support mRNA vaccine distribution networks. The EPA's AIM Act refrigerant phase-down is compressing hydrofluorocarbon availability and accelerating compressor redesign cycles. Cold storage construction concentrates in the Research Triangle and Greater Boston biotech corridors.
China
Domestic appliance demand intersects with export manufacturing scale as GB standards and NMPA cold chain guidelines tighten compliance layers. The country's dual carbon goals are pressuring manufacturers toward natural refrigerant architectures. Yangtze River Delta production hubs supply Southeast Asian food processing corridors with walk-in freezer systems.
Germany
EU F-Gas Regulation enforcement is filtering lower-tier imports from European distribution channels and accelerating retrofit demand across commercial foodservice. Ecodesign requirements under CE marking directives establish minimum efficiency thresholds. Industrial cold storage engineering concentrates in Baden-Württemberg and Bavaria.
Vietnam
Frozen seafood export facilities are driving specification upgrades for EU market access compliance. The country's food processing corridors are concentrating prepared food production capacity. Ho Chi Minh City and Mekong Delta industrial zones anchor walk-in freezer installation demand.
India
Production-linked incentive schemes for white goods are attracting component localization investments that reduce landed costs for domestic freezer assembly. FSSAI cold chain mandates for vaccine storage are expanding institutional procurement. Gujarat and Maharashtra manufacturing clusters are scaling compressor component supply.
Freezers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in biopharmaceutical cold storage and fragmented competition in residential replacement markets. Tier-one players anchor premium specification segments through instrumentation heritage and smart appliance ecosystems. Mid-scale OEMs compete on manufacturing scale and regional distribution density. Dominant competitive moves include backward integration into compressor component supply and technology licensing partnerships for natural refrigerant architectures.
Among diversified appliance conglomerates, Haier Group and Samsung Electronics exemplify scale-driven positioning across residential and light commercial segments. Thermo Fisher Scientific occupies the precision-tier vector for biopharmaceutical cold storage specifications. These three entities represent distinct competitive archetypes: manufacturing scale, smart ecosystem integration, and life sciences instrumentation heritage.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Haier Group |
| Samsung Electronics |
| LG Electronics |
| Liebherr Group |
| Panasonic Holdings Corporation |
| Koninklijke Philips N.V. |
| BSH Hausgeräte GmbH |
| Hitachi, Ltd. |
| Others |
Supply Flow & Price Mechanics
Variable-speed compressor technology adoption is simultaneously compressing manufacturing cost curves and concentrating procurement leverage among scale-tier OEMs with captive component supply. The shift redraws margin pools across tiered supplier bases as energy-efficiency premiums command pricing power in regulated markets.
Pricing Analysis
Distributor margins in commercial freezer channels typically absorb 18-25 points before retail markup, compressing netbacks for mid-tier manufacturers without direct fleet operator relationships. Three-tier pricing structure across premium smart-connected, standard efficiency-compliant, and economy manual-defrost levels stratifies procurement decisions. Pricing pressure stems from copper and steel input volatility that erodes fixed-contract profitability. Independent restaurants and emerging-market households exhibit highest price sensitivity; biopharmaceutical cold chain operators demonstrate lowest sensitivity due to compliance documentation requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cold chain logistics fleet demand, while specialized refrigeration distributors serve fragmented foodservice and retail replacement markets. Compressor manufacturing concentrates in China, Germany, and Thailand, with hydrofluoroolefin blend production anchored in Chinese chemical manufacturing zones. Supply chains draw from copper coil assemblies, polyurethane foam insulation, and refrigerant chemicals as critical inputs. Single-source dependency on Chinese HFO production creates vulnerability to export licensing shifts. Distribution runs through authorized service networks for commercial installations and mass retail for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freezers market functions as a stable compounder anchored by regulatory-mandated replacement cycles for refrigerant transitions and cold chain infrastructure buildouts in pharmaceutical distribution.
For Market Incumbents: Deploy backward integration into compressor component supply to defend margin pools against raw material volatility and Chinese HFO supply concentration. Accelerate smart technology certification investments to capture pharmaceutical cold chain specification locks before regulatory documentation requirements tighten further. Natural refrigerant architecture R&D represents essential defensive positioning as EU F-Gas Regulation enforcement filters import competition. For New Entrants and Emerging Players: Capture India's PLI scheme white space through component localization partnerships that reduce landed costs for domestic freezer assembly. Target Vietnam's frozen seafood export corridor with EU F-Gas Regulation-compliant walk-in systems as specification upgrades create entry windows for compliant suppliers. Subscription-based temperature monitoring services offer lower capital-barrier go-to-market positioning versus hardware-only incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional OEMs lacking smart technology portfolios or natural refrigerant certifications. Five-to-ten year viability favors suppliers with demonstrated pharmaceutical cold chain compliance documentation and Southeast Asian manufacturing footprints. Monitor EPA AIM Act refrigerant phase-down acceleration as inflection signal for replacement cycle timing and compressor platform obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Development | EU F-Gas Regulation compliance gates market access for European commercial installations. |
| Remote Temperature Monitoring Subscription Launch | Pharmaceutical logistics operators outsource compliance documentation to specialized service providers. |
| Backward Integration into Compressor Components | Captive supply of copper coil assemblies mitigates raw material price volatility exposure. |
| PLI Scheme Manufacturing Localization | India's production-linked incentives reduce landed costs for domestic freezer assembly operations. |
| Biopharmaceutical Cold Storage Certification Investment | Thermo Fisher Scientific's instrumentation heritage demonstrates specification lock-in value for precision-tier positioning. |
Methodological Framework
Direct dialogue with cold chain logistics operators, commercial refrigeration OEM procurement directors, refrigerant chemical suppliers, foodservice fleet maintenance managers, and pharmaceutical distribution compliance officers grounded qualitative assessment. Secondary validation incorporated EPA AIM Act regulatory filings, EU F-Gas Regulation implementation schedules, NMPA cold chain guidelines, customs trade data for compressor component flows, and SEC 10-K disclosures from diversified appliance conglomerates. Bottom-up unit shipment modeling triangulated against top-down cold chain infrastructure investment tracking.
Installed base forecasts by product type, end-user segment, technology tier, and installation format across the projection horizon enabled granular demand decomposition. CAGRs derived from regression analysis against regulatory phase-down timelines, cold chain fleet expansion trajectories, and frozen food retail network density proxies. Refrigerant chemistry transition schedules and Southeast Asian food processing corridor buildouts served as primary industry-specific forecast inputs.
Refrigerant regulation acceleration, copper and steel commodity price spikes, and natural refrigerant safety code adoption delays are the dominant revision risks that could compress or extend replacement cycle timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cold chain infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Milk Sterilizer Machine Market