
 Beer Brewing Equipment Market | 2026-2036
Beer Brewing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Brewing Equipment Market Intelligence
Stricter food contact material standards, such as those guided by the EFSA in Europe, is realigning the cost-of-entry calculus for new equipment manufacturers. Established suppliers like GEA Group leverage extensive engineering expertise to ensure compliance across their diverse product lines. Krones sustains its leadership in the large brewery segment through highly automated, turnkey system installations. Meanwhile, Alfa Laval specializes in critical components like separators and heat exchangers that meet the most stringent hygienic requirements.
Beer brewing equipment comprises the integrated system of vessels, pumps, and controls used for beer production, from mashing and boiling to fermentation and conditioning. Most equipment is constructed from food-grade stainless steel, typically 304 or 316L, to ensure sanitation and prevent flavor contamination. The primary commercial purpose is to enable precise control over temperature, time, and process flow to achieve consistent and high-quality beer. The Microbreweries and Brewpubs end-user segments are driving sales of systems with a capacity between 21 and 100 gallons, while Fermenters and Kettles remain core product types attracting significant R&D investment.
The regulatory environment is defined by bodies like the FDA in the United States, which governs materials safe for food contact. In Germany, while not a direct equipment law, the Reinheitsgebot influences equipment design to process traditional ingredients effectively. Global benchmarks like ISO 22000 for food safety management systems create a baseline for manufacturing quality. Equipment suppliers must decide whether to engineer for universal compliance or to develop specialized systems tailored to regional regulatory and consumer preferences.
Market Dynamics
The market's central dynamic is the bifurcation of equipment demand, driven by the simultaneous expansion of large automated breweries and the proliferation of artisanal microbreweries, creating distinct requirements for system scale, automation, and cost.
Growth Catalysts
- Microbrewery Expansion:Consumer enthusiasm for craft beers in established markets like the United States and the United Kingdom directly fuels sales of smaller-capacity systems, particularly those between 21 and 100 gallons.
- Sustainability Mandates:Policy frameworks such as the EU Green Deal pressure breweries to invest in equipment featuring advanced water-saving and energy-recovery technologies, creating a replacement and upgrade cycle.
- Process Automation:The accessibility of affordable control systems enables smaller breweries to achieve a level of product consistency previously only possible for large-scale producers, increasing demand for semi-automated fermenters and kettles.
Market Restraints
- Material Price Volatility:Fluctuations in the cost of food-grade 304 and 316L stainless steel, the primary construction material, create significant cost uncertainty for equipment manufacturers and can delay purchasing decisions.
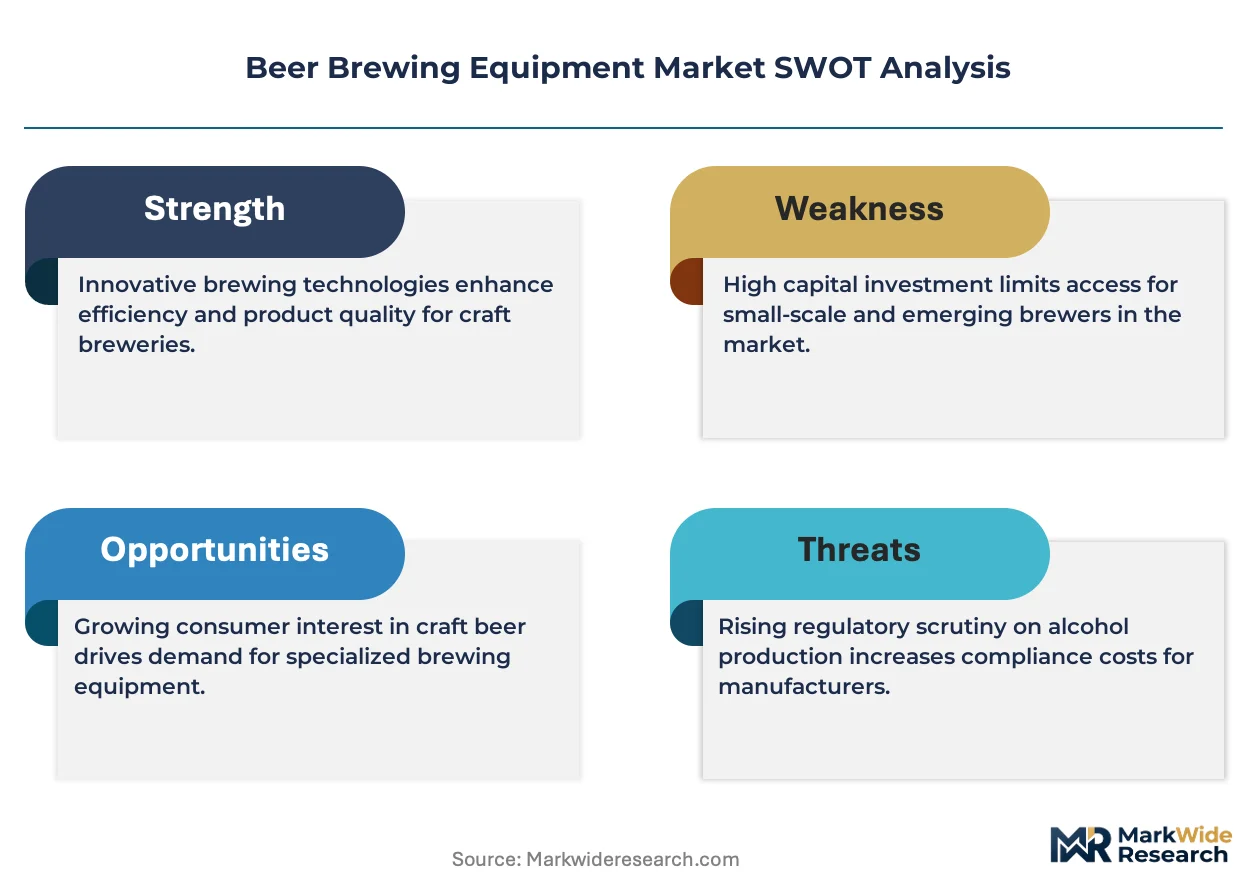
- Regulatory Compliance Costs:Adhering to stringent food contact material standards set by bodies like the EFSA in Europe and the FDA in the US elevates engineering and testing costs, acting as a barrier for new entrants.
- Long Equipment Lifespan:The inherent durability of stainless steel brewing vessels results in long replacement cycles, which limits the overall volume of new unit sales to primarily new projects or capacity expansions.
Strategic Opportunities
- Modular System Design:Offering scalable, modular equipment configurations allows new and growing breweries to expand capacity incrementally, aligning capital expenditure with business growth and reducing initial investment risk.
- Equipment for Non-Alcoholic Beer:Developing specialized systems for dealcoholization and flavor retention caters to the fast-growing non-alcoholic and low-alcohol beer segment, opening a new product vertical for manufacturers.
- Emerging Craft Beer Geographies:Untapped demand in regions like Latin America and Southeast Asia, where craft beer culture is nascent, provides a growth vector for suppliers of smaller, cost-effective brewing systems.
Industry Challenges
- Integration with Legacy Systems:Breweries face significant technical hurdles and operational downtime when attempting to integrate modern, automated components with older, manually operated equipment from different manufacturers.
- Shortage of Skilled Technicians:The convergence of mechanical engineering, brewing science, and software automation creates a talent gap for operators and maintenance personnel capable of managing complex, integrated brewing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Brewing Equipment Market |
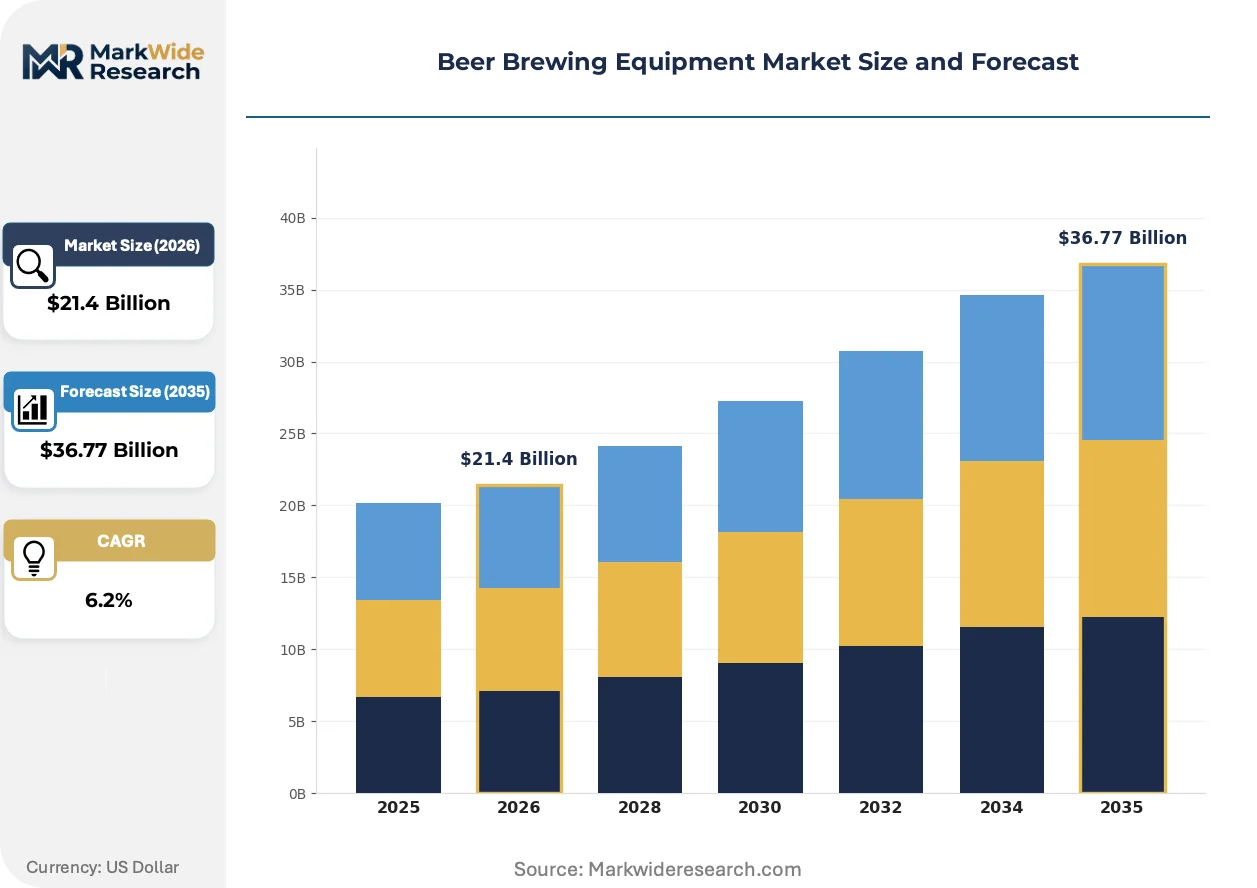
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $36.77 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kettles, Fermenters, Pumps, Wort Chillers Technology: Electric, Steam, Gravity, Hybrid End User: Microbreweries, Brewpubs, Homebrewers, Large Breweries Capacity: 1-5 Gallons, 6-20 Gallons, 21-100 Gallons, Over 100 Gallons |
| Companies Covered | GEA Group, Krones, Alfa Laval, Meura, Della Toffola, Lehui, Paul Mueller Company, Criveller Group, BrauKon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Brewing Equipment Market Strategic Shifts & Innovations
A convergence of digitalization and sustainability is reshaping equipment design. The focus is shifting from standalone vessel manufacturing to creating integrated, data-driven systems that optimize resource use while ensuring precise quality control from grain to glass.
Integrated IoT sensors and cloud-based software are becoming standard features in modern brewing equipment. Microbreweries and brewpubs are the primary adopters, seeking to guarantee batch consistency and streamline operations. This technology is unifying disparate brewing stages like mashing, boiling, and fermentation into a single, cohesive, and digitally monitored production workflow.
European Union regulations, particularly sustainability targets within the EU Green Deal, are a powerful force in equipment innovation. These policies directly incentivize the development of systems that minimize water consumption, recapture thermal energy, and improve overall process efficiency. Large-scale breweries are most affected, prioritizing high-efficiency equipment for new installations to meet corporate and regulatory sustainability mandates.
Brewery purchasing behavior is evolving toward modular and phased capital deployment. Instead of committing to large, fixed-capacity brewhouses, many startups and expanding craft breweries now prefer to acquire smaller, scalable components like individual fermenters or conditioning tanks as needed. This trend is most visible in the North American brewpub segment, where it allows for flexible, demand-driven capacity expansion.
Beer Brewing Equipment Market Segmentation
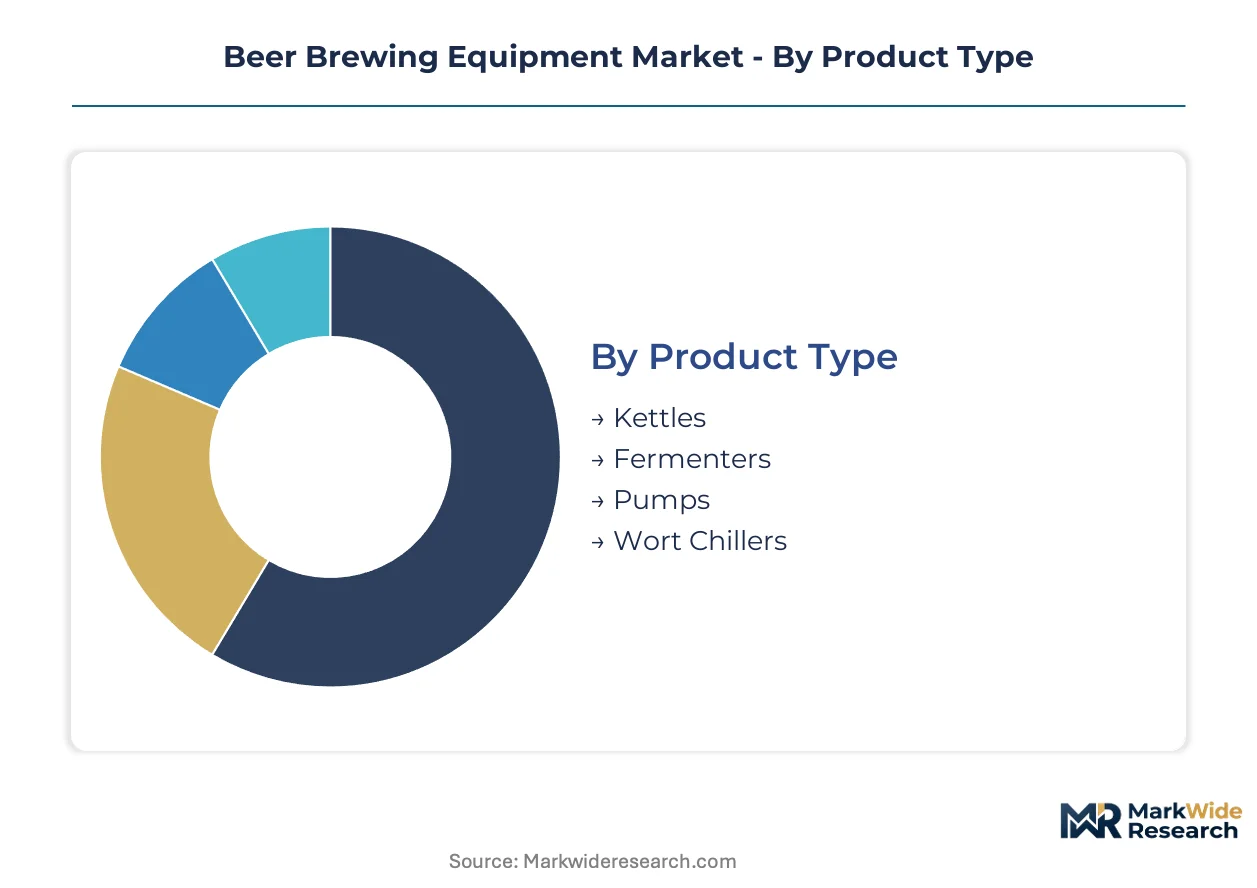
The beer brewing equipment market exhibits diverse requirements across its operational spectrum, necessitating a granular understanding of segment-specific dynamics. Equipment manufacturers must align product development with distinct end-user needs and technological preferences. This segmentation analysis dissects the market to reveal where value concentrates and where growth opportunities emerge.
Product Type:
Investment in core brewing components represents a significant upfront capital expenditure for breweries of all scales, directly influencing operational efficiency and product quality.
- Fermenters:These vessels are crucial for converting wort into beer through yeast activity, requiring precise temperature control and hygienic design. Demand concentrates in both microbreweries and large-scale operations, driven by the need for consistent batch quality.
- Kettles:Brewing kettles are central to the boiling and hopping stages, demanding robust construction and efficient heating mechanisms. Established craft beer markets such as the United States and Germany drive sales, focusing on energy-efficient designs.
- Pumps:Essential for transferring liquids throughout the brewing process, industrial-grade pumps ensure efficient and sanitary fluid movement.
- Wort Chillers:These heat exchangers rapidly cool wort before fermentation, preventing bacterial contamination and optimizing yeast performance.
Fermenters absorb the bulk of installed capacity; Kettles are expanding most quickly.
Technology:
The choice of brewing technology directly impacts energy consumption and operational scalability, with different systems optimized for specific production volumes and resource availability.
- Steam:Steam-heated systems offer rapid and precise temperature control, making them prevalent in large commercial breweries for high-volume production. These systems are favored in regions with established industrial infrastructure, such as Germany and the United Kingdom, for their efficiency.
- Electric:Electric brewing systems provide simpler installation and lower initial costs, making them popular among microbreweries and brewpubs. Their adoption is widespread in urban centers across the United States, where space and utility access are considerations.
- Gravity:Gravity-fed systems utilize natural elevation differences to move liquids, reducing the need for pumps and offering a traditional brewing approach.
- Hybrid:Hybrid systems combine elements of different technologies, such as electric heating with gravity transfer, to optimize specific process steps.
Efficiency and scalability considerations drive technology choices for breweries.
End User:
Different end-user segments demand equipment tailored to their distinct production volumes, automation needs, and investment capacities, from artisanal operations to industrial-scale facilities.
- Microbreweries:These smaller commercial breweries focus on craft and artisanal beers, requiring flexible systems often between 21 and 100 gallons. Consumer enthusiasm for craft beers in markets like the United States and the United Kingdom fuels demand for these systems.
- Large Breweries:Industrial-scale operations prioritize high-throughput, fully automated systems for mass production and consistent quality. Established players like Krones sustain their leadership in this segment through highly automated, turnkey system installations.
- Brewpubs:Combining a brewery with a restaurant, brewpubs typically require compact, visible brewing systems that can produce beer for on-site consumption.
- Homebrewers:Hobbyist brewers utilize small-scale, often manual equipment for personal consumption, representing a niche but foundational market segment.
Microbreweries and Large Breweries represent the primary revenue generators for equipment suppliers.
Capacity:
Equipment capacity directly correlates with production volume, influencing operational scale and the target market for brewed products, from small-batch craft to industrial output.
- 21-100 Gallons:This capacity range caters primarily to microbreweries and brewpubs, offering a balance of scalability and manageable investment. Sales are driven by the proliferation of craft beer establishments in North America and Europe.
- Over 100 Gallons:Systems exceeding 100 gallons are designed for large-scale commercial breweries demanding high production volumes and continuous operation. These larger systems are critical for established brands seeking to meet global demand.
- 1-5 Gallons:This small capacity serves homebrewers and experimental batches, emphasizing ease of use and affordability for personal or pilot productions.
- 6-20 Gallons:Equipment in this range targets advanced homebrewers or very small-scale commercial ventures, providing more flexibility than smaller systems.
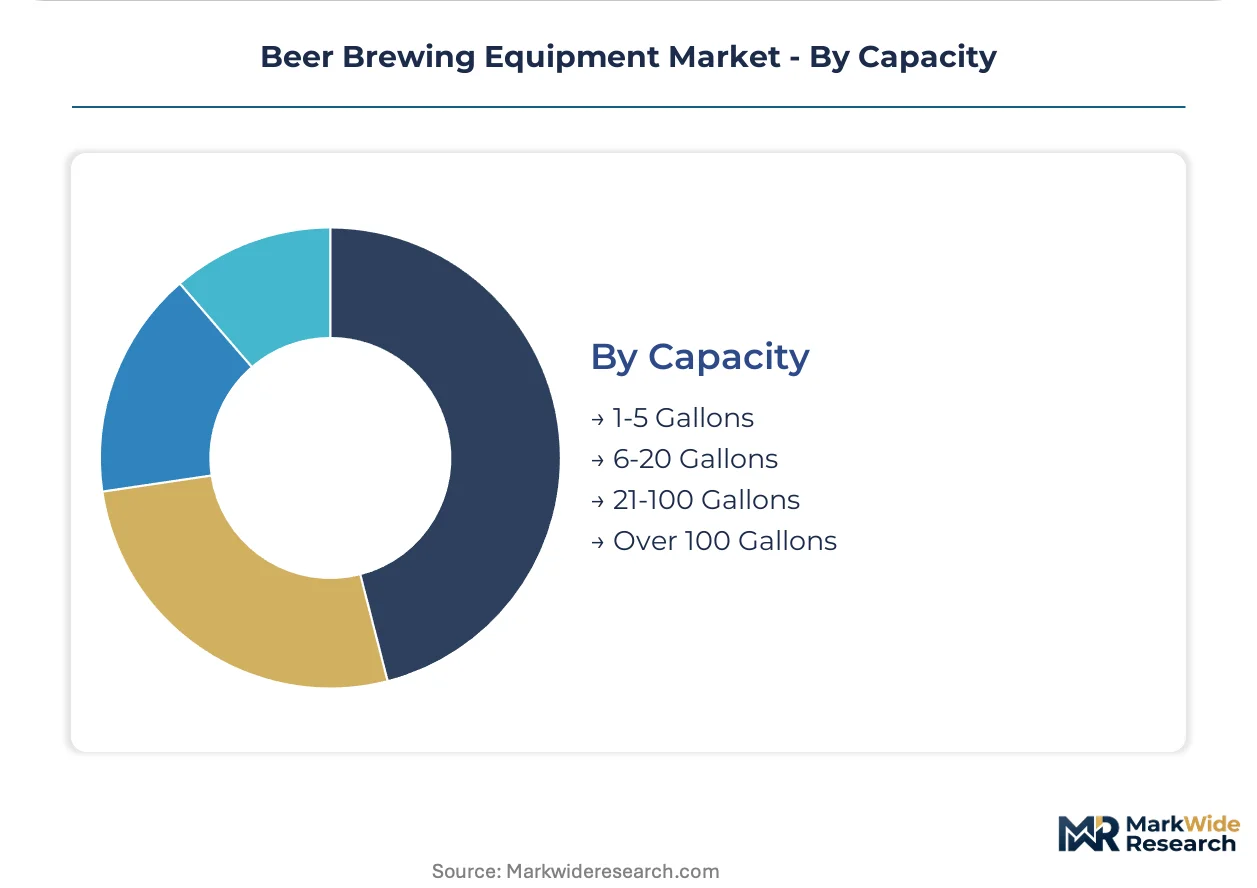
The 21-100 Gallons segment shows the steepest expansion trajectory due to craft beer growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The proliferation of craft brewery zones, often supported by local economic development incentives in the United States, drives concentrated demand for brewing equipment across various global regions. This localized growth pattern creates distinct requirements for system scale, automation, and cost, influencing market dynamics significantly.
United States
The United States market sees robust demand from microbrewery expansion, fueled by strong consumer enthusiasm for craft beers. FDA regulations for food contact materials significantly influence equipment design and material choices. Portland, Oregon, within the Pacific Northwest, remains a hub for craft brewing innovation, driving sales of flexible, smaller-capacity systems.
Germany
Germany's market for brewing equipment is shaped by its established large breweries and the enduring influence of the Reinheitsgebot. EFSA standards for food contact materials ensure high-quality construction and hygiene across all equipment lines. Bavaria, with its deep-rooted brewing heritage, continues to drive demand for energy-efficient kettles and precision control systems.
United Kingdom
United Kingdom microbrewery growth directly fuels sales of smaller-capacity systems, responding to evolving consumer preferences. Policy frameworks like the EU Green Deal, though post-Brexit, still influence the adoption of water-saving and energy-recovery technologies. London's dynamic craft beer scene actively seeks compact, visible brewing systems for brewpub installations.
Brazil
Brazil presents a growth vector for brewing equipment suppliers, driven by its nascent but expanding craft beer culture. ANVISA, the national health surveillance agency, mandates stringent food safety and material compliance for all processing equipment. São Paulo and Minas Gerais states are witnessing significant investment in new small-scale brewery projects.
Vietnam
Vietnam's emerging craft beer market creates new opportunities for cost-effective brewing systems, particularly in urban centers. The Ministry of Health establishes food safety and hygiene regulations that equipment must satisfy. Ho Chi Minh City's rapidly expanding hospitality sector supports a rising number of brewpub and microbrewery installations.
Beer Brewing Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure for beer brewing equipment. The market features global system integrators, specialized component manufacturers, and regional fabricators. Dominant competitive moves include portfolio diversification to serve multiple brewery scales and strategic partnerships for technology integration.
Within the diversified system provider archetype, Germany-based GEA Group and Krones AG exemplify comprehensive engineering and turnkey solutions for large-scale breweries. Alfa Laval AB, a Sweden-based company, anchors the specialized component segment, focusing on critical items like separators and heat exchangers that meet stringent hygienic requirements.
| Leading Market Players |
|---|
| GEA Group |
| Krones |
| Alfa Laval |
| Meura |
| Della Toffola |
| Lehui |
| Paul Mueller Company |
| Criveller Group |
| BrauKon |
| Others |
Cost & Logistics Intelligence
The global stainless steel price index, a key commodity benchmark, directly cascades through the beer brewing equipment supply chain into distinct pricing tiers for finished products. This volatility creates cost uncertainty for manufacturers and influences purchasing decisions across all brewery scales.
Pricing Analysis
Lead-time-driven pricing offers a premium for rapid delivery of standardized equipment, while custom project installations often involve contract-based long-term agreements. Pricing separates high-performance systems from basic components, driven by quality grade of stainless steel and level of automation. Pricing pressure stems from material price volatility and intense competition among regional fabricators. Microbreweries and new entrants often exhibit the highest price sensitivity, balancing initial capital expenditure with desired operational capabilities.
Supply Chain Analysis
Direct sales channels handle large-scale brewery installations, while distributor networks serve the fragmented microbrewery segment. Geographic supply concentration for critical components centers on Germany, China, and Sweden. The supply chain draws heavily from specialized food-grade stainless steel (304 and 316L) and precision control systems. Material price volatility for stainless steel represents a significant structural risk across the entire supply chain. Component suppliers often rely on global logistics networks for timely delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with equipment manufacturers pursuing upstream control over specialized component production to enhance differentiation.
For Market Incumbents: Extend product portfolios to include specialized systems for non-alcoholic beer production, addressing a fast-growing consumer segment. Invest in advanced automation and IoT integration to maintain a technological edge against emerging low-cost manufacturers. Leverage extensive engineering expertise to ensure compliance with evolving food contact material standards like EFSA regulations, reinforcing market leadership.
For New Entrants and Emerging Players: Regional distributors offer a vital channel for new entrants to penetrate nascent craft beer markets in Latin America and Southeast Asia. Target the 21-100 gallon capacity segment, which represents the fastest-growing opportunity due to microbrewery expansion. Offer modular, scalable equipment configurations to align with the capital expenditure cycles of growing craft breweries. Develop strong after-sales service networks as a key go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized component manufacturers in established brewing regions like Germany, offering strategic value. The long-term viability of the brewing industry, driven by consistent global beer consumption, supports sustained investment over a multi-year horizon. Target technology-focused firms specializing in water-saving or energy-recovery solutions. Consolidation among smaller equipment providers signals market maturation and potential acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand modular system offerings | Supports incremental capacity growth for microbreweries and reduces their initial investment risk. |
| Invest in dealcoholization technology | Captures share in the rapidly expanding non-alcoholic and low-alcohol beer segment. |
| Develop integrated IoT platforms | Enhances batch consistency and operational efficiency for both large and small breweries. |
| Form strategic partnerships in emerging markets | Facilitates market entry and localized distribution in regions with nascent craft beer cultures. |
| Prioritize advanced water-saving features | Addresses sustainability mandates from policies like the EU Green Deal and reduces operational costs. |
Research Approach
Independent corroboration across industry association reports, government food safety guidelines, and company financial disclosures underwrites the qualitative findings. This study combined extensive primary interviews with industry stakeholders, including brewery owners, equipment engineers, procurement managers, and regulatory compliance specialists, with thorough secondary validation. A bottom-up approach for market sizing was triangulated with top-down validation.
The forecast framework anchored the projection horizon to historical reference periods, establishing a robust baseline for future estimates. Segmentation dimensions modeled included product type, technology, end user, capacity, and regional regulatory environments. Compound Annual Growth Rates were derived through regression analysis, incorporating market-specific growth factors such as craft beer consumption trends and stainless steel prices over the analysis window.
Several conditions sit outside the modeled scope, including unforeseen geopolitical instability affecting raw material supply or sudden shifts in consumer beverage preferences. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Bread Processing Equipment Market