
 Bottling Line Machinery Market | 2026-2036
Bottling Line Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Bottling Line Machinery Market Intelligence
The capability gap between supplying fully integrated turnkey lines and standalone modular equipment is collapsing. Krones AG dominates the high-speed, integrated systems segment for major beverage producers. In contrast, ProMach specializes in providing a diverse portfolio of specialized machinery across various packaging functions. Syntegon Technology GmbH leverages its expertise in pharmaceutical-grade filling and processing to serve high-value applications, demonstrating a focus on precision and sterility that commands premium pricing.
Bottling line machinery comprises interconnected equipment designed for filling, sealing, and labeling containers in a continuous process. These systems are engineered to handle specific product viscosities and container materials like glass or PET at speeds that can exceed 50,000 bottles per hour. The beverage application segment, driven by non-alcoholic drinks and water, constitutes the largest share of the market. Within technology, fully automatic systems are displacing semi-automatic variants due to pressures from labor costs and the need for higher operational efficiency.
Compliance with standards such as the EU's CE marking for machinery safety and the US FDA's regulations for food-contact surfaces is mandatory for market access. These frameworks dictate material selection, clean-in-place capabilities, and operator safety features, directly influencing equipment design and cost. Equipment buyers must now evaluate a machine's adaptability to new container formats and its readiness for digital integration with factory management systems.
Market Dynamics
The drive for operational agility defines the market, creating tension between demand for flexible, modular lines for craft beverages and the need for high-speed systems for mass-market water and soda production.
Growth Catalysts
- Craft Beverage Growth:Expansion in microbreweries and artisanal spirit producers creates demand for smaller, adaptable filling and capping machinery.
- Stringent Regulations:Mandates from the FDA and EFSA on food contact materials push investment in equipment with superior hygienic design and clean-in-place capabilities.
- Automation in Asia:China's food and beverage sector requires high-speed automated systems to offset rising labor costs and increase output.
Market Restraints
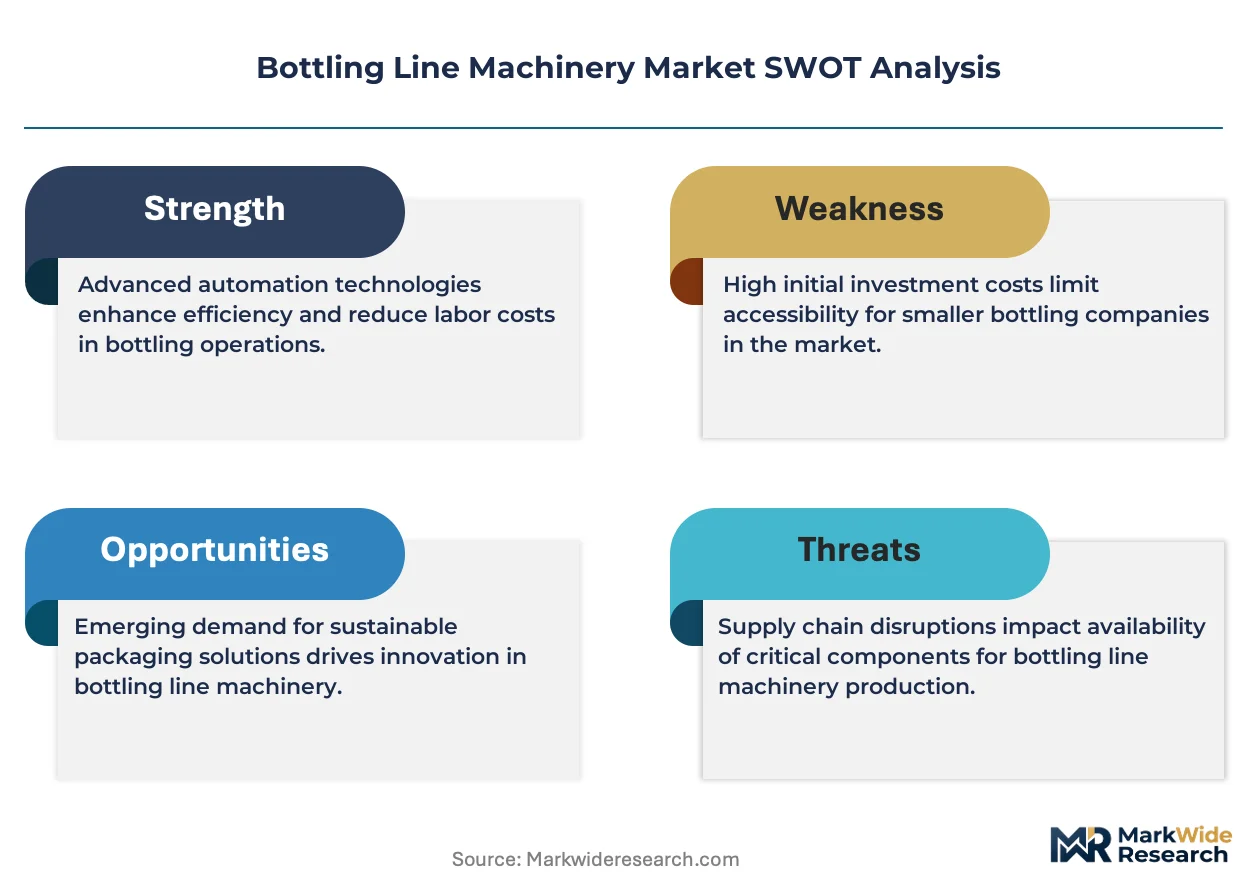
- High Capital Outlay:The significant investment for fully automatic, integrated lines is a major barrier for small to mid-sized enterprises.
- Component Supply Volatility:Reliance on specialized electronics, like PLCs from a concentrated supplier base, creates production risks.
- Flexibility vs. Speed Trade-off:Designing equipment for both maximum throughput and rapid container changes is a persistent engineering constraint.
Strategic Opportunities
- Alternative Beverages:The market for plant-based milks and functional drinks needs specialized filling lines adapted to unique product viscosities.
- AI-Powered Maintenance:Integrating AI for predictive maintenance offers a new value stream via service contracts that reduce customer downtime.
- Southeast Asia Modernization:Upgrading bottling infrastructure in markets like Vietnam and Thailand to meet rising beverage demand presents growth potential.
Industry Challenges
- Mechatronics Skill Gap:A shortage of technicians with combined mechanical, electronic, and software expertise hinders installation and servicing of advanced systems.
- Inter-Vendor Integration:Ensuring seamless data and physical synchronization between machines from different manufacturers in a mixed-vendor line is a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottling Line Machinery Market |
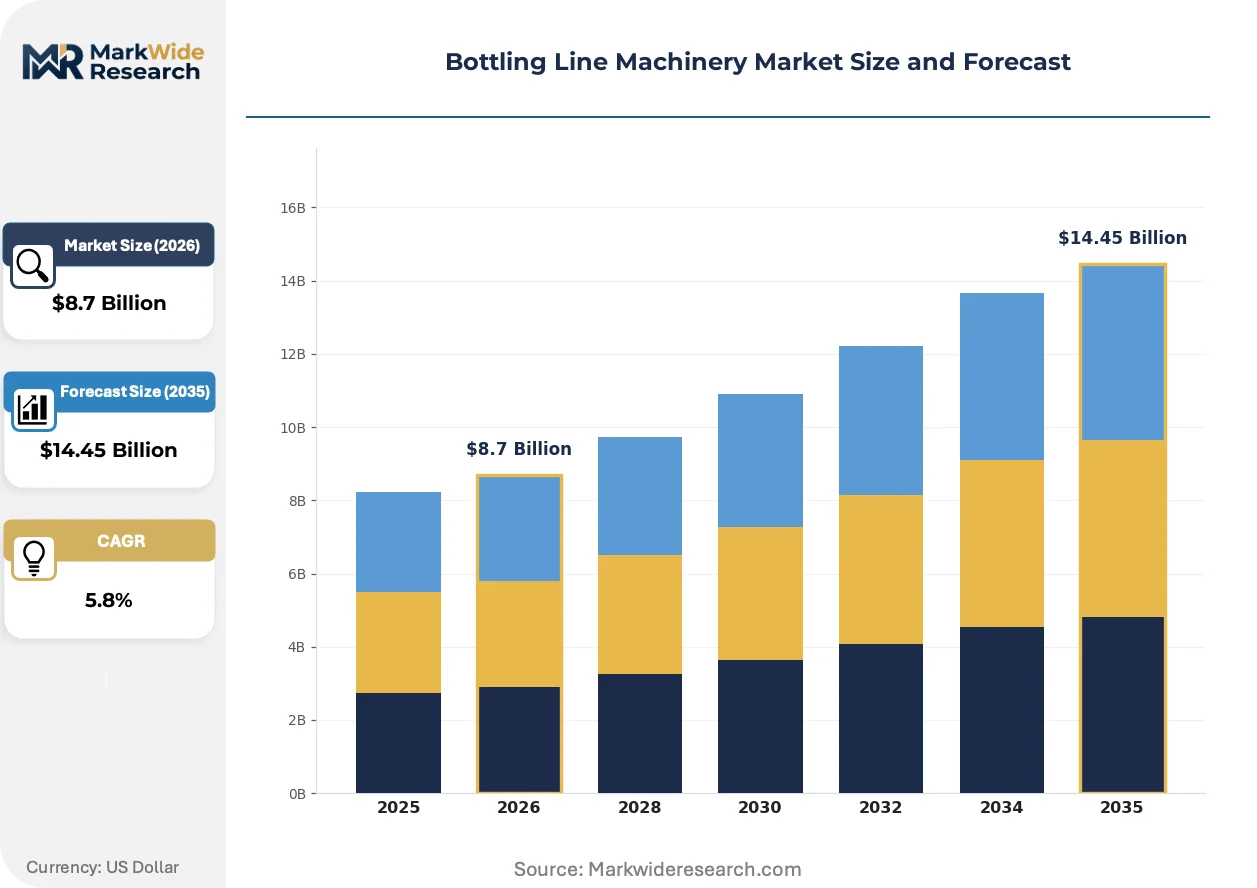
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filling Machines, Capping Machines, Labeling Machines, Bottle Washers Application: Beverage, Chemical, Pharmaceutical, Food Technology: Automatic, Semi-Automatic, Manual, Hybrid End User: Beverage Manufacturers, Food Producers, Chemical Plants, Contract Packagers |
| Companies Covered | Syntegon Technology GmbH, ProMach, Krones AG, Sacmi Imola S.C., GEA Group, KHS GmbH, Coesia S.p.A., Barry-Wehmiller Group, Tetra Laval Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottling Line Machinery Market Strategic Shifts & Innovations
Digitalization and sustainability are the primary forces acting on equipment design. Manufacturers are embedding intelligence into machinery for operational efficiency while simultaneously adapting systems to handle new, environmentally-driven packaging materials and formats.
Smart Sensors: Smart sensors with IO-Link connectivity provide granular, real-time data on critical process parameters like fill level and capping torque. Beverage producers and pharmaceutical fillers are adopting these components to enhance process control. This integration of distributed intelligence is miniaturizing the physical control cabinet and decentralizing process adjustments to the individual machine module.
Regulatory Material Compliance: The European Union's Packaging and Packaging Waste Regulation (PPWR) proposes mandatory recycled content targets for PET bottles. This impacts machinery design, requiring systems that can process rPET, which has different properties than virgin material. The non-alcoholic beverage segment is most affected, prompting investment in more tolerant and adaptive equipment.
Service-Based Procurement: Equipment buyers are exploring usage-based models like leasing, shifting focus from a single capital expense to operational costs. This trend challenges the traditional direct sales channel, creating an opening for OEMs bundling equipment with long-term service guarantees. This procurement shift is most visible among European contract manufacturers seeking to reduce capex.
Bottling Line Machinery Market Segmentation
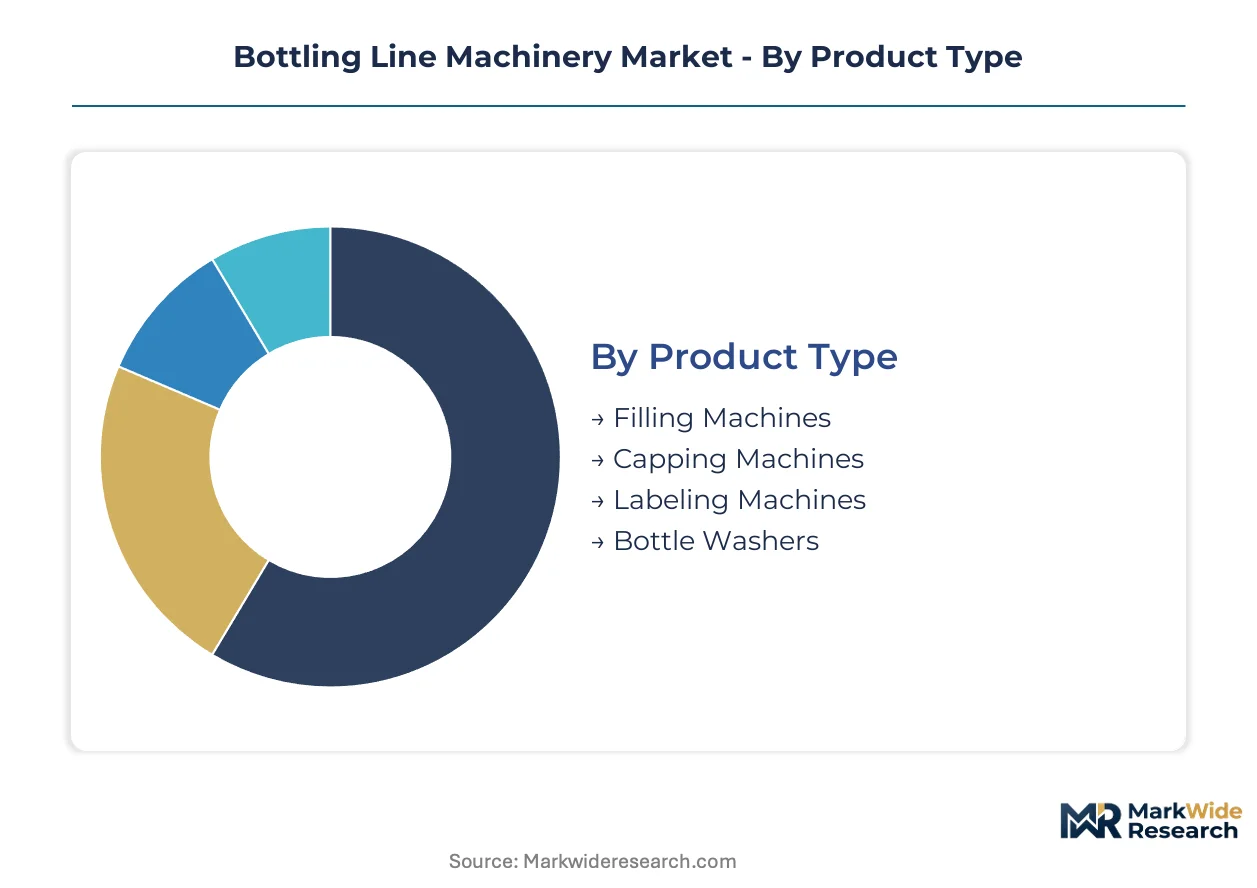
The bottling line machinery market differentiates across diverse product types and applications, reflecting specialized requirements for various liquid products. Understanding these segments helps manufacturers tailor equipment to specific operational demands and evolving regulatory landscapes. This granular view highlights areas of concentrated investment and emerging technological shifts.
Product Type:
Within bottling line machinery, certain product types face stronger substitution pressure from integrated multi-function units or advancements in upstream packaging. This dynamic influences investment cycles and technological innovation.
- Filling Machines:These systems precisely dispense liquid products into containers, utilizing technologies like volumetric, gravimetric, or net weight filling. Demand concentrates in high-speed beverage production in China, driven by the need for rapid throughput and consistent product quality.
- Capping Machines:These units securely seal containers with screw caps, snap-on caps, or ROPP closures, ensuring product integrity.
- Labeling Machines:This equipment applies various label types, including pressure-sensitive, shrink sleeve, or roll-fed, to containers for brand identification and regulatory information. Beverage manufacturers in Germany adopt advanced labelers to accommodate diverse packaging formats and meet EU CE marking requirements.
- Bottle Washers:Industrial washing systems clean and sterilize containers, crucial for hygienic packaging in pharmaceutical and food applications.
Filling Machines anchor the volume base while Labeling Machines gain share at the steepest rate, driven by evolving branding and regulatory demands.
Application:
The profitability margins for bottling line machinery vary significantly across different application segments, influenced by regulatory stringency, product value, and production volumes.
- Beverage:This segment includes machinery for non-alcoholic drinks, carbonated soft drinks, water, and alcoholic beverages, requiring high-speed and flexible lines. Investment in automated beverage lines is strong in Southeast Asia, driven by rising consumer demand and modernization efforts.
- Chemical:Bottling lines for industrial chemicals, lubricants, and household products often require robust, corrosion-resistant materials.
- Pharmaceutical:Equipment for sterile filling and packaging of medicines, vaccines, and other healthcare products demands extreme precision and compliance with cGMP standards. Manufacturers in the United States prioritize advanced pharmaceutical lines to meet stringent FDA regulations and ensure product safety.
- Food:This application covers machinery for sauces, edible oils, dairy products, and preserves, focusing on hygiene and product integrity.
Beverage applications represent the largest volume concentration, while Pharmaceutical applications command the highest value per unit of equipment.
Technology:
The technological maturity of bottling line systems dictates their adoption rates and suitability across varying production scales and labor cost environments.
- Automatic:Fully automated systems operate with minimal human intervention, integrating filling, capping, and labeling into a continuous, high-speed process. Chinese food and beverage producers heavily invest in automatic lines to enhance operational efficiency and mitigate rising labor expenses.
- Semi-Automatic:These machines require some operator involvement for tasks like loading or unloading containers, balancing cost-effectiveness with increased throughput. Craft beverage producers in Europe utilize semi-automatic solutions for flexible production runs and lower capital outlay.
- Manual:Hand-operated or simple machines are suitable for very low-volume production or specialized artisanal products.
- Hybrid:These systems combine elements of automatic and semi-automatic technologies, offering flexibility for diverse production needs.
Automatic technology dominates the market for mass production, while Semi-Automatic systems serve critical niche applications requiring flexibility.
End User:
The concentration of demand from specific end-user segments significantly influences machinery design, service requirements, and market penetration strategies for equipment suppliers.
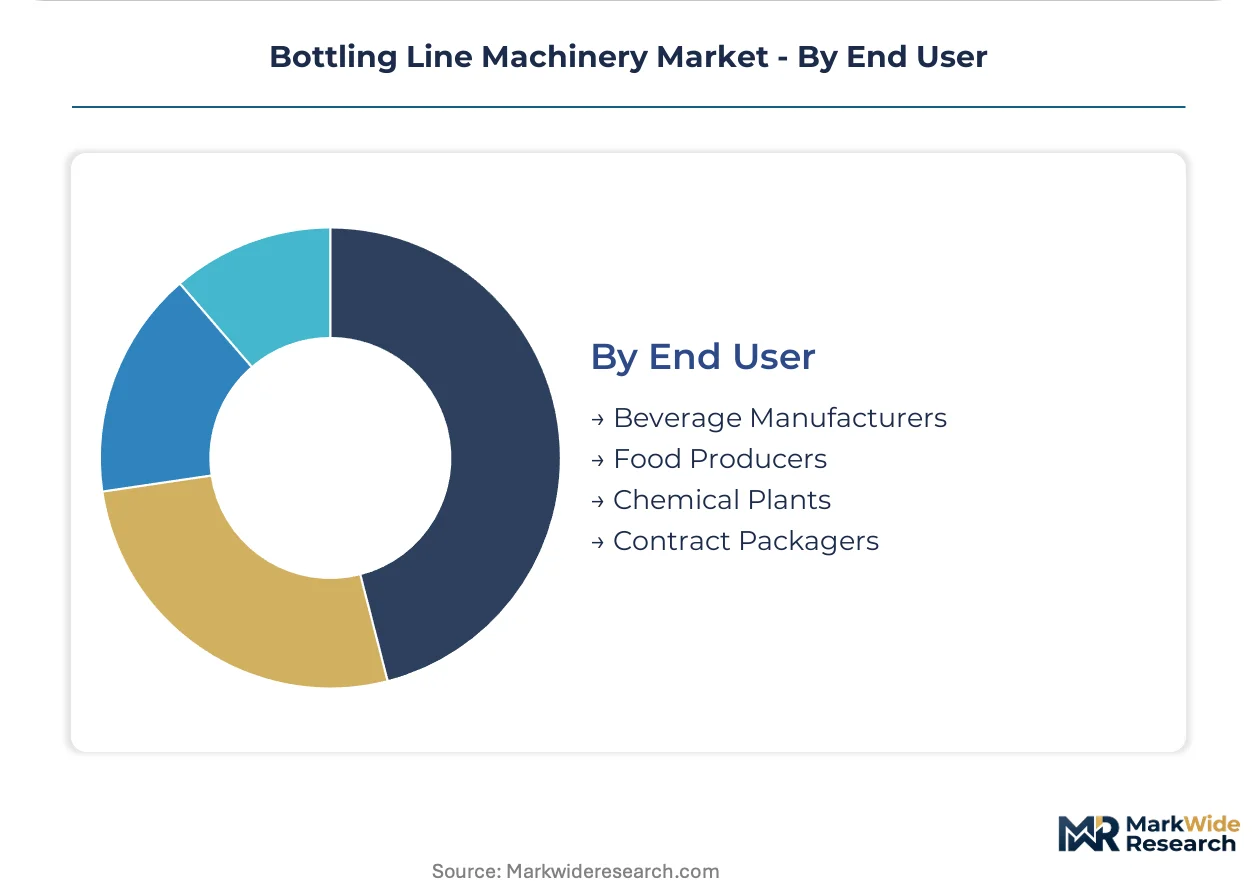
- Beverage Manufacturers:These companies produce a wide array of drinks, demanding high-speed, reliable, and adaptable bottling lines for diverse container formats. Major beverage corporations in Brazil continuously upgrade their lines to meet escalating consumer demand and competitive pressures.
- Food Producers:Manufacturers of various food products require bottling lines adhering to strict hygiene and safety standards for viscous and particulate-laden items.
- Chemical Plants:Facilities producing industrial chemicals, lubricants, and other non-food liquids need robust, often explosion-proof, bottling equipment.
- Contract Packagers:Third-party firms provide packaging services for multiple brands, requiring highly flexible and versatile machinery capable of rapid changeovers. European contract manufacturers prioritize adaptable equipment to service diverse client portfolios and reduce capital expenditure.
Beverage Manufacturers represent the largest segment in terms of installed base, with Contract Packagers demonstrating the most specialized growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bottling line machinery market exhibits varied consumption patterns globally, with some regions prioritizing high-speed automation while others focus on flexible, smaller-scale solutions. China's industrialization drives significant investment in fully automatic systems, contrasting with Europe's emphasis on regulatory compliance and specialized applications. This regional divergence shapes equipment demand and technological adoption across diverse markets.
China
China's rapidly expanding food and beverage sector demands high-speed automated bottling lines to meet consumer needs. The country's GB standards for food safety influence hygienic design and material selection in new equipment. Investment concentrates in industrial hubs like the Yangtze River Delta, where producers upgrade facilities to enhance output.
United States
American pharmaceutical manufacturers prioritize advanced bottling lines for sterile filling, driven by stringent FDA regulations for product safety. The Food Safety Modernization Act (FSMA) mandates robust clean-in-place capabilities for food contact surfaces. Biotech clusters in Massachusetts and California adopt specialized machinery for high-value applications.
Germany
German beverage producers adopt advanced labeling machines to accommodate diverse packaging formats and comply with EU CE marking requirements. The European Union's Packaging and Packaging Waste Regulation (PPWR) influences machinery design for processing recycled PET. Bavaria's strong manufacturing base supports innovation in precision engineering for bottling solutions.
Brazil
Brazilian beverage manufacturers continuously upgrade their bottling lines to meet escalating consumer demand for non-alcoholic drinks and competitive pressures. ANVISA regulations for food and beverage processing dictate equipment hygiene and material standards. São Paulo's industrial park serves as a major hub for bottling line installations and service centers.
Vietnam
Vietnamese food and beverage companies modernize bottling infrastructure to serve a growing middle class and rising beverage demand. The country's Ministry of Health (MOH) sets standards for food contact materials and hygiene in processing equipment. Ho Chi Minh City sees significant investment in automated lines for mass-market production.
Bottling Line Machinery Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure for bottling line machinery. This tiered environment includes global full-line suppliers, specialized component manufacturers, and regional integrators. Strategic archetypes encompass those focused on high-speed turnkey solutions and others emphasizing modular, flexible systems for niche markets. Dominant competitive moves include strategic partnerships for digital integration and continuous portfolio diversification to address evolving packaging needs.
Within the high-speed, integrated systems segment, Krones AG, a German-based Aktiengesellschaft, exemplifies manufacturers providing comprehensive solutions for major beverage producers. ProMach, an American company, represents a diverse portfolio approach, offering specialized machinery across various packaging functions. Syntegon Technology GmbH, another German-based GmbH, occupies a position leveraging pharmaceutical-grade filling expertise for high-value, precision-driven applications. These entities anchor distinct market approaches, from mass production scale to specialized, hygienic processing.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| ProMach |
| Krones AG |
| Sacmi Imola S.C. |
| GEA Group |
| KHS GmbH |
| Coesia S.p.A. |
| Barry-Wehmiller Group |
| Tetra Laval Group |
| Others |
Cost & Logistics Intelligence
The shift to recycled PET (rPET) for bottling reshapes both the geographic sourcing of raw materials and the pricing economics for adaptive machinery.
Pricing Analysis
Long-term project-based contracts dominate pricing for fully integrated bottling lines, contrasting with more transactional models for standalone units. Customization level and after-sales service drive price differentiation, particularly for specialized pharmaceutical equipment. Pricing softness stems from intense competition among modular solution providers for craft beverage producers. Small to mid-sized enterprises exhibit the highest price sensitivity, while pharmaceutical manufacturers are least sensitive.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized electronics from Asian trade lanes, influence the supply chain for bottling line machinery. Germany, the United States, and Italy represent key supply concentrations for equipment manufacturing. Reliance on specialized electronics, such as PLCs, creates a structural risk of component supply volatility. Distribution runs through direct sales channels for integrated systems and via distributor networks for modular equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottling line machinery market presents a fragmentation opportunity, driven by the craft beverage industry's demand for specialized, adaptable filling solutions.
For Market Incumbents: Secure market share against modular specialists by accelerating R&D into AI-powered predictive maintenance platforms. Invest in digital integration capabilities to counter the threat from emerging software-driven solutions. Expand capacity in Southeast Asia to address rising consumer demand, leveraging economies of scale. Develop modular solutions to appeal to flexible production needs, mitigating competitive pressure.
For New Entrants and Emerging Players: Anchor in niche applications like specialized filling lines for alternative beverages, leveraging flexible, semi-automatic solutions. Target the underpenetrated craft beverage segment in Europe with adaptable equipment. Focus on service-based procurement models to lower initial capital outlay for small producers. Emphasize hygienic design for plant-based milks, a high-growth white-space target.
For Investors and Strategic Acquirers: The market sits at a modernization phase that favors technology-forward specialists capable of digital integration. Long-term viability remains strong due to continuous beverage consumption and automation needs. Acquisition targets include vertically integrated mid-cap specialists with robust software and mechatronics expertise. The adoption rate of smart sensors and digital twin technologies serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Integration | Enhances operational efficiency for beverage manufacturers through seamless factory management systems. |
| Modular System Development | Addresses the craft beverage industry's demand for flexible and scalable production lines. |
| AI-Powered Maintenance | Reduces downtime for pharmaceutical producers, ensuring continuous high-value operations. |
| rPET Processing Adaptation | Ensures compliance with EU PPWR regulations for non-alcoholic beverage packaging. |
| Southeast Asia Capacity Expansion | Capitalizes on rising consumer demand and infrastructure modernization in Vietnam. |
Research Approach
The analysis maps filling, capping, and labeling machinery sub-sectors, each validated through primary interviews with plant managers and procurement leads. Stakeholders include R&D directors at equipment OEMs and contract packagers. Secondary validation draws from industry association reports, patent databases, company financial filings, and regulatory body publications like FDA and EFSA. Both bottom-up and top-down triangulation methods were applied.
Forecast outputs were validated against external benchmarks, including industry production statistics and regional economic growth projections. The analytical framework modeled segmentation dimensions across product type, application, technology, end user, and regional adoption patterns. CAGRs were derived from historical trends, projected technology adoption rates, and relevant macroeconomic indicators across the analysis window. Key forecast inputs included beverage consumption trends and labor cost indices.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory frameworks and consistent component supply. Material deviation in geopolitical stability or sudden shifts in packaging material preferences would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Food Processing Machinery Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Pizza Preparation Refrigerator Market