
 US Webtoons Market | 2026-2036
US Webtoons Market Size, Share, and Industry Trends Forecast 2026-2036
US Webtoons Market Insights
High-definition panel optimization and creator revenue-sharing tiers is unwinding legacy comic distribution economics in the United States. NAVER WEBTOON Ltd. dominates the vertical-scroll infrastructure with proprietary rendering engines that reduce load latency. Tapas Media leverages its freemium-to-subscription pipeline to sustain creator retention. Lezhin Entertainment specializes in mature-genre paywalls that anchor premium ARPU segments.
Webtoons constitute digitally native sequential art delivered through server-rendered vertical scroll architectures optimized for smartphone aspect ratios, typically employing infinite canvas mechanics and compressed image streaming to minimize bandwidth overhead. The format's primary commercial purpose centers on capturing fragmented mobile attention spans through episodic release cadences that convert casual readers into recurring subscribers. Fantasy and romance genres lead volume consumption among teens and young adults, where ad-supported models capture entry-level engagement before funneling users toward subscription tiers. Pay-per-episode mechanics within mature-audience horror and action verticals concentrate margin pools where completion rates justify premium unit pricing.
The FTC monitors native advertising disclosures and in-app purchase transparency for platforms targeting minors, while COPPA compliance obligations shape data collection boundaries for children-oriented content tiers. California's CCPA adds state-layer privacy constraints on reader behavioral tracking that underpins targeted ad monetization. Stakeholders must weigh platform investment against creator-side IP ownership terms as the regulatory environment tightens around digital content labor classifications.
Market Dynamics
Server-rendered vertical scroll architectures are compressing legacy comic distribution timelines, forcing publishers to restructure creator contracts around mobile-first episodic release cadences rather than print-volume economics.
Growth Catalysts
- California CCPA data monetization:Platforms leveraging first-party reader behavioral data under tightened privacy constraints unlock targeted ad inventory that sustains freemium-to-subscription funnels.
- Smartphone aspect ratio standardization:Infinite canvas mechanics optimized for 9:19.5 displays reduce production friction for independent creators entering the format.
- Young adult mobile fragmentation:Episodic release cadences capturing 18-34 year-old attention spans convert casual scrollers into recurring subscribers through push-notification retention loops.
Market Restraints
- COPPA data collection boundaries:FTC enforcement restricts behavioral tracking for minors, compressing ad-targeting precision on youth-facing content tiers and forcing reliance on contextual rather than personalized inventory.
- Creator IP ownership concentration:Platform-side terms concentrating derivative rights in publisher hands deter established comic artists from migrating exclusive catalogs.
- Bandwidth compression ceilings:Image streaming optimization hits diminishing returns on rural 4G networks, limiting addressable audience expansion outside metropolitan fiber corridors.
Strategic Opportunities
- Texas entertainment-tech corridor:Austin's lower operational costs and state tax incentives attract secondary platform headquarters seeking relief from California's regulatory density.
- Mature-genre paywall mechanics:Completion-rate data in horror and action verticals justifies premium per-episode pricing models currently underexploited by ad-dependent competitors.
- FTC native advertising disclosure frameworks:Early compliance with evolving influencer-marketing transparency rules positions platforms for brand partnership expansion as traditional display advertising faces scrutiny.
Industry Challenges
- Sequential art talent pipeline gaps:Training programs for vertical-scroll composition and motion-panel scripting lag behind platform demand, forcing costly in-house academy investments.
- Revenue-sharing tier complexity:Negotiating creator contracts across ad-supported, subscription, and pay-per-episode models generates administrative overhead that scales nonlinearly with catalog expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Webtoons Market |
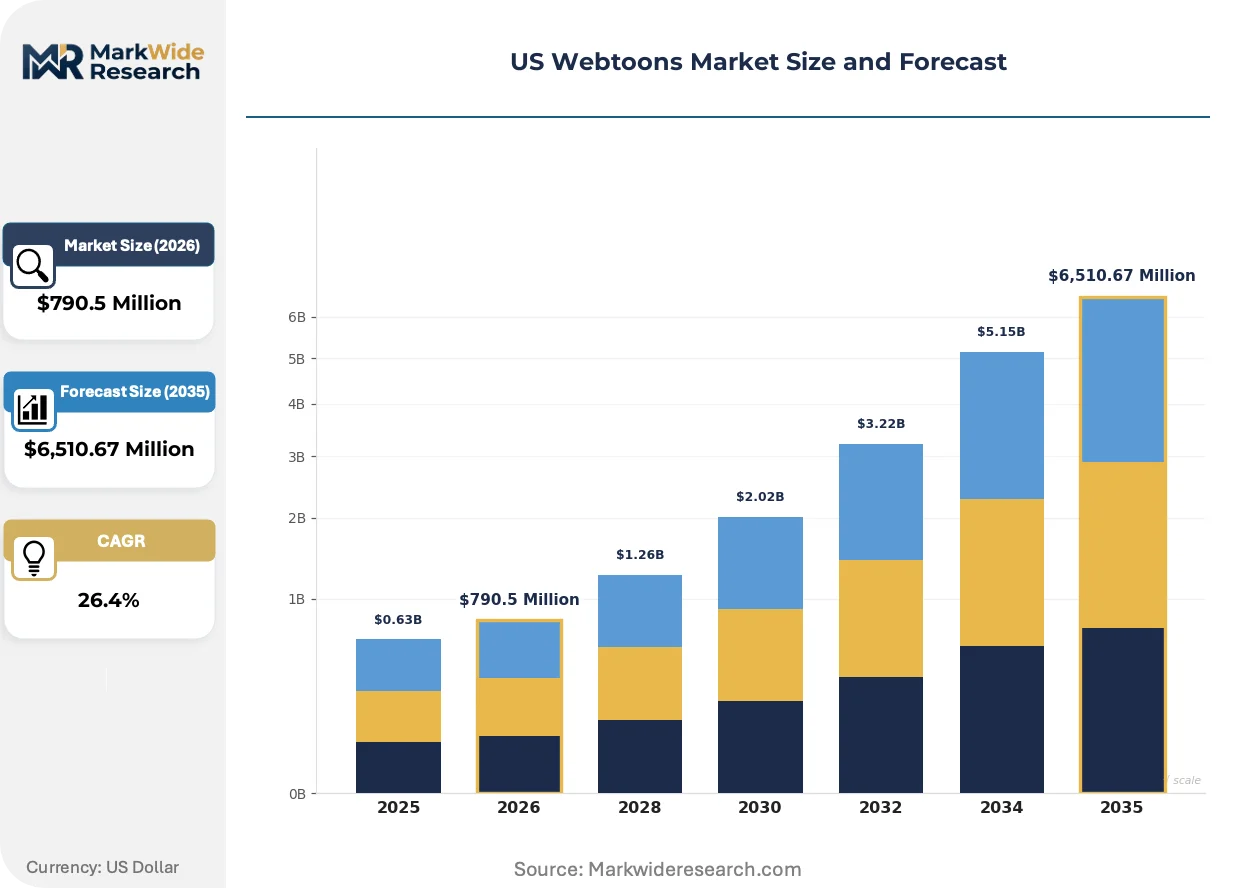
| Market Size in 2026 | $790.5 Million |
| Market Size in 2035 | $6,510.67 Million |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: Vertical Scroll, Horizontal Scroll, Webcomic, Manga Style Genre: Fantasy, Romance, Action, Horror Monetization Model: Subscription, Ad-Supported, Freemium, Pay-per-episode Target Audience: Teens, Young Adults, Adults, Children |
| Companies Covered | Lezhin Entertainment, Tappytoon, NAVER WEBTOON Ltd., Toomics Global, INKR, Kakao Entertainment, MANTA, Pixiv, Tapas Media, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Webtoons Market Trends and Innovations
Compression algorithms and AI-assisted panel layout tools are restructuring production economics, enabling smaller creator teams to match output volumes previously requiring studio infrastructure.
Proprietary rendering engines optimized for sub-100ms load latency are displacing generic content delivery networks in platform competitive positioning. Publishers adopting these architectures retain readers who abandon titles during buffering intervals. The displacement compresses infrastructure vendor margins while rewarding in-house engineering investment.
FTC guidance on in-app purchase transparency for minors is tightening disclosure requirements around freemium conversion mechanics. Platforms must now surface total episode costs before reader commitment, altering funnel design toward subscription-first rather than microtransaction-heavy models. California-based publishers face the earliest compliance deadlines under state-level consumer protection layering.
Reader procurement patterns are fragmenting across platform-exclusive titles rather than consolidating around multi-publisher aggregators. Subscription fatigue drives churn toward single-franchise loyalty programs with early-access perks. This behavioral shift concentrates marketing spend on individual IP promotion rather than platform brand building, most visible in New York's media publishing cluster where creator-owned studios command premium licensing terms.
US Webtoons Market Segmentation
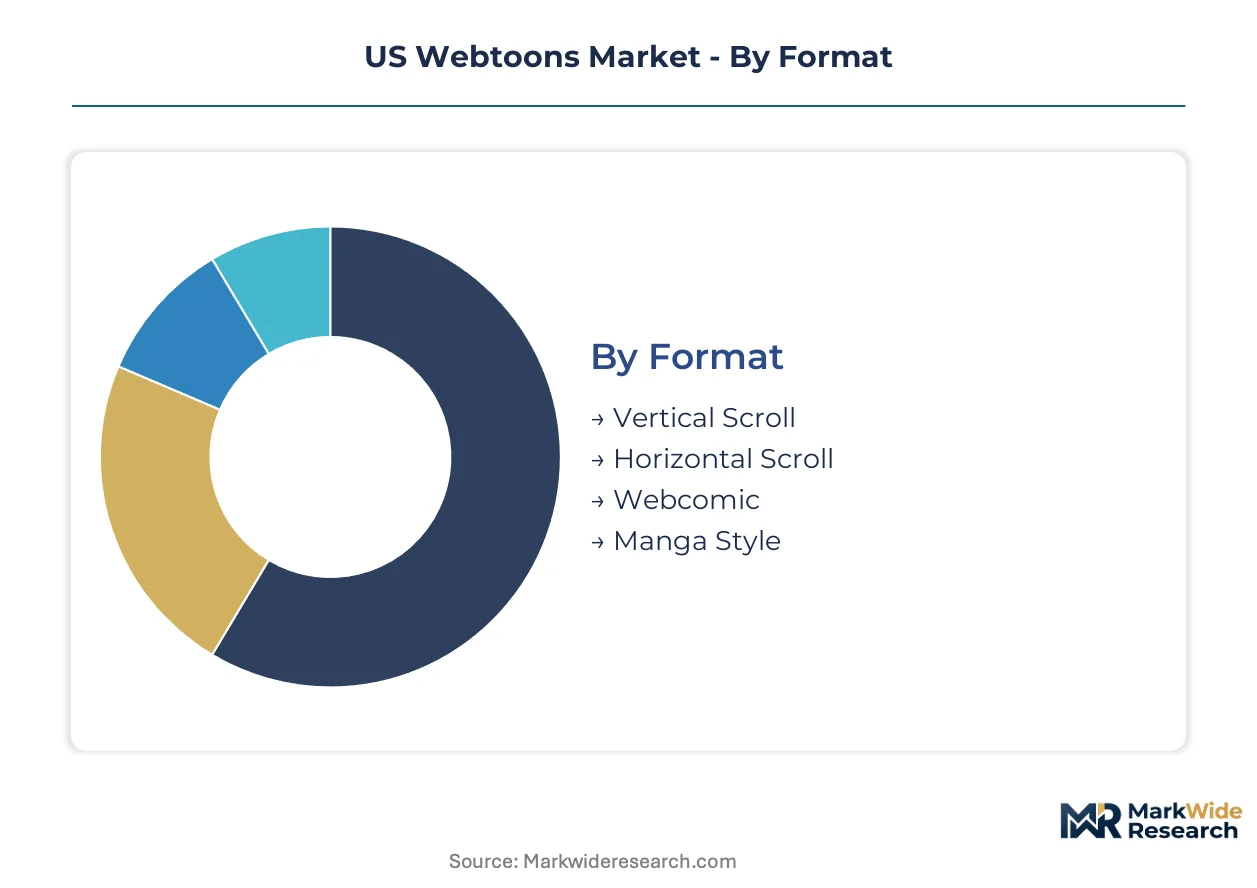
Webtoons segmentation reveals how platform economics bifurcate between mass-market ad inventory and premium subscriber monetization. Each dimension carries distinct FTC compliance obligations and production cost structures that reshape creator contract negotiations across the United States.
Format:
FTC disclosure requirements vary sharply by scroll architecture, with vertical formats facing stricter native advertising scrutiny due to immersive engagement mechanics that blur sponsored content boundaries.
- Vertical Scroll:Infinite canvas mechanics optimized for 9:19.5 smartphone displays compress bandwidth through server-side image tiling. California's entertainment-tech corridor concentrates engineering talent for proprietary rendering engines that sub-100ms load latency demands.
- Webcomic:Traditional panel layouts repurposed for mobile consumption carry lower production overhead but face stiffer competition from established print-digital hybrids. New York's media publishing cluster hosts migration pipelines for legacy comic artists adapting to episodic release cadences.
- Horizontal Scroll:Landscape-oriented sequential art serves tablet-dominant readers with larger screen real estate for detailed artwork.
- Manga Style:Right-to-left reading patterns imported from Japanese publishing conventions attract established fan communities.
Vertical Scroll handles the majority of throughput; Webcomic is the fastest mover on share as legacy publishers accelerate mobile adaptation.
Genre:
Content classification determines COPPA applicability thresholds, with fantasy and romance titles skirting stricter minor-facing data collection restrictions than horror verticals targeting adult demographics.
- Romance:Episodic cliffhanger structures maximize push-notification retention loops among 18-34 year-old readers. Completion-rate data from this segment justifies premium subscription tiering that ad-supported competitors struggle to match.
- Horror:Mature-audience paywalls anchor the highest ARPU segments through per-episode pricing mechanics. Texas entertainment-tech corridor platforms exploit this vertical's lower regulatory scrutiny to test aggressive monetization experiments.
- Fantasy:World-building density demands larger creative teams but sustains longer reader lifecycles through franchise extension opportunities.
- Action:Motion-panel scripting requirements strain talent pipelines trained in static composition techniques.
Romance commands the largest addressable audience; Horror is climbing the fastest on revenue per user metrics.
Monetization Model:
Revenue architecture selection constrains platform growth trajectories, with California's CCPA layering additional privacy compliance costs onto behavioral-targeting dependent models.
- Freemium:Tiered access gates convert casual scrollers through time-delayed episode unlocks balanced against subscription bypass options. This model concentrates in platforms with sufficient catalog depth to sustain reader patience through wait-time mechanics.
- Ad-Supported:Contextual inventory replaces behavioral targeting for minor-facing content tiers under COPPA enforcement, compressing CPM rates but preserving reach among teens where subscription penetration lags.
- Subscription:All-access catalogs compete for wallet share against streaming video services with overlapping demographic targets.
- Pay-per-episode:Unit economics favor completed series with demonstrated completion rates that justify premium pricing without subscription commitment friction.
Freemium captures the widest user base; Pay-per-episode is gaining share fastest among mature-genre specialists.
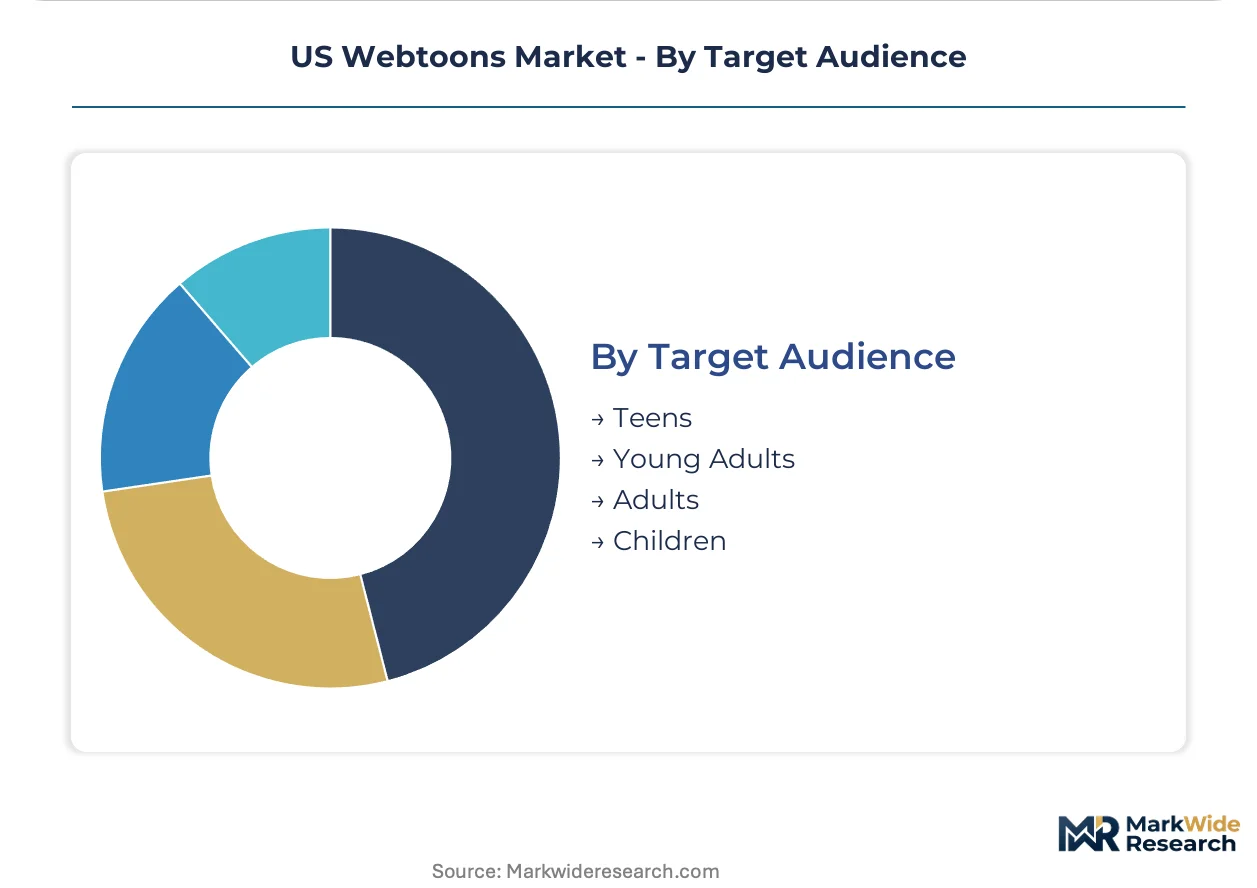
Target Audience:
Age-band targeting triggers distinct regulatory frameworks, with FTC in-app purchase transparency mandates intensifying for content tiers attracting minors.
- Young Adults:The 18-34 demographic concentrates platform marketing spend through push-notification retention engineering and social sharing mechanics. California and New York media clusters compete for creator talent capable of sustaining episodic output volumes this segment demands.
- Children:COPPA compliance obligations restrict data collection to contextual advertising inventory, forcing reliance on parental consent workflows that increase customer acquisition costs. Platforms serving this tier face earlier FTC disclosure deadlines under state-level consumer protection layering.
- Teens:Transitional regulatory status requires hybrid compliance approaches balancing engagement optimization against minor-protection safeguards.
- Adults:Mature content paywalls escape COPPA constraints but face narrower addressable markets and higher content production standards.
Young Adults generates the dominant share of platform revenue; Children is expanding most quickly as educational content publishers enter the format.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent clusters along three distinct corridors, with each concentration feeding different monetization specializations and regulatory exposure profiles across the United States.
California
Los Angeles and San Francisco anchor the dominant engineering pipeline for proprietary rendering engines. The state's CCPA imposes first-party data constraints that reshape behavioral targeting economics for freemium platforms. Santa Monica studios concentrate fantasy and romance production teams serving young adult demographics.
New York
Manhattan and Brooklyn host legacy comic publisher migration pipelines adapting print-digital hybrids to mobile-first formats. The state's consumer protection layering adds disclosure requirements beyond federal FTC baselines for in-app purchase transparency. Queens-based creator collectives negotiate premium IP ownership terms with platform distributors.
Texas
Austin's lower operational costs attract secondary platform headquarters seeking relief from California regulatory density. State tax incentives for entertainment-tech ventures support mature-genre paywall experiments outside COPPA-intensive youth tiers. Dallas-Fort Worth corridors test bandwidth compression optimization for rural 4G network expansion.
Washington
Seattle's cloud infrastructure ecosystem supplies server-rendered vertical scroll architectures to distributed creator networks. State privacy legislation mirrors California's constraints on reader behavioral tracking for ad inventory. Bellevue engineering offices optimize image streaming protocols for Pacific Northwest fiber corridor speeds.
Georgia
Atlanta's emerging animation pipeline feeds motion-panel scripting demand for action and horror verticals. State film production incentives extend to digital content studios establishing satellite operations. Savannah technical institutes train vertical-scroll composition specialists for platform talent pipeline gaps.
US Webtoons Market Competitive Landscape
Concentration sits with vertically integrated platform publishers controlling proprietary rendering infrastructure. The competitive structure tiers between infrastructure owners, freemium-to-subscription intermediaries, and mature-genre paywall specialists. Three archetypes dominate: Korean-origin platform parents with captive technology stacks, US-based creator-aggregation intermediaries, and niche specialists in adult-demographic monetization. Dominant competitive moves include creator contract restructuring around episodic release economics and geographic headquarters relocation to optimize regulatory exposure.
Within the Korean-origin infrastructure tier, NAVER WEBTOON Ltd. and Kakao Entertainment exemplify platform parents with captive rendering technology. Tapas Media occupies a position among US-based intermediaries leveraging freemium conversion pipelines. Lezhin Entertainment anchors the mature-genre paywall archetype with specialized adult-audience monetization mechanics.
| Leading Market Players |
|---|
| Lezhin Entertainment |
| Tappytoon |
| NAVER WEBTOON Ltd. |
| Toomics Global |
| INKR |
| Kakao Entertainment |
| MANTA |
| Pixiv |
| Tapas Media |
| Others |
Pricing and Supply Chain Analysis
Server-rendered vertical scroll architectures compress creator-to-reader lead times from months to days, concentrating pricing power with platforms that own proprietary rendering infrastructure while fragmenting margin capture across ad-supported, subscription, and pay-per-episode tiers. This compression feeds back into supply chain choices, incentivizing in-house engineering investment over third-party CDN reliance.
Pricing Analysis
FTC in-app purchase transparency mandates dictate the pricing tier structure across youth-facing content, forcing subscription-first models that surface total episode costs upfront rather than microtransaction-heavy funnels. Price differentiation hinges on completion-rate data quality and proprietary rendering engine ownership, with mature-genre paywalls commanding premium positioning against ad-dependent competitors. Pricing pressure intensifies downward on freemium tiers as COPPA enforcement compresses behavioral-targeting CPMs and contextual inventory underperforms. Subscription buyers exhibit lowest price sensitivity, while teen-facing ad-supported segments face acute churn risk from wait-time mechanics.
Supply Chain Analysis
Container availability fluctuations on Trans-Pacific lanes from South Korea and Japan disrupt proprietary rendering engine hardware shipments and cloud infrastructure expansion timelines for US platform headquarters. Creator talent supply concentrates in South Korea, Japan, and domestic California-New York corridors, with sequential art training programs lagging platform demand. Raw material dependencies span cloud compute capacity, mobile device display panels, and compression algorithm licensing. Supply chain risk centers on single-source vulnerability for Korean-origin platform parents controlling captive technology stacks. Distribution runs through app store gatekeepers and direct-to-reader mobile web channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward creator-owned studios as platform-exclusive IP fragmentation concentrates marketing spend on individual franchises rather than aggregator brands. This consolidation among content suppliers elevates negotiating leverage for established artists with demonstrated completion-rate performance.
For Market Incumbents: Fortify proprietary rendering infrastructure through in-house engineering retention and sub-100ms load latency optimization that generic CDNs cannot replicate. Deepen backward integration into creator academy pipelines to address sequential art talent gaps. Defend against emerging pay-per-episode specialists by accelerating mature-genre catalog expansion before niche platforms anchor premium ARPU segments. For New Entrants and Emerging Players: Anchor in Texas entertainment-tech corridors where state tax incentives and lower operational costs offset California regulatory density. Target horror and action verticals where completion-rate data justifies premium unit pricing and COPPA scrutiny remains minimal. Pursue direct creator IP ownership terms as the primary go-to-market angle to differentiate from platform-side rights concentration. For Investors and Strategic Acquirers: Carve-out targets emerge from Korean-origin platform parents seeking to monetize non-core US creator networks. Long-term viability hinges on regulatory arbitrage positioning between state-level privacy constraints and federal FTC enforcement timelines. Monitor FTC native advertising disclosure rulemaking as the key inflection signal for brand partnership expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Rendering Engine Development | Sub-100ms load latency retention displaces generic CDN dependence and compresses infrastructure vendor margins. |
| Creator Academy Pipeline Investment | In-house vertical-scroll composition training addresses talent scarcity forcing costly competitive poaching. |
| Texas Headquarters Relocation | State tax incentives and reduced regulatory density attract secondary platform operations from California. |
| Mature-Genre Paywall Expansion | Horror and action completion-rate data justifies premium per-episode pricing outside COPPA-intensive tiers. |
| FTC Compliance-First Architecture | Early native advertising disclosure frameworks position platforms for brand partnership expansion as display advertising faces scrutiny. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across platform engineering executives, creator contract negotiators, mobile advertising operations leads, and regulatory compliance officers. Secondary validation drew from SEC filings of publicly traded platform parents, FTC enforcement action databases, CCPA regulatory guidance documents, and app store revenue disclosure patterns. Bottom-up creator economics modeling and top-down platform revenue aggregation were triangulated to cross-validate segment sizing.
Across the analysis window, forecasts integrated format-specific adoption curves, genre-based monetization rate differentials, and regional regulatory cost layering. Segmentation dimensions spanned scroll architecture, content classification, revenue model, and age-band targeting with state-level compliance burden weighting. CAGRs were derived from platform-reported subscriber conversion benchmarks and ad inventory yield trajectories. Inputs included proprietary rendering engine deployment timelines and COPPA enforcement intensity indices.
Material uncertainties — FTC rulemaking finalization, creator talent pipeline expansion rates, and bandwidth compression ceiling breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about young adult mobile fragmentation persistence and subscription fatigue thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Transport Media Market
Digital Media
Mobile Entertainment Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Media and Entertainment Market
Digital Media
Volumetric Video Market
Digital Media
Cognitive Media Market
Digital Media
Digital Media Switchers Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Da Vinci Systems Market
Digital Media
Digital Content Locker Market
Digital Media
Video Player Market
Digital Media
Anime Market
Digital Media
Europe Animation Market
Digital Media
4K Content Market
Digital Media
Sports Graphics Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market