
 Da Vinci Systems Market | 2026-2036
Da Vinci Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Da Vinci Systems Market Intelligence
The increasing emphasis on software-defined features and long-term service contracts is repositioning the core offering from a one-time capital equipment sale to a recurring revenue platform. Intuitive Surgical dominates this integrated model, leveraging its extensive installed base and proprietary instrument ecosystem. Competitors such as Johnson & Johnson and Medtronic compete by developing robotic platforms that integrate with their broad portfolios of surgical devices and digital health tools.
A Da Vinci system is a robotic-assisted surgical platform designed to facilitate complex procedures using a minimally invasive approach. It consists of a surgeon's console for control, a patient-side cart with multiple interactive robotic arms, and an endoscopic 3D high-definition vision system. While the initial sale of Robotic Surgical Systems forms the capital base, the market's value is increasingly driven by high-margin, consumable Instrumentation and Accessories. Urology represents a mature application segment, whereas general surgery and cardiothoracic surgery are areas of rapid procedural expansion.
Regulatory bodies such as the US FDA, the NMPA in China, and European authorities enforcing the MDR for CE marking govern market entry. These agencies mandate extensive clinical trials and define the approved surgical applications, creating high barriers to entry for new systems. Consequently, navigating the evolving landscape of data privacy regulations, including HIPAA and GDPR, will be critical for vendors developing next-generation, data-driven surgical platforms.
Market Dynamics
The central structural force shaping the market is the pivot from one-time capital equipment sales to a recurring revenue model. This shift is driven by the increasing integration of software-defined features and long-term service contracts for instruments and accessories.
Growth Catalysts
- Expanded Regulatory Approvals:The continuous clearance of new surgical procedures by bodies like the US FDA validates the technology's clinical efficacy and safety, opening new application areas and driving procedural volume growth in segments such as gynecology.
- Demand for Minimally Invasive Procedures:Patients and providers increasingly prefer minimally invasive surgery due to benefits like reduced recovery time and lower complication rates, directly fueling adoption of robotic-assisted platforms that enable such approaches.
- Infrastructure Development:The establishment of specialized surgical centers, particularly in the United States, creates concentrated hubs of demand and expertise, which accelerates the adoption and refinement of advanced robotic surgical technologies.
Market Restraints
- High Capital Investment:The substantial upfront cost of acquiring a robotic surgical system, often running into millions of dollars, remains a significant barrier to adoption for smaller hospitals and healthcare facilities with limited capital budgets.
- Proprietary Ecosystem Lock-in:The design of systems requiring proprietary instruments and accessories creates vendor lock-in, limiting a hospital's purchasing flexibility and bargaining power over the long-term cost of consumables and service.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy approval processes mandated by agencies such as the FDA in the US, NMPA in China, and European authorities for CE marking creates high barriers to entry for new competitors.
Strategic Opportunities
- Expansion into New Surgical Specialties:While urology is a mature segment, significant white space exists in applying robotic systems to general, cardiothoracic, and orthopedic surgery, representing major avenues for procedural volume growth.
- Geographic Market Penetration:Untapped demand in markets across Asia and Latin America presents a substantial opportunity for expansion, contingent on navigating local regulatory pathways and adapting to regional healthcare economics.
- Integration of AI and Data Analytics:The convergence of robotics with artificial intelligence offers opportunities to develop next-generation platforms that provide real-time surgical guidance, performance analytics, and predictive insights to improve patient outcomes.
Industry Challenges
- Surgical Training and Skill Gaps:The effective use of robotic surgical systems requires extensive, specialized training for surgeons and operating room staff, creating an implementation bottleneck and adding to the total cost of ownership for healthcare providers.
- Data Security and Privacy Compliance:As platforms become more connected and data-driven, vendors face the challenge of ensuring robust cybersecurity and compliance with stringent data privacy regulations like HIPAA and GDPR, which govern sensitive patient health information.
- Interoperability with Hospital IT:Integrating robotic surgical platforms with existing hospital information systems, such as electronic health records and picture archiving systems, presents a significant technical and operational challenge for seamless data flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Da Vinci Systems Market |
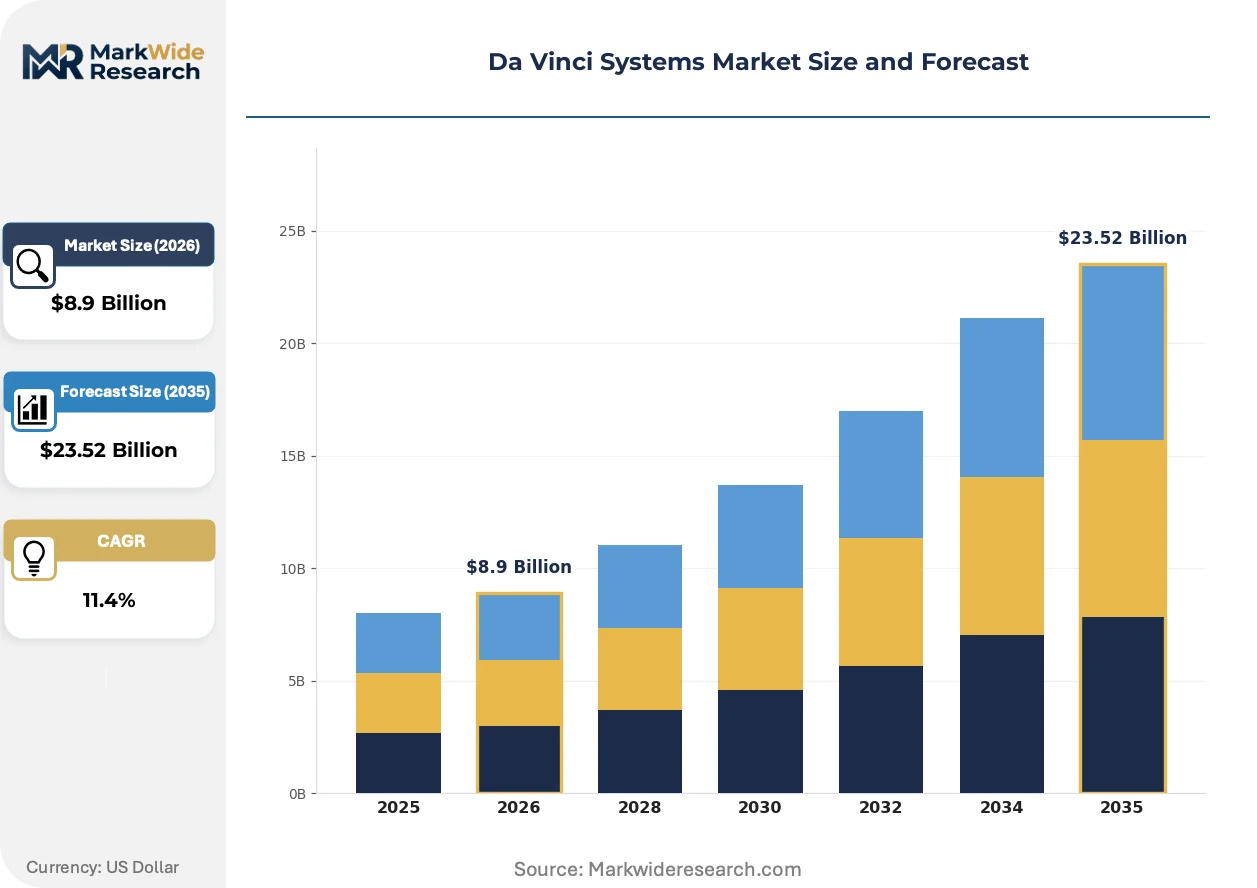
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $23.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Accessories, Imaging Systems, Instrumentation Application: Cardiothoracic Surgery, Urology, Gynecology, General Surgery End User: Hospitals, Surgical Centers, Research Institutions, Academic Medical Centers Technology: MIS, Robotic Arms, Tele-surgery, Haptic Feedback |
| Companies Covered | Intuitive Surgical, Medtronic, Stryker, Johnson & Johnson, Smith & Nephew, CMR Surgical, Karl Storz, Applied Medical, Richard Wolf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Da Vinci Systems Market Strategic Shifts & Innovations
The evolution of robotic surgery is defined by its transformation from a purely mechanical aid into an intelligent, data-integrated ecosystem. This transition is creating new possibilities for surgical precision, training, and workflow efficiency within the operating room.
Miniaturization and modularity are key product innovations. Smaller, single-port robotic platforms are being developed to support less complex procedures and fit within smaller operating spaces. Ambulatory surgery centers and specialized outpatient clinics are early adopters of these more accessible systems. This development is decentralizing robotic surgery capabilities beyond the confines of large, research-focused tertiary hospitals.
Europe's Medical Device Regulation (MDR) represents a significant regulatory shift. It mandates more rigorous clinical evidence and continuous post-market surveillance for all medical devices, including robotic surgical systems. This increases the time and cost required for manufacturers to obtain and maintain CE marking for their products. Both new entrants and established vendors are most affected, as they must invest heavily in long-term data collection to meet these heightened standards.
A notable shift in purchasing behavior involves the move toward flexible, usage-based financial models. The traditional model of a large, one-time capital equipment purchase is being challenged by subscription or "per-procedure" pricing structures. This trend is most visible in the United States, where large hospital networks use these models to manage technology costs and fleet-wide upgrades more predictably across their facilities.
Da Vinci Systems Market Segmentation
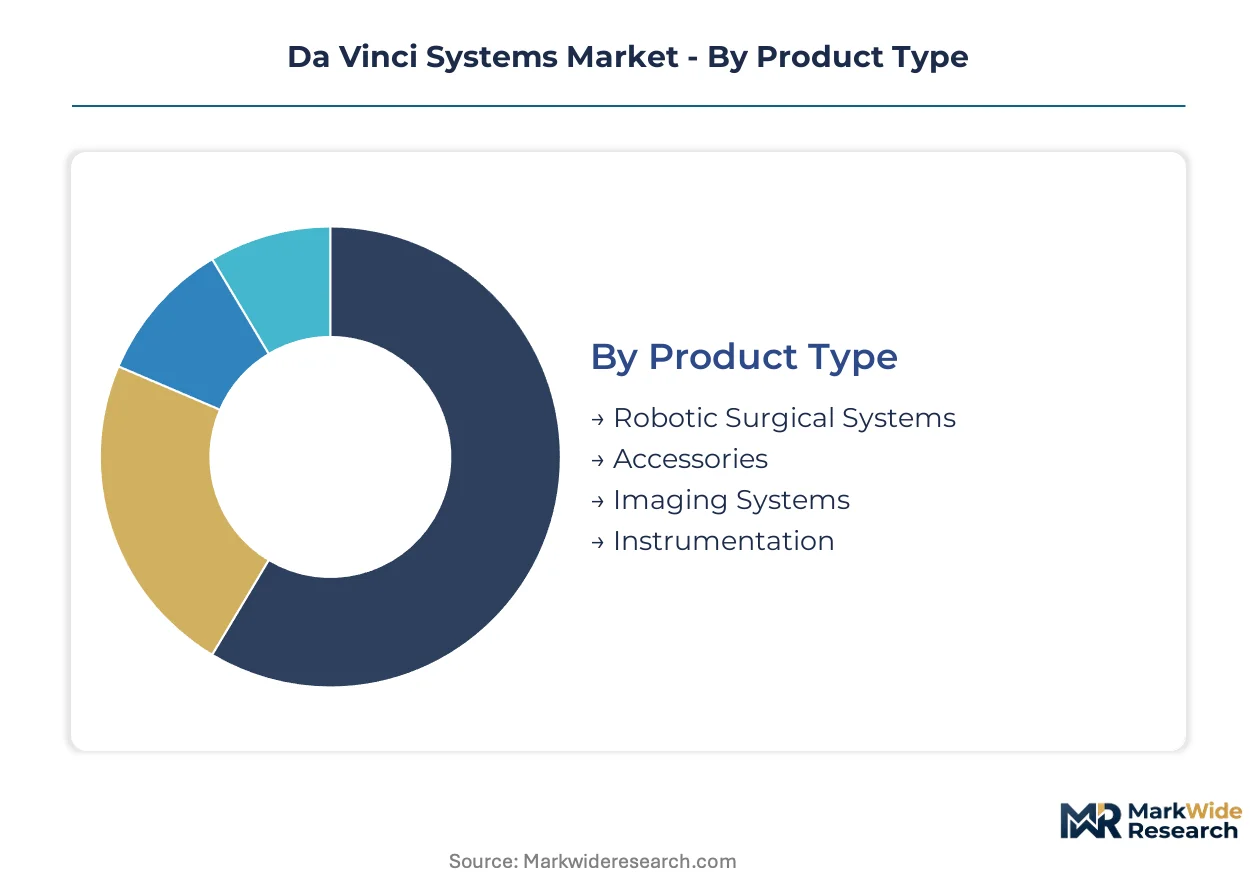
The Da Vinci Systems market's segmentation provides a granular view of its diverse components, highlighting the varied regulatory pathways and commercial dynamics influencing each segment. Understanding these distinctions is critical for strategic market entry and product development across different functional areas.
Product Type:
Manufacturers must navigate stringent regulatory approvals from bodies like the US FDA and European authorities enforcing the MDR for each product type, particularly for novel devices or significant modifications.
- Robotic Surgical Systems:These integrated platforms consist of a surgeon's console, a patient-side cart with robotic arms, and a vision system, facilitating complex minimally invasive procedures. Demand concentrates in specialized surgical centers in the United States, driven by the desire for enhanced precision and improved patient outcomes.
- Instrumentation:These high-margin, consumable tools are specifically designed for use with robotic systems, including scalpels, forceps, and energy devices, requiring continuous resupply. The recurring revenue model for these instruments is a significant commercial driver, especially for established systems with large installed bases.
- Accessories:This segment encompasses various support items such as drapes, trocars, and sterilization trays essential for the operational readiness of robotic surgical procedures. These components face less rigorous regulatory scrutiny than the primary systems.
- Imaging Systems:Providing 3D high-definition visualization, these systems are integral to the surgeon's ability to perform precise movements during robotic-assisted surgery. Enhanced imaging capabilities improve surgical accuracy.
Leading the category by volume: Robotic Surgical Systems. Growing fastest: Instrumentation.
Application:
The application segments vary significantly in terms of procedural volume and the economic value generated from each surgical intervention.
- Gynecology:This segment includes procedures such as hysterectomies and myomectomies, where robotic assistance offers benefits like reduced blood loss and shorter hospital stays. Growth is pronounced as hospitals seek better patient outcomes.
- General Surgery:Covering a broad range of abdominal and thoracic procedures, this segment represents a significant area of rapid procedural expansion for robotic systems. The versatility of robotic platforms allows for their application across diverse complex cases.
- Urology:Procedures like prostatectomies and nephrectomies constitute a mature application segment for robotic surgery, demonstrating established clinical utility and high adoption rates. This segment has historically driven initial robotic system adoption.
- Cardiothoracic Surgery:This segment focuses on procedures involving the heart and lungs, where the precision of robotic systems can minimize invasiveness and improve patient recovery. This area is experiencing rapid procedural expansion.
Demand concentrates in Gynecology due to these systems' ability to enhance patient outcomes. General Surgery shows the steepest expansion trajectory.
End User:
The type of end-user facility dictates procurement patterns, capital investment capacity, and the scale of robotic system deployment.
- Hospitals:These large healthcare institutions represent the primary purchasers of robotic surgical systems, driven by patient demand, physician preference, and the ability to handle high capital investments. Hospitals often acquire multiple systems for various departments.
- Surgical Centers:Specialized outpatient facilities are increasingly adopting robotic platforms, particularly smaller, more modular systems, to expand their procedural offerings. These centers prioritize efficiency and quick patient turnaround.
- Academic Medical Centers:These institutions utilize robotic systems for advanced surgical training, research, and complex cases, often acting as early adopters of new technologies. They contribute to clinical validation and skill development.
- Research Institutions:These organizations employ robotic platforms for experimental surgical techniques, device development, and studying human-robot interaction in medical contexts. Their focus is on innovation rather than routine patient care.
Hospitals account for the largest share of system installations. Surgical Centers demonstrate significant potential for decentralized adoption.
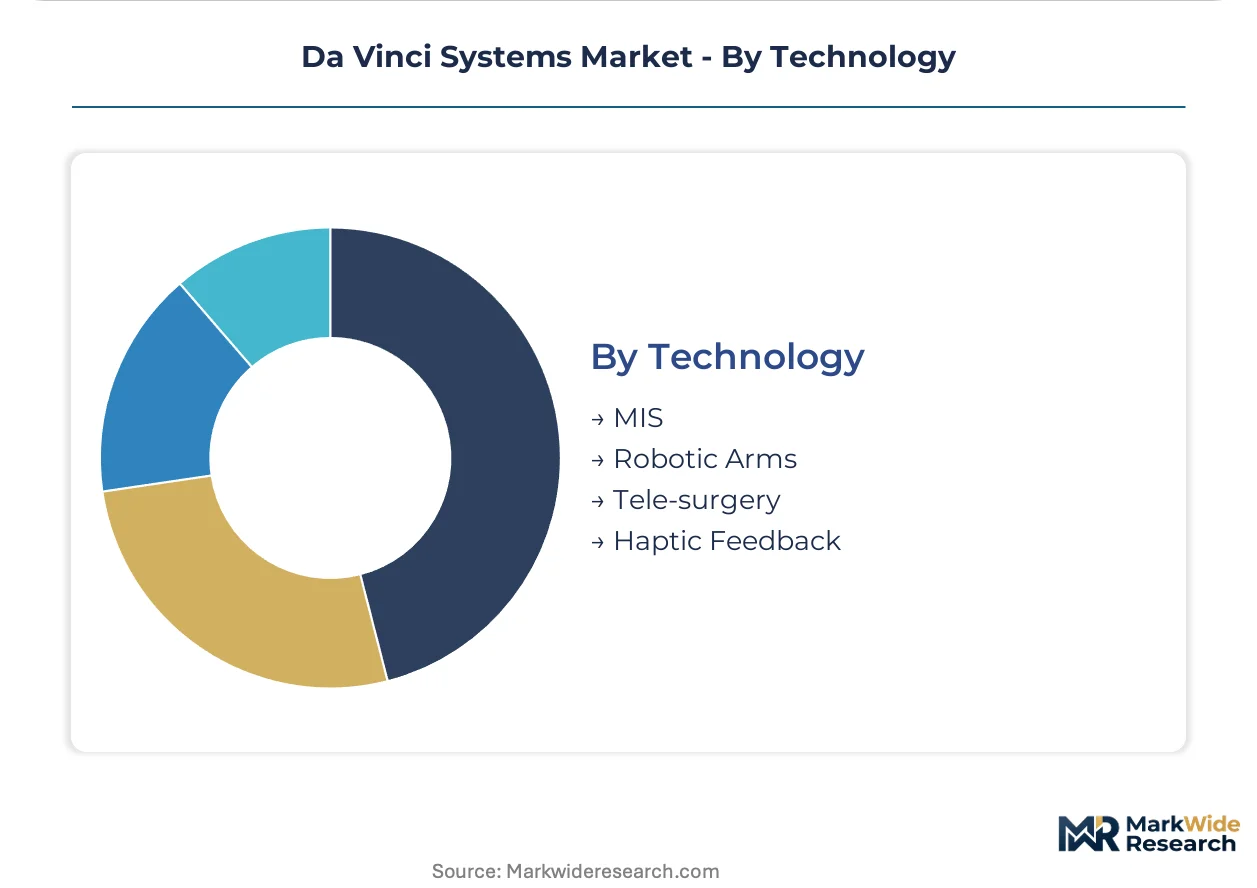
Technology:
Technological advancements drive the evolution of robotic surgery, enhancing precision, expanding capabilities, and improving user experience.
- Robotic Arms:These articulated mechanical components replicate a surgeon's hand movements with enhanced dexterity and tremor filtration, enabling precise tissue manipulation in confined spaces. Miniaturization and increased degrees of freedom are continuous development areas.
- Tele-surgery:This technology enables surgeons to operate remotely, controlling robotic systems over long distances, potentially expanding access to specialized care. Integration with high-speed networks and secure data transmission is critical for its widespread adoption.
- MIS:Minimally Invasive Surgery is the overarching approach that robotic systems facilitate, involving smaller incisions and reduced trauma for patients. Robotic platforms enhance the capabilities of traditional MIS techniques.
- Haptic Feedback:This feature provides tactile sensations to the surgeon's console, simulating the feel of tissue resistance and tension during surgery. Haptic feedback improves the surgeon's sense of control and reduces cognitive load.
The foundational element remains Robotic Arms. Innovation is most pronounced in Tele-surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Da Vinci Systems market exhibits a clear divide between concentrated consumption in advanced healthcare economies and the global innovation hubs driving technological development. Specialized surgical centers in developed nations, particularly the United States, lead in system adoption and procedural volume. This regional disparity influences market entry strategies and regulatory compliance efforts for manufacturers.
United States
Demand for robotic surgical platforms in the United States stems from specialized surgical centers prioritizing enhanced patient outcomes in gynecological and general surgery. The US FDA's continuous expansion of approved procedures validates technology's clinical utility. Major medical technology clusters like Boston and the San Francisco Bay Area drive innovation in robotic platforms and integrated digital health solutions.
Germany
Germany's robust healthcare infrastructure and emphasis on precision medicine fuel the adoption of Da Vinci systems within academic medical centers. European authorities enforcing the Medical Device Regulation (MDR) mandate rigorous clinical evidence for market access. Erlangen and Munich serve as key hubs for medical technology research and development, supporting advanced surgical system deployment.
China
Expanding healthcare access and increasing investment in advanced medical technologies drive demand for robotic surgery in China. The NMPA's regulatory approvals are critical for market entry and local manufacturing partnerships. Shanghai and Shenzhen are emerging as significant centers for medical device innovation and the adoption of cutting-edge surgical platforms.
Japan
Japan's aging population and preference for minimally invasive procedures contribute to sustained demand for robotic surgical systems. The PMDA's stringent approval processes ensure high standards for medical device safety and efficacy. Tokyo's advanced hospital networks and research institutions lead in the integration of robotic surgery with emerging AI capabilities.
United Kingdom
The United Kingdom's National Health Service (NHS) increasingly integrates robotic surgical systems to improve patient recovery times and surgical precision. The MHRA governs medical device approvals, ensuring compliance with post-Brexit regulatory frameworks. London and Cambridge host significant medical research and biotech clusters, fostering innovation in robotic-assisted surgery.
Da Vinci Systems Market Key Industry Players
Top-tier vendors anchor the integrated robotic surgical platform segment, while specialized medical device companies focus on niche applications and component innovation. This market structure features a dominant installed base leader alongside diversified medical technology conglomerates. Strategic archetypes include integrated ecosystem providers and broader surgical device portfolio companies. Dominant competitive moves involve continuous product innovation and portfolio diversification through technology acquisition.
The integrated ecosystem model is exemplified by Intuitive Surgical, which maintains a substantial installed base and proprietary instrument ecosystem. Diversified medical technology conglomerates like Johnson & Johnson and Medtronic represent another key archetype. These companies leverage their extensive portfolios of surgical devices and digital health tools to integrate robotic platforms into a comprehensive offering for healthcare providers.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Smith & Nephew |
| CMR Surgical |
| Karl Storz |
| Applied Medical |
| Richard Wolf |
| Others |
Cost & Logistics Intelligence
Vertical integration by dominant players anchors robust supply positions and enables premium pricing power within the Da Vinci Systems market. This strategy leverages proprietary instrument ecosystems and extensive installed bases.
Pricing Analysis
Margin tightening for smaller hospitals reflects the substantial upfront cost of robotic surgical systems. The dominant pricing model is transitioning from one-time capital equipment sales to a recurring revenue platform, driven by high-margin instrumentation and long-term service contracts. Proprietary instrument ecosystems and software-defined features act as key price differentiation drivers, reinforcing vendor lock-in. Healthcare providers with limited capital budgets exhibit high price sensitivity, while large hospital networks leverage flexible usage-based financial models.
Supply Chain Analysis
Regulatory certification gating, particularly from the US FDA and European authorities enforcing MDR, profoundly shapes the Da Vinci Systems supply chain. High-value component manufacturing and innovation concentrate in the United States, Germany, and Japan, with China emerging for specific sub-components. The industry relies on precision mechanical parts, advanced optical systems, and specialized control electronics. Stringent regulatory approval processes represent a significant structural risk, creating high barriers to entry. Distribution runs through direct sales channels and specialized technical support networks to healthcare institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Da Vinci Systems market is fundamentally a cost-of-compliance story, where stringent regulations like Europe's Medical Device Regulation (MDR) create a significant barrier-to-entry moat. This mandates extensive clinical evidence and continuous post-market surveillance for all medical devices.
For Market Incumbents: Hedge against emerging competitive platforms by continuously investing in software-defined features and AI integration for real-time surgical guidance. Expand long-term service contracts and proprietary instrument ecosystems to reinforce recurring revenue streams. This counters rising competition from diversified medical technology conglomerates like Johnson & Johnson. Focus R&D efforts on advanced imaging capabilities and haptic feedback to maintain a technological lead.
For New Entrants and Emerging Players: Specialized distributors offer a viable go-to-market angle for new entrants seeking to penetrate the Da Vinci Systems market. Target white space in orthopedic surgery or specific general surgery applications not dominated by incumbents. The most penetrable segment involves smaller, modular systems for ambulatory surgery centers and outpatient clinics. Implement flexible, usage-based financial models to overcome high capital investment barriers for healthcare providers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology firms developing advanced AI, haptic feedback, or miniaturized robotic systems. The market demonstrates strong long-term viability, driven by expanding procedural applications and recurring revenue streams. Target acquisition candidates include companies innovating in real-time surgical guidance or data analytics for surgical platforms. The pace of regulatory approvals for new robotic surgical procedures by agencies like the US FDA serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Product Innovation | Enhances surgical precision and expands application areas, reinforcing incumbent market leadership. |
| Expand Recurring Revenue Models | Secures long-term financial stability by leveraging high-margin consumables and service contracts. |
| Geographic Market Penetration | Accesses untapped demand in regions like Asia and Latin America, diversifying revenue streams. |
| AI and Data Analytics Integration | Provides surgeons with real-time insights and predictive capabilities, improving patient outcomes. |
| Flexible Financial Models | Lowers adoption barriers for smaller healthcare facilities, accelerating decentralized robotic surgery capabilities. |
Research Approach
Multi-period observation of procedural volumes and technology adoption rates anchored the trend analysis, supplemented by interviews with industry experts. Primary research involved discussions with robotic surgeons, hospital procurement managers, and regulatory affairs specialists. Secondary validation drew from US FDA filings, European MDR guidance documents, and medical device company financial reports. A combination of bottom-up data aggregation and top-down market sizing ensured data accuracy.
An input-output matrix facilitated the quantitative modeling of market dynamics across the analysis window. Segmentation dimensions included product type, application, end-user, technology, and regional regulatory clusters. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key forecast inputs included new regulatory approvals for procedures and healthcare capital expenditure trends.
Caveats apply where changes in regulatory frameworks or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions regarding market evolution and adoption rates. A model refresh is warranted upon material change in any major market driver.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Europe Online Gambling Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Indonesia Digital Media Market
Digital Media
North America Online Gambling Market
Digital Media
Naruto Around Market
Digital Media
Manga Market
Digital Media
Professional Dubbing Services Market
Digital Media
Social TV Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Global Streaming Media Device Market
Digital Media
Global Stock Video Market
Digital Media
Animation Services Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market