
 Volumetric Video Market | 2026-2036
Volumetric Video Market Size, Share, and Industry Trends Forecast 2026-2036
Volumetric Video Market Analysis
Content delivery pipelines for immersive media are being redrawn as volumetric video is reshaping how three-dimensional human performances reach end users. Microsoft Corporation leverages its Azure cloud infrastructure to power distributed volumetric processing workflows for enterprise clients. Sony Corporation anchors professional capture through its proprietary sensor arrays and studio-grade camera systems. Intel Corporation competes on silicon optimization for real-time point-cloud compression at the edge.
Volumetric video captures three-dimensional spatial data of moving subjects using synchronized multi-camera arrays and depth sensors, generating dynamic 3D models viewable from any angle for applications in immersive entertainment, surgical training, and virtual collaboration. Depth sensors and 3D reconstruction technologies lead current deployment, while AI integration represents the fastest-expanding segment as machine learning automates mesh cleanup and motion retargeting. Media companies dominate end-user demand, though healthcare providers are emerging as a high-margin segment where surgical simulation commands premium licensing fees.
The Federal Communications Commission shapes bandwidth allocation for volumetric streaming at scale, while the Food and Drug Administration governs clinical validation requirements for surgical training applications. ISO standards for 3D data interoperability increasingly determine which capture formats achieve enterprise adoption. Stakeholders must monitor regulatory divergence between entertainment and medical use cases as compliance costs fragment platform economics.
Market Dynamics
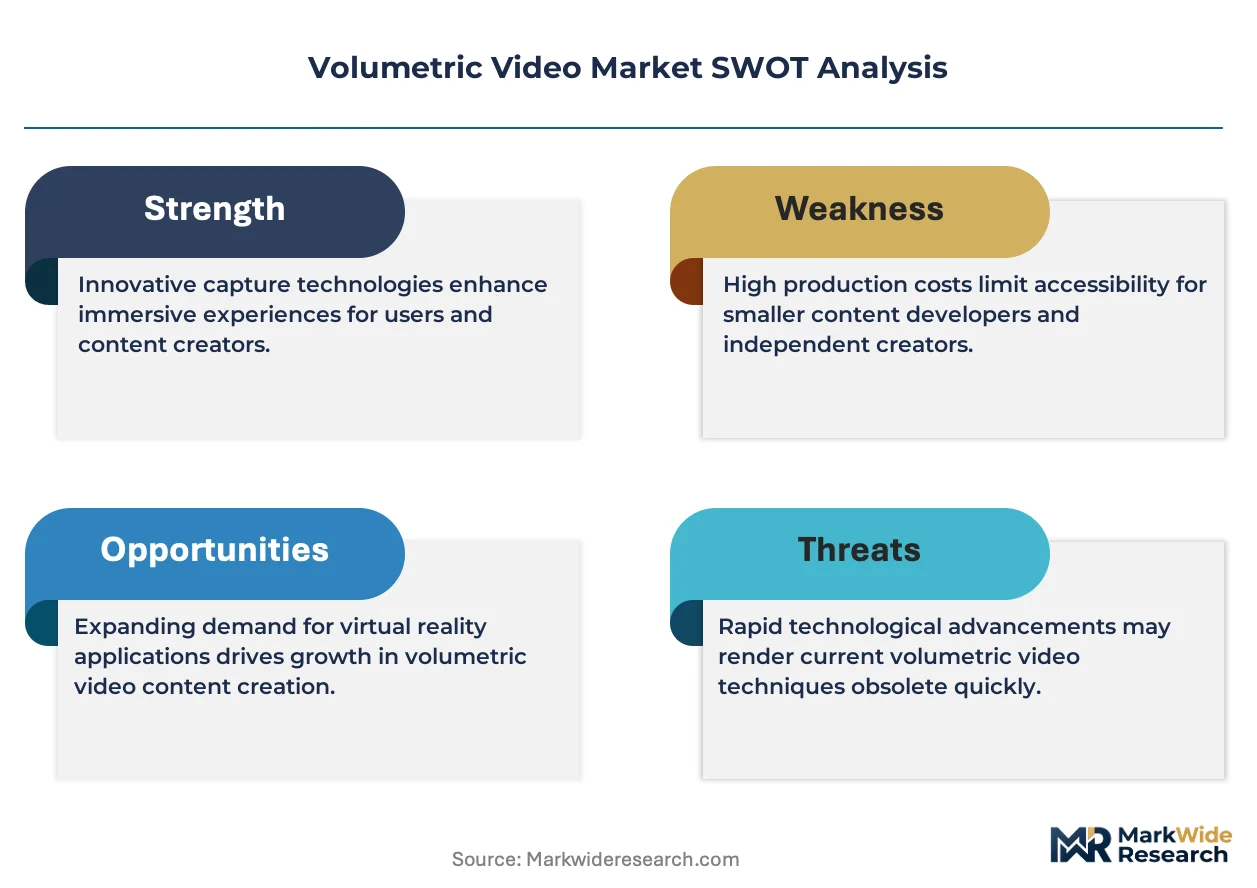
Real-time rendering pipelines are compressing production timelines from weeks to hours, forcing studios to reconfigure capital deployment around cloud-distributed processing rather than on-premise render farms. This compression is redrawing competitive advantage toward firms with Azure, AWS, or Google Cloud integration capabilities.
Growth Catalysts
- FCC bandwidth allocation:The Federal Communications Commission's spectrum policies for high-throughput volumetric streaming enable scalable delivery to mass-market headsets and mobile devices.
- Surgical simulation demand:Healthcare providers are emerging as a high-margin segment where premium licensing fees for procedural training modules justify specialized capture investments.
- Depth sensor maturation:Advances in time-of-flight and structured-light sensors are reducing per-camera costs while improving point-cloud fidelity for mid-tier studios.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in AI-accelerated rendering silicon creates single-source vulnerability for real-time mesh generation pipelines.
- ISO 3D interoperability delays:Fragmented standards for capture format exchange force studios to maintain redundant processing workflows across client ecosystems.
- Optical component volatility:German and Japanese lens manufacturers control precision glass supply, exposing production schedules to geopolitical shipping disruptions.
Strategic Opportunities
- India PLI scheme:India's production-linked incentive program for electronics manufacturing offers cost advantages for sensor assembly and camera module fabrication.
- AI motion retargeting convergence:Machine learning automation of skeletal mapping and mesh cleanup is opening volumetric capture to indie game developers previously priced out.
- Telehealth deployment:Post-operative rehabilitation and remote physical therapy represent underexploited applications for patient-specific 3D avatar generation.
Industry Challenges
- Point-cloud engineer scarcity:The specialized skill set combining computer vision, computational geometry, and real-time graphics commands salary premiums that strain mid-market studio budgets.
- FDA 510(k) timelines:Surgical training modules face extended clinical validation cycles that delay revenue recognition and compress development runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volumetric Video Market |
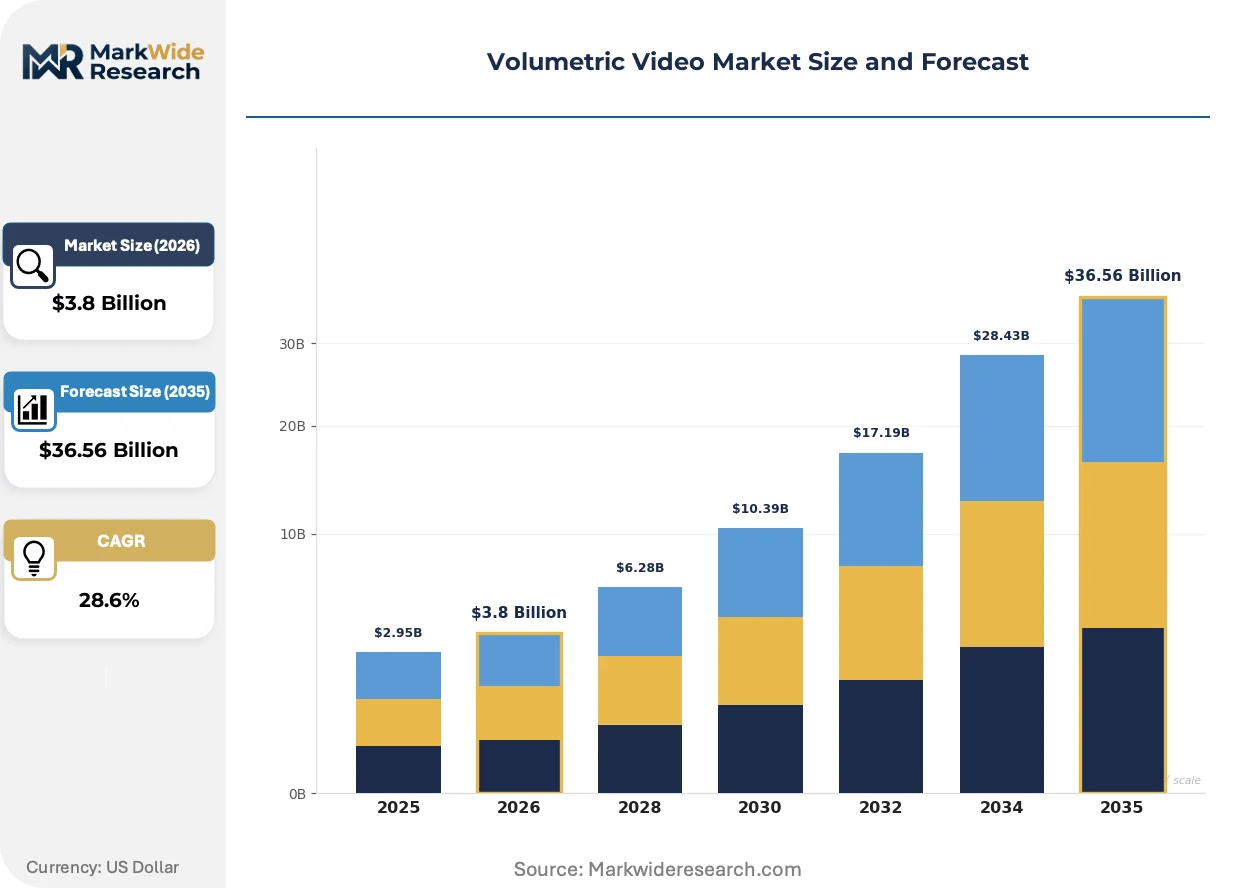
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Entertainment, Healthcare, Education, Virtual Tours Technology: Depth Sensors, 3D Reconstruction, Real-time Rendering, AI Integration End User: Media Companies, Educational Institutions, Healthcare Providers, Retailers Delivery Mode: Streaming, Downloadable Formats, Real-time Interaction, Pre-recorded Content |
| Companies Covered | Microsoft Corporation, Intel Corporation, 4Dviews, 8i, Unity Technologies, Alphabet Inc., Canon Inc., Sony Corporation, Meta Platforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volumetric Video Market Emerging Trajectories
Neural rendering architectures are displacing traditional polygon-based pipelines, enabling photorealistic human performance capture at fractions of previous computational cost. This shift is democratizing access to studio-grade volumetric production.
Neural radiance fields (NeRF) and Gaussian splatting are virtualizing how three-dimensional performances are stored and transmitted. Media companies are adopting these representations for streaming applications where bandwidth constraints previously blocked deployment. The technology is virtualizing asset delivery pipelines, collapsing the distinction between live capture and post-produced content.
The EU AI Act's transparency requirements for synthetic media are forcing disclosure protocols on volumetric content used in advertising and political communication. Studios serving European clients must now embed provenance metadata and manipulation detection signals. Healthcare applications face additional MDR scrutiny for AI-generated surgical guidance, slowing go-to-market timelines for mixed-reality training platforms.
Enterprise buyers are consolidating vendor relationships around full-stack volumetric service providers rather than assembling point solutions. This pattern concentrates contract value with studios offering capture, processing, and platform integration under single accountability. The shift is most pronounced in United States entertainment and United Kingdom healthcare procurement, where procurement teams prioritize interoperability guarantees over component cost optimization.
Volumetric Video Market Segmentation
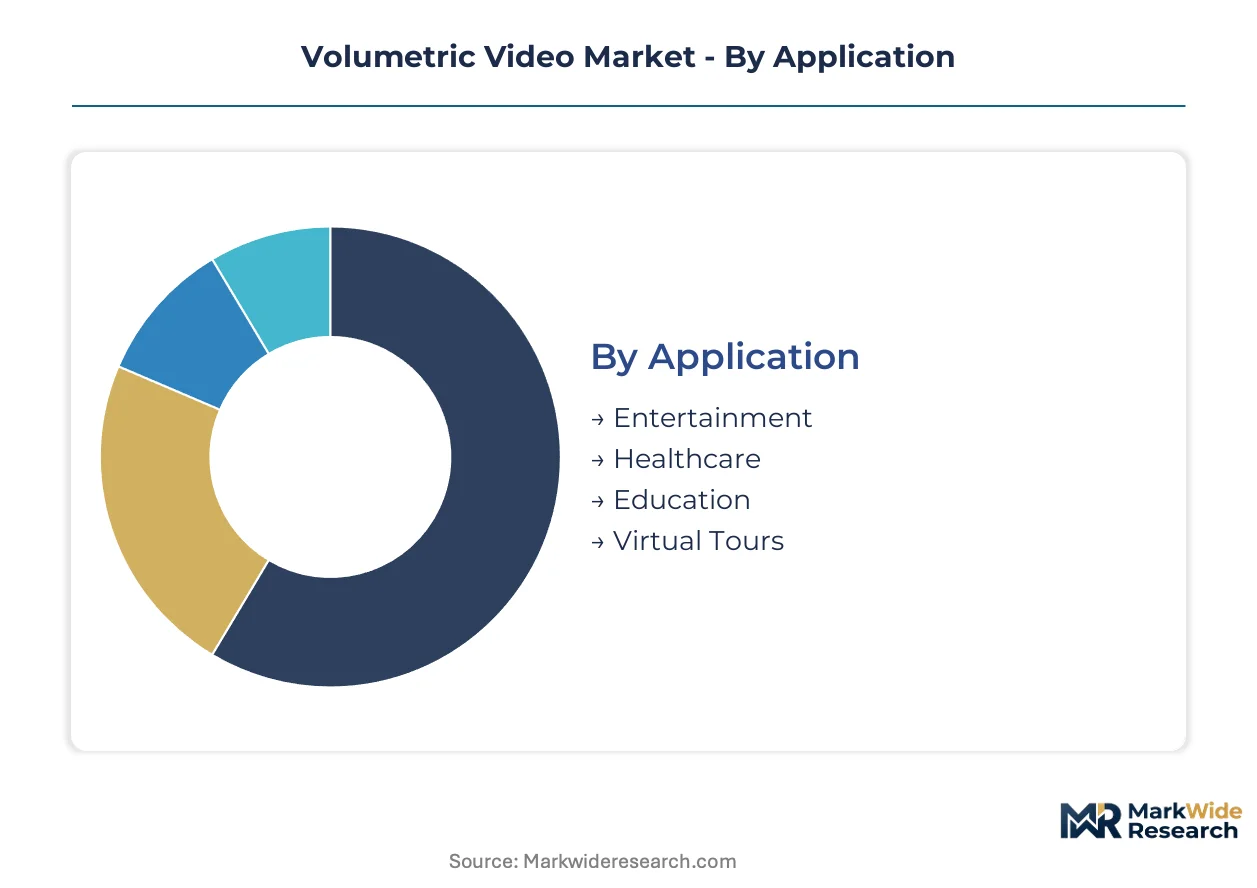
Volumetric video segmentation reveals divergent technology maturities and margin structures across capture, processing, and delivery layers. Each category maps distinct investment horizons and capability requirements for market participants.
Application:
Mature entertainment deployments coexist with emerging healthcare validation cycles across this category's maturity spectrum.
- Entertainment:Hollywood studios and streaming platforms deploy volumetric stages for immersive film production and virtual concert experiences. Los Angeles production facilities command premium licensing rates for celebrity digital twin capture.
- Healthcare:Surgical simulation modules require FDA 510(k) clearance, extending development timelines but yielding recurring licensing revenue from hospital training programs.
- Education:Universities integrate volumetric capture for remote laboratory instruction and historical artifact digitization.
- Virtual Tours:Real estate and cultural institutions adopt lightweight capture for property walkthroughs and museum exhibitions.
Entertainment retains volume leadership; healthcare holds the steepest expansion curve.
Technology:
Cost tier stratification separates commodity depth sensing from premium AI-augmented reconstruction pipelines.
- Depth Sensors:Time-of-flight and structured-light arrays form the foundational capture layer, with German and Japanese optical component suppliers controlling precision glass supply chains.
- 3D Reconstruction:Photogrammetry pipelines convert multi-camera feeds into mesh geometries, dominating mid-tier studio deployments where per-project budgets constrain AI adoption.
- Real-time Rendering:NVIDIA GPU acceleration enables live preview capabilities, though silicon supply concentration creates procurement vulnerability for smaller studios.
- AI Integration:Neural radiance fields and Gaussian splatting automate mesh cleanup and motion retargeting, compressing production timelines from weeks to hours.
Depth sensors retain volume leadership; AI integration commands the steepest expansion trajectory.
End User:
Customer type determines procurement complexity, with enterprise media buyers consolidating around full-stack vendors while healthcare maintains specialized tender processes.
- Media Companies:Streaming platforms and film studios drive bulk capture demand, consolidating vendor relationships around Azure-integrated processing pipelines.
- Healthcare Providers:Hospital systems and surgical training centers require MDR-compliant platforms in Europe and FDA-cleared modules in the United States.
- Educational Institutions:Universities prioritize interoperability guarantees over component cost optimization in procurement decisions.
- Retailers:E-commerce platforms deploy virtual try-on and product visualization at smaller scale than entertainment verticals.
Media companies retain volume leadership; healthcare providers deliver the highest margin expansion.
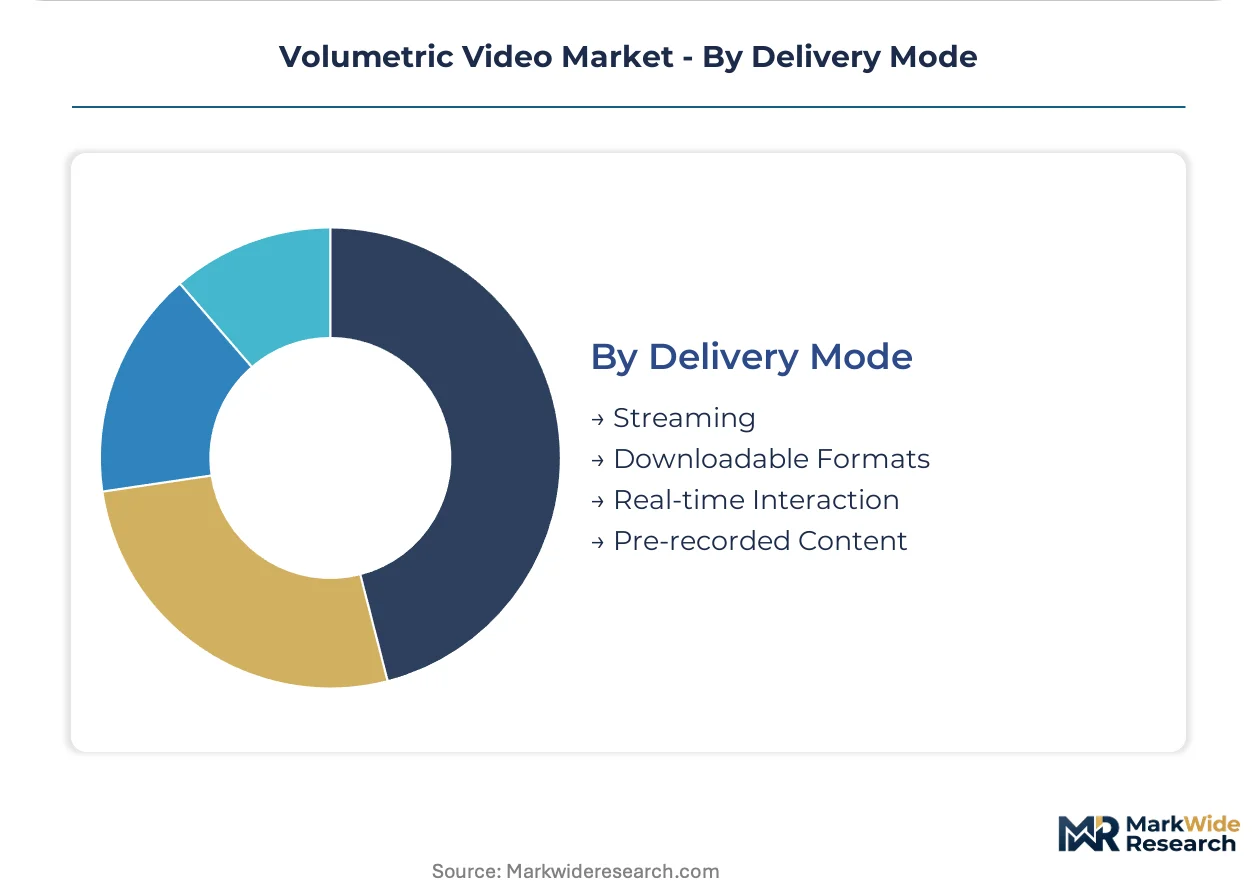
Delivery Mode:
Bandwidth requirements and latency sensitivity fragment this category across infrastructure-dependent and infrastructure-agnostic approaches.
- Streaming:FCC spectrum allocation for high-throughput delivery enables mass-market headset deployment, contingent on 5G network density.
- Downloadable Formats:Pre-packaged assets suit enterprise training deployments where network reliability cannot be guaranteed.
- Real-time Interaction:Live volumetric telepresence demands edge-optimized compression, limiting adoption to fiber-connected urban markets.
- Pre-recorded Content:Post-produced volumetric assets dominate current entertainment consumption through existing content libraries.
Pre-recorded content retains volume leadership; real-time interaction faces the steepest capability climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors volumetric video infrastructure through dense fiber-optic interconnects linking Los Angeles production stages to Azure cloud processing nodes. Submarine cable landing stations on both coasts enable low-latency transmission of point-cloud data to European and Asian markets. This backbone positions American facilities as the primary capture and distribution hub for immersive content.
United States
Hollywood studios and streaming platforms drive capture demand through celebrity digital twin production. The FCC governs spectrum allocation for high-throughput volumetric streaming to mass-market headsets. Los Angeles and San Francisco host the densest clusters of volumetric production facilities and specialized engineering talent pools.
Germany
Industrial automation firms and automotive OEMs deploy volumetric capture for virtual prototyping and training simulations. The country's national data protection authority enforces GDPR compliance for biometric capture used in synthetic media. Munich and Stuttgart concentrate precision optics manufacturers supplying time-of-flight sensor arrays to global studios.
China
Domestic streaming platforms and gaming conglomerates scale volumetric stages for virtual idol concerts and immersive social experiences. MIIT issues network access licenses for real-time 3D content delivery over 5G infrastructure. Shenzhen and Beijing house integrated hardware-software vendors compressing capture-to-stream latency for consumer applications.
Japan
Broadcasters and telecommunications carriers invest in volumetric studios for next-generation sports viewing and remote cultural preservation. METI subsidizes domestic sensor manufacturing to reduce import dependency on German optical components. Tokyo and Osaka maintain legacy broadcast infrastructure now retrofitted for volumetric content distribution.
United Kingdom
Post-production houses and advertising agencies adopt volumetric workflows for brand campaigns and immersive retail experiences. The Medicines and Healthcare products Regulatory Agency oversees clinical validation for surgical training modules using volumetric patient avatars. London anchors European production demand through Soho-based visual effects studios.
Volumetric Video Market Vendor Landscape
On the supply side, the industry is consolidating around full-stack service providers capable of integrating capture hardware, cloud processing, and platform delivery. Tiered competition separates hyperscale cloud-integrated vendors from specialized capture-stage operators and component suppliers. Strategic archetypes include infrastructure-backed platform providers, sensor-anchored hardware specialists, and AI-augmented software vendors. Dominant competitive moves encompass vertical integration into proprietary processing pipelines and strategic partnerships with streaming platforms for exclusive content libraries.
Within the infrastructure-backed tier, Microsoft Corporation and Sony Corporation exemplify divergent approaches to market positioning. Microsoft leverages its Azure cloud infrastructure to anchor enterprise volumetric processing workflows. Sony anchors professional capture through studio-grade camera systems and proprietary sensor arrays. Intel Corporation occupies a position within the silicon optimization segment, competing on edge-based point-cloud compression capabilities. These three entities represent the primary competitive anchors shaping how three-dimensional performance data flows from capture stages to end-user devices.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Intel Corporation |
| 4Dviews |
| 8i |
| Unity Technologies |
| Alphabet Inc. |
| Canon Inc. |
| Sony Corporation |
| Meta Platforms |
| Others |
Supply Flow & Price Mechanics
Los Angeles production facilities anchor global volumetric capture capacity, concentrating pricing power with studios commanding premium licensing rates for celebrity digital twin production while mid-tier operators face margin compression from cloud processing commoditization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Hollywood celebrity capture from mid-market studio services and indie game developer SaaS subscriptions. Price differentiation hinges on ISO 3D interoperability certification and real-time rendering capability tiers. Pricing pressure stems from AI-automated mesh cleanup reducing labor-intensive production costs. Media companies exhibit highest price sensitivity due to volume procurement consolidation, while healthcare providers accept premium pricing for FDA-cleared surgical training modules.
Supply Chain Analysis
Time-of-flight sensor arrays and precision optical glass feed volumetric capture hardware production. German and Japanese manufacturers control precision lens supply, while Taiwan and South Korea dominate CMOS sensor fabrication. Supply chain risk centers on single-source vulnerability for NVIDIA GPU acceleration silicon. Distribution runs through Azure-integrated cloud processing pipelines to enterprise media buyers and MDR-compliant healthcare platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as neural rendering architectures democratize studio-grade production, creating niches for specialized AI-augmented software vendors between hyperscale cloud providers and component suppliers.
For Market Incumbents: Insulate proprietary processing pipelines through backward integration into sensor-anchored hardware design, securing captive supply of time-of-flight arrays against German and Japanese optical component volatility. Defend margin position by embedding Azure cloud infrastructure deeper into enterprise client workflows, creating switching costs that neutralize AWS and Google Cloud competitive threats.
For New Entrants and Emerging Players: India's electronics manufacturing clusters offer underpenetrated cost advantages for sensor assembly and camera module fabrication under the PLI scheme. Target telehealth rehabilitation applications for patient-specific 3D avatar generation, deploying lightweight edge-optimized compression to bypass fiber-connected urban market limitations. Go-to-market through direct partnerships with hospital systems seeking MDR-compliant mixed-reality training platforms.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates divesting non-core volumetric capture divisions as neural rendering reduces hardware dependency. Long-term viability favors full-stack service providers integrating capture, processing, and platform delivery under single accountability. Monitor FDA 510(k) clearance timelines for surgical training modules as inflection indicator for healthcare segment revenue recognition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Rendering Architecture Deployment | Gaussian splatting adoption by media companies collapses live capture and post-production distinction. |
| Azure Cloud Processing Integration | Enterprise clients consolidate vendor relationships around distributed volumetric processing workflows. |
| ISO 3D Interoperability Certification | Capture format standardization determines which studios achieve multi-client enterprise adoption. |
| AI Motion Retargeting Automation | Machine learning mesh cleanup opens volumetric capture to indie developers previously priced out. |
| FDA 510(k) Clearance Pathway | Surgical simulation modules yield recurring licensing revenue from hospital training programs. |
Methodological Framework
The analysis maps depth sensor hardware, 3D reconstruction software, real-time rendering pipelines, and AI integration segments, each validated through volumetric stage operators, cloud platform engineers, healthcare simulation directors, and entertainment procurement leads. Primary interviews combined with secondary validation from FCC spectrum allocation filings, FDA 510(k) submission databases, MIIT network access licenses, and hyperscaler capex disclosures. Bottom-up capture stage capacity estimates triangulate against top-down content production spend analysis.
Assumptions held fixed include regulatory timelines for FDA clinical validation and FCC bandwidth allocation, while neural rendering adoption curves and GPU supply concentration were varied across sensitivity scenarios. Segmentation dimensions modeled encompass application vertical, technology tier, end-user procurement complexity, and delivery mode bandwidth requirements. CAGRs derived from installed base growth of volumetric stages and per-project production value compression. Forecast inputs include 5G network density trajectories and AI-accelerated rendering silicon availability.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hyperscale cloud providers would shift outcomes toward consolidated platform economics. Cross-checking against entertainment production budget allocations and hospital capital expenditure plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Music Video Production Market
Digital Media
Online Movie Market
Digital Media
Pro AV Market
Digital Media
Cognitive Media Market
Digital Media
Manga Market
Digital Media
Anime Streaming Tool Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Digital Content Creation Market
Digital Media
Anime Derivatives Market
Digital Media
Global Animation Market
Digital Media
Entertainment Market
Digital Media
Secondary Ticket Market
Digital Media
Photographic Services Market
Digital Media
Europe Animation, VFX and Post Production Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Anime Merchandising Market