
 Global Playout Automation and Channel in a Box Market | 2026-2036
Global Playout Automation and Channel in a Box Market Size, Share, and Industry Trends Forecast 2026-2036
Global Playout Automation and Channel in a Box Market Intelligence
The traditional broadcast hardware supply chain is fragmenting as broadcasters aggressively prioritize software-defined and cloud-native solutions over capital-intensive infrastructure. Harmonic Inc. leverages its strong position in video compression and delivery to offer fully integrated cloud playout solutions. Grass Valley USA competes with a comprehensive portfolio addressing both live production and complex media asset management needs. Evertz Microsystems Ltd differentiates through its deep expertise in IP-based infrastructure, particularly with solutions compliant with SMPTE 2110 standards.
Playout automation and channel in a box (CiaB) solutions integrate functions like graphics, switching, and server playout into a unified platform. Their primary purpose is to streamline broadcast workflows, reduce hardware complexity, and lower costs for content distributors. Among solutions, Channel in a Box systems are expanding rapidly due to their cost-effectiveness for smaller broadcasters. The technology segment is defined by a shift from on-premise to cloud-based deployments, which offer greater operational flexibility and scalability for OTT platforms and IPTV services.
Regulatory bodies such as the US Federal Communications Commission (FCC) and the United Kingdom's communications regulator mandate specific standards for broadcast quality, loudness, and closed captioning. Adherence to technical standards from organizations like the Society of Motion Picture and Television Engineers (SMPTE) ensures interoperability in increasingly complex multi-vendor environments. Vendor selection will increasingly depend on a platform's ability to manage multi-format deliveries across both linear broadcast and digital streaming endpoints.
Market Dynamics
The pivot to software-defined architectures over capital-intensive hardware is the central force redefining the broadcast technology stack. This transition prioritizes operational flexibility and IP-based workflows, altering vendor and broadcaster strategies.
Growth Catalysts
- OTT Platform Proliferation:The global expansion of streaming services creates a substantial need for scalable, cloud-native playout solutions capable of managing dynamic channel lineups and targeted advertising.
- Cost Reduction Mandates:Channel in a Box systems offer a lower total cost of ownership, enabling smaller broadcasters and content creators to launch new linear channels without significant upfront hardware investment.
- IP Standards Adoption:SMPTE standards like ST 2110 provide interoperability, de-risking investment in IP-based playout infrastructure and encouraging market transition away from legacy SDI.
Market Restraints
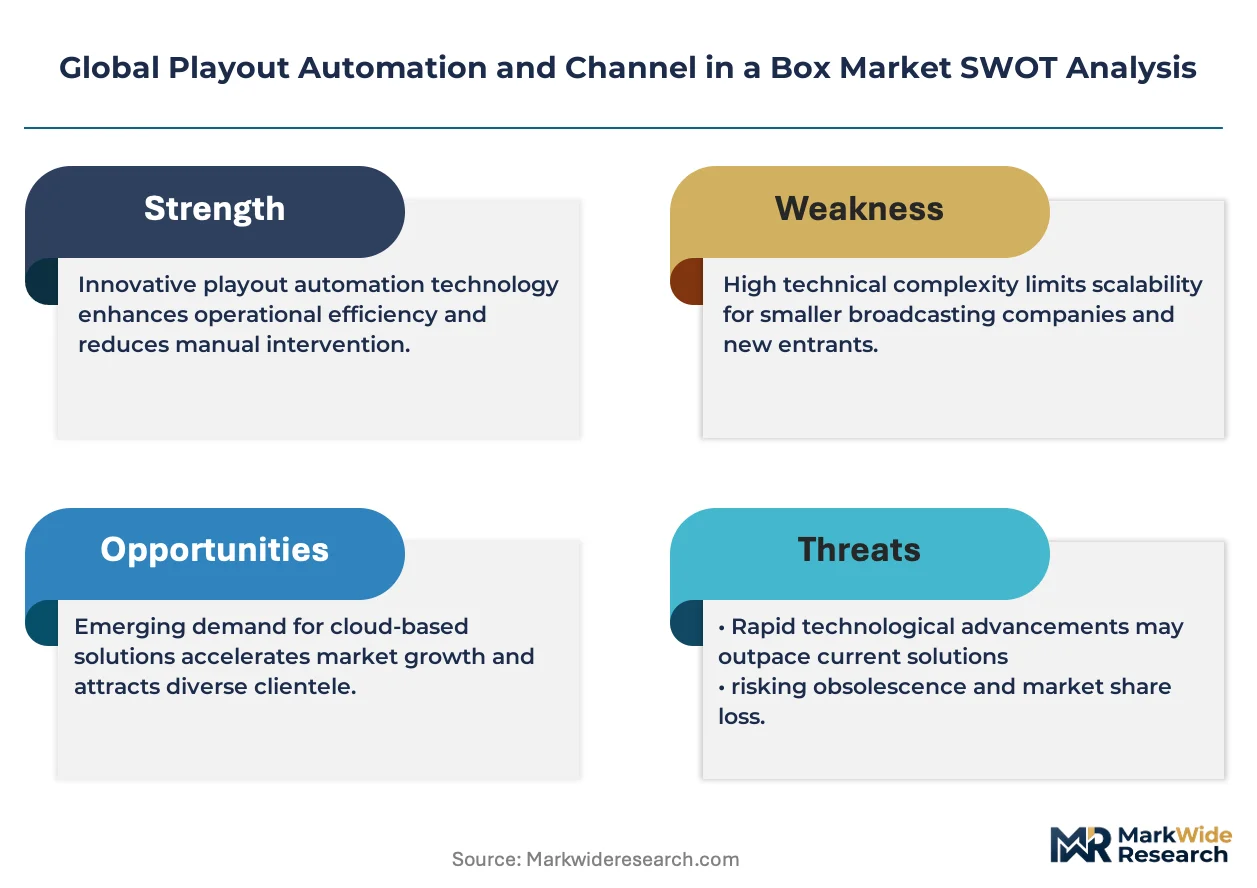
- Legacy System Integration:The complexity and expense of integrating modern IP-based playout solutions with entrenched, baseband SDI infrastructure create significant technical and financial hurdles for established broadcasters.
- High Bandwidth Costs:Cloud-based playout for high-bitrate formats, particularly 4K and HDR, requires sustained, high-cost network connectivity, which can be a prohibitive operational expense for some operators.
- Vendor Lock-In Concerns:The proprietary nature of some highly integrated CiaB and cloud playout ecosystems creates concerns among broadcasters about a lack of flexibility and dependency on a single supplier.
Strategic Opportunities
- Hyper-Personalized Channels:Leveraging AI to dynamically assemble and playout niche content streams for specific viewer demographics represents a significant opportunity for targeted advertising and content monetization.
- Emerging Media Markets:Broadcasters in regions like Southeast Asia and Latin America can leapfrog legacy infrastructure by directly adopting cost-effective CiaB and cloud solutions for new channel launches.
- FAST Channel Enablement:Developing turnkey solutions that bundle playout automation with monetization and distribution services for Free Ad-supported Streaming TV (FAST) platforms meets a clear market need.
Industry Challenges
- Broadcast Engineering Talent Gap:A shortage of engineers skilled in both traditional broadcast video and modern IT networking creates implementation and maintenance hurdles for operators deploying IP-based systems.
- Cybersecurity Vulnerabilities:IP-based workflows expose critical broadcast chains to new cybersecurity threats, requiring specialized security protocols and constant vigilance which adds significant operational overhead.
- Multi-Jurisdictional Compliance:Ensuring content meets varied regulatory requirements for loudness, such as the US CALM Act, and content standards across different countries is a complex operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Playout Automation and Channel in a Box Market |
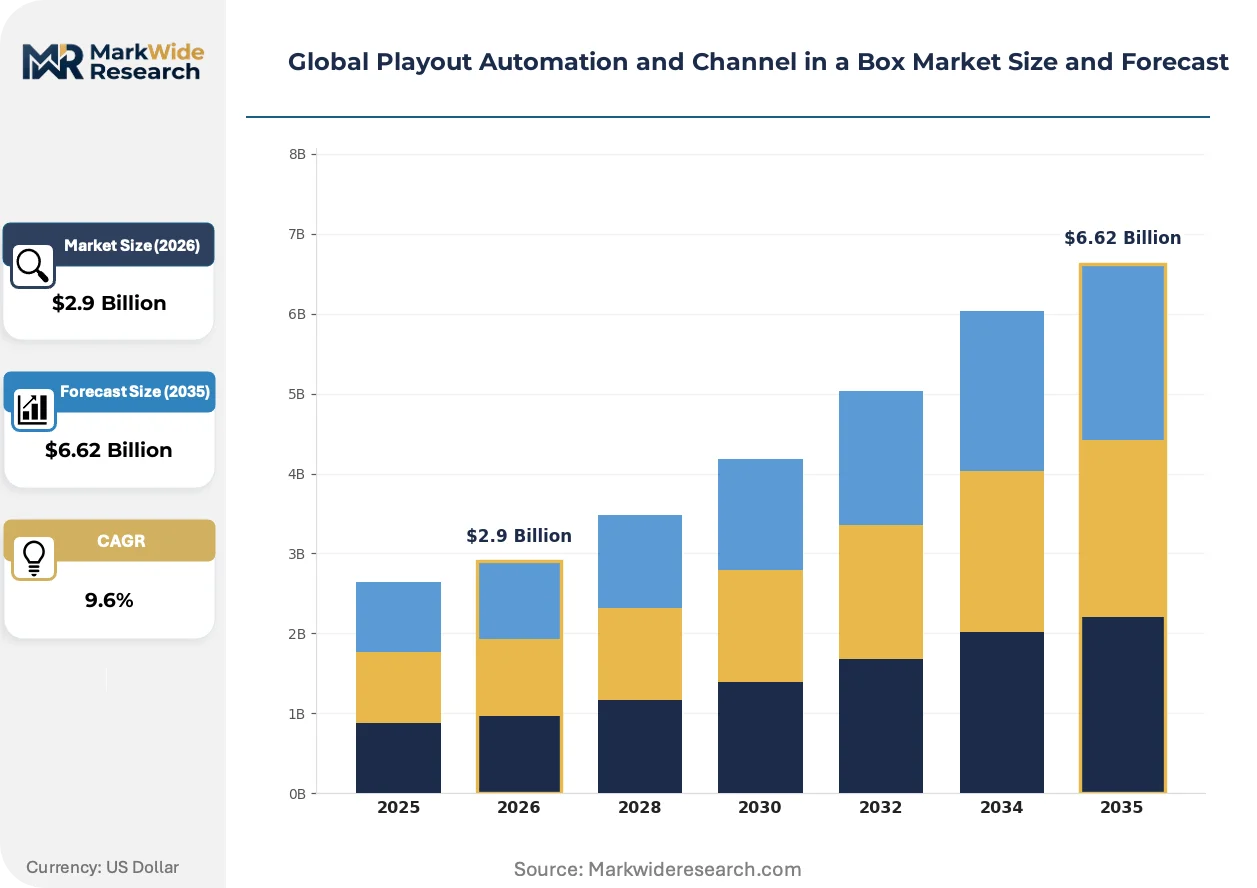
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $6.62 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Playout Automation System, Channel in a Box Solution, Media Asset Management, Content Delivery Platform, Broadcast Management Software Technology: Cloud-Based, On-Premise, Hybrid, IP-Based, Virtualized Application: Television Broadcasting, Radio Broadcasting, OTT Platforms, IPTV Services, Satellite Transmission End User: Broadcasters, Content Distributors, Network Operators, Media Production Houses, Streaming Service Providers |
| Companies Covered | Harmonic Inc., Evertz Microsystems Ltd, Pebble Beach Systems, Grass Valley USA, Imagine Communications, Avid Technology, PlayBox Technology, Anyware Video, Brightcove, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Playout Automation and Channel in a Box Market Strategic Shifts & Innovations
The broadcast value chain is being fundamentally transformed by the convergence of IT principles and media workflows. This shift favors software-defined solutions that offer scalability and operational agility over static, hardware-based systems.
Cloud-native playout platforms manage scheduling and stream origination from remote data centers. Traditional broadcasters and new OTT players adopt these systems to gain operational flexibility and scalability. This technology is hybridizing broadcast operations, blending on-premise control for high-value live events with cloud playout for thematic and pop-up channels.
Mandates from regulators like the US Federal Communications Commission (FCC) for closed captioning and loudness control (CALM Act) are key. This forces playout automation systems to integrate robust, reliable compliance-checking and logging features. Vendors must ensure platforms can automatically insert and verify this data for all channels, especially those distributed nationally.
A preference for operational expenditure (OpEx) models is replacing large, upfront capital investments in broadcast hardware. This shift favors subscription-based, software-as-a-service (SaaS) offerings over traditional, perpetual license systems. The trend is most prominent among new media entrants in North America and Western Europe that prioritize scalability and cost predictability.
Global Playout Automation and Channel in a Box Market Segmentation
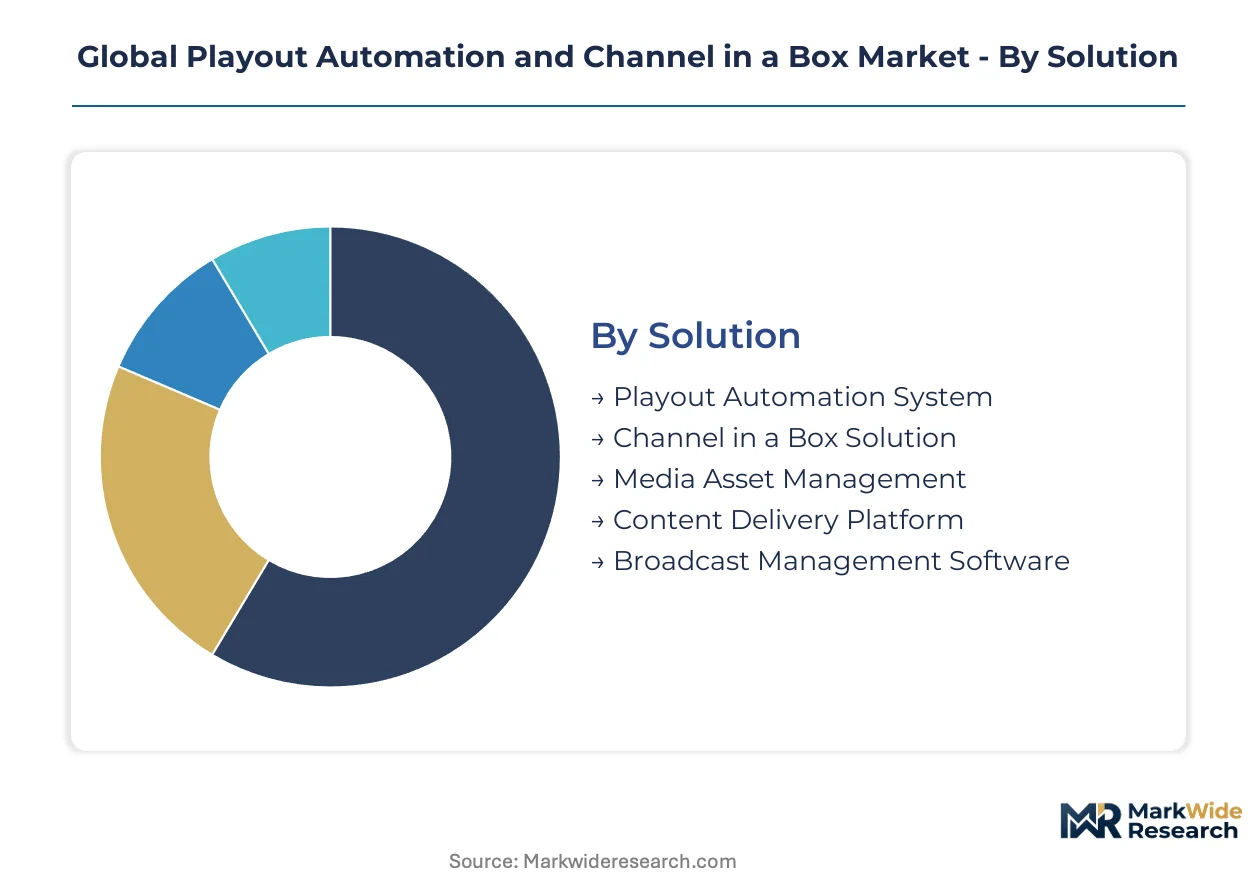
Understanding the segmentation of the global playout automation and channel in a box market reveals how diverse needs drive technology adoption and solution development. Each segment reflects specific operational challenges and strategic priorities for content creation, management, and distribution. Analyzing these distinctions helps stakeholders identify areas of high growth and targeted investment.
Solution:
Solution types vary by the level of integration and functionality required across broadcast operations.
- Playout Automation System:This comprehensive software suite manages scheduling, content ingest, graphics insertion, and transmission for linear channels. Broadcasters in established markets like the United States rely on these systems for complex, multi-channel operations and regulatory compliance.
- Channel in a Box Solution:These integrated, often software-defined, systems combine multiple broadcast functions such as switching, graphics, and server playout into a single unit. Emerging media markets in Southeast Asia are rapidly adopting CiaB for cost-effective new channel launches.
- Media Asset Management:This solution organizes, stores, and retrieves digital media files, streamlining content workflows.
- Content Delivery Platform:These platforms ensure efficient and secure delivery of video content to end-users across various networks.
- Broadcast Management Software:This software handles business operations, including scheduling, rights management, and ad sales.
Playout Automation System holds installed capacity. Channel in a Box Solution is rotating up the share rankings.
Technology:
Deployment models for these solutions reflect evolving infrastructure preferences and operational strategies.
- Cloud-Based:These solutions leverage remote data centers for processing and storage, offering high scalability and operational flexibility. OTT platforms globally favor cloud-based deployments for dynamic channel lineups and rapid market entry.
- On-Premise:Hardware and software are hosted within the broadcaster's own facilities, providing maximum control and security. Major broadcasters in Western Europe often retain on-premise systems for critical live production workflows.
- Hybrid:This model combines on-premise infrastructure with cloud services, balancing control with scalability.
- IP-Based:Utilizing internet protocol for signal transport, these technologies enable flexible, software-defined workflows.
- Virtualized:Software runs on generic server hardware, abstracting functions from physical machines for efficiency.
Demand for On-Premise technology remains strong, while Cloud-Based solutions are expanding most quickly.
Application:
The diverse range of content distribution platforms dictates specific requirements for playout and channel management.
- OTT Platforms:These applications deliver video content directly to viewers over the internet, bypassing traditional broadcast infrastructure. The proliferation of streaming services in North America drives substantial demand for scalable playout solutions.
- Television Broadcasting:This traditional application involves transmitting scheduled programming over terrestrial, satellite, or cable networks. Established networks in countries like Germany continue to invest in modernizing their television broadcasting playout.
- Radio Broadcasting:This segment focuses on audio content transmission, requiring specific automation for scheduling and ad insertion.
- IPTV Services:These services deliver television programming using the internet protocol suite over a managed network.
- Satellite Transmission:This application uses satellite technology for wide-area content distribution, particularly in remote regions.
Television Broadcasting applications maintain a substantial base. OTT Platforms are driving significant new deployments.
End User:
Different organizational types drive demand for playout automation and channel in a box systems based on their scale and content needs.
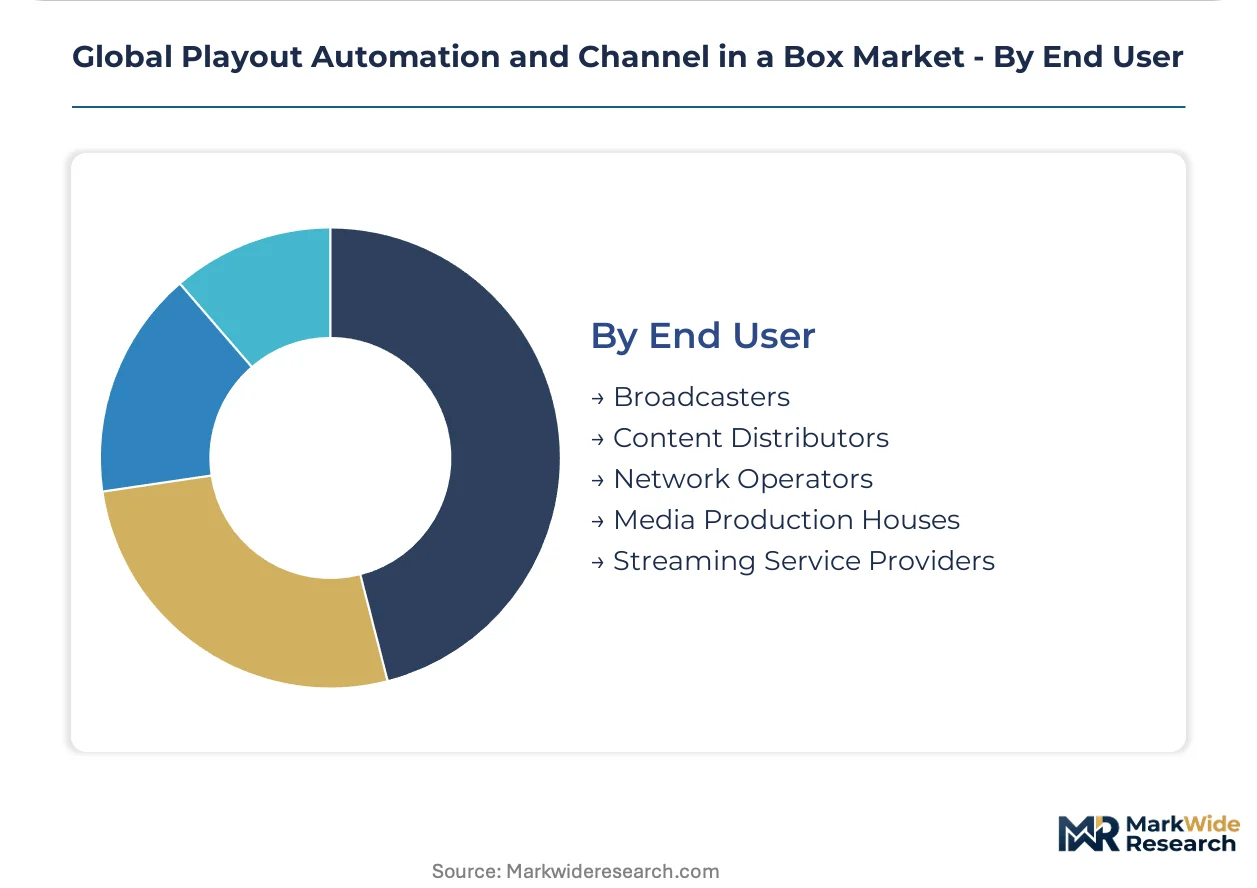
- Broadcasters:These entities operate traditional television and radio channels, requiring robust systems for scheduling, playout, and regulatory compliance. Major broadcast networks across Europe are upgrading their playout infrastructure.
- Streaming Service Providers:These companies deliver on-demand or linear content directly to consumers via the internet. Global streaming giants frequently deploy cloud-native playout solutions for their expanding content libraries.
- Content Distributors:These organizations manage the dissemination of content to various platforms and regions.
- Network Operators:These companies manage the physical infrastructure for content delivery, including cable and telecom networks.
- Media Production Houses:These entities create content and require playout solutions for quality control and delivery to partners.
Traditional Broadcasters represent a foundational user base. Streaming Service Providers are rapidly increasing their adoption of these systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive digital media infrastructure and widespread internet penetration across mature markets underwrite robust demand for playout automation and channel in a box solutions. These regions prioritize sophisticated, scalable systems for multi-channel operations and stringent regulatory compliance. Emerging markets, conversely, leverage these technologies to establish new, cost-effective broadcast and streaming services.
United States
The United States drives demand for cloud-native playout solutions, particularly from OTT platforms seeking dynamic channel lineups and targeted advertising capabilities. The US Federal Communications Commission (FCC) mandates strict standards for loudness (CALM Act) and closed captioning, requiring advanced compliance features in playout systems. Major media hubs like Los Angeles and New York City concentrate broadcasting innovation, where studios and networks invest in hybrid cloud models.
Germany
German broadcasters maintain a strong demand for on-premise playout systems, especially for critical live production workflows requiring maximum control and security. Germany's communications regulator ensures adherence to broadcast quality standards, influencing the technical specifications of local playout solutions. The media cluster in Munich, for instance, focuses on modernizing existing television broadcasting playout infrastructure with IP-based capabilities.
India
India's rapidly expanding streaming services and new linear channel launches accelerate the adoption of cost-effective channel in a box solutions. The Telecom Regulatory Authority of India (TRAI) oversees broadcasting standards, encouraging scalable and compliant playout technologies. The media production hub in Mumbai sees significant investment in cloud solutions, allowing content creators to bypass legacy infrastructure.
Singapore
Singapore acts as a regional hub for media innovation, with a strong preference for cloud-based deployments supporting OTT platforms and IPTV services across Southeast Asia. The Infocomm Media Development Authority (IMDA) promotes digital transformation in the media sector, fostering an environment for advanced playout solutions. Technology parks like one-north attract streaming service providers and content distributors deploying highly scalable playout automation.
Brazil
Brazil's growing streaming market and the need for efficient content distribution across a large geography generate demand for flexible, scalable playout systems. The Agência Nacional de Telecomunicações (ANATEL) regulates broadcast and telecommunications, influencing technical requirements for playout solutions. Sao Paulo, a major economic and media center, experiences significant uptake of cloud-based playout for new content offerings.
Global Playout Automation and Channel in a Box Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing modular elements. The market exhibits a tiered structure, with established players offering comprehensive end-to-end solutions alongside nimble software vendors focusing on cloud-native deployments. Strategic partnerships between technology providers and content distributors represent a dominant competitive move, alongside continuous portfolio diversification into IP-based workflows.
On the enterprise-grade playout vector, Harmonic Inc. exemplifies a provider leveraging its video compression expertise to deliver integrated cloud playout solutions. Evertz Microsystems Ltd, a Canada-based company, occupies a position emphasizing deep expertise in IP-based infrastructure, particularly with SMPTE 2110 compliant offerings. Grass Valley USA, Inc., an American entity, represents a comprehensive portfolio approach, addressing both live production and complex media asset management needs for broadcasters.
| Leading Market Players |
|---|
| Harmonic Inc. |
| Evertz Microsystems Ltd |
| Pebble Beach Systems |
| Grass Valley USA |
| Imagine Communications |
| Avid Technology |
| PlayBox Technology |
| Anyware Video |
| Brightcove |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure utilization in mature media markets drives vendor investment strategies, influencing both pricing models and the efficiency of the supply chain for playout solutions. This dynamic ensures that software-defined offerings gain cost advantages over traditional hardware, impacting procurement decisions.
Pricing Analysis
Volume-based tiering structures characterize pricing models for playout automation and Channel in a Box (CiaB) solutions, often delivered as subscription-based SaaS offerings. Customization level for specific broadcast workflows and the extent of after-sales support represent key price differentiation drivers. Pricing softness stems from the aggressive cost reduction mandates across the broadcasting sector. Smaller broadcasters and new OTT entrants exhibit the highest price sensitivity, seeking cost-effective CiaB solutions, while major networks prioritize comprehensive features over minimal cost.
Supply Chain Analysis
Extended payment terms often define the upstream supplier-customer relationships for specialized IP hardware components and software licenses. Geographic supply concentration for core development resides in the United States, Canada, and Western Europe, where media technology expertise is deep. Key dependencies include cloud compute resources and specialized IP-enabled hardware. Vendor lock-in concerns represent a significant structural risk for broadcasters. Downstream distribution runs primarily through direct sales channels for enterprise clients and value-added resellers for smaller market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection point, driven by the shift towards IP-based workflows and the SMPTE 2110 ecosystem. Such a transformation reshapes competitive dynamics and strategic priorities for all participants.
For Market Incumbents: Insulate core broadcast revenue streams by accelerating cloud transition and deepening IP infrastructure expertise. This defends against nimble software vendors and cloud-native entrants. Invest in AI-driven content automation for hyper-personalization, leveraging existing channel control to maintain market share. Focus R&D on integrated solutions that simplify complex multi-vendor environments for broadcasters.
For New Entrants and Emerging Players: Build out niche cloud-native solutions targeting underserved segments, such as emerging media markets in Southeast Asia and Latin America. Focus on developing turnkey solutions for FAST channel enablement, offering bundled monetization and distribution services. Smaller broadcasters and content creators represent the most penetrable segment. A SaaS-first go-to-market strategy provides operational flexibility and cost predictability for these new customers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across the channel-in-a-box segment, favoring software-centric business models. Long-term viability favors scalable, software-defined platforms over traditional hardware. Acquisition targets should include niche cloud playout providers and AI-driven content automation firms with strong IP portfolios. Growth in cloud consumption metrics for media workloads remains a critical signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Dynamic Content Assembly | This enhances hyper-personalization capabilities for OTT platforms and targeted advertising revenues. |
| Partner with Hyperscale Cloud Providers | This ensures optimized content delivery infrastructure and global scalability for streaming services. |
| Launch Turnkey FAST Channel Solutions | This addresses the growing demand for cost-effective ad-supported streaming content creation. |
| Expand into Emerging Media Markets | This captures new channel launches and streaming service growth in regions like Southeast Asia. |
| Acquire Cybersecurity Specialization Firm | This strengthens IP-based workflow security, protecting critical broadcast chains from threats. |
Research Approach
Operator-level perspectives from broadcast engineers, IT architects, and content distribution executives anchored the qualitative base for this analysis. Primary interviews with these industry stakeholders were triangulated with extensive secondary research. This included reviewing industry association reports, regulatory body publications from the FCC and TRAI, technology vendor whitepapers, and financial filings of public companies. Bottom-up and top-down triangulation ensured data consistency and robust market sizing.
Scenario-bracketing underpinned the quantitative analysis, establishing plausible upper and lower bounds for market progression over the projection horizon. The modeling incorporated segmentation dimensions including solution type, technology deployment, application, end-user, geographic region, and content format. Compound annual growth rates were derived through regression analysis of historical trends and projected future adoption rates. Key industry-specific forecast inputs included OTT subscriber growth rates and IP infrastructure investment trends.
Sensitivities concentrate around the pace of IP infrastructure adoption and evolving regulatory mandates. Forecasts reflect assumptions regarding technological advancements and market acceptance across the analysis window. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
North America Online Gambling Market
Digital Media
North America Webtoons Market
Digital Media
North America Photographic Services Market
Digital Media
Animation Services Market
Digital Media
Video Content Management Market
Digital Media
Secondary Ticket Market
Digital Media
Global Virtual Goods Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Stock Photography Market
Digital Media
Global Digital Painting Market
Digital Media
3D Animation Market
Digital Media
LED Stadium Screens Market
Digital Media
Video Player Market
Digital Media
Drone Wedding Photography Market
Digital Media
Europe Online Gambling Market