
 4K Content Market | 2026-2036
4K Content Market Size, Share, and Industry Trends Forecast 2026-2036
4K Content Market Outlook
The EU Green Deal is pivoting streaming infrastructure investments toward energy-efficient encoding and data center operations. Netflix leverages proprietary compression codecs to reduce bandwidth per 4K stream. Disney Plus anchors its competitive position through exclusive premium 4K libraries tied to franchise intellectual property. Amazon Prime Video extends its reach by bundling 4K content with broader e-commerce membership economics.
4K content denotes video material with a horizontal resolution of approximately 4000 pixels, typically 3840 × 2160 pixels under the UHD-1 standard, requiring HEVC or AV1 encoding to deliver viable bitrates over consumer broadband. Its primary commercial purpose is to differentiate premium subscription tiers and justify price escalation against HD alternatives. Movies and TV Shows command the largest current revenue pools within content type segmentation, while Sports Events represent the fastest-growing category as live rights holders invest in native 4K production. Streaming dominates delivery mode economics, though Blu-ray retains a durable niche among collectors seeking uncompressed bitrates and archival permanence.
The FCC in the United States mandates accessibility features for broadcast and streaming video, indirectly shaping 4K subtitle and audio description standards. The EU AI Act imposes transparency requirements on algorithmic content recommendation systems that curate 4K libraries. Stakeholders must monitor how regulatory fragmentation around data localization and content moderation reshapes cross-border licensing for ultra-high-definition catalogs.
Market Dynamics
Streaming infrastructure operators face mounting pressure from the EU Green Deal's digital sustainability criteria, forcing wholesale recalibration of encoding architectures and data center energy intensity per streamed hour.
Growth Catalysts
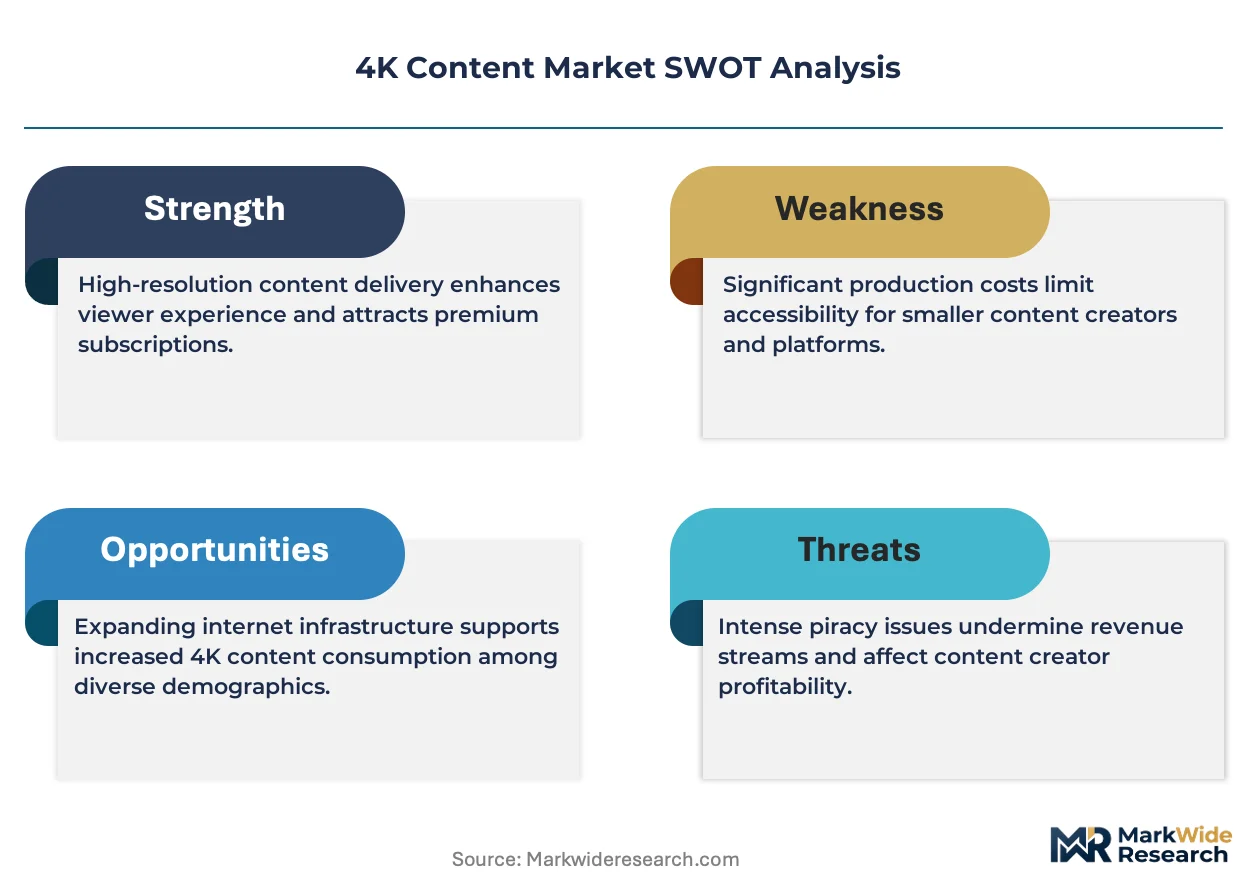
- HEVC/AV1 encoding standards:Advanced compression codecs slash bandwidth requirements for 4K delivery, enabling viable streaming economics over standard consumer broadband connections.
- US household penetration:American homes lead globally in 4K-compatible display ownership and subscription stacking behaviors, anchoring premium tier demand.
- EU AI Act transparency mandates:Algorithmic content recommendation systems must disclose curation logic, indirectly standardizing 4K library presentation across member states.
Market Restraints
- Data center energy costs:4K streaming's computational load intensifies electricity consumption, exposing operators to volatile European power pricing and carbon border adjustments.
- Blu-ray archival permanence:Physical media retains a durable collector niche, constraining full digital transition and complicating licensing window management.
- FCC accessibility mandates:Subtitle and audio description requirements for 4K broadcasts impose technical overhead that slows rollout timelines.
Strategic Opportunities
- Sports live production:Native 4K investment in live rights represents the fastest-expanding content category, outpacing movies and scripted television.
- Cross-border licensing arbitrage:Regulatory fragmentation around data localization creates white space for rights holders who navigate multi-territorial clearance efficiently.
- Cloud gaming convergence:Interactive entertainment platforms are integrating cinematic 4K assets, opening new monetization channels beyond passive viewing.
Industry Challenges
- Codec patent pools:HEVC and emerging VVC licensing complexity creates legal friction for encoding infrastructure procurement.
- Legacy HD infrastructure:Broadcast and cable operators face costly headend upgrades to support 4K simulcast without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4K Content Market |
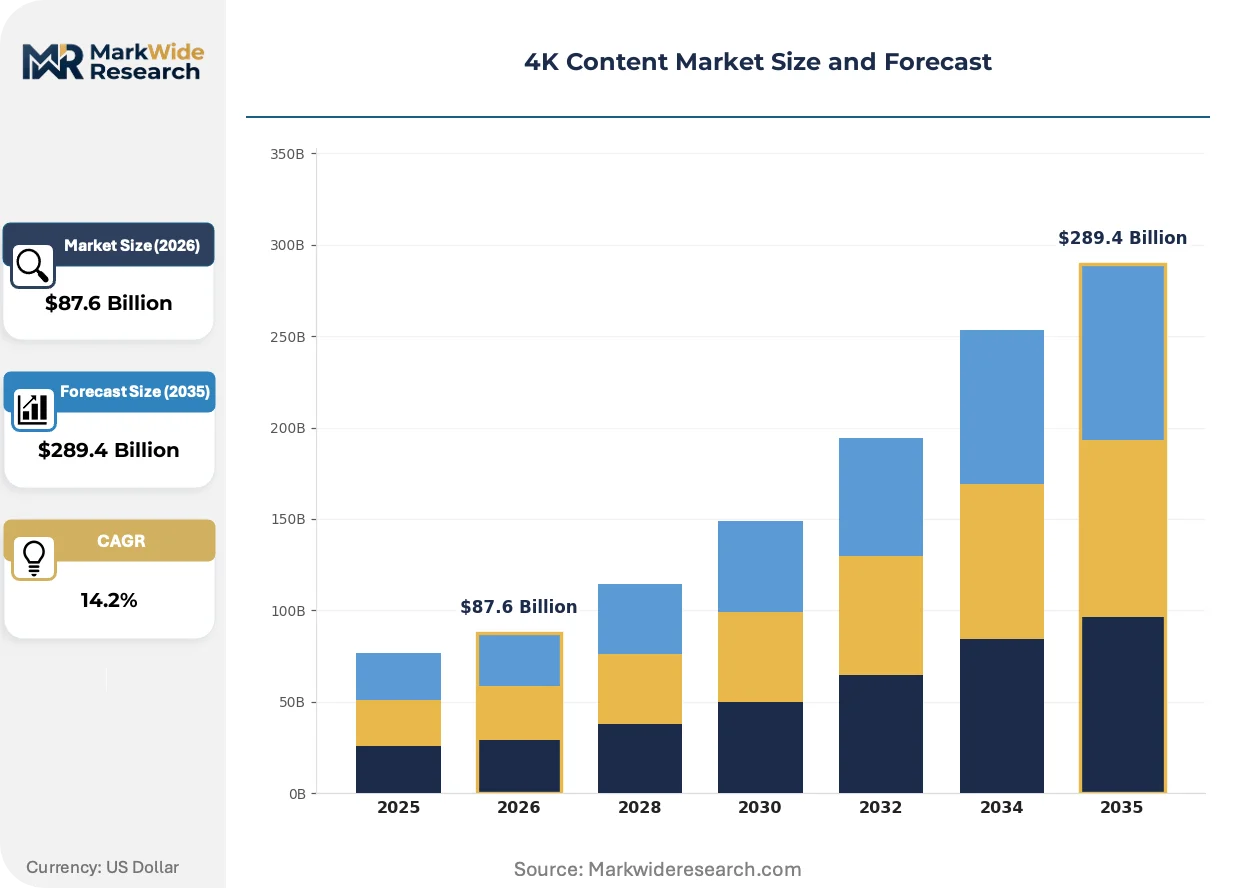
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Shows, Documentaries, Sports Events Delivery Mode: Streaming, Downloadable, Blu-ray, Rental End User: Home Users, Cinemas, Educational Institutions, Businesses Device Compatibility: Smart TVs, Streaming Devices, Gaming Consoles, Projectors |
| Companies Covered | HBO Max, Peacock, Netflix, Paramount Plus, Hulu, Disney Plus, Apple TV, ESPN, Amazon Prime Video, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4K Content Market Strategic Shifts
Compression technology and regulatory energy frameworks are rewriting the economics of ultra-high-definition delivery. Three developments are restructuring competitive positioning.
AV1 royalty-free encoding is electrifying streaming platform technical roadmaps. Netflix and Amazon Prime Video have deployed AV1 at scale for 4K catalogs, cutting per-stream bitrates by thirty to fifty percent against HEVC baselines. This compression efficiency is compressing infrastructure capex recovery periods and enabling 4K expansion into bandwidth-constrained emerging markets.
The EU Green Deal's sector-specific digital sustainability criteria are forcing data center operators to disclose energy consumption per streamed hour. Amazon Web Services and Equinix facilities serving European 4K traffic now face mandatory carbon intensity reporting. Sports streaming services with live 4K rights are relocating processing workloads to Nordic hydroelectric-powered regions to maintain compliance margins.
Subscription stacking fatigue is fragmenting household 4K access patterns. Consumers in the United States maintain multiple premium tiers simultaneously but rotate activation based on content release calendars. This behavior is compressing average revenue per user stability and forcing platforms to front-load exclusive 4K franchise releases to minimize churn windows.
4K Content Market Segmentation
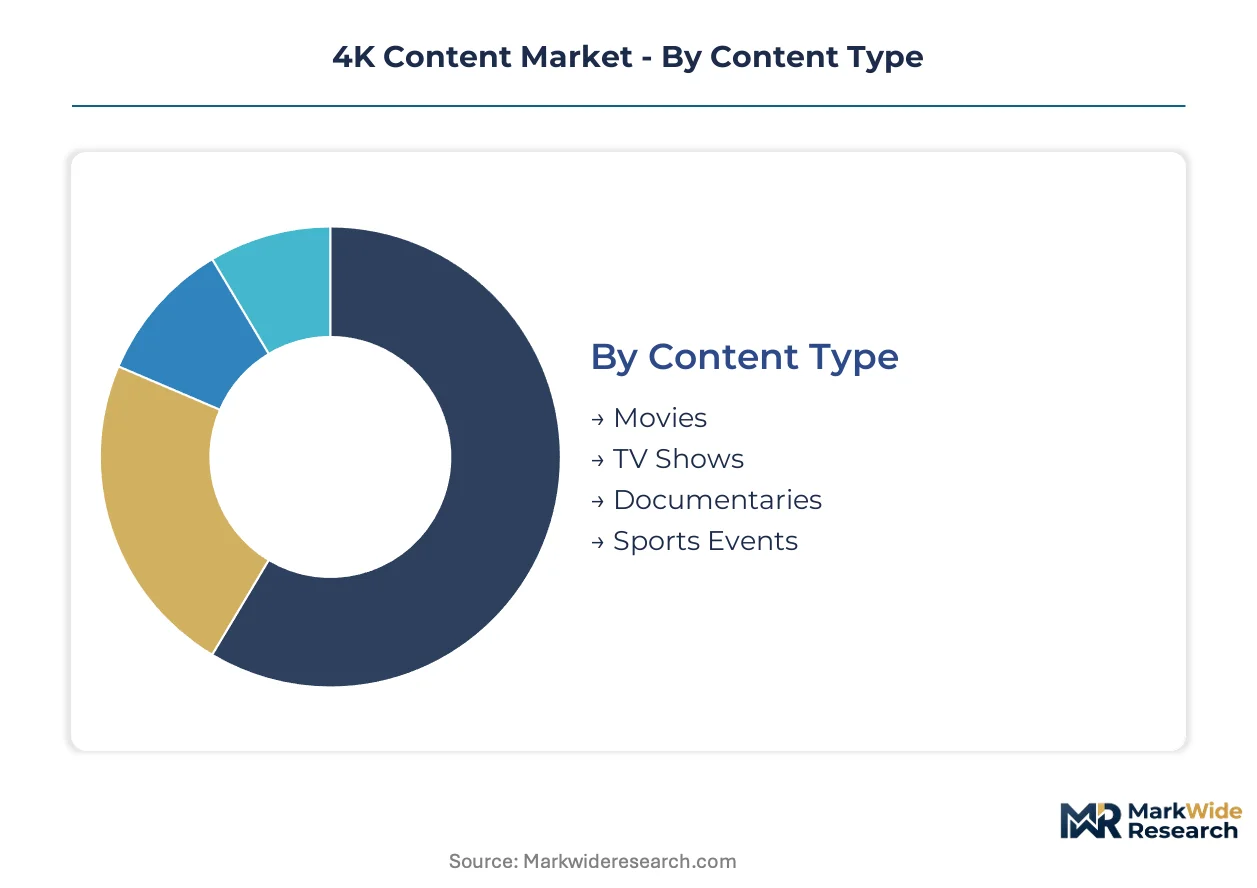
4K content segmentation reveals how compression economics, display penetration, and licensing windows fragment revenue pools across distinct consumption contexts. Each dimension exposes different margin structures and infrastructure requirements that shape platform investment priorities.
Content Type:
Movies and TV Shows operate as standalone premium offerings with established production pipelines, while Sports Events and Documentaries embed into live infrastructure and educational distribution systems respectively.
- Movies:Feature-length productions mastered at 3840×2160 resolution with HDR grading dominate premium tier subscriptions. Hollywood studios in the United States anchor licensing volumes through day-and-date streaming releases.
- TV Shows:Serialized episodic content leverages existing production infrastructure with 4K finishing becoming standard for prestige drama. Netflix and Disney Plus commission native 4K to justify subscription pricing against ad-supported tiers.
- Documentaries:Nature and science programming exploits 4K's resolution for macro cinematography and aerial footage. BBC Natural History Unit productions drive specialist catalog demand.
- Sports Events:Live native 4K production requires redundant fiber infrastructure and real-time encoding clusters. UEFA Champions League and NFL Sunday Ticket rights holders invest in stadium camera arrays to differentiate broadcast packages.
Movies lead volumes today; Sports Events is gaining share fastest.
Delivery Mode:
Cost tier separation distinguishes bandwidth-heavy streaming from ownership models where archival permanence commands price premiums.
- Streaming:Adaptive bitrate delivery via CDN edge nodes consumes the majority of 4K viewing hours. HEVC and AV1 encoding reduce per-stream bandwidth costs for platform operators serving mass audiences.
- Blu-ray:Physical media retains uncompressed bitrates up to 100 Mbps for collector markets. Japanese and German consumers sustain manufacturing volumes through boutique label distribution.
- Downloadable:File-based ownership allows offline playback on portable devices with storage constraints limiting resolution selection. Apple iTunes Store and Google Play Movies maintain transactional catalogs.
- Rental:Time-limited access through cable VOD and digital storefronts captures windowed releases before subscription availability. Amazon Prime Video channels and Apple TV app integrate rental layers.
Streaming leads volumes today; Blu-ray sustains margin concentration in collector segments.
End User:
Customer type determines whether 4K serves individual consumption, commercial exhibition, institutional licensing, or corporate communication purposes.
- Home Users:Residential subscribers with 4K-compatible displays and broadband exceeding 25 Mbps drive mass-market economics. United States households stack multiple premium services with 4K tiers.
- Cinemas:Commercial exhibition venues deploy 4K laser projection for premium large-format screens. AMC and Cineworld circuits upgrade auditoriums to justify ticket pricing against home streaming.
- Educational Institutions:Universities and museums license documentary and archival 4K for research and public programming. Kanopy and Docuseek aggregate educational distribution rights.
- Businesses:Corporate training, digital signage, and hospitality in-venue entertainment procure 4K content through B2B licensing. Hotels in Dubai and Singapore deploy 4K VOD as amenity differentiation.
Home Users lead volumes today; Cinemas is expanding most quickly in premium exhibition formats.
Device Compatibility:
Application context separates fixed-display home theater systems from portable and projection environments with varying brightness and viewing distance constraints.
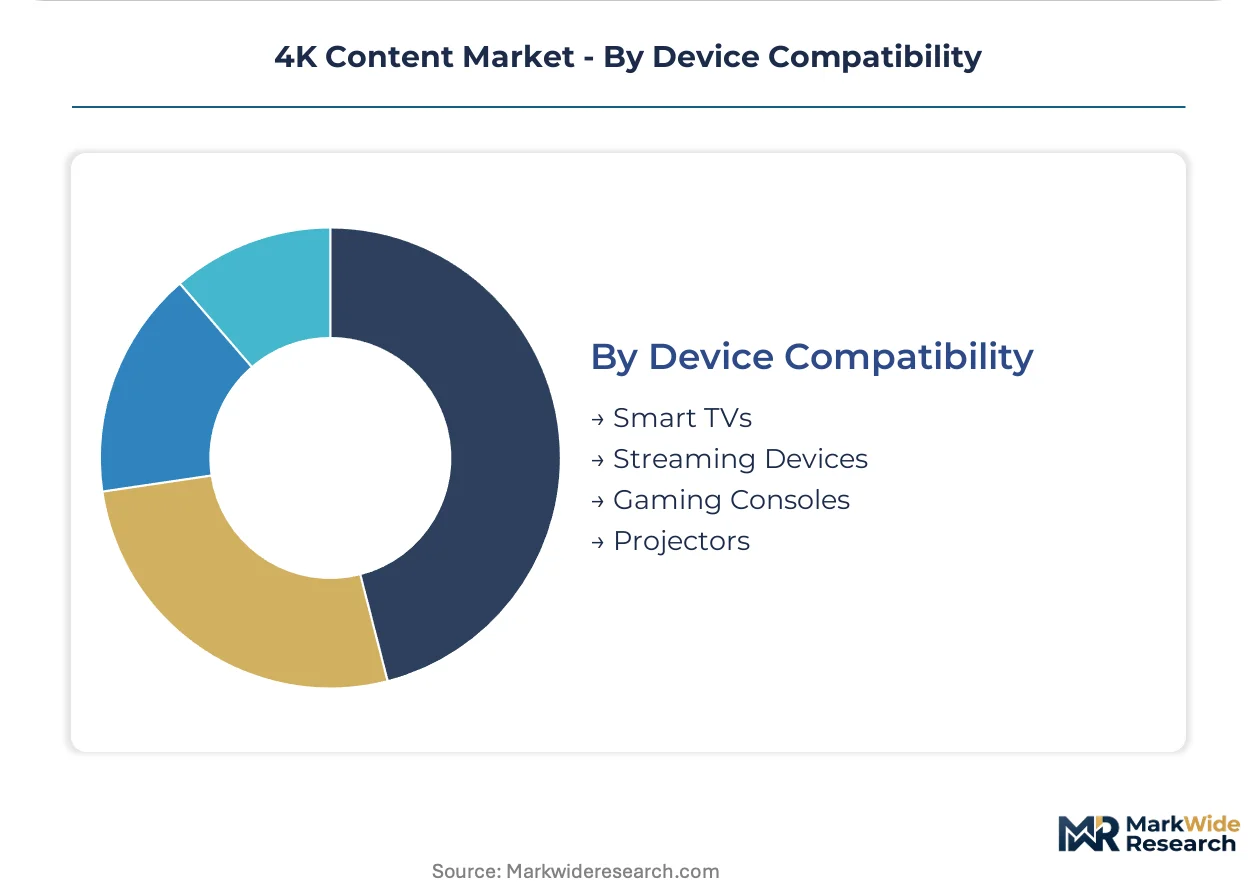
- Smart TVs:Integrated streaming applications on 55-inch and larger panels constitute the primary 4K consumption endpoint. Samsung and LG display divisions in South Korea dominate panel supply.
- Streaming Devices:External HDMI dongles and set-top boxes upgrade legacy displays. Roku and Amazon Fire TV Stick 4K Max enable 4K adoption on older television hardware.
- Gaming Consoles:PlayStation 5 and Xbox Series X render interactive 4K content with variable refresh rates. Cloud gaming services stream cinematic 4K assets beyond native hardware capability.
- Projectors:Home theater projection systems require dedicated dark-room environments for HDR effectiveness. Sony and JVC native 4K projectors serve enthusiast installations.
Smart TVs lead volumes today; Streaming Devices is climbing the fastest in emerging market broadband expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles-based production crews and London post-production houses anchor the creative workforce driving 4K content pipelines across major economies.
United States
American households maintain the highest 4K display penetration and subscription stacking rates globally, with FCC accessibility mandates shaping subtitle and audio description standards for ultra-high-definition broadcasts. The FCC mandates closed captioning and audio description requirements that 4K streaming services must integrate. Production clusters in Los Angeles and New York City generate the majority of native 4K scripted content for global distribution.
Germany
German consumers sustain a durable Blu-ray collector market demanding uncompressed bitrates, while public broadcasters invest in native 4K documentary production. The EU Green Deal's digital sustainability criteria pressure data centers serving German 4K traffic to reduce energy intensity per streamed hour. Berlin and Munich host post-production facilities specializing in HDR grading for European theatrical releases.
United Kingdom
British households demonstrate strong appetite for premium 4K tiers tied to sports rights, particularly Premier League and rugby broadcasts. The UK regulator Ofcom enforces accessibility standards aligned with FCC frameworks for streaming video services. London's Soho district concentrates color grading and mastering facilities serving international streaming platforms.
South Korea
South Korean electronics manufacturers dominate global 4K panel supply, with Samsung and LG display divisions driving hardware adoption curves. The Ministry of Trade, Industry and Energy (METI) supports next-generation broadcasting standards including 4K terrestrial transmission. Seoul's Gangnam district houses streaming platform headquarters negotiating exclusive K-content 4K licensing.
Japan
Japanese broadcasters pioneered 4K terrestrial transmission standards, with NHK's technical research influencing global codec development pathways. The Ministry of Internal Affairs and Communications regulates spectrum allocation for 4K broadcast services. Tokyo's Shibuya ward clusters streaming service operations targeting anime and J-drama 4K remastering.
4K Content Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the 4K content ecosystem, with streaming platforms owning encoding infrastructure while production houses rent camera and post-production capacity. The market structure consolidates around a handful of global subscription services controlling distribution economics, with tiered competition separating premium original producers from aggregator platforms. Three strategic archetypes dominate: vertically integrated studios with proprietary IP libraries, technology-forward platforms investing in compression R&D, and sports-rights holders building live 4K production capabilities. Competitive moves center on exclusive content licensing windows and geographic expansion through localized 4K catalog investments.
Among US-based streaming platforms, Netflix, Disney Plus, and Amazon Prime Video exemplify the vertically integrated archetype, each controlling original production pipelines and proprietary encoding infrastructure. Netflix represents the technology-forward position through proprietary compression codec deployment, while Disney Plus anchors premium tier positioning through exclusive franchise IP libraries. Amazon Prime Video occupies the bundling archetype, integrating 4K content access within broader membership economics.
| Leading Market Players |
|---|
| HBO Max |
| Peacock |
| Netflix |
| Paramount Plus |
| Hulu |
| Disney Plus |
| Apple TV |
| ESPN |
| Amazon Prime Video |
| Others |
Value Chain & Pricing Dynamics
Los Angeles-based post-production colorists and London finishing artists command wage premiums that widen spreads between premium streaming tiers and standard HD offerings. Labor-cost differentials between elite mastering facilities and volume encoding houses translate directly into subscription pricing architecture across consumer markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors consumer segmentation, with HDR grading and exclusive franchise windows differentiating top tiers from ad-supported alternatives. Price differentiation stems from compression efficiency investments and exclusive IP licensing windows. Cost compression in standard tiers is intensifying because AV1 deployment slashes bandwidth overhead. Ad-supported tiers show highest price sensitivity; collector-facing Blu-ray editions show lowest.
Supply Chain Analysis
Cross-border content licensing logistics and territorial rights-clearance freight costs complicate multi-territory rollout economics. Production concentrates in the United States, South Korea, and the United Kingdom, with post-production drawing from specialized grading facilities in Germany and Japan. Raw material dependencies include camera sensor arrays, fiber transmission infrastructure, and cloud compute instances. Single-source vulnerability in proprietary codec licensing creates legal friction. Distribution runs through CDN edge nodes and streaming platform proprietary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 4K content market functions as a stable compounder, with broadband infrastructure expansion delivering predictable demand expansion across connected households worldwide.
For Market Incumbents: Deepen proprietary compression R&D to maintain bandwidth efficiency advantages against emerging codec alternatives. Expand captive production capacity in Nordic hydroelectric-powered data center regions to preempt EU Green Deal compliance costs. Consolidation around exclusive sports live rights insulates against subscription stacking rotation behaviors.
For New Entrants and Emerging Players: Smart TV OEM pre-installation partnerships offer the most penetrable distribution channel for platform buildout. Target educational institutional licensing as an underexploited vertical with stable procurement cycles and lower content acquisition costs. Documentary and archival 4K remastering presents white-space opportunity with differentiated pricing power.
For Investors and Strategic Acquirers: Technology-forward streaming platforms with proprietary encoding infrastructure are the most active acquirer in this space, consolidating production and distribution capabilities. Long-term viability rests on exclusive IP library depth and compression patent positioning. Watch for AV1 patent pool clarification as an inflection signal for infrastructure investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Codec Deployment | Netflix's custom compression reduces per-stream bandwidth costs against HEVC baselines. |
| Exclusive Franchise Licensing | Disney Plus anchors premium tier pricing through Marvel and Star Wars 4K libraries. |
| Nordic Data Center Relocation | Amazon Web Services shifts European workloads to hydroelectric-powered regions for EU Green Deal compliance. |
| Live Sports Native Production | NFL Sunday Ticket and UEFA Champions League rights holders invest in stadium 4K camera arrays. |
| Educational Institutional Licensing | Kanopy aggregates documentary 4K rights for university library procurement channels. |
Study Parameters
Bottom-up streaming subscriber modeling reconciled against top-down content production tracking forms the analytical core of this study. Primary interviews with streaming platform CTOs, post-production facility technical directors, sports rights procurement executives, and CDN infrastructure operators combined with secondary validation against SEC 10-K filings, EU regulatory disclosure databases, and hyperscaler capex reports. Triangulation across these sources ensures segmentation accuracy.
Historical trendline analysis of resolution adoption curves and compression efficiency gains informed projection frameworks across the analysis window. Segmentation dimensions modeled include content type, delivery mode, end-user category, and device compatibility tier. CAGRs derive from fitted adoption curves calibrated against broadband penetration trajectories and display replacement cycles. Forecast inputs incorporate EU Green Deal compliance cost assumptions and AV1 deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation around data localization and algorithmic transparency mandates. Forecasts reflect assumptions about codec licensing resolution and sports rights renewal economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Anime Market
Digital Media
Sports Graphics Market
Digital Media
Video Content Management Market
Digital Media
Global Music Video Production Market
Digital Media
Playout Solutions Market
Digital Media
Mobile Entertainment Market
Digital Media
3D Animation Market
Digital Media
Webtoons Market
Digital Media
LED Stadium Screens Market
Digital Media
Global Virtual Goods Market
Digital Media
Mexico Webtoons Market
Digital Media
In Flight Entertainment Market
Digital Media
Online Gambling Market
Digital Media
Media Gateway Market
Digital Media
Video Production Market
Digital Media
Blockchain in Media and Entertainment Market