
 Media and Entertainment Market | 2026-2036
Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Media and Entertainment Market Foresight
Short-form video creator labor pools is unwinding traditional studio gatekeeping and flooding platforms with low-cost content. Netflix sustains subscriber stickiness through localized original programming across multiple continents. Warner Bros. Discovery anchors its streaming strategy around HBO's premium scripted library and live sports rights. Disney controls theatrical-to-streaming windowing with precision that protects box office while feeding Disney+.
Media and entertainment encompasses the creation, aggregation, and distribution of audio-visual and interactive content through physical and digital channels, typically encoded at bitrates ranging from 5 Mbps for standard HD to 25 Mbps for 4K streaming to ensure seamless delivery. Its primary commercial purpose is to capture consumer attention and convert it into subscription revenue, advertising inventory, or transactional purchases. Streaming within the content type dimension leads absolute revenue contribution as cord-cutting accelerates across mature markets. Online distribution channels capture the fastest growth trajectory as connected TV penetration expands broadband-dependent consumption. Virtual reality technology remains nascent in consumer adoption but commands premium pricing in location-based entertainment venues and enterprise training applications.
The Federal Communications Commission shapes US market access through net neutrality oscillations that directly impact streaming quality-of-service negotiations between platforms and internet service providers. The European Union's Digital Services Act and GDPR impose content moderation and data handling obligations that increase compliance costs for platforms operating across member states. India's Ministry of Information and Broadcasting exercises licensing authority over direct-to-home and cable operations that foreign platforms must navigate for linear distribution. Stakeholders must monitor how generative AI copyright disputes reshape content acquisition economics and creator compensation frameworks.
Market Dynamics
Streaming technology is decomposing legacy distribution hierarchies by enabling direct creator-to-consumer pathways that bypass traditional studio intermediaries and reshape how content monetizes across digital channels.
Growth Catalysts
- EU AI Act compliance mandates:European content platforms are accelerating investments in algorithmic transparency tools and audit-ready recommendation systems to meet disclosure requirements.
- India's mobile-first expansion:Low-cost data plans and regional language content libraries are drawing hundreds of millions of first-time streaming subscribers into addressable markets.
- Connected TV penetration:Broadband-dependent consumption through smart television hardware is converting linear viewers to addressable digital inventory at accelerating velocity.
Market Restraints
- Content cost inflation:Exclusive sports rights and premium scripted programming are commanding escalated licensing fees that compress platform margins.
- GDPR data handling friction:Cross-border content personalization engines face operational constraints from European data localization and consent management requirements.
- Creator labor oversupply:Short-form video platforms are flooding markets with zero-marginal-cost content that deflates per-view monetization rates for professional productions.
Strategic Opportunities
- Location-based virtual reality:Enterprise training venues and immersive entertainment installations command premium pricing for hardware-software bundled experiences.
- Generative AI content tools:Automated pre-production workflows and synthetic voice localization are compressing time-to-market for regional original programming.
- Direct-to-consumer theatrical windowing:Precision-timed streaming releases that protect box office revenue while feeding subscription growth represent underexploited yield optimization.
Industry Challenges
- Skill scarcity in AI governance:Platforms struggle to hire compliance engineers capable of building explainable recommendation systems that satisfy regulator audit demands.
- Legacy rights database fragmentation:Decades of territorial licensing agreements create legal complexity when attempting global simultaneous releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media and Entertainment Market |
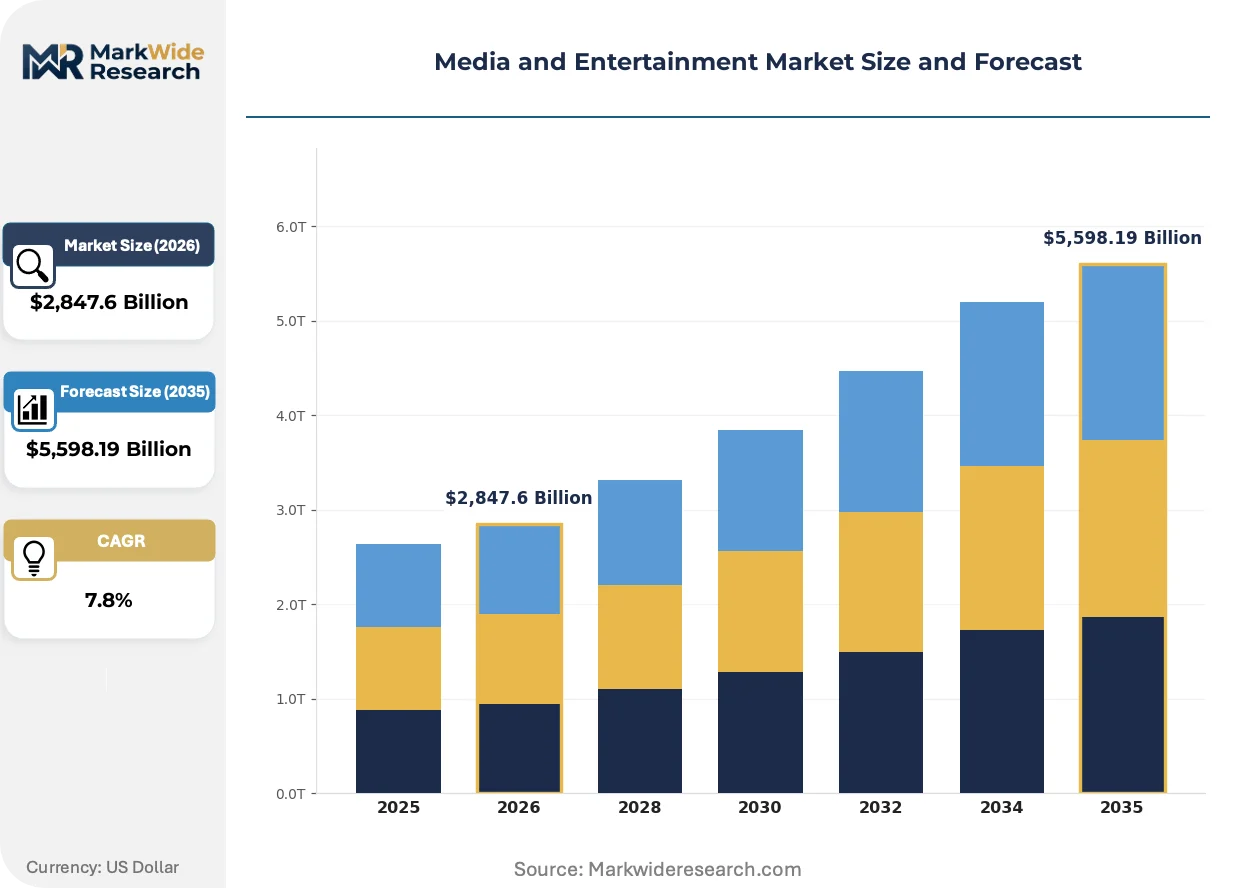
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $5,598.19 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Film, Television, Streaming, Music Distribution Channel: Cable, Satellite, Online, Theatrical End User: Consumers, Advertisers, Businesses, Content Creators Technology: Digital, Virtual Reality, Augmented Reality, 3D |
| Companies Covered | Warner Bros. Discovery, Charter Communications, Inc., Netflix, Inc., Warner Music Group Corp., Roku, Inc., The Walt Disney Company, Live Nation Entertainment, Inc., Paramount Global, Comcast Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media and Entertainment Market Shifts & Advancements
Generative AI and immersive display technologies are rewriting production economics while regulatory frameworks force transparency into previously opaque algorithmic systems.
Generative AI production pipelines are decomposing traditional pre-visualization and localization workflows by enabling synthetic voice generation, automated subtitling, and scene completion at fractions of historical cost. Mid-tier studios and regional content arms of major platforms are adopting these tools fastest, compressing production timelines from months to weeks for non-premium scripted content.
GDPR and the EU AI Act are mandating algorithmic explainability for content recommendation engines that shape user consumption patterns. European platforms must now document how ranking systems prioritize certain titles, forcing engineering teams to build audit trails that were previously proprietary black boxes. This regulatory pressure concentrates compliance costs most heavily on mid-size distributors lacking in-house legal-technical hybrid teams.
Subscription fatigue among streaming households is driving ad-supported tier adoption that unbundles premium experiences from baseline access. Younger demographics and price-sensitive markets are migrating fastest to hybrid models that trade attention for reduced monthly outlays, with Indian and Southeast Asian markets showing the most pronounced behavioral pivot toward ad-load tolerance in exchange for content breadth.
Media and Entertainment Market Segmentation
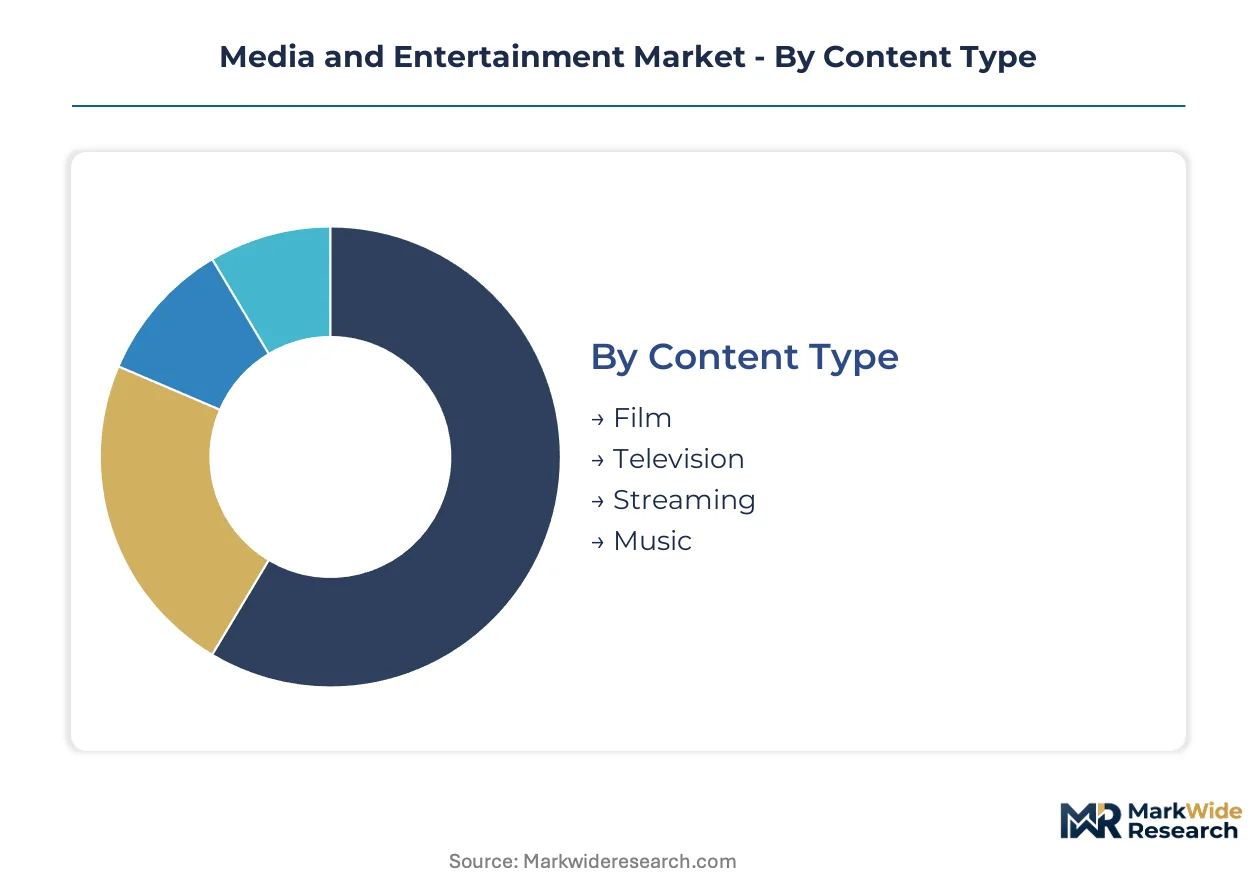
Segmentation in media and entertainment reveals how value migrates across delivery mechanisms and audience relationships. Content type determines production economics, while distribution channel selection shapes monetization velocity and margin structure.
Content Type:
Streaming faces acute substitution pressure from short-form video platforms that deliver comparable attention capture at near-zero production cost.
- Streaming:Broadband-encoded content delivered at 5-25 Mbps bitrates enables seamless 4K consumption across connected devices. Indian mobile-first consumers and Southeast Asian price-sensitive households are driving subscriber expansion through ad-supported tier adoption.
- Television:Linear broadcast and cable programming maintains residual reach among demographics resistant to digital migration. Live sports rights and appointment-viewing events preserve advertiser commitment despite cord-cutting headwinds in mature markets.
- Film:Theatrical releases anchor premium windowing strategies that protect box office revenue before streaming exclusivity.
- Music:Audio streaming platforms have displaced physical and download formats through unlimited access subscriptions.
Streaming retains volume leadership; Streaming holds the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates premium theatrical experiences from mass-market digital access.
- Online:IP-based delivery through smart TV hardware and mobile applications converts linear viewers to addressable digital inventory. Connected TV penetration accelerates broadband-dependent consumption across US and European households.
- Theatrical:Premium exhibition venues command ticket pricing power through immersive formats and social experience differentiation. Windowing precision protects box office yield while feeding downstream subscription growth.
- Cable:Legacy coaxial infrastructure retains subscribers through sports bundling and regional programming exclusives.
- Satellite:Direct-to-home broadcast maintains relevance in geographies with limited broadband penetration.
Online distribution captures the largest addressable base; Online is climbing the fastest.
End User:
Customer type determines pricing power and retention economics across the value chain.
- Consumers:Individual subscribers and transactional purchasers generate recurring revenue through monthly commitments or per-title rentals. Subscription fatigue drives ad-supported tier migration among price-sensitive demographics.
- Advertisers:Brand marketers purchase addressable inventory against streaming viewership data and connected TV impression metrics. GDPR consent management constrains personalization precision in European markets.
- Businesses:Enterprise licensing for venue exhibition, corporate training, and hospitality applications commands bulk pricing arrangements.
- Content Creators:Individual producers and studio entities monetize intellectual property through platform revenue-sharing and direct fan relationships.
Consumers anchor absolute revenue contribution; Advertisers are gaining share fastest as ad-supported tiers proliferate.
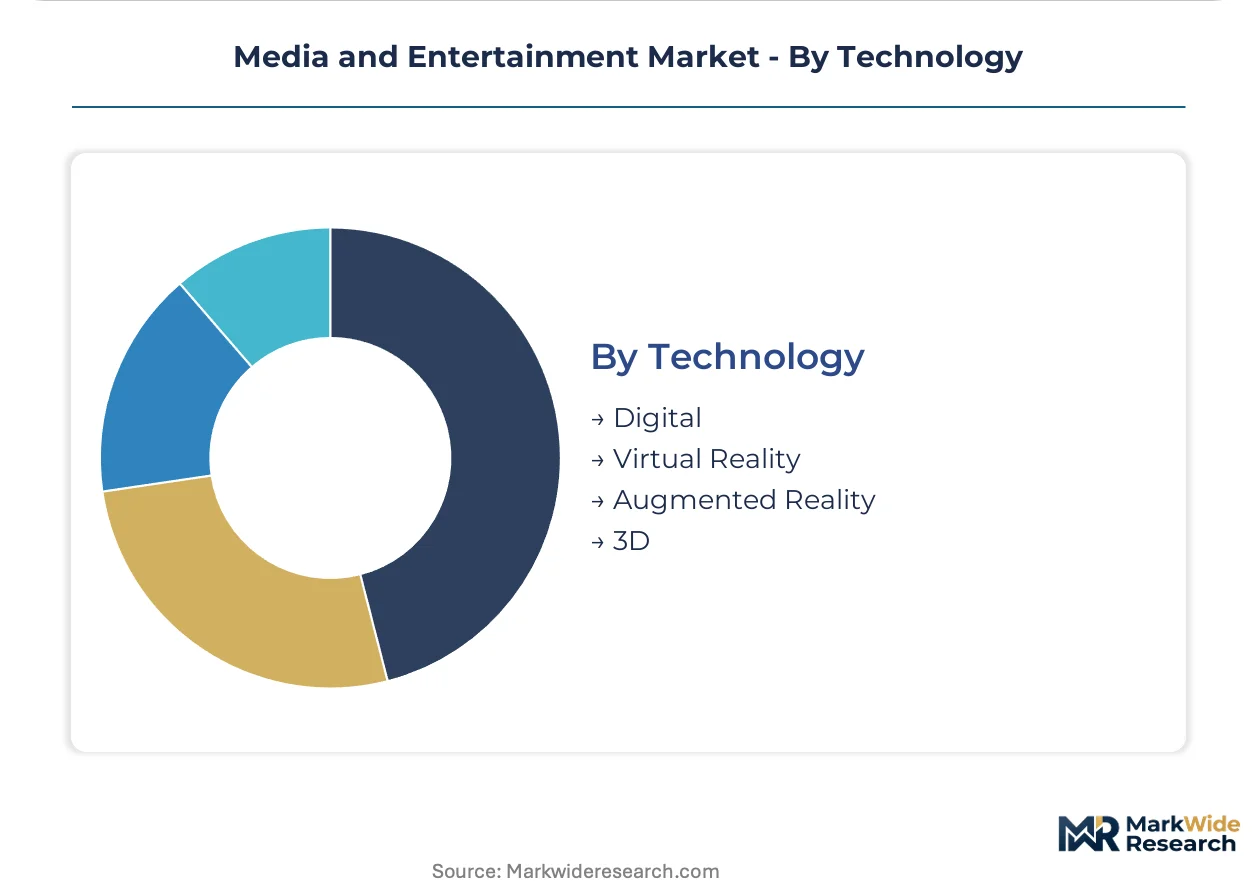
Technology:
Maturity stage separates mass-market digital deployment from nascent immersive formats.
- Digital:Standard encoding and compression protocols enable global content distribution at scale. EU AI Act compliance mandates accelerate investment in algorithmic transparency tools for recommendation engines.
- Virtual Reality:Headset-dependent immersive experiences command premium pricing in location-based entertainment venues and enterprise training applications. Hardware cost barriers constrain consumer household penetration.
- Augmented Reality:Overlay graphics and interactive elements enhance live events and mobile gaming applications.
- 3D:Stereoscopic exhibition formats retain niche theatrical deployment for blockbuster tentpole releases.
Digital technology dominates installed base; Virtual Reality shows the steepest expansion trajectory among emerging formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streaming consumption patterns diverge sharply by geography: US households favor connected TV bundles, Indian users prioritize mobile-first regional content, and European markets demand algorithmic transparency that slows personalization deployment.
United States
Connected TV penetration and sports streaming bundles drive broadband-dependent consumption across suburban and urban households. The FCC shapes market access through net neutrality oscillations that directly impact streaming quality-of-service negotiations between platforms and internet service providers. Los Angeles anchors production concentration as legacy studios and tech-native distributors compete for creative talent and soundstage capacity.
India
Low-cost data plans and regional language content libraries draw hundreds of millions of first-time streaming subscribers into addressable markets. The Ministry of Information and Broadcasting exercises licensing authority over direct-to-home and cable operations that foreign platforms must navigate for linear distribution. Mumbai and Hyderabad concentrate original programming investment as platforms localize production infrastructure for Hindi and South Indian language markets.
Germany
GDPR consent management constrains personalization precision while driving investment in audit-ready recommendation systems. The EU AI Act mandates algorithmic explainability for content ranking engines that shape user consumption patterns. Berlin and Munich host compliance engineering clusters where mid-size distributors build legal-technical hybrid teams to satisfy regulator audit demands.
United Kingdom
Subscription fatigue accelerates ad-supported tier migration among price-sensitive demographics seeking content breadth over premium exclusivity. Ofcom regulates broadcast standards and streaming platform accountability under evolving digital competition frameworks. London concentrates global headquarters for multinational platforms managing European content licensing and talent acquisition.
South Korea
High-bandwidth infrastructure enables seamless 4K streaming adoption across densely connected urban households. The Korea Communications Commission enforces content rating and platform competition rules that shape local and foreign operator market entry. Seoul anchors K-content export production as streaming platforms invest in original programming for global distribution.
Media and Entertainment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven studios and platform-agnostic distributors occupying distinct competitive positions. The market structure favors entities controlling both content libraries and direct distribution channels. Three archetypes dominate: vertically integrated studios with theatrical-to-streaming windowing precision, hardware-software bundlers capturing connected TV penetration, and talent-representation hybrids monetizing live experience and intellectual property. Competitive intensity centers on exclusive sports rights acquisition and generative AI content tool deployment.
Among US-based integrated studios, Warner Bros. Discovery and The Walt Disney Company exemplify the vertically consolidated archetype, while Netflix, Inc. occupies a position as the technology-native distributor with global original programming infrastructure. These entities represent contrasting strategic postures: legacy studio asset integration versus algorithm-driven content personalization at scale.
| Leading Market Players |
|---|
| Warner Bros. Discovery |
| Charter Communications, Inc. |
| Netflix, Inc. |
| Warner Music Group Corp. |
| Roku, Inc. |
| The Walt Disney Company |
| Live Nation Entertainment, Inc. |
| Paramount Global |
| Comcast Corporation |
| Others |
Supply & Pricing Matrix
Long-term sports rights offtake agreements lock in both exclusive content access and predictable subscriber pricing for streaming platforms negotiating with leagues across North America and Europe. These multi-year contracts anchor platform value propositions while exposing buyers to escalator clauses that compress margins when audience fragmentation accelerates.
Pricing Analysis
Long-term offtake structures dominate premium content acquisition, with platforms committing to escalating fees for exclusive sports rights and scripted originals that span five to ten year windows. Price differentiation rests on content tier exclusivity and regional licensing scope, with global simultaneous releases commanding premiums over staggered territorial windows. Cost compression in ad-supported tiers is intensifying because short-form video platforms flood markets with zero-marginal-cost alternatives. Emerging market consumers exhibit highest price sensitivity, while US and European households show greater tolerance for subscription stacking when bundled with broadband or mobile services.
Supply Chain Analysis
Los Angeles production infrastructure serves as a chokepoint where soundstage capacity constraints and below-the-line labor shortages delay original programming timelines for multiple platforms. Content supply concentrates in the United States, India, and South Korea, with Mumbai and Hyderabad expanding regional language production capacity for Southeast Asian distribution. Raw material dependencies span physical production equipment, cloud rendering compute, and synthetic media training datasets. Single-source vulnerability runs through concentrated visual effects houses and localized dubbing talent pools. Distribution runs through IP-based delivery networks that bypass legacy cable and satellite intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are shifting toward interoperability ecosystems where content libraries, recommendation engines, and advertising stacks must integrate across hardware-software boundaries to capture household attention.
For Market Incumbents: Fortify exclusive sports rights positions through early renewal negotiations that preempt competitive bidding wars. Deepen in-house production of regional original programming to reduce licensing exposure and build subscriber stickiness against short-form video substitution. Control downstream distribution through connected TV operating system partnerships that gatekeep audience access. For New Entrants and Emerging Players: Lead with generative AI-enabled content localization that compresses time-to-market for non-English language markets underserved by major platforms. Target India's mobile-first subscriber base through ad-supported tier pricing that matches regional data cost structures. Pursue white-label content aggregation partnerships with telecom operators seeking bundled streaming offerings. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated studios with theatrical-to-streaming windowing precision and proprietary IP libraries that sustain franchise monetization across decades. Long-term viability hinges on controlling both content creation and direct distribution channels rather than relying on platform-agnostic licensing. Watch generative AI copyright litigation outcomes as a signal for whether synthetic content tools expand or contract production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Sports Rights Acquisition | Live event content anchors subscriber retention against churn in mature streaming markets. |
| Generative AI Content Localization | Synthetic voice and automated subtitling compress regional original production timelines for Indian and Southeast Asian markets. |
| Connected TV Operating System Partnership | Hardware-software bundling gates audience access and captures addressable advertising inventory at scale. |
| Ad-Supported Tier Expansion | Subscription fatigue conversion unlocks price-sensitive demographics in emerging markets through attention-for-access tradeoffs. |
| Algorithmic Transparency Investment | EU AI Act compliance builds audit-ready recommendation systems that preempt regulatory enforcement action. |
Research Methodology
A spread of perspectives from streaming platform executives, content licensing directors, advertising technology specialists, and regulatory compliance officers converged on the working assumptions governing subscriber growth and monetization trajectories. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU regulatory impact assessments, TRAI sector reports, and connected TV penetration databases. Bottom-up subscriber and revenue modeling triangulated against top-down addressable market sizing across the analysis window.
Segmentation dimensions modeled include content type, distribution channel, end user archetype, and technology deployment format, with regional regulatory clusters treated as distinct forecast inputs. CAGRs were derived from trend extrapolation anchored in documented subscriber additions and pricing tier migrations. Forecast inputs incorporated broadband infrastructure buildout timelines, mobile data cost curves, and territorial licensing agreement renewal schedules.
The analysis sits within stated boundaries; outcomes outside sustained cord-cutting velocity, stable regulatory enforcement patterns, or contained content cost inflation would require recalibration. Forecasts reflect assumptions about platform competitive dynamics and technology adoption curves that may shift with generative AI deployment or antitrust intervention. Practitioners should keep alternative scenarios live as EU algorithmic transparency requirements and India mobile data pricing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Africa Animation Market
Digital Media
Stock Photography Market
Digital Media
Digital Media Production Software Market
Digital Media
North America Webtoons Market
Digital Media
VFX Market
Digital Media
Middle East and Africa Animation Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Mexico Webtoons Market
Digital Media
Video Player Market
Digital Media
Anime Merchandising Market
Digital Media
Europe Online Video Platform Market
Digital Media
Pro AV Market
Digital Media
Playout Solutions Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
3D Animation Market
Digital Media
Online Art Market