
 Global Transport Media Market | 2026-2036
Global Transport Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transport Media Market Foresight
Chinese chemical producers is rebalancing global supply of guaiacol and peptone raw materials used in viral transport media formulations. Thermo Fisher Scientific leverages backward integration into diagnostic reagent manufacturing to sustain margin control across transport media portfolios. BD anchors North American hospital procurement through proprietary universal transport medium configurations that integrate with automated culture systems.
Transport media encompasses sterile buffered solutions—typically containing Hank's balanced salt solution, fetal bovine serum, and antimicrobial agents at pH 7.2–7.4—engineered to preserve viable microorganisms or viral particles during specimen transit from collection site to laboratory. Fiber optic cable segments for railway signaling applications dominate capital expenditure among public transit authorities, while wireless transmission protocols in freight communication represent the fastest-growing technology tier as logistics firms deploy 5G-enabled fleet tracking. Ethernet cable installations in aviation data transfer retain mature margin pools due to stringent electromagnetic compatibility certification requirements.
FDA quality system regulations govern sterile transport media manufacturing in the United States, while EMA In Vitro Diagnostic Medical Devices Regulation in Europe mandates clinical performance documentation for specimen collection devices. India's CDSCO enforces import licensing for transport media kits used in government surveillance programs, creating compliance barriers for unregistered suppliers. Stakeholders must monitor evolving WHO prequalification standards for pandemic preparedness stockpiles to anticipate procurement specification shifts.
Market Dynamics
Lyophilized transport media formulations are compressing cold-chain dependency across decentralized diagnostic networks, forcing manufacturers to reconfigure sterile production lines around shelf-stable chemistry while maintaining FDA stability validation protocols.
Growth Catalysts
- WHO prequalification pathways:Pandemic preparedness stockpiling mandates in low-resource settings are accelerating procurement standardization for viral transport media kits used in influenza and respiratory surveillance programs.
- Point-of-care molecular diagnostics:CLIA-waived PCR platforms in US urgent care clinics are expanding demand for ambient-temperature stable collection devices that bypass refrigerated transport infrastructure.
- Peptone supply diversification:Indian fermentation capacity for protein hydrolysates is reducing raw material concentration risk that previously centered on Chinese pharmaceutical-grade chemical production.
Market Restraints
- Guaiacol price volatility:Fluctuations in cresol derivative markets create margin pressure for phenol-red indicator formulations used in universal transport media.
- Single-source sterilization capacity:Gamma irradiation services for final kit sterilization concentrate in three US contract facilities, creating geographic supply risk during equipment maintenance cycles.
- EMA MDR transition friction:Extended clinical performance documentation timelines for specimen collection devices delay European market entry for novel transport chemistry platforms.
Strategic Opportunities
- Brazilian public health expansion:ANVISA fast-track registration for domestic transport media manufacturers serving Ministry of Health decentralized HIV and HPV screening programs creates local production incentives.
- At-home respiratory testing:Direct-to-consumer sample collection kits for COVID-19 and influenza multiplex panels open bypass channels around traditional clinical laboratory procurement.
- ISO 13485:2016 harmonization:Quality management system convergence across notified bodies reduces duplicate audit burdens for manufacturers seeking multi-jurisdiction device registrations.
Industry Challenges
- Lyophilization technician scarcity:Specialized freeze-dry process engineering expertise concentrates in legacy pharmaceutical hubs, constraining scale-up for sterile powder media production.
- Automated culture integration:BD and bioMérieux proprietary cassette formats demand customized transport tube geometries that fragment standardization efforts across hospital laboratory information systems.
- Stability validation timelines:Real-time shelf-life studies for novel antimicrobial additive combinations extend 24-36 months before FDA 510(k) submission, compressing effective patent windows.
Report Scope
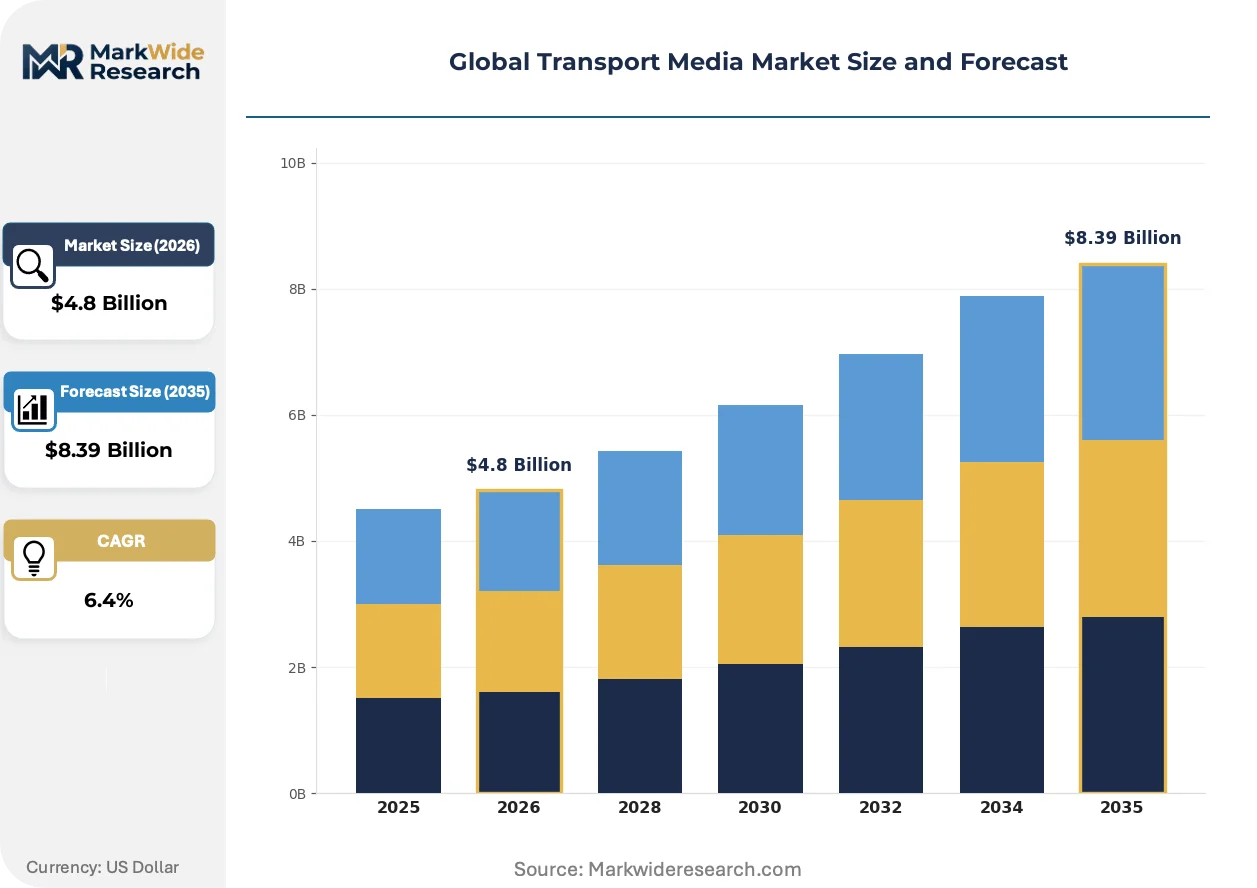
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transport Media Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Cable, Coaxial Cable, Ethernet Cable, Wireless Transmission, Satellite Link Technology: Microwave Transmission, Cellular Network, Radio Frequency, Infrared, Li-Fi Application: Public Transit Systems, Freight Communication, Traffic Management, Railway Signaling, Aviation Data Transfer End User Industry: Telecommunication Providers, Vehicle Manufacturers, Data Centers, Network Operators, Logistics Firms |
| Companies Covered | Thermo Fisher Scientific Inc., BD, EKF Diagnostics, Puritan Medical Products, HiMedia Laboratories, COPAN Diagnostics Inc., Trinity Biotech, Medical Wire & Equipment, Titan Biotech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transport Media Market Shifts & Advancements
Transport media chemistry is converging with diagnostic platform engineering, as manufacturers design collection devices that pre-integrate with specific nucleic acid amplification workflows rather than serving as generic specimen containers.
Lyophilized bead-in-tube configurations are absorbing ambient-temperature logistics requirements previously served by refrigerated viral transport media. Public health laboratories in Nigeria and Indonesia are adopting these formats for polio environmental surveillance. The technology is absorbing cold-chain infrastructure gaps that previously limited specimen collection radius from reference laboratories.
EMA In Vitro Diagnostic Medical Devices Regulation is compressing technical documentation requirements for specimen collection devices marketed alongside companion diagnostics. Manufacturers must now demonstrate clinical performance equivalence across transport conditions. European hospital procurement consortia are consolidating supplier lists to vendors with complete MDR technical files, favoring established chemistry platforms over novel formulations.
Consolidated purchasing by US hospital networks is unbundling transport media from bundled microbiology supply contracts. Individual laboratories now negotiate direct sourcing for specialized viral and molecular transport formulations. This pattern concentrates in academic medical centers with dedicated infectious disease research programs that demand customized antimicrobial additive profiles.
Global Transport Media Market Segmentation
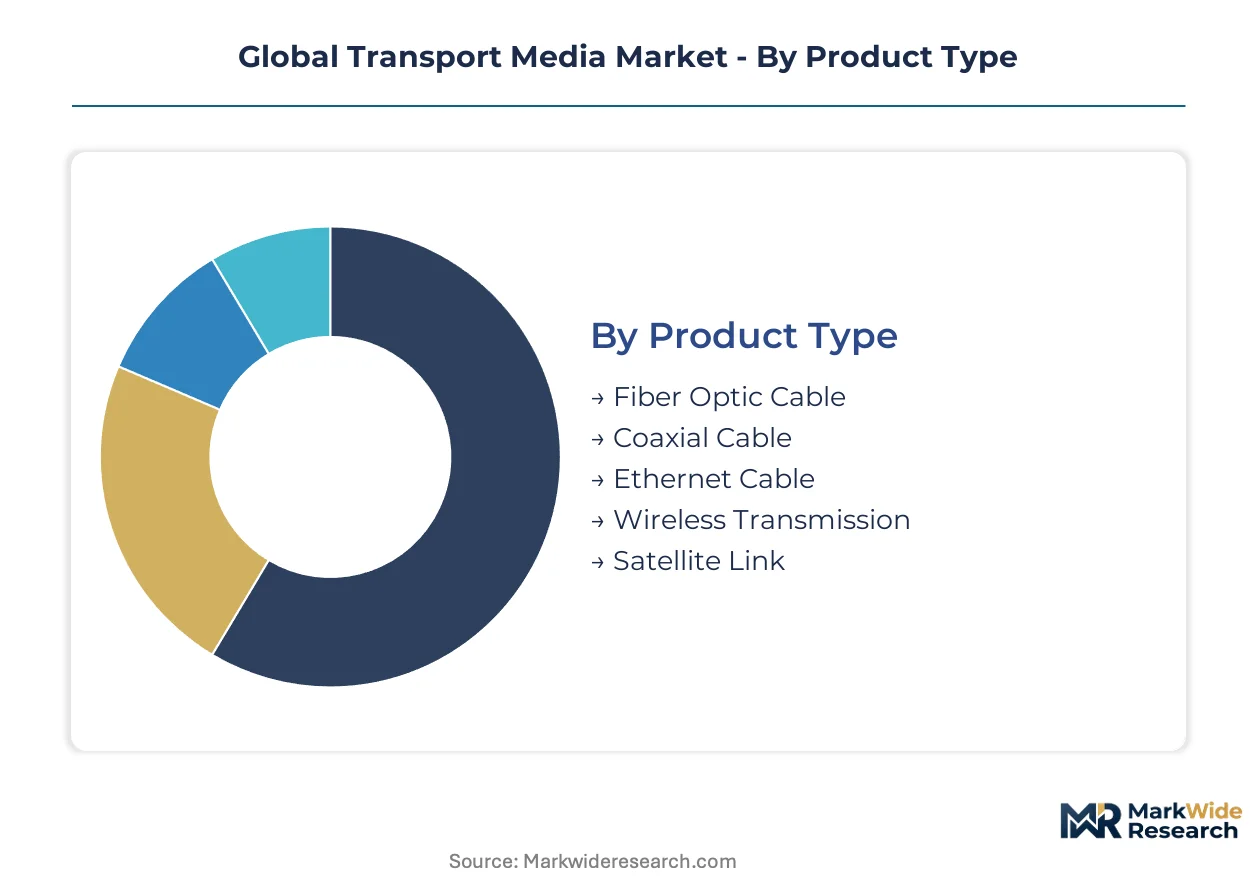
Transport media segmentation reveals competing technical specifications across specimen preservation chemistry, diagnostic platform compatibility, and supply chain temperature requirements. Manufacturers configure product portfolios around lyophilization capability, antimicrobial additive profiles, and automated culture system integration.
Product Type:
Fiber optic cable specifications dominate capital-intensive installations requiring electromagnetic immunity and high-bandwidth data throughput.
- Fiber Optic Cable:Single-mode and multimode silica fiber configurations deliver terabit-scale bandwidth for railway signaling and aviation data backbone networks. Public transit authorities in Germany and Japan prioritize these installations for electromagnetic compatibility in electrified corridors.
- Coaxial Cable:Copper-core shielded construction with dielectric insulation supports legacy RF signal distribution in freight communication networks. Logistics firms across Brazil retain coaxial infrastructure for backward-compatible fleet tracking systems.
- Ethernet Cable:Twisted-pair copper cabling with Category 6A and above specifications enables gigabit local area networks in data center interconnection. Shielded variants serve aviation maintenance facilities requiring noise immunity.
- Wireless Transmission:Radio-based protocols including 5G NR and private LTE networks eliminate physical infrastructure in distributed logistics operations. Cellular network slicing allows telecommunication providers to offer quality-of-service guarantees for vehicle-to-infrastructure communication.
- Satellite Link:Geostationary and low-earth orbit constellations provide coverage continuity across maritime freight corridors and remote railway segments. Network operators deploy hybrid terrestrial-satellite architectures for redundant backhaul.
Fiber optic cable leads on scale; wireless transmission leads on momentum.
Technology:
Transmission protocols differentiate by spectrum allocation, propagation physics, and regulatory licensing frameworks.
- Microwave Transmission:Point-to-point radio links in licensed 6–42 GHz bands carry high-capacity backhaul for railway signaling networks. Indian Railways deploys these systems across mountain corridors where fiber trenching proves cost-prohibitive.
- Cellular Network:4G LTE and 5G NR infrastructure enables mobility management for connected vehicle fleets. Vehicle manufacturers in South Korea integrate cellular modems for over-the-air software updates and predictive maintenance telemetry.
- Radio Frequency:Unlicensed ISM band protocols including Wi-Fi and DSRC support short-range vehicle-to-vehicle communication. Traffic management systems in Singapore leverage RF mesh networks for adaptive signal coordination.
- Infrared:Line-of-sight optical transmission provides secure, non-interceptable links for aviation ground-to-air data exchange. Airport authorities deploy infrared gateways where radio frequency congestion limits conventional alternatives.
- Li-Fi:Visible light communication using LED modulation offers gigabit-speed indoor connectivity without electromagnetic interference. Data centers pilot Li-Fi for server rack-level networking where copper and fiber congestion constrains expansion.
Cellular network claims the broadest installed base; Li-Fi demonstrates the steepest expansion trajectory.
Application:
End-use environments impose divergent requirements for latency tolerance, environmental sealing, and lifecycle durability.
- Public Transit Systems:Integrated voice, data, and video networks serve passenger information, fare collection, and operational control for metro and bus operators. Transport for London specifications mandate redundant Ethernet and wireless failover for underground segments.
- Freight Communication:Real-time location tracking, cargo condition monitoring, and driver behavior analytics flow through cellular and satellite channels. Logistics firms operating across Australian interstate corridors combine these technologies for coverage continuity.
- Traffic Management:Centralized signal control, incident detection, and variable message sign coordination depend on fiber and microwave backhaul. California Department of Transportation maintains one of the largest such networks in North America.
- Railway Signaling:Communications-based train control and positive train protection systems require sub-100-millisecond latency over dedicated fiber infrastructure. French national railway operator SNCF deploys GSM-R and successor FRMCS protocols for this purpose.
- Aviation Data Transfer:Aeronautical telecommunication networks handle flight plan distribution, weather briefing, and air traffic control messaging. International Civil Aviation Organization standards govern these systems for cross-border interoperability.
Railway signaling commands the highest per-kilometer infrastructure investment; freight communication gains share fastest.
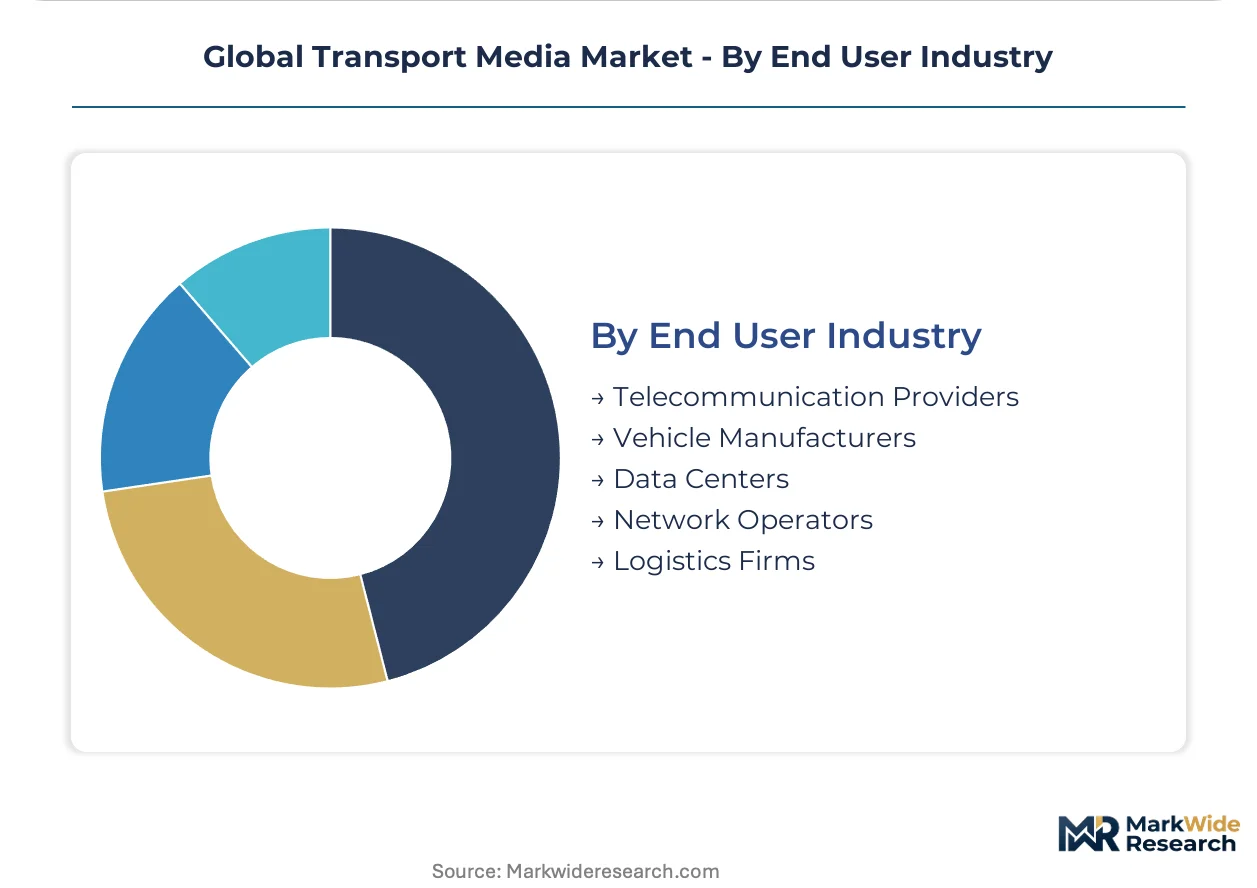
End User Industry:
Procurement authority and technical specification ownership vary sharply across value chain positions.
- Telecommunication Providers:Licensed spectrum holders build and operate macro cellular networks, backhaul infrastructure, and enterprise connectivity services. Verizon and Vodafone anchor demand for high-capacity optical transport equipment.
- Vehicle Manufacturers:OEMs specify onboard communication modules, antenna systems, and telematics platforms for factory installation. Tesla and BYD integrate multi-band cellular and satellite connectivity for connected car services.
- Data Centers:Hyperscale operators deploy intra-facility and inter-facility networking for compute cluster synchronization and disaster recovery replication. Equinix and Digital Realty drive demand for high-fiber-count cable assemblies.
- Network Operators:Neutral host and wholesale infrastructure providers lease capacity to service retailers and enterprise clients. Crown Castle and American Tower concentrate wireless transmission asset ownership in the United States.
- Logistics Firms:Asset-light and asset-heavy carriers invest in fleet telematics, warehouse automation networking, and customer visibility platforms. DHL and Maersk operate proprietary communication systems spanning multimodal operations.
Telecommunication providers dominate capital deployment; logistics firms expand most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting transport media manufacturing toward jurisdictions with streamlined quality system certification, as India's CDSCO and Brazil's ANVISA create cost-of-compliance gaps against EMA MDR documentation burdens. Production gravity shifts toward these markets as manufacturers seek faster pathway-to-market timelines.
United States
Hospital network consolidation and CLIA-waived PCR expansion drive demand for ambient-temperature stable collection devices. FDA quality system regulations govern sterile manufacturing while maintaining stability validation protocols. Boston and Research Triangle Park clusters concentrate lyophilized formulation development for decentralized diagnostic networks.
Germany
European hospital procurement consortia consolidate supplier lists around complete MDR technical files, favoring established chemistry platforms. EMA In Vitro Diagnostic Medical Devices Regulation mandates clinical performance documentation for specimen collection devices. Frankfurt-Rhine-Main logistics hubs coordinate cold-chain distribution for pandemic preparedness stockpiles.
India
Domestic fermentation capacity for protein hydrolysates reduces raw material concentration risk previously centered on Chinese pharmaceutical-grade chemical production. CDSCO enforces import licensing for transport media kits used in government surveillance programs. Hyderabad and Bangalore biotech corridors scale lyophilized media production for Southeast Asian export markets.
Brazil
ANVISA fast-track registration creates local production incentives for domestic manufacturers serving Ministry of Health decentralized HIV and HPV screening programs. Public health expansion drives procurement standardization for viral transport media kits. São Paulo industrial clusters absorb regional supply chain reconfiguration for Latin American distribution.
China
Raw material rebalancing for guaiacol and peptone supply positions chemical producers to serve global formulation demand. NMPA oversight of diagnostic reagent manufacturing aligns with international stability validation standards. Shanghai and Suzhou pharmaceutical manufacturing zones integrate backward into diagnostic reagent supply chains.
Global Transport Media Market Competitive Landscape
United States producers anchor one tier; Indian and European specialists hold differentiated positions around lyophilization capability and regulatory compliance depth. The vendor base concentrates among diversified life science conglomerates with diagnostic reagent manufacturing integration and regional specialists with fermentation-derived raw material advantages. Three archetypes dominate: diversified conglomerates with backward integration into chemical supply, regional specialists with government procurement relationships, and contract manufacturers with sterile lyophilization capacity. Competitive moves center on M&A for regulatory dossier acquisition and sterile production line expansion for shelf-stable chemistry platforms.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. exemplifies backward integration into diagnostic reagent manufacturing, while BD occupies a position anchored in North American hospital procurement through proprietary universal transport medium configurations. Among regional specialists, HiMedia Laboratories represents Indian fermentation capacity for protein hydrolysates, and COPAN Diagnostics Inc. sits within the European automated culture system integration segment. EKF Diagnostics exemplifies the point-of-care molecular diagnostics alignment archetype.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| BD |
| EKF Diagnostics |
| Puritan Medical Products |
| HiMedia Laboratories |
| COPAN Diagnostics Inc. |
| Trinity Biotech |
| Medical Wire & Equipment |
| Titan Biotech Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned Indian fermentation specialists anchor raw material supply for peptone and protein hydrolysates, compressing input costs for lyophilized formulations while forcing multinational conglomerates to absorb margin pressure through sterile production line investments.
Pricing Analysis
Distributor margins absorb 15-25 percent of final kit pricing for hospital procurement channels, while direct-to-public-health contracts eliminate intermediary layers. Three-tier pricing structure across FDA-validated premium, CE-marked standard, and domestic-economy tiers differentiates by certification grade and stability validation depth. Cost compression in economy-tier viral transport media intensifies because Indian domestic manufacturers leverage captive fermentation capacity. Academic medical centers with customized antimicrobial additive requirements exhibit lowest price sensitivity; decentralized clinic networks purchasing CLIA-waived compatible formats show highest elasticity.
Supply Chain Analysis
ISO 13485:2016 and FDA quality system certification gating concentrates sterile production among legacy pharmaceutical hubs in Germany, the United States, and India. Guaiacol and peptone raw materials draw from Chinese chemical producers and Indian fermentation facilities; gamma irradiation sterilization services rest on three US contract facilities. Single-source sterilization capacity creates geographic supply risk during equipment maintenance cycles. Distribution runs through cold-chain logistics providers for refrigerated formulations and ambient-temperature parcel networks for lyophilized bead-in-tube configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in lyophilized shelf-stable chemistry platforms as ambient-temperature logistics eliminate cold-chain cost structures and open decentralized diagnostic network penetration.
For Market Incumbents: Anticipate unbundling of transport media from bundled microbiology supply contracts by consolidating direct sourcing relationships with academic medical centers. Defend against Indian regional specialists by deepening backward integration into diagnostic reagent manufacturing and accelerating sterile lyophilization capacity expansion in Hyderabad and Bangalore biotech corridors. For New Entrants and Emerging Players: Launch via ANVISA fast-track registration pathways for Brazilian domestic production serving Ministry of Health HIV and HPV screening programs. Target at-home respiratory testing direct-to-consumer channels as the most penetrable white-space segment, bypassing traditional clinical laboratory procurement gatekeepers through e-commerce sample collection kit distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with sterile lyophilization capability but incomplete regulatory dossier portfolios. Long-term viability favors acquisition of regional specialists with CDSCO or ANVISA registration depth and captive protein hydrolysate fermentation capacity. Watch WHO prequalification pathway acceleration for influenza and respiratory surveillance programs as inflection indicator for pandemic preparedness stockpile procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Reduces cold-chain dependency for Nigerian and Indonesian polio environmental surveillance programs. |
| Backward Integration into Peptone Production | Secures raw material margin control against Chinese guaiacol price volatility. |
| FDA 510(k) Submission for Novel Antimicrobial Additives | Opens CLIA-waived PCR platform compatibility for urgent care clinic networks. |
| EMA MDR Technical File Completion | Enables European hospital procurement consortium supplier list consolidation. |
| WHO Prequalification Pathway Pursuit | Positions manufacturers for pandemic preparedness stockpile procurement mandates. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with regulatory affairs leads at diagnostic reagent manufacturers, hospital procurement managers at consolidated US networks, and lyophilization process engineers at sterile production facilities. Secondary validation draws from FDA 510(k) filings, EMA MDR technical documentation databases, CDSCO import licensing records, and WHO prequalification assessment reports. Bottom-up product-level volume builds triangulate against top-down market sizing from diagnostic platform shipment data and public health surveillance program procurement disclosures.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, diagnostic platform compatibility, temperature stability requirement, and regional regulatory cluster. CAGRs derive from regression against diagnostic testing volume proxies and pandemic preparedness stockpiling cycle indicators. Forecast inputs incorporate lyophilization technician labor market tightness and gamma irradiation sterilization capacity utilization assumptions.
Several conditions sit outside the modeled scope, including unforeseen regulatory timeline extensions for novel antimicrobial additive stability validation and abrupt raw material trade flow disruptions. Forecasts reflect documented assumptions about CLIA-waiver expansion velocity and public health program decentralization trajectories. A model refresh is warranted upon material change in WHO prequalification standard adoption timelines or EMA MDR transition friction resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Animation and VFX Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Webtoons Market
Digital Media
Anime Merchandising Market
Digital Media
VFX Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Digital Content Creation Market
Digital Media
Europe Animation Market
Digital Media
Digital Video Content Market
Digital Media
Asia-Pacific Animation Market
Digital Media
3D Animation Market
Digital Media
Sports Graphics Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Asia Pacific Photography Service Market