
 Europe Animation Market | 2026-2036
Europe Animation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Animation Market Foresight
Cloud-based rendering infrastructure is broadening cost structures across European animation houses, replacing capital-intensive on-premise server farms with elastic compute models. Aardman Animations leverages its Bristol-based claymation heritage to sustain premium brand positioning in stop-motion theatrical releases. BluBlu Studios anchors its Warsaw operations around commercial motion graphics for advertising clients, while Blue-Zoo Animation Studio competes through London-based children's television production with established broadcaster relationships.
Europe animation encompasses the design, production, and post-processing of moving image content through frame-by-frame manipulation, typically requiring 24 frames per second for broadcast-standard output and leveraging digital compositing pipelines for final delivery. Its primary commercial purpose spans entertainment distribution, advertising communication, and educational content delivery across multiple screen formats. Streaming platforms represent the fastest-expanding distribution channel as subscriber-funded content budgets displace traditional broadcaster commissioning models, while 3D animation leads technique-based value capture due to higher per-minute production costs and expanded use in feature film and premium series work. Stop motion retains specialized margin pools in theatrical and prestige segments where tactile craft differentiation commands premium licensing terms.
France's CNC tax rebate scheme, the United Kingdom's Film Tax Relief administered by HMRC, and the EU's AVMSD content quota framework collectively shape production location decisions and cross-border financing structures across the region. EMA guidelines on advertising content targeting minors further constrain animation deployment in certain commercial applications, particularly affecting campaigns directed at children. Stakeholders must monitor how national subsidy program revisions interact with platform consolidation trends to determine sustainable studio capacity planning across the continent.
Market Dynamics
Streaming platform consolidation is compressing commissioning timelines across European animation houses while simultaneously elevating content quality thresholds as subscriber-funded budgets displace traditional broadcaster pipelines.
Growth Catalysts
- AVMSD Content Quotas:The EU's Audiovisual Media Services Directive mandates minimum European works percentages for video-on-demand platforms, guaranteeing baseline commissioning volume for continental studios.
- Cloud Rendering Migration:Elastic compute models through Amazon Web Services and Microsoft Azure are replacing capital-intensive server farms, lowering entry barriers for mid-sized animation houses in Poland and Spain.
- France's CNC Tax Rebate:The Centre national du cinéma et de l'image animée offers production incentives that anchor volume leadership in Paris and Angoulême studio clusters.
Market Restraints
- Skilled Talent Scarcity:Pipeline TDs and senior character riggers concentrate in London and Paris, creating wage inflation pressure for studios outside these metropolitan hubs.
- Rendering Cost Volatility:Spot pricing fluctuations for GPU-intensive cloud compute directly impact per-minute production economics for 3D feature work.
- Platform Consolidation Risk:Subscriber growth plateaus at Netflix and Disney+ are tightening greenlight criteria, reducing speculative development funding for independent European properties.
Strategic Opportunities
- Eastern European Capacity:Underdeveloped animation infrastructure in Romania and Bulgaria offers labor cost arbitrage for roto-scoping and compositing work.
- Virtual Production Convergence:Real-time game engines from Epic Games are merging with traditional animation pipelines, enabling hybrid live-action-animated series production.
- Educational Content Mandates:Public broadcaster obligations under national media laws in Germany and Scandinavia sustain demand for curriculum-aligned animated programming.
Industry Challenges
- Pipeline Integration Complexity:Legacy Maya and Nuke workflows resist seamless incorporation of AI-assisted inbetweening tools, requiring costly pipeline re-engineering.
- Cross-Border Co-Production Coordination:Divergent national subsidy claim requirements between France, the United Kingdom, and Ireland complicate financing structures for multinational projects.
- Intellectual Property Fragmentation:Split rights ownership across co-producing broadcasters limits merchandising and secondary window exploitation for original European properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Animation Market |
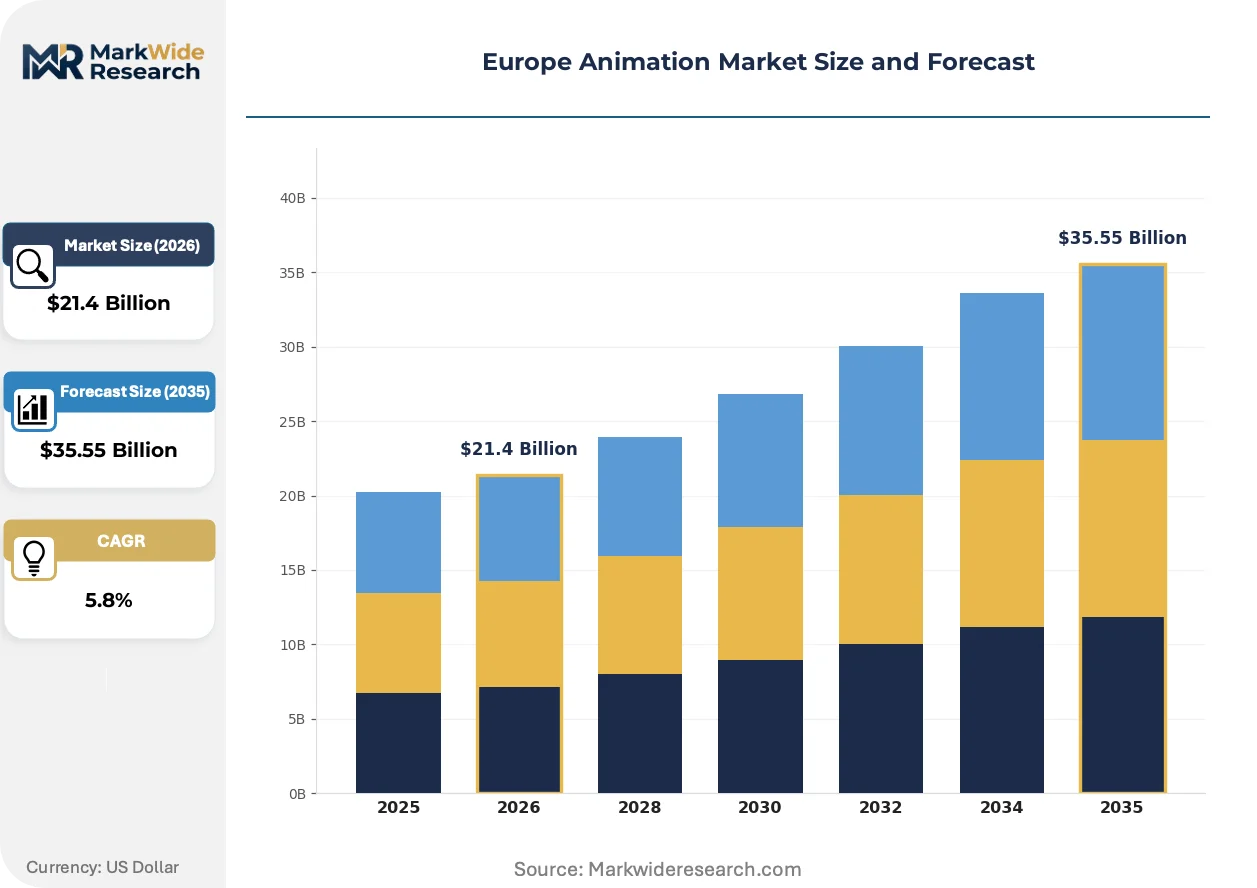
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $35.55 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Feature Films, Short Films, Series, Web Series Animation Technique: 2D Animation, 3D Animation, Stop Motion, Motion Graphics Distribution Channel: Theatrical, Television, Streaming Platforms, DVD/Blu-ray Target Audience: Children, Teens, Adults, Family |
| Companies Covered | Pigeon Studio, Yans Media, Aardman Animations, Panic Studio, Mellow Studio, Blue-Zoo Animation Studio, BluBlu Studios, Drasik Studio, Studio AKA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Animation Market Shifts & Advancements
Generative AI tools are penetrating European animation pipelines at uneven rates, with large studios piloting automated inbetweening while smaller houses grapple with workflow integration costs and talent resistance.
Real-time rendering engines are absorbing pre-visualization and final-output functions previously handled by offline batch systems. Major children's television producers in London are adopting Unreal Engine for episodic series delivery, collapsing traditional layout and lighting departments into unified virtual production environments. This compression is absorbing mid-tier technical artist roles while elevating demand for engine-native generalists.
The EU's AI Act transparency requirements are imposing documentation burdens on studios deploying machine-learning-assisted tools for character animation or background generation. Productions utilizing generative systems must now maintain audit trails for training data provenance and output modification logs. French public broadcasters are responding by restricting AI tool deployment to post-production enhancement rather than primary content creation.
Subscriber-funded platforms are consolidating purchasing power through exclusive output deals with established studio banners, displacing the fragmented commissioning landscape of multiple competing broadcasters. Independent producers in Spain and Italy face narrowing distribution pathways as Netflix, Disney+, and Amazon Prime Video capture exclusive windows. This concentration is most visible in preschool content, where platform-owned IP now dominates catalog depth across German-speaking markets.
Europe Animation Market Segmentation
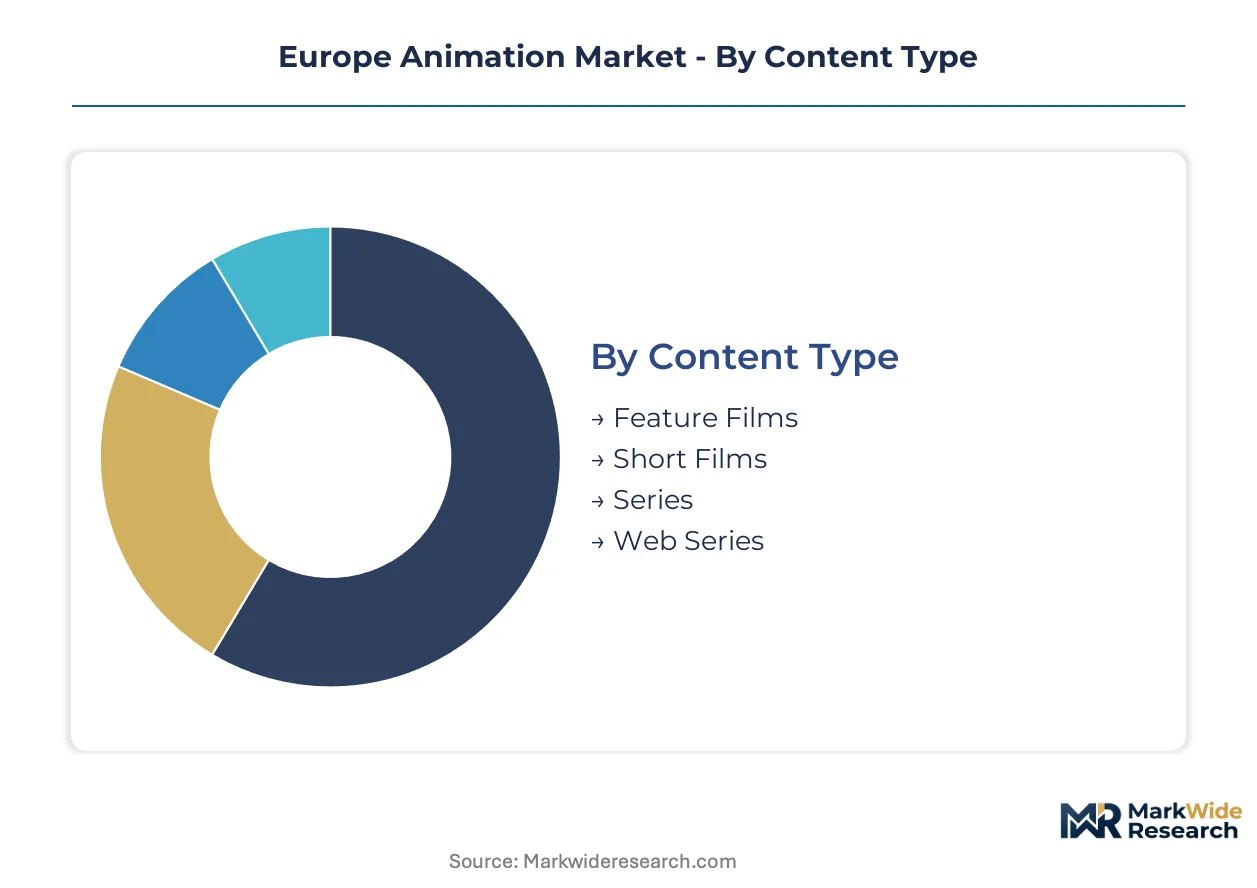
Production economics and distribution economics diverge sharply across animation formats in Europe. Technique selection drives cost-per-minute variation by an order of magnitude, while platform choice determines recoupment windows and IP control terms.
Content Type:
Format length dictates financing structure and risk profile across European production pipelines.
- Feature Films:90-minute theatrical formats command the highest per-minute budgets, typically €800K-€2M for European co-productions. French CNC rebates and UK Film Tax Relief anchor financing for Paris and London-based theatrical slates, though platform consolidation is narrowing independent distribution pathways.
- Series:Episodic formats of 11-22 minutes sustain studio employment continuity through multi-year broadcaster commitments. German public broadcasters ARD and ZDF maintain volume demand for curriculum-aligned children's series under national media law obligations.
- Short Films:Festival-circuit formats serve talent pipeline and prestige functions with limited commercial recoupment.
- Web Series:Platform-native short-form content targets mobile-first consumption patterns with compressed production cycles.
Mature deployment sits with Series. Newer deployment is concentrated in Web Series.
Animation Technique:
Technical sophistication separates premium theatrical work from volume television production.
- 3D Animation:Digital character rigging and GPU-intensive rendering dominate feature film and premium streaming series. Cloud compute migration through AWS and Azure is lowering capital barriers for mid-sized houses in Warsaw and Barcelona, though senior technical director scarcity concentrates wage pressure in London and Paris.
- 2D Animation:Traditional frame-based production retains cost advantages for television volume and stylistic differentiation in adult-oriented series. Eastern European studios in Prague and Budapest exploit labor arbitrage for inbetweening and clean-up work.
- Stop Motion:Physical puppet animation commands premium positioning in theatrical and prestige segments where tactile craft differentiation justifies extended production timelines. Aardman Animations sustains Bristol-based capacity through established IP franchises.
- Motion Graphics:Vector-based commercial animation serves advertising and corporate communication with rapid turnaround requirements. BluBlu Studios anchors Warsaw operations around this segment for pan-European brand clients.
Volume leadership rests with 2D Animation. Value capture is climbing fastest in 3D Animation.
Distribution Channel:
Windowing strategy determines revenue timing and territorial control for European producers.
- Streaming Platforms:Subscriber-funded budgets from Netflix, Disney+, and Amazon Prime Video are displacing traditional broadcaster commissioning. AVMSD content quotas guarantee baseline European works percentages, though exclusive output deals with major studios are narrowing independent pathway access.
- Television:Public broadcaster obligations in Germany and Scandinavia sustain demand for educational programming. Commercial channels face advertising pressure as younger audiences migrate to on-demand consumption.
- Theatrical:Exhibition release commands highest per-ticket revenue but carries print and marketing cost burden. Stop-motion features from established banners retain specialized audience pull.
- DVD/Blu-ray:Physical media persists in collector markets and library sales, though revenue contribution has diminished to marginal status.
Established revenue concentration lies with Television. Steepest expansion trajectory belongs to Streaming Platforms.
Target Audience:
Demographic targeting shapes content regulation exposure and merchandising potential.
- Children:Preschool and early-primary programming faces strictest EMA advertising content guidelines and national media literacy mandates. Platform-owned IP now dominates catalog depth across German-speaking markets.
- Family:Cross-generational theatrical animation commands highest per-capita spend and downstream licensing value.
- Adults:Mature-themed series exploit subscription platform appetite for differentiated content with reduced regulatory constraint.
- Teens:Young adult animation bridges children's heritage properties and mature original IP with compressed episode formats.
Regulatory intensity peaks with Children. Margin expansion is gaining share fastest in Adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and the United Kingdom concentrate commissioning authority for European animation through established tax incentive schemes and streaming platform headquarters. Germany and Poland anchor volume production through public broadcaster obligations and cost-competitive service work. Spain and Italy face narrowing distribution pathways as subscriber-funded platforms consolidate purchasing power.
France
The Centre national du cinéma et de l'image animée (CNC) tax rebate scheme sustains the continent's highest production volume through rebates on eligible expenditure. Studio clusters in Paris and Angoulême anchor theatrical feature and premium series pipelines. Major streaming platforms maintain dedicated French-language commissioning teams in Île-de-France.
United Kingdom
HMRC-administered Film Tax Relief attracts international co-productions for children's television and feature animation. London-based producers leverage established broadcaster relationships with BBC and Channel 4 for multi-year series commitments. Blue-Zoo Animation Studio exemplifies the capital's concentration of children's television specialists.
Germany
Public broadcasters ARD and ZDF sustain demand for curriculum-aligned programming under national media law obligations. The country's federal structure disperses production across Cologne, Munich, and Hamburg rather than concentrating in a single metropolis. German-language preschool content dominates catalog depth in Austria and Switzerland.
Poland
Warsaw-based BluBlu Studios anchors commercial motion graphics capacity for pan-European advertising clients. Lower labor costs relative to Western Europe attract roto-scoping and compositing work from London and Paris-based producers. Cloud rendering migration through AWS and Azure lowers capital barriers for mid-sized houses.
Spain
Barcelona and Madrid studios face intensifying competition for platform commissioning slots as Netflix and Disney+ narrow greenlight criteria. The country's animation infrastructure remains underdeveloped relative to France and the United Kingdom for premium theatrical work. Independent producers encounter widening gaps between development funding and distribution guarantees.
Europe Animation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with IP-owning studios capturing downstream licensing value while service houses compete on per-minute rates. The vendor base organizes into three tiers: established banners with platform output deals, mid-sized houses with broadcaster relationships, and emerging studios competing on cost. Strategic archetypes include heritage stop-motion specialists, cloud-native service providers, and vertically integrated children's IP owners. Competitive moves concentrate on exclusive platform partnerships and pipeline technology licensing rather than capacity expansion.
Within the heritage craft tier, Aardman Animations and Studio AKA occupy positions defined by tactile production methodologies and established IP franchises. BluBlu Studios and Blue-Zoo Animation Studio exemplify contrasting geographic and segment specializations, with the former anchoring Warsaw-based commercial motion graphics and the latter concentrating London-based children's television production. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Pigeon Studio |
| Yans Media |
| Aardman Animations |
| Panic Studio |
| Mellow Studio |
| Blue-Zoo Animation Studio |
| BluBlu Studios |
| Drasik Studio |
| Studio AKA |
| Others |
Supply & Pricing Matrix
Captive cloud rendering infrastructure anchors both supply position and pricing power across European animation houses, with AWS and Azure elastic compute models replacing capital-intensive on-premise server farms and compressing per-minute production economics for mid-tier studios in Warsaw and Barcelona.
Pricing Analysis
Volume-vs-margin split separates commodity service work from premium theatrical output. Project-based pricing dominates episodic series commissioning through Netflix and Disney+, while stop-motion theatrical releases command premium-mid-economy pricing differentiation based on tactile craft heritage and IP franchise value. Cost compression in 3D feature work intensifies because GPU-intensive cloud compute spot pricing volatility directly impacts per-minute budgets. Advertising clients purchasing motion graphics from BluBlu Studios exhibit highest price sensitivity, whereas public broadcasters in Germany and Scandinavia demonstrate lowest sensitivity due to curriculum-mandated programming obligations.
Supply Chain Analysis
Single-source vulnerability sits with senior technical director concentration in London and Paris, where pipeline TDs and character riggers anchor production quality thresholds for premium streaming series. Geographic supply concentration clusters in France, the United Kingdom, and Poland, with Paris and Angoulême studio clusters, London children's television specialists, and Warsaw service houses drawing from distinct talent pools. Raw material dependencies encompass GPU compute cycles from AWS and Azure, proprietary Maya and Nuke licensing, and physical puppet materials for stop-motion theatrical work. Tariff exposure on cloud compute cross-border data flows represents structural supply chain risk. Distribution runs through exclusive output deals with streaming platforms, displacing fragmented broadcaster commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled talent scarcity in pipeline technical roles props pricing for senior capabilities, with wage inflation pressure concentrated in London and Paris creating durable margin pools for studios holding established crew relationships.
For Market Incumbents: Deepen exclusive platform partnerships to lock multi-year commissioning volume before subscriber growth plateaus tighten greenlight criteria further. Secure captive cloud rendering capacity through long-term AWS and Azure reserved instance commitments to stabilize per-minute production economics against spot pricing volatility. Vertical integration into educational content IP ownership captures downstream licensing value as German public broadcaster obligations sustain baseline demand. For New Entrants and Emerging Players: AVMSD content quotas in the European Union open a window for Romanian and Bulgarian studios to capture roto-scoping and compositing overflow from London and Paris producers seeking labor cost arbitrage. Target underdeveloped premium theatrical infrastructure in Spain and Italy where Netflix and Disney+ narrowing greenlight criteria have left independent producers without distribution guarantees. Pursue co-production financing structures leveraging France's CNC tax rebate alongside Eastern European cost advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisition of vertically integrated children's IP owners with established preschool catalog depth across German-speaking markets. Long-term viability favors studios combining cloud-native infrastructure with exclusive broadcaster relationships, as subscriber-funded budgets displace traditional commissioning models. Watch for inflection in AI-assisted tool deployment rates, where French public broadcaster restrictions on primary content creation signal regulatory risk for machine-learning-dependent production pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Migration | AWS and Azure elastic compute lowers capital barriers for mid-sized houses in Warsaw and Barcelona. |
| Exclusive Platform Partnership | Netflix and Disney+ output deals displace fragmented broadcaster commissioning for volume certainty. |
| Tax Incentive Optimization | CNC rebates in France and UK Film Tax Relief anchor cross-border co-production financing structures. |
| Virtual Production Integration | Unreal Engine adoption collapses layout and lighting departments into unified technical environments. |
| Educational Content IP Ownership | German ARD and ZDF curriculum obligations sustain recurring demand for curriculum-aligned programming. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with animation studio executives, streaming platform commissioning editors, public broadcaster programming directors, and cloud infrastructure procurement leads with validation against CNC expenditure reports, HMRC Film Tax Relief submissions, and EU AVMSD implementation documents. Bottom-up project pipeline tracking triangulated with top-down platform content budget disclosures.
Data-stream reconciliation across production volume estimates, commissioning value flows, and platform subscriber-funded budget allocations shaped the analytical framework. Segmentation dimensions modeled encompass content format, animation technique, distribution channel, and target audience demographic across the projection horizon. CAGRs derived from elasticity-adjusted production cost trajectories and platform content budget growth assumptions, incorporating cloud compute pricing volatility and talent wage inflation as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for generative AI tool deployment would alter the outlook if French public broadcaster restrictions expand across the EU. Forecasts reflect assumptions on platform consolidation pace and national subsidy program stability. Deviation in AVMSD quota enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
3D Anaglyph Glasses Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Global Music Video Production Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Video Wall Market
Digital Media
Stock Photography Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Entertainment Market
Digital Media
Mexico Webtoons Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Photography Services Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Global Transport Media Market
Digital Media
Webtoons Market
Digital Media
Digital Rights Management in Media and Entertainment Market