
 Sports Graphics Market | 2026-2036
Sports Graphics Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Graphics Market Analysis
GDPR is broadening the cost-of-entry calculus for sports graphics vendors serving European broadcast clients, as data privacy compliance now extends to biometric tracking in player overlays and fan-facing digital displays. Pixellot leverages its automated camera systems to sustain production efficiency across mid-tier sporting leagues. Supponor anchors the virtual advertising segment with its broadcast-integrated overlay technology. Immersiv.io differentiates through spatial computing platforms that merge real-time graphics with venue architecture.
Sports graphics encompass the design, production, and deployment of visual communication systems used in athletic environments, typically fabricated from vinyl substrates with UV-resistant ink formulations rated for outdoor exposure exceeding five years, and engineered to withstand wind loads and crowd impact in stadium settings. Their primary commercial purpose is to convert spectator attention into measurable brand impressions for sponsors while reinforcing team identity. Digital printing now leads volume output for short-run merchandise and event-specific apparel, while screen printing dominates bulk orders for standardized team kits where color consistency across thousands of units remains critical. Composite materials represent the fastest-growing material category as venues seek lighter, more durable alternatives to traditional aluminum-backed signage for suspended installations.
The Federal Communications Commission shapes broadcast graphics standards in the United States, while the EU Green Deal and REACH framework govern chemical composition and end-of-life treatment for stadium materials across European markets. Compliance with these overlapping regimes determines which vendors qualify for major league contracts and international tournament supply agreements. Stakeholders must monitor how emerging AI-generated content regulations will redefine liability for real-time graphics rendering in live broadcasts.
Market Dynamics
Real-time augmented overlay systems are compressing production timelines for live sports broadcasts while simultaneously elevating technical specifications for graphics vendors. Broadcast networks now demand sub-second latency for virtual insertions, forcing fabricators to integrate broadcast-engineering capabilities alongside traditional print manufacturing.
Growth Catalysts
- EU Green Deal sustainability mandates:Stadium operators across Germany, France, and Italy face binding requirements for recyclable substrates and water-based ink formulations, creating replacement demand for legacy vinyl installations.
- Automated camera-to-graphics pipelines:Mid-tier sporting leagues are deploying AI-driven production systems that require standardized overlay templates, expanding addressable market volume beyond premium broadcast properties.
- Bundesliga infrastructure investment:Host cities preparing for upcoming tournament cycles are awarding multi-year stadium signage contracts that bundle digital display integration with traditional printed graphics.
Market Restraints
- Petrochemical input volatility:PVC resin and solvent-based adhesive prices fluctuate with crude oil indices, compressing margins on long-dated stadium contracts with fixed pricing terms.
- Single-source specialty substrate concentration:European manufacturers rely on a limited German supply base for recyclable fabric meeting REACH compliance, creating vulnerability to capacity constraints.
- Biometric data friction under GDPR:Player-tracking overlays incorporating facial recognition or gait analysis trigger heightened consent requirements and liability exposure for broadcast-integrated graphics vendors.
Strategic Opportunities
- Spatial computing convergence:Venue architecture integration combining real-time graphics with AR-enabled spectator devices opens premium service tiers for technology-forward stadium operators.
- India tournament infrastructure buildout:Cricket stadium modernization programs create first-mover positioning for vendors establishing local production partnerships ahead of international event hosting cycles.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates compel sponsor brands to verify supply-chain carbon footprints, favoring graphics vendors with certified lifecycle documentation.
Industry Challenges
- Broadcast-engineering skill scarcity:Graphics fabricators lack in-house expertise for SDI signal integration and frame-accurate overlay synchronization, requiring costly subcontractor relationships or training programs.
- Multi-jurisdiction certification timelines:Products destined for cross-border tournament use must simultaneously satisfy FCC broadcast standards, REACH chemical compliance, and host-nation fire safety codes, extending pre-production validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Graphics Market |
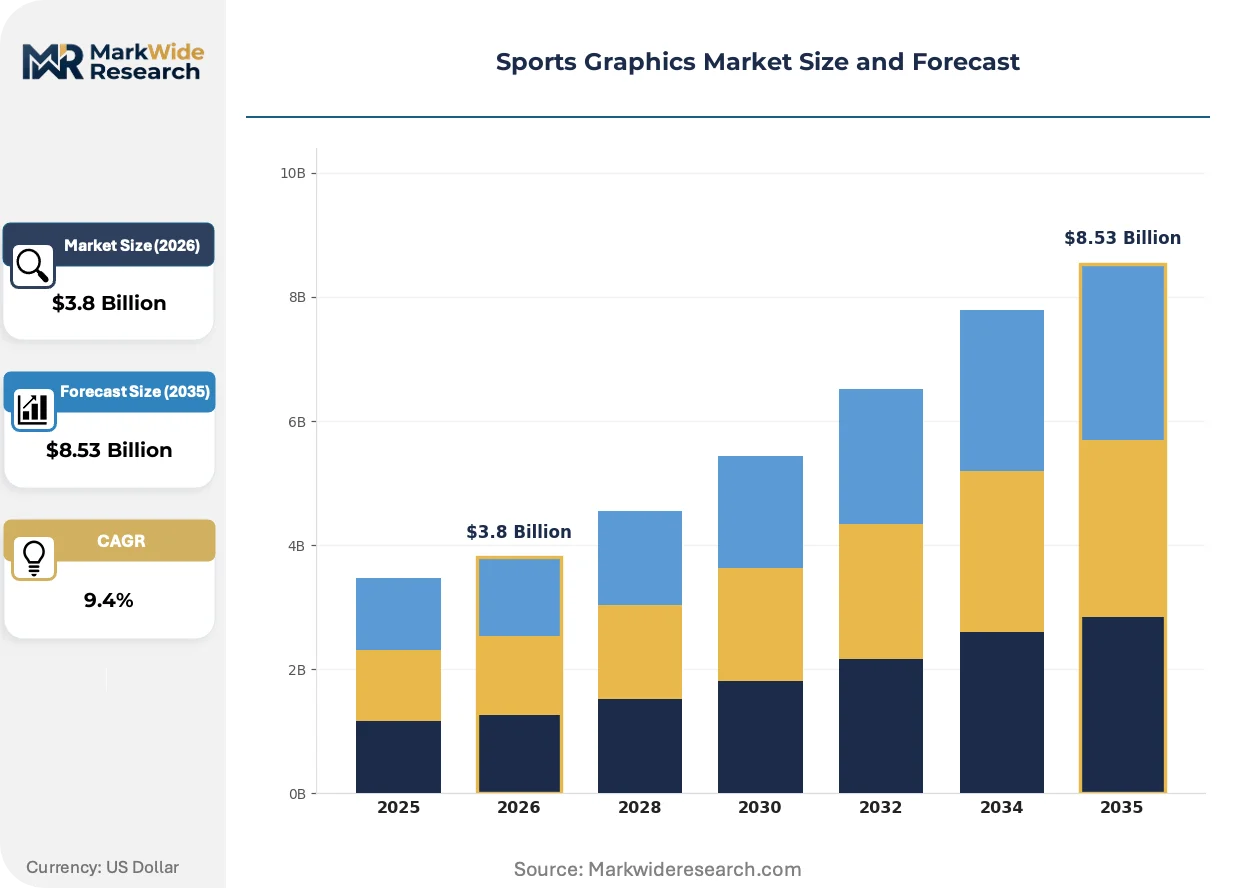
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Stadium Signage, Apparel, Merchandise, Digital Displays Material Type: Vinyl, Fabric, Paper, Composite Technology: Screen Printing, Embroidery, Digital Printing, 3D Modeling Customer Type: Teams, Sponsors, Retailers, Event Organizers |
| Companies Covered | Serotonin, Pixellot, Perfect Form, Misapplied Sciences, The Famous Group, BluBlu Studios, Supponor, Immersiv.io, Watson Creative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Graphics Market Emerging Trajectories
Graphics production is bifurcating between ultra-short-run digital workflows for event-specific applications and highly standardized screen-printed volumes for team kit consistency. This divergence is reshaping equipment investment priorities and vendor specialization patterns across the supply base.
Composite material substrates incorporating fiberglass-reinforced polymers are rewriting weight-bearing specifications for suspended stadium installations. Venue operators in Spain and the United Kingdom are specifying these materials for overhead signage exceeding fifteen-meter spans, eliminating aluminum backing plates while maintaining wind-load ratings. The shift is compressing installation labor costs and enabling more complex three-dimensional forms previously impractical with metal substrates.
REACH framework amendments governing per- and polyfluoroalkyl substances are restricting legacy stain-resistant coatings previously standard on outdoor vinyl graphics. German manufacturers are reformulating ink-receptive top layers to maintain five-year colorfastness warranties without fluorinated chemistry. The regulatory pressure is accelerating water-based UV-curable ink adoption, with Italian and Dutch print houses reporting faster cure times and reduced volatile organic compound emissions.
Sponsor procurement departments are unbundling graphics production from long-term venue service agreements, shifting toward competitive bidding for individual events. This fragmentation is visible most acutely in North American professional leagues, where marketing agencies now specify print vendors separately from installation contractors. The disintermediation is compressing contract values while expanding the vendor pool qualified for single-event work.
Sports Graphics Market Segmentation
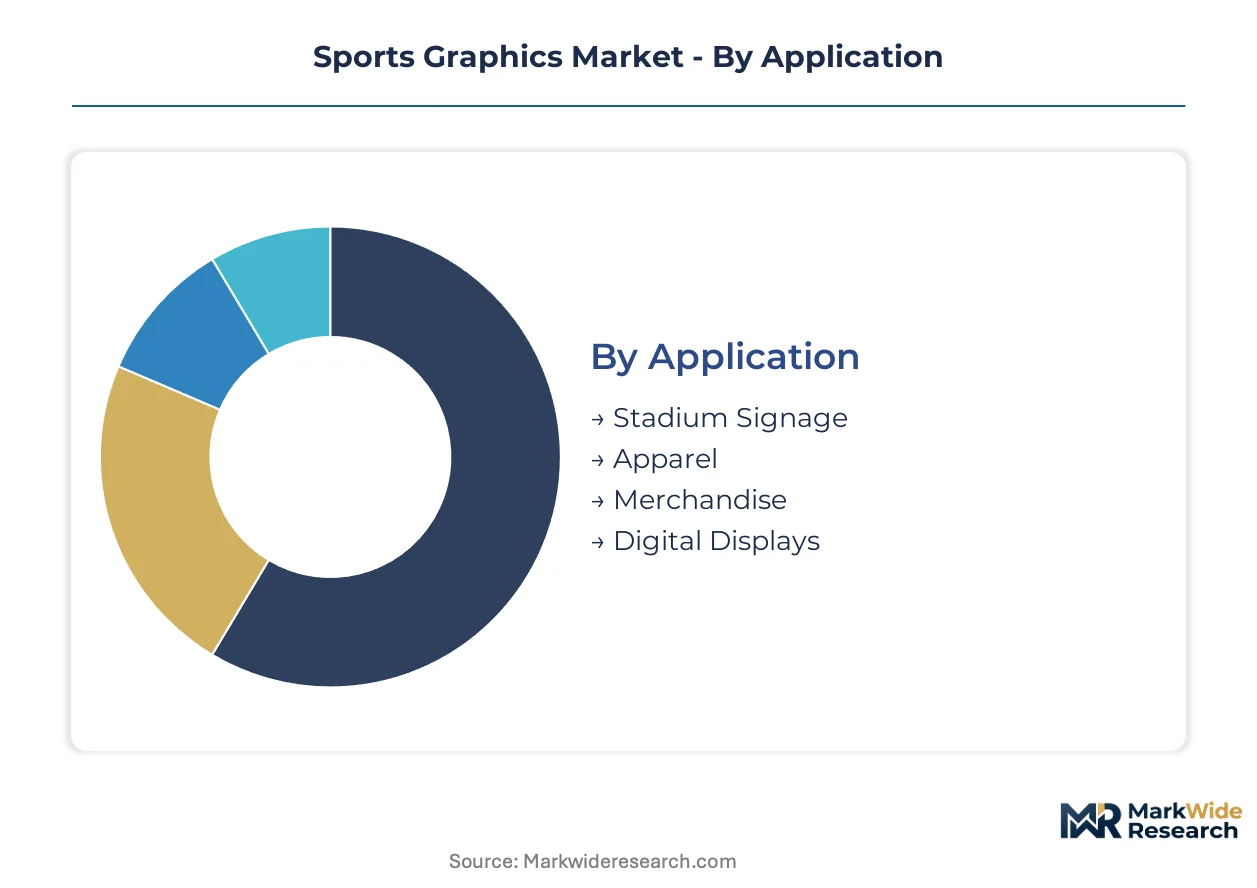
Sports graphics procurement follows distinct technical and commercial logics across application contexts. Understanding how material specifications, production technologies, and buyer categories interact reveals where replacement cycles concentrate and margin structures diverge.
Application:
Upgrade cycles vary dramatically by installation permanence and exposure conditions, with temporary tournament deployments refreshing faster than fixed infrastructure.
- Stadium Signage:Permanent and semi-permanent installations fabricated from UV-resistant substrates rated for multi-year outdoor exposure. Bundesliga clubs and tournament host cities in Germany are driving premium contracts that bundle digital integration with traditional printed systems.
- Apparel:Team kits and fan merchandise requiring color consistency across thousands of units. Screen printing dominates bulk production where standardized palettes matter, while digital workflows handle short-run specialty items.
- Merchandise:Event-specific collectibles and limited-edition products with compressed production timelines. Digital printing enables rapid turnaround for championship celebrations and player transfer announcements.
- Digital Displays:LED-integrated and projection-mapped surfaces requiring broadcast-engineering coordination. Real-time augmented overlay systems are elevating technical specifications for vendors serving streaming platforms.
Stadium Signage sits at the top of the volume ranking, with Digital Displays climbing the fastest.
Material Type:
Cost tier positioning separates commodity substrates from premium alternatives certified under EU sustainability frameworks.
- Vinyl:Legacy PVC-based substrates with solvent-adhesive backing, facing displacement as REACH restrictions on fluorinated coatings tighten. Petrochemical input volatility compresses margins on long-dated contracts with fixed pricing.
- Fabric:Recyclable woven substrates with water-based ink receptivity, now mandatory for EU Green Deal compliance. German manufacturers anchor the supply base for REACH-certified materials, creating concentration risk.
- Paper:Temporary and indoor applications with limited weather resistance. Event programs, tickets, and promotional inserts consume volume in tournament hosting cycles.
- Composite:Fiberglass-reinforced polymers eliminating aluminum backing plates for suspended installations. Spanish and British venue operators specify these for overhead spans exceeding fifteen meters, cutting labor costs while enabling complex three-dimensional forms.
Vinyl retains the largest installed base, though Fabric is expanding most quickly as regulatory deadlines approach.
Technology:
Production method selection hinges on run length consistency requirements versus customization flexibility.
- Screen Printing:Bulk production technology dominating standardized team kits where color matching across thousands of units remains critical. Setup costs amortize efficiently only above threshold volumes.
- Embroidery:Premium decoration for authentic on-field apparel and executive merchandise. Labor-intensive production concentrates in specialized facilities serving luxury positioning strategies.
- Digital Printing:Short-run workflows for event-specific applications and personalized merchandise. Italian and Dutch print houses report faster cure times and reduced volatile organic compound emissions with water-based UV-curable formulations.
- 3D Modeling:Spatial computing platforms merging real-time graphics with venue architecture. AR-enabled spectator devices are opening premium service tiers for technology-forward stadium operators.
Screen Printing commands the highest throughput, while 3D Modeling is gaining share fastest among emerging capabilities.
Customer Type:
Procurement authority fragmentation is reshaping vendor relationships across the value chain.
- Teams:Long-term identity management with standardized kit refresh cycles. Bundesliga clubs bundle multi-year stadium signage contracts with digital display integration.
- Sponsors:Brand impression optimization driving unbundling of graphics production from venue service agreements. North American marketing agencies now specify print vendors separately from installation contractors.
- Retailers:Volume-driven merchandise procurement with margin pressure on unit economics. Inventory risk sits with licensees managing demand volatility across seasonal peaks.
- Event Organizers:Temporary infrastructure with compressed timelines and cross-border certification requirements. Multi-jurisdiction validation cycles extend pre-production for international tournament supply.
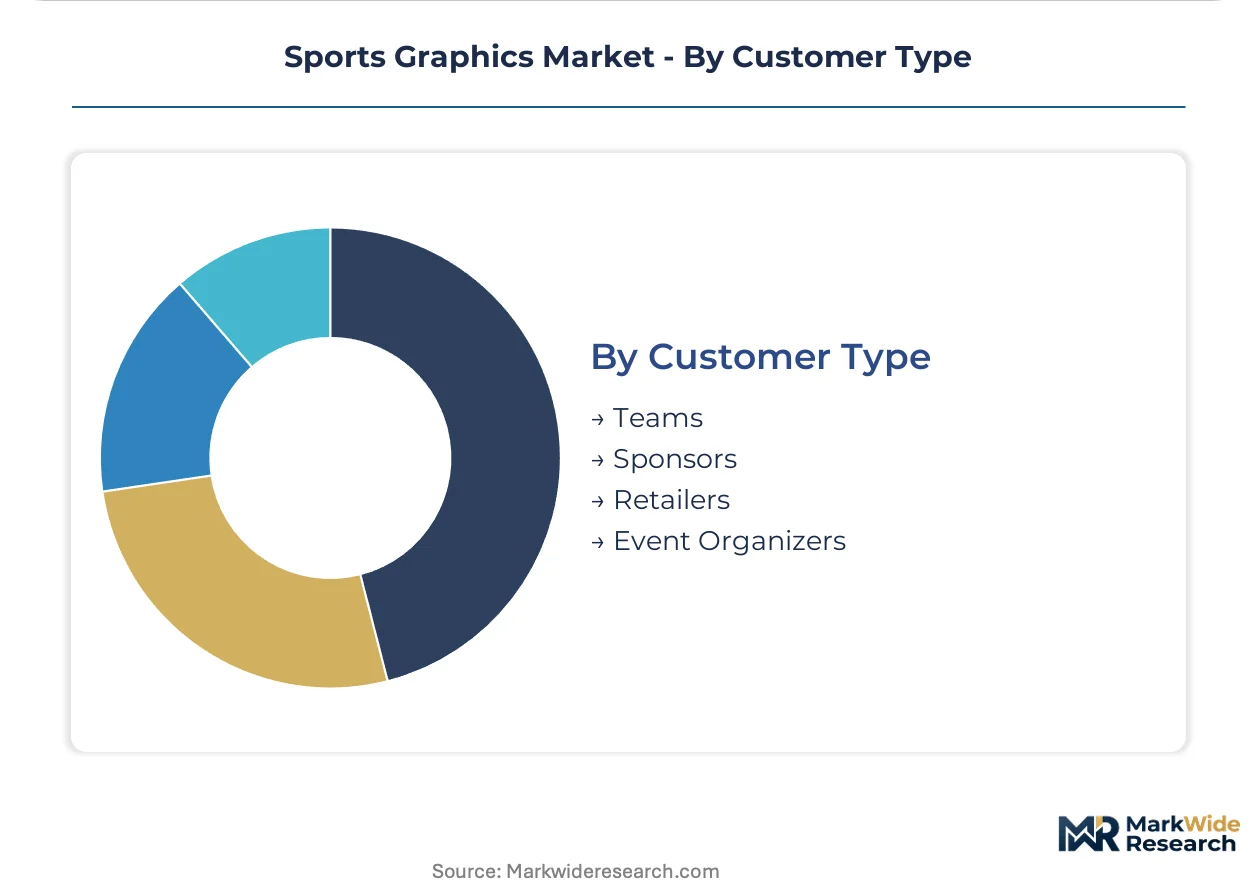
Teams generate the most predictable recurring revenue, with Event Organizers showing the steepest expansion trajectory as tournament hosting cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadcast-engineering talent clusters in Germany, the United Kingdom, and the United States anchor the sports graphics industry's technical development. These concentrations support real-time overlay integration and spatial computing platforms. Regulatory divergence across REACH, FCC, and emerging AI frameworks shapes vendor qualification requirements.
United States
NFL and NBA broadcast networks drive demand for sub-second latency virtual insertions. The FCC governs signal standards and frame-accurate overlay synchronization for live sports transmission. Los Angeles and New York media clusters host production facilities integrating SDI pipelines with traditional print fabrication.
Germany
Bundesliga clubs and tournament host cities award multi-year stadium signage contracts bundling digital displays with printed systems. The EU Green Deal mandates recyclable fabric substrates and water-based inks for all venue installations. Munich and Dortmund industrial zones concentrate REACH-certified substrate manufacturing capacity.
United Kingdom
Premier League broadcasters compress production timelines through automated camera-to-graphics pipelines. GDPR compliance extends to biometric tracking in player overlays, elevating consent management costs. London production houses specialize in spatial computing platforms merging real-time graphics with venue architecture.
Spain
La Liga venues specify fiberglass-reinforced composite materials for overhead signage exceeding fifteen-meter spans. REACH framework amendments restrict fluorinated stain-resistant coatings on outdoor vinyl graphics. Barcelona fabricators reformulate ink-receptive top layers to maintain colorfastness warranties without legacy chemistry.
India
Cricket stadium modernization programs create first-mover positioning for vendors establishing local production partnerships. BIS certification requirements govern imported substrate quality for international tournament hosting. Mumbai and Bangalore emerging as fabrication hubs for event-specific merchandise and temporary tournament infrastructure.
Sports Graphics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the sports graphics value chain. The vendor base separates into three tiers: broadcast-technology integrators, traditional print fabricators, and spatial computing platform developers. Strategic archetypes include automated production system providers, virtual advertising overlay specialists, and venue architecture integration firms. Capacity expansion and technology licensing dominate competitive moves as vendors bridge manufacturing and broadcast-engineering capabilities.
Within the broadcast-technology tier, Pixellot exemplifies automated camera system providers while Supponor occupies a position among virtual advertising overlay specialists. Immersiv.io represents the spatial computing convergence vector merging real-time graphics with AR-enabled spectator platforms. These three companies anchor distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Serotonin |
| Pixellot |
| Perfect Form |
| Misapplied Sciences |
| The Famous Group |
| BluBlu Studios |
| Supponor |
| Immersiv.io |
| Watson Creative |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's sustainability mandates gate qualified supply and premium-tier pricing access for sports graphics vendors, as REACH-certified recyclable fabric substrates and water-based ink formulations command material premiums over legacy PVC alternatives while disqualifying uncertified competitors from Bundesliga and tournament host city contracts.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the sports graphics market. Long-term venue service agreements bundling installation, maintenance, and digital integration command premium-mid-economy pricing differentiation based on contract duration and sustainability certification tier. Cost compression in unbundled single-event procurement is intensifying as North American marketing agencies separately specify print vendors and installation contractors. Sponsors exhibit highest price sensitivity for temporary tournament deployments, while Bundesliga clubs demonstrate lowest sensitivity for multi-year infrastructure bundles.
Supply Chain Analysis
Freight cost escalation from German substrate manufacturers to Spanish and British venue operators is reshaping regional sourcing patterns. Raw material supply concentrates in Germany for REACH-certified recyclable fabrics, China for PVC resin and solvent-based adhesives, and Italy for water-based UV-curable ink formulations. The supply chain rests on petrochemical input volatility for vinyl substrates and single-source concentration for EU-compliant specialty fabrics. Distribution runs through stadium operators, broadcast-technology integrators, and event marketing agencies in tiered fulfillment structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sustainability-certified premium tiers and broadcast-engineering service layers, as EU Green Deal compliance costs filter out commodity competitors and automated camera-to-graphics pipelines elevate technical specifications.
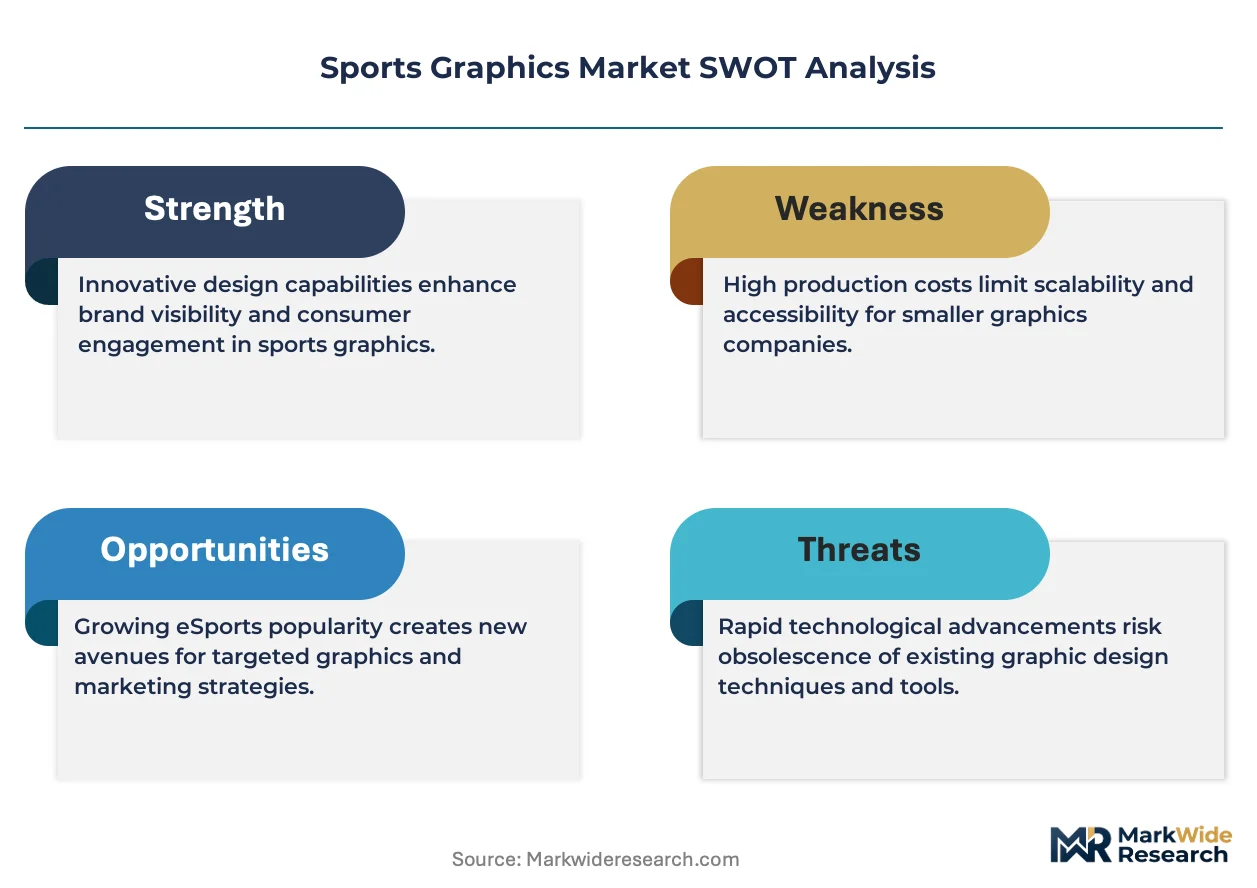
For Market Incumbents: Extend broadcast-engineering capabilities through in-house SDI signal integration training or targeted acquisition of overlay synchronization specialists. Threats from spatial computing platform developers like Immersiv.io demand defensive certification investment in AR-enabled venue architecture integration. Backward integration into REACH-certified substrate manufacturing in Munich and Dortmund industrial zones secures supply continuity. For New Entrants and Emerging Players: Broadcast-technology integrators represent the most penetrable channel partner type for mid-tier sporting league penetration. White-space targets include AI-driven production system standardization for automated camera-to-graphics pipelines and local production partnerships for India's cricket stadium modernization programs. A direct-to-venue sales model targeting tournament host cities with compressed certification timelines accelerates initial traction. For Investors and Strategic Acquirers: Roll-up economics work for broadcast-technology specialists because broadcast-engineering skill scarcity fragments vendor capabilities across automated production, virtual advertising, and spatial computing segments. Long-term viability favors vertically integrated platforms bridging print fabrication with real-time overlay integration. The signal to watch is sponsor procurement department unbundling velocity in North American professional leagues.| Strategic Initiative | Industry Significance |
|---|---|
| Broadcast-Engineering Capability Acquisition | SDI signal integration expertise addresses skill scarcity compressing vendor margins. |
| REACH-Certified Substrate Manufacturing Scale-Up | EU Green Deal deadlines concentrate replacement demand in German industrial zones. |
| Automated Camera-to-Graphics Pipeline Partnership | Pixellot's production systems expand addressable market beyond premium broadcast properties. |
| Spatial Computing Platform Development | AR-enabled spectator devices open premium service tiers for venue architecture integration. |
| India Local Production Partnership | BIS certification requirements favor first-mover fabrication hubs in Mumbai and Bangalore. |
Methodological Framework
Multiple input streams — executive interviews with broadcast-technology integrators and stadium procurement directors, regulatory filing analysis of EU Green Deal implementation timelines, and trade data on substrate imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged broadcast production heads, venue operations managers, print house technical directors, and sponsor marketing procurement leads across Germany, the United Kingdom, the United States, Spain, and India. Secondary validation drew from FCC broadcast standards documentation, ECHA REACH substance restrictions, Bundesliga infrastructure investment disclosures, and BIS certification requirement publications.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include application permanence, material sustainability certification tier, production technology run-length economics, and customer procurement authority structure. CAGRs were derived from installed base replacement cycles, tournament hosting calendar intensity, and regulatory deadline clustering. Industry-specific forecast inputs incorporated automated camera system deployment rates in mid-tier leagues and spatial computing platform adoption curves among technology-forward venue operators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI-generated content liability frameworks, petrochemical price volatility, and single-source substrate supply disruptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and broadcast-network latency specifications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Multichannel Network Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
4K Content Market
Digital Media
Global Animation Market
Digital Media
Stock Photography Market
Digital Media
Digital Content Creator Market
Digital Media
United States Online Gambling Market
Digital Media
US Webtoons Market
Digital Media
Digital Video Content Market
Digital Media
Da Vinci Systems Market
Digital Media
Global Stock Video Market
Digital Media
Global Digital Painting Market
Digital Media
Japan Webtoons Market
Digital Media
Video Content Management Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
North America Online Gambling Market