
 Native Advertising Market | 2026-2036
Native Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Native Advertising Market Intelligence
The rise of performance-focused direct-to-consumer brands is redrawing the competitive landscape, shifting budget away from traditional brand awareness campaigns. This pivot prioritizes measurable outcomes like conversions over simple impressions. Content discovery platforms like Taboola and MGID specialize in serving these performance clients across the open web. Google Ads leverages its vast search network to integrate native formats within its ecosystem, capturing spend from both brand and performance advertisers.
Native advertising refers to paid media designed to blend into the form and function of the platform where it is displayed. These ads often use structured data feeds to dynamically populate components like headlines and images, ensuring a seamless fit with the publisher's content. In-feed ads and recommendation widgets constitute the largest share of formats, integrated directly into content streams. The shift towards programmatic buying models is accelerating, allowing for more efficient, data-driven ad purchasing at scale compared to direct buying.
Regulatory frameworks from bodies like the U.S. Federal Trade Commission (FTC) and Europe's GDPR mandate clear and conspicuous disclosure for native ads. These rules require explicit labeling such as 'Sponsored' or 'Advertisement' to prevent consumer deception and maintain trust in publisher platforms. The deprecation of third-party cookies is a critical technological shift forcing advertisers to develop new strategies for targeting and measurement within native environments.
Market Dynamics
The deprecation of third-party cookies is the central structural force redefining audience targeting and measurement. This technological shift compels advertisers and publishers to adopt new first-party data strategies and privacy-centric advertising models to maintain campaign effectiveness and relevance.
Growth Catalysts
- Programmatic Adoption:The shift to programmatic buying models enables more efficient, data-driven purchasing of native ad inventory at scale, moving spend away from slower, direct-buy negotiations with individual publishers.
- D2C Brand Proliferation:The expansion of performance-focused direct-to-consumer brands, particularly in consumer goods, fuels demand for native formats that deliver measurable conversions and return on ad spend.
- Regulatory Clarity:Stricter advertising disclosure rules, including FTC guidelines in the United States and GDPR in Europe, push advertisers toward clearly labeled native formats to build consumer trust.
Market Restraints
- Ad Blocker Proliferation:The widespread use of ad-blocking software on desktop and mobile browsers prevents native ads served by third-party platforms from reaching their intended audience, reducing effective inventory.
- Data Privacy Restrictions:Evolving data privacy laws like GDPR and the California Consumer Privacy Act (CCPA) limit the data available for targeting, making it harder to deliver personalized native content.
- Walled Garden Competition:Large social media platforms offer highly integrated native advertising solutions within their closed ecosystems, diverting significant budget away from open web publishers and content discovery networks.
Strategic Opportunities
- Connected TV Environments:The expansion of ad-supported streaming services creates opportunities for new native ad formats integrated into content discovery UIs on CTV platforms, reaching audiences in a lean-back viewing mode.
- AI-Driven Creative Optimization:Combining artificial intelligence with dynamic creative optimization allows for the real-time generation of native ad components like headlines and images, improving user engagement.
- Southeast Asian Markets:Rapid digitalization and mobile-first internet consumption in countries like Indonesia and Vietnam present underpenetrated markets for native advertising, especially through mobile-centric content platforms.
Industry Challenges
- Cross-Platform Measurement:Advertisers face difficulty in consistently measuring the performance and attribution of native campaigns that run across multiple publishers, devices, and platforms, hindering budget allocation decisions.
- Creative Strategy Skills:A scarcity of talent skilled in developing compelling native content that aligns with both brand messaging and publisher editorial standards limits the effectiveness of many campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Advertising Market |
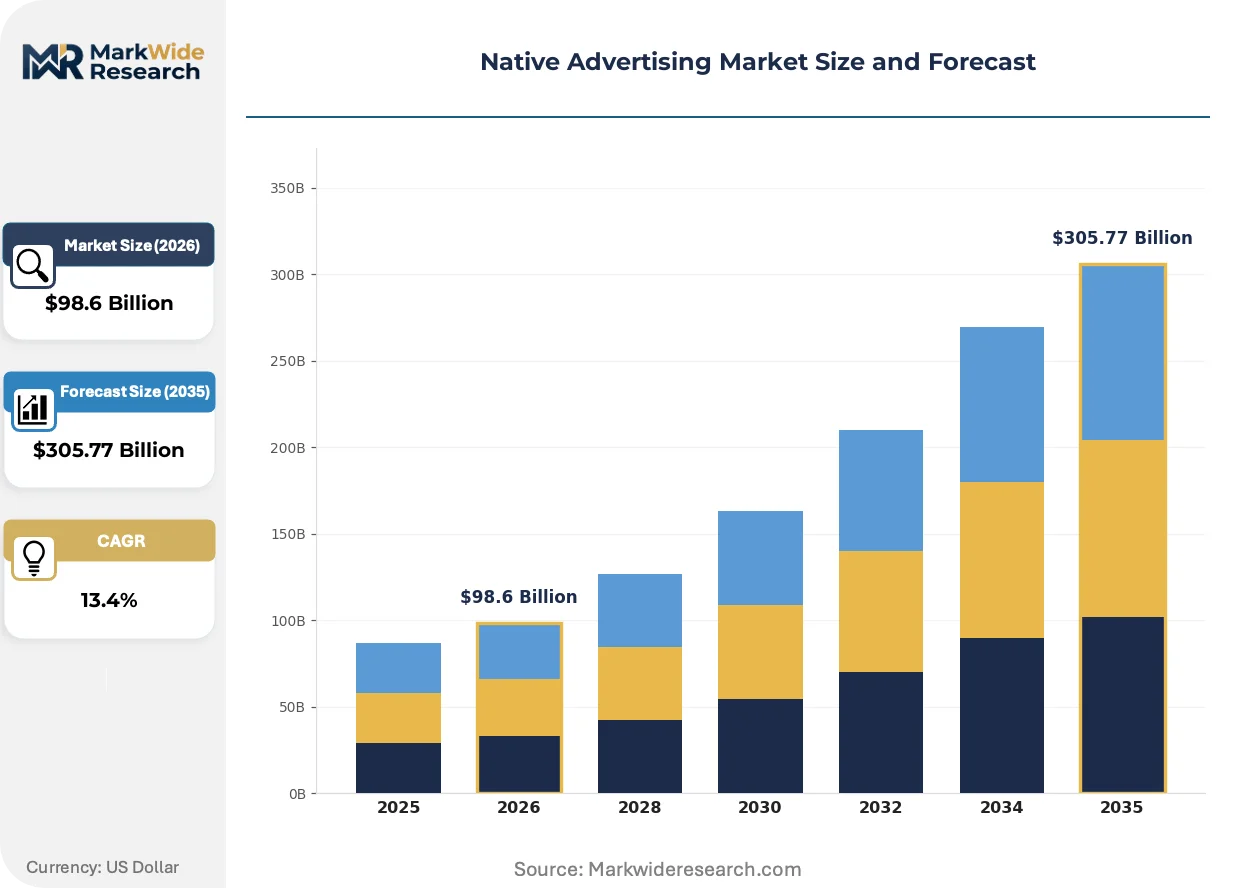
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $305.77 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: In-Feed Ads, Sponsored Content, Recommendation Widgets, Custom Ads, Branded Videos Industry Vertical: Technology, Consumer Electronics, Travel & Hospitality, Telecommunications, Entertainment Device Type: Desktop, Mobile, Tablet, Connected TV, Wearables Buying Model: Programmatic, Direct Buying, Real-Time Bidding, Private Marketplace |
| Companies Covered | MGID, StackAdapt, Google Ads, Sharethrough, Amazon Media Group, Taboola, PropellerAds, EvaDav, Revcontent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Advertising Market Strategic Shifts & Innovations
The native advertising ecosystem is fundamentally re-architecting itself around privacy-first principles and first-party data. This transition away from third-party identifiers is creating new models for audience engagement and campaign measurement across the open web, which is reshaping competitive positioning.
Contextual targeting technology, powered by natural language processing, analyzes page content to serve relevant ads without using personal user data. Publishers and ad tech platforms are rapidly adopting these solutions to prepare for the end of third-party cookies. This technological shift is bifurcating targeting strategies into privacy-safe contextual methods on the open web and first-party data approaches within walled gardens.
Regulations such as Europe's GDPR and upcoming privacy legislation in various U.S. states are mandating greater transparency and user consent for data use. These frameworks place strict controls on data collection and processing for advertising purposes, increasing compliance burdens for all market participants. Content discovery platforms are most affected, as this is forcing them to re-engineer recommendation algorithms to function with less personal data.
A pronounced behavioral shift among direct-to-consumer brands prioritizes performance-based advertising models over traditional brand awareness campaigns. This change de-emphasizes impression-based metrics, favoring models that tie advertising spend directly to measurable outcomes like sales or lead generation. This trend is most visible in the e-commerce and fintech sectors, particularly in mature digital markets like the United States and the United Kingdom.
Native Advertising Market Segmentation
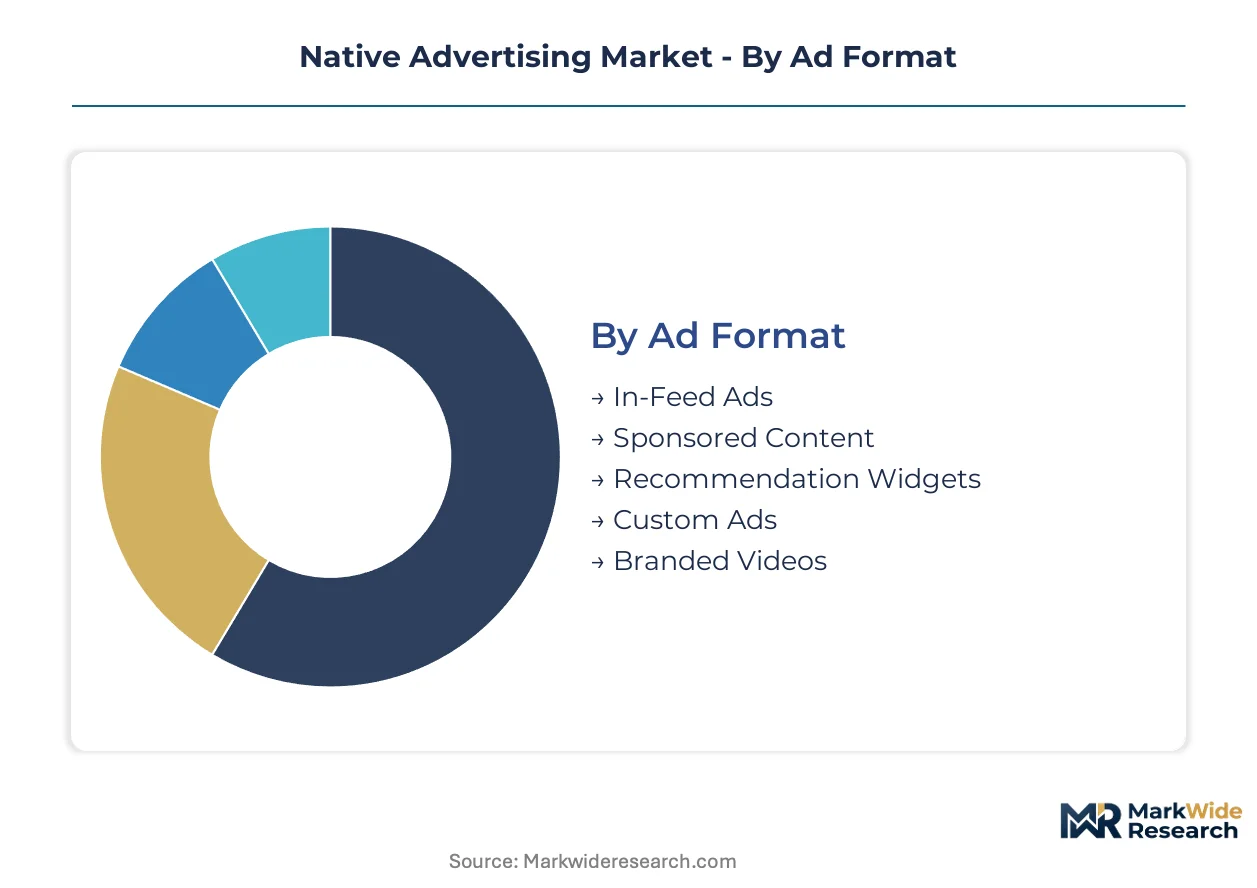
The Native Advertising Market segments across diverse ad formats, industry verticals, device types, and buying models, reflecting the varied strategies advertisers employ to engage audiences. Understanding these distinctions helps stakeholders identify areas of concentrated investment and evolving consumer interaction patterns. Each segment presents unique opportunities for content integration and performance measurement within digital ecosystems.
Ad Format:
Margin pools within native advertising formats often sit with those offering deeper integration and higher creative flexibility.
- In-Feed Ads:These advertisements appear seamlessly within a user's content stream on social media platforms or news sites. Demand concentrates in social media environments, driven by platform algorithms that prioritize user engagement over explicit ad breaks.
- Sponsored Content:Publishers create editorial-style content, such as articles or videos, on behalf of an advertiser, clearly labeled as sponsored. The entertainment industry drives significant demand for this format, seeking authentic audience connection through high-quality storytelling.
- Recommendation Widgets:These units typically appear at the bottom of articles, suggesting additional content, including paid advertisements.
- Custom Ads:Tailored native ad experiences are designed for specific publishers or campaigns, offering unique integration points.
- Branded Videos:Short video advertisements are designed to blend into content feeds, often without explicit calls to action.
In-Feed Ads holds installed capacity. Sponsored Content is rotating up the share rankings.
Industry Vertical:
Application of native advertising varies significantly across different industry sectors, influencing campaign objectives and content strategies.
- Technology:Technology companies leverage native ads for product launches and software downloads, focusing on performance metrics like conversions. The United States market sees high adoption due to a mature digital infrastructure and strong consumer tech spending.
- Consumer Electronics:Brands in consumer electronics utilize native formats to showcase new devices and drive online sales. Europe's privacy-conscious consumers drive demand for transparently labeled content.
- Travel & Hospitality:This sector uses native ads to promote destinations and booking offers, often through visually rich content.
- Telecommunications:Telecom providers employ native advertising for new service promotions and customer acquisition.
- Entertainment:Entertainment companies use native ads to promote new releases and engage fan bases.
The Technology segment shows strong market penetration, while Entertainment is expanding most quickly.
Device Type:
The volume of native ad impressions is heavily influenced by the primary device consumers use for content consumption.
- Mobile:Native ads optimized for smartphones and tablets are integrated into mobile apps and web browsers. Demand concentrates on mobile devices, driven by pervasive smartphone ownership across Southeast Asian markets.
- Desktop:These ads appear on traditional desktop and laptop computer screens, often within news portals and content sites. The United States maintains strong desktop usage for professional and longer-form content consumption.
- Tablet:Native advertising content is adapted for the larger screen size of tablet devices.
- Connected TV:Native formats are emerging within streaming service interfaces and smart TV content hubs.
- Wearables:Limited native ad integration exists on smartwatches and other wearable technology.
Mobile devices capture the largest user base, with Connected TV gaining significant traction.
Buying Model:
Supply concentration in buying models reflects the efficiency and scalability offered by automated systems.
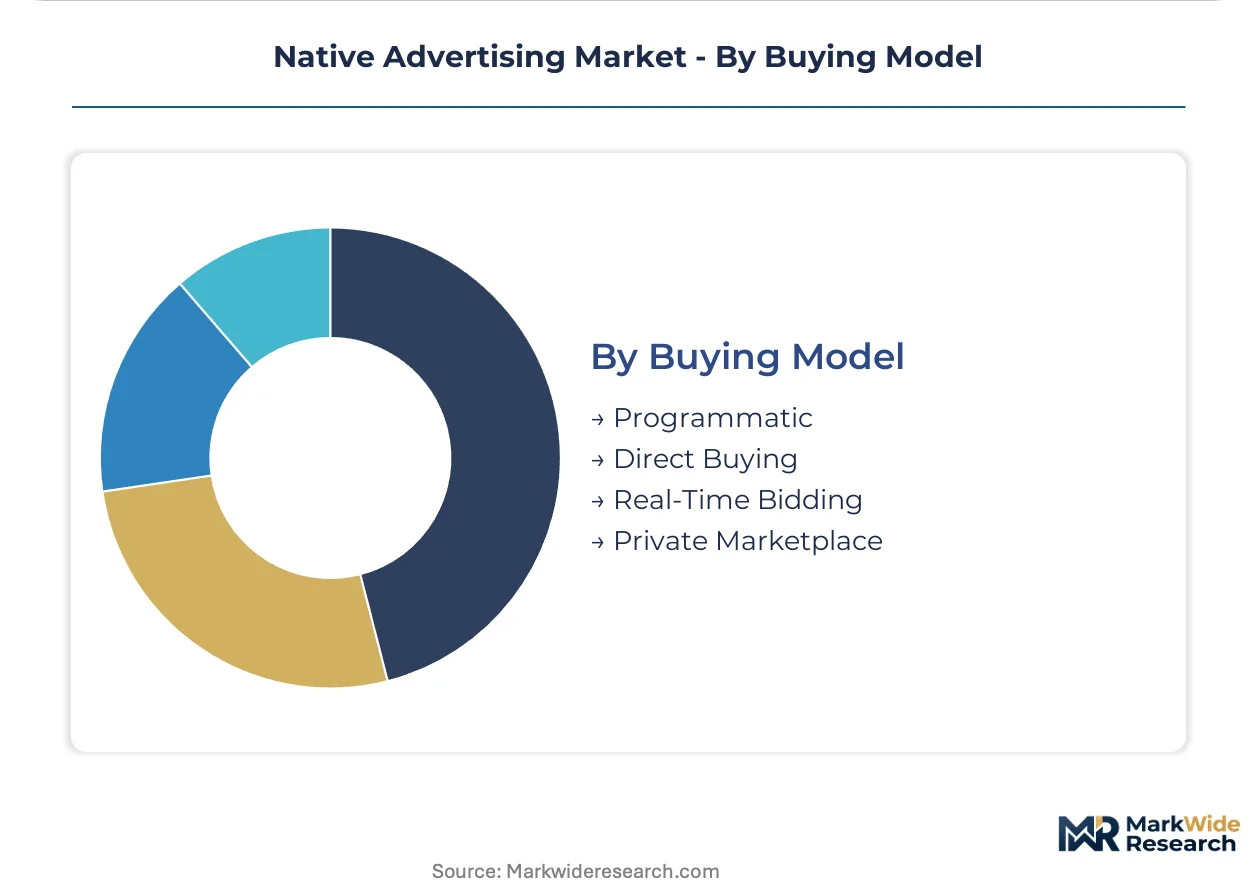
- Programmatic:Automated buying and selling of native ad inventory through real-time bidding platforms. Demand concentrates in programmatic channels, driven by advertiser needs for granular targeting and campaign optimization.
- Direct Buying:Advertisers negotiate directly with publishers for native ad placements. This model persists for premium placements and custom content collaborations with specific publishers.
- Real-Time Bidding:An auction-based system where ad impressions are bought and sold in milliseconds.
- Private Marketplace:Programmatic deals are executed within an invitation-only environment involving select publishers and advertisers.
Programmatic buying dominates transaction volumes, as Real-Time Bidding platforms refine their offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration for native advertising solutions increasingly sits with technologically advanced digital markets that possess mature digital media ecosystems. These regions exhibit high consumer internet penetration and a robust landscape of direct-to-consumer brands. Regulatory frameworks also influence market development, pushing for greater transparency in ad formats.
United States
Demand for native advertising in the United States is driven by a large base of performance-focused direct-to-consumer brands seeking measurable outcomes. The FTC mandates clear disclosure for native ads, ensuring consumer trust and transparent practices. Major ad tech hubs in Silicon Valley and New York City continue to innovate in programmatic native solutions.
United Kingdom
The United Kingdom market prioritizes performance-based native advertising, particularly within the e-commerce sector, to drive conversions. GDPR regulations significantly influence data privacy practices, pushing advertisers towards first-party data strategies. London's vibrant ad tech ecosystem fosters innovation in contextual targeting and dynamic creative optimization.
Germany
Germany exhibits strong demand for native advertising, particularly among brands focused on building authentic connections with privacy-conscious consumers. GDPR compliance is a central concern, guiding the development of privacy-centric ad solutions. Berlin's growing startup scene contributes to new native ad formats and measurement technologies.
China
China's native advertising market expands rapidly, fueled by a mobile-first internet consumption culture and a massive user base. Strict internet regulations and content censorship policies shape the types of native content permissible. Digital marketing firms in Shanghai and Beijing are at the forefront of integrating native ads within super-apps and social commerce platforms.
India
India's market for native advertising is propelled by rapid digitalization and increasing smartphone penetration, especially for mobile-centric content platforms. Upcoming data protection laws will influence targeting and measurement strategies, emphasizing privacy. Bangalore's tech hubs are developing localized native ad solutions to cater to diverse linguistic and cultural audiences.
Native Advertising Market Key Industry Players
Concentration sits with large ad tech platforms and content discovery networks that offer scalable programmatic solutions across the open web. The market structure includes specialized content discovery platforms, search engine giants, and emerging in-app native ad providers. Dominant competitive moves include strategic mergers and acquisitions to expand inventory and technology licensing to integrate new privacy-centric targeting capabilities.
Content discovery platforms like Taboola and MGID exemplify the specialized service providers focused on performance clients across various publishers. Google Ads, a search engine giant, leverages its vast ecosystem to integrate native formats for both brand and performance advertisers. These firms occupy a position at the forefront of developing privacy-compliant targeting and measurement solutions for the evolving digital advertising landscape.
| Leading Market Players |
|---|
| MGID |
| StackAdapt |
| Google Ads |
| Sharethrough |
| Amazon Media Group |
| Taboola |
| PropellerAds |
| EvaDav |
| Revcontent |
| Others |
Cost & Logistics Intelligence
Large-scale programmatic platforms create significant scale economies, driving supply concentration among major ad tech providers. This efficiency dictates price floors for native ad inventory across diverse digital ecosystems.
Pricing Analysis
Volume-based discount structures characterize native advertising pricing, particularly within programmatic channels. Price differentiation stems from publisher audience quality and ad placement visibility within content feeds. Pricing pressure emerges from performance-focused direct-to-consumer brands demanding measurable return on ad spend. These D2C brands exhibit high price sensitivity, while large brand advertisers prioritize premium placements and brand safety.
Supply Chain Analysis
Just-in-time inventory management defines the native advertising supply chain, with ad impressions served dynamically based on real-time demand. Supply concentration for ad inventory and tech platforms centers in the United States, alongside significant development in the United Kingdom and Germany. Raw material dependencies include publisher ad space and first-party audience data. Data privacy restrictions present a structural risk, limiting available targeting data. Distribution runs primarily through programmatic ad exchanges and content discovery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The native advertising market exhibits a strong defensive moat, primarily driven by the network effect of established content discovery platforms. This ecosystem creates significant switching costs for advertisers and publishers alike, reinforcing market leadership.
For Market Incumbents: Compound investments in first-party data solutions to mitigate the deprecation of third-party cookies. Acquire specialized AI creative optimization firms to maintain engagement amidst evolving consumer preferences. Vertical integration into publisher ad tech platforms strengthens control over premium inventory. This strategy counters the threat posed by large walled garden ecosystems.
For New Entrants and Emerging Players: Lead with innovative native ad formats tailored for Connected TV environments, leveraging content discovery UIs. Target underpenetrated mobile-first markets in Southeast Asia, particularly Indonesia and Vietnam, focusing on local language content. A privacy-centric contextual targeting approach offers a compelling go-to-market angle for open web publishers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ad tech firms with robust first-party data and contextual AI capabilities. The long-term viability of native advertising remains strong, driven by the shift towards privacy-first principles. Target acquisition archetypes include specialists in CTV ad integration and advanced audience measurement solutions. Widespread adoption of privacy-enhancing technologies by major web browsers signals a critical inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop First-Party Data Solutions | Enables privacy-compliant targeting and measurement in a cookie-less future. |
| Invest in AI Creative Optimization | Enhances ad relevance and user engagement through dynamic content generation. |
| Expand into Connected TV (CTV) Ad Formats | Captures growing audiences on streaming platforms with integrated native experiences. |
| Acquire Contextual Targeting Technology | Provides privacy-safe audience reach by analyzing page content without personal data. |
| Enter Southeast Asian Mobile Markets | Accesses rapidly digitalizing regions with high mobile-first internet consumption. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, ad platform disclosures, and regulatory guidelines. Primary interviews engaged ad tech executives, publisher ad operations managers, and performance marketing directors. This approach synthesized insights from both demand and supply sides of the market. Bottom-up and top-down triangulation validated market sizing and growth projections.
Segmentation dimensions modeled include ad formats, industry verticals, device types, buying models, and regional adoption patterns. The analytical framework projects market evolution across the analysis window, integrating historical data and expert consensus. Compound Annual Growth Rates were derived through regression analysis. Publisher inventory growth and programmatic spend penetration served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant shifts in privacy regulations or digital platform policies would require recalibration. Forecasts reflect assumptions regarding technological adoption and advertiser behavior. Revision becomes warranted when ad tech ecosystem structural changes cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Middle East and North Africa Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Global Print Advertising Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market