
 Stanozolol Market | 2026-2036
Stanozolol Market Size, Share, and Industry Trends Forecast 2026-2036
Stanozolol Market Insights
A capital-intensity divergence between large-scale API manufacturers and regional formulators is unwinding competitive stability in the Stanozolol landscape. Hikma Pharmaceuticals PLC leverages vertically integrated fermentation capacity to sustain cost advantages across regulated European markets. Sun Pharmaceutical Industries Ltd. anchors its position through dedicated steroid synthesis infrastructure in India. Zhejiang Xianju Pharmaceutical competes aggressively on raw material sourcing, controlling critical precursor supply chains.
Stanozolol is a synthetic anabolic steroid derived from dihydrotestosterone, characterized by a pyrazole ring fusion at the A-ring that enhances its anabolic-to-androgenic ratio and oral bioavailability; manufacturers produce it through multi-step organic synthesis involving palladium-catalyzed coupling reactions followed by crystallization to achieve pharmaceutical-grade purity. Injectable solutions command premium positioning due to superior bioavailability and extended half-life compared to oral tablets, while powders dominate bulk procurement by underground laboratories. Medical treatment applications remain structurally constrained by scheduling restrictions, whereas bodybuilding channels absorb the majority of volume despite regulatory prohibition.
FDA scheduling under the Anabolic Steroid Control Act, DEA enforcement against illicit distribution, and WADA's prohibited substance list collectively shape legitimate market access while diverting demand toward unregulated channels. The EU's EMA framework and national health regulators in Germany and France impose additional barriers to prescription authorization. Stakeholders must monitor evolving enforcement patterns and precursor chemical controls to anticipate supply disruptions and channel migration.
Market Dynamics
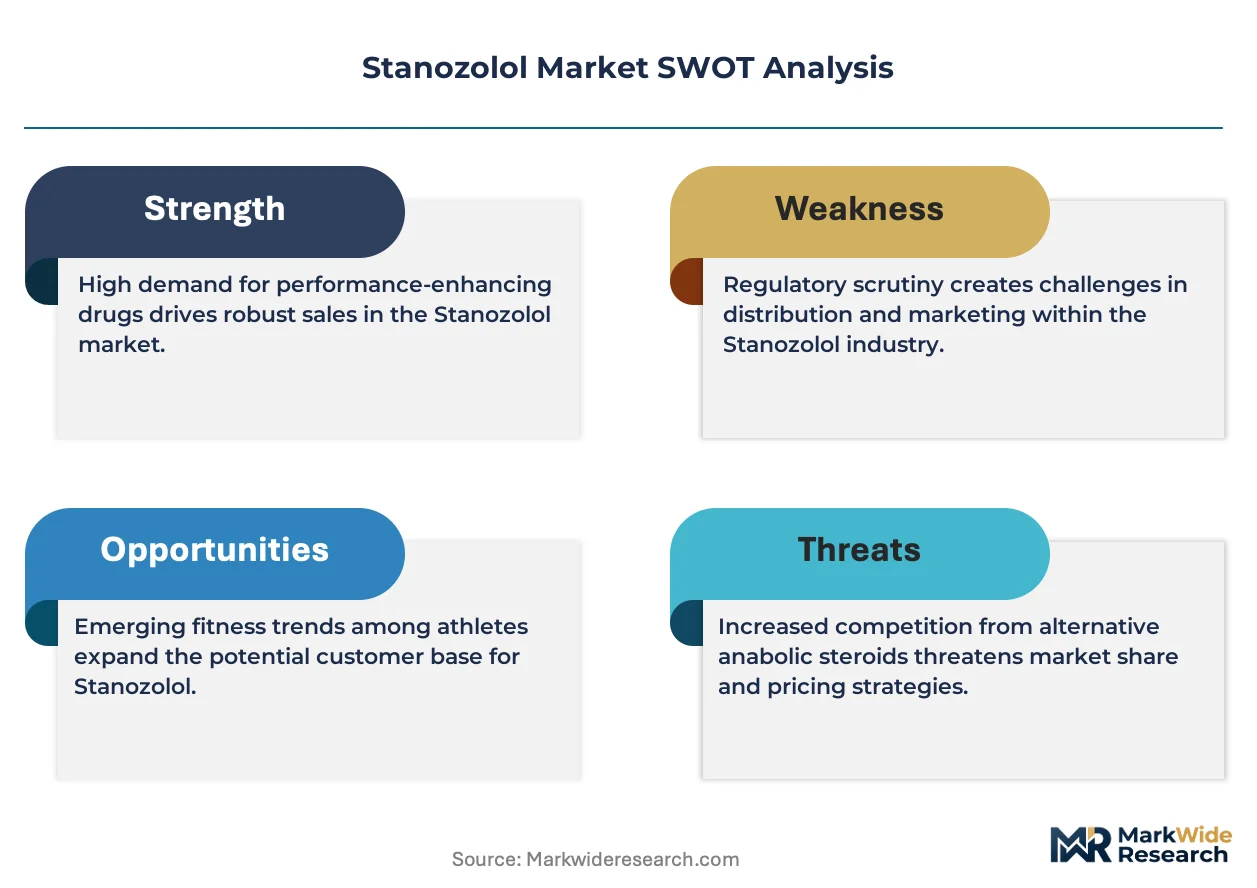
The Stanozolol market operates under persistent regulatory compression that diverts legitimate pharmaceutical production toward uncontrolled distribution channels. WADA's prohibited substance protocols and national scheduling regimes have eliminated conventional commercial pathways, forcing supply chain reconfiguration around precursor control evasion and subterranean laboratory networks.
Growth Catalysts
- Veterinary therapeutic protocols:Licensed applications in animal husbandry across Brazil and Argentina sustain residual manufacturing capacity. Off-label diversion from these channels feeds emerging market demand.
- Underground laboratory proliferation:Southeast Asian chemical clusters in Thailand and Vietnam have developed sophisticated steroid synthesis capabilities. Regional precursor availability lowers entry barriers for illicit producers.
- EMA regulatory harmonization gaps:Inconsistent enforcement across EU member states creates arbitrage opportunities. Divergent national prescription frameworks enable cross-border channel exploitation.
Market Restraints
- Palladium catalyst cost volatility:The metal's price swings directly compress margins for API manufacturers. Synthetic route economics become unpredictable at laboratory scale.
- Precursor chemical concentration:China dominates pyrazole ring intermediates and specialized reagent supply. Geopolitical friction threatens raw material continuity.
- DEA Schedule III classification:The Anabolic Steroid Control Act imposes severe penalties on distribution. Legitimate pharmaceutical development becomes commercially unviable.
Strategic Opportunities
- Indian CDSCO registration pathways:Domestic regulatory frameworks for veterinary steroids remain less restrictive than Western equivalents. Local manufacturing permits export-oriented positioning.
- Bioidentical hormone convergence:Compounding pharmacy regulations in select US states create adjacent positioning opportunities. Stanozolol derivatives may qualify for customized therapeutic exemptions.
- Blockchain-secured provenance systems:Emerging authentication technologies could enable grey-market quality differentiation. Premium pricing attaches to verified synthesis documentation.
Industry Challenges
- Steroid synthesis expertise attrition:Pharmaceutical chemists with dihydrotestosterone derivative experience are aging out of the workforce. Academic programs have abandoned anabolic steroid research.
- Multi-jurisdiction compliance complexity:Simultaneous adherence to FDA, EMA, and national anti-doping frameworks demands specialized regulatory personnel. Talent acquisition costs escalate.
- Crystallization protocol standardization delays:No universal pharmaceutical-grade purity benchmarks exist for underground production. Quality inconsistency undermines channel credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stanozolol Market |
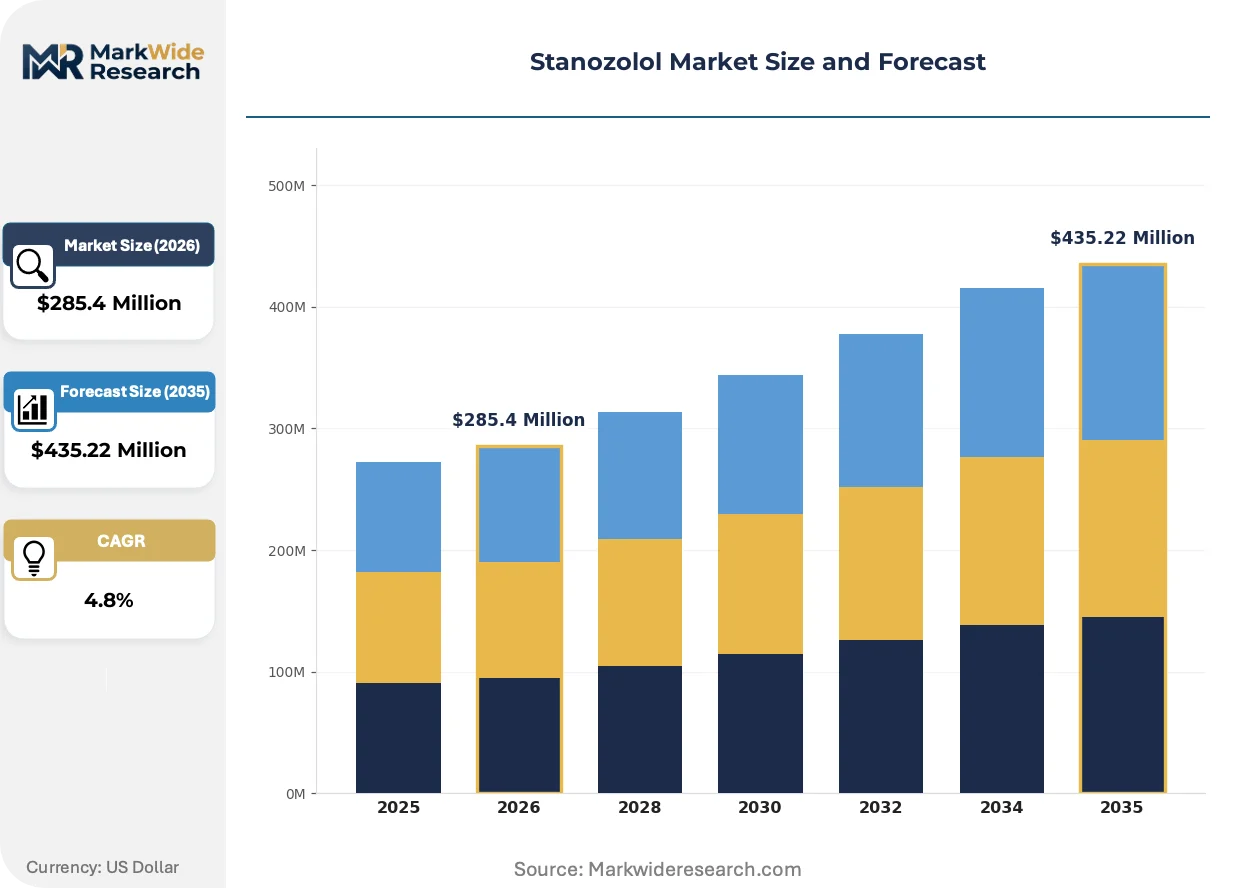
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Injectable Solutions, Powders, Capsules Application: Athletic Performance, Bodybuilding, Medical Treatment, Weight Gain End User: Sports Professionals, Bodybuilders, Clinics, Fitness Enthusiasts Distribution Channel: Online Retail, Pharmacies, Wholesale Distributors, Specialty Stores |
| Companies Covered | Hikma Pharmaceuticals PLC, Sun Pharmaceutical Industries Ltd., Mylan N.V., Organon, Zhejiang Xianju Pharmaceutical, Guangxi Nanning Baihui Pharmaceutical Group, Chifeng Mengxin Pharmaceutical, Guangzhou Baiyunshan Pharmaceutical, Actavis Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stanozolol Market Trends and Innovations
Active pharmaceutical ingredient manufacturing is fragmenting between regulated pharmaceutical infrastructure and adaptive chemical synthesis operations. This divergence is reshaping competitive capabilities and market access patterns across all geographic zones.
Microfluidic continuous-flow synthesis is bifurcating batch production economics in underground laboratory operations. Southeast Asian operators are adopting these systems to reduce solvent volumes and detection footprints. The technology is compressing traditional multi-step organic synthesis timelines from weeks to days, enabling rapid response to precursor availability disruptions.
REACH precursor registration requirements are tightening control over pyrazole derivative commerce across EU member states. ECHA's updated substance evaluation protocols are extending documentation burdens to intermediate chemical traders. Underground distributors in Eastern Europe are responding by relocating procurement toward non-EU Balkan supply corridors.
Direct-to-consumer encrypted platform distribution is displacing traditional gym-based broker networks in North American demand channels. Bodybuilding communities are migrating toward cryptocurrency-settled transactions with verified laboratory documentation. This behavioral shift is most visible in Texas and Florida metropolitan clusters where fitness culture density supports decentralized procurement models.
Stanozolol Market Segmentation
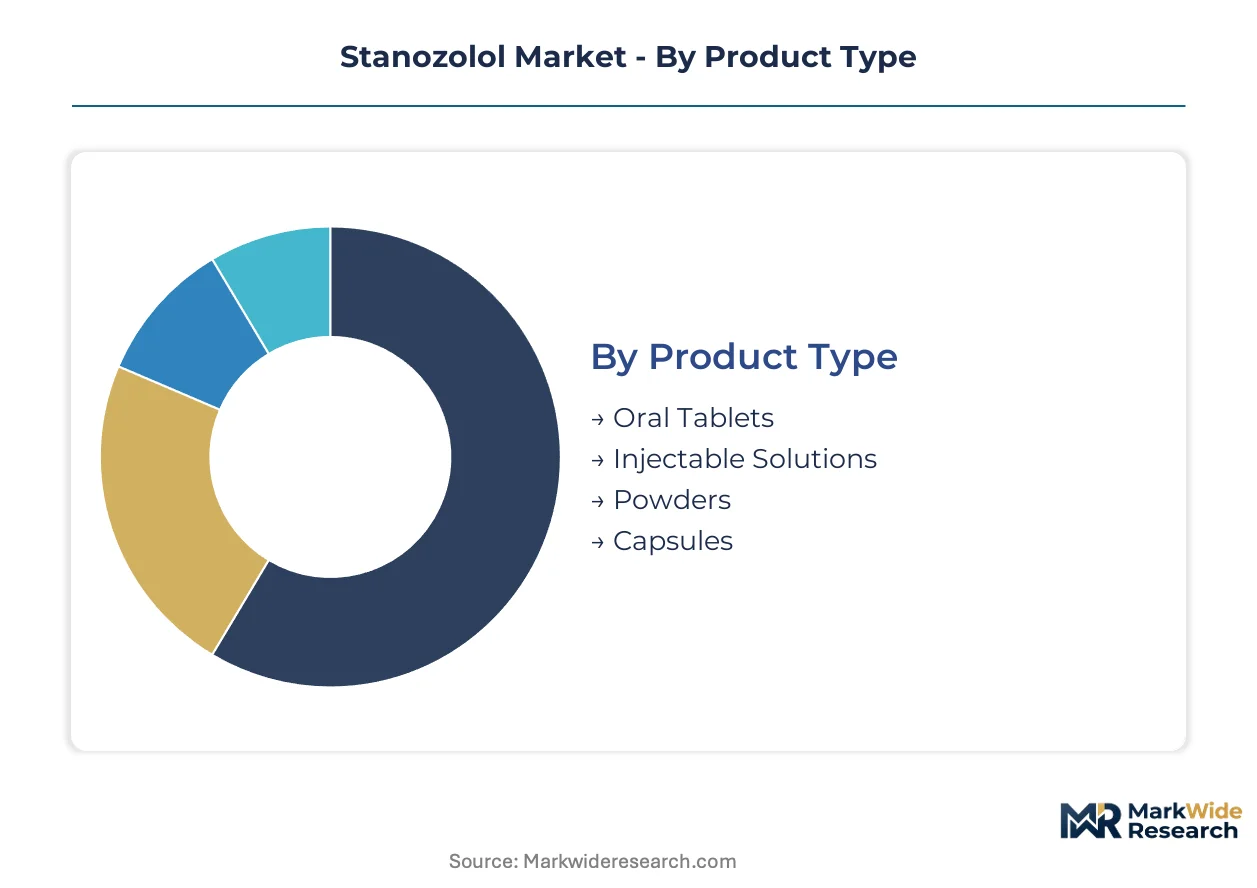
Segmentation in the Stanozolol market reveals how regulatory compression has fragmented value capture across product forms and channel structures. Each dimension exposes distinct margin vulnerabilities and enforcement exposure profiles that shape competitive positioning.
Product Type:
Margin pools concentrate in injectable formats where bioavailability premiums offset synthesis complexity, while powder segments compete on volume throughput to underground laboratories.
- Oral Tablets:Compressed formulations with pyrazole-ring-modified dihydrotestosterone cores enable discrete consumption. Demand clusters in North American fitness communities where portability outweighs hepatotoxicity concerns; DEA scheduling intensifies procurement friction.
- Injectable Solutions:Aqueous or oil-based suspensions deliver extended half-life through intramuscular depot formation. European bodybuilding channels absorb majority volume despite EMA restrictions; WADA detection windows drive cycling protocols that sustain repeat purchase frequency.
- Powders:Bulk API for compounding operations and underground laboratory formulation. Southeast Asian chemical clusters in Thailand supply regional conversion facilities.
- Capsules:Gelatin-encapsulated variants targeting consumers averse to tablet compression aesthetics. Limited differentiation from standard oral formats constrains premium positioning.
Injectable Solutions holds installed capacity. Oral Tablets is rotating up the share rankings.
Application:
Application-based segmentation tracks how end-use intent determines channel access and regulatory risk allocation across consumer populations.
- Athletic Performance:Dosing protocols designed for strength-to-weight optimization in tested competition environments. National anti-doping agency enforcement in Germany and Australia compresses legitimate sourcing windows; cryptocurrency-settled procurement is displacing traditional broker networks.
- Bodybuilding:Aesthetic muscle hypertrophy and definition-focused consumption dominates absolute volume. Underground laboratory networks across Eastern Europe feed demand through gym-based distribution clusters in Poland and Romania.
- Medical Treatment:Licensed indications for hereditary angioedema and anemia sustain residual prescription channels. FDA Schedule III classification eliminates commercial viability for new therapeutic development.
- Weight Gain:Appetite stimulation and lean mass accretion for cachectic patients or hardgainer phenotypes. Veterinary diversion from Brazilian animal husbandry operations supplies emerging market demand.
Bodybuilding commands current volume leadership. Athletic Performance is gaining share fastest as encrypted platform distribution matures.
End User:
End user segmentation exposes how professionalization level correlates with procurement sophistication and quality verification demands.
- Sports Professionals:Tested athletes in Olympic and professional league structures with structured anti-doping obligations. WADA whereabouts requirements and biological passport programs enforce consumption discipline; demand concentrates in pre-competition windows.
- Bodybuilders:Competitive and recreational physique athletes pursuing judged or personal aesthetic outcomes. Texas and Florida metropolitan clusters support decentralized procurement through direct-to-consumer platform migration.
- Clinics:Licensed medical facilities with controlled substance prescribing authority. DEA registration requirements and state-level prescription monitoring programs constrain dispensing volume.
- Fitness Enthusiasts:Recreational gym attendees without competitive aspirations seeking performance or cosmetic enhancement. Price sensitivity and quality uncertainty dominate purchase criteria.
Bodybuilders hold installed capacity. Sports Professionals is rotating up the share rankings.
Distribution Channel:
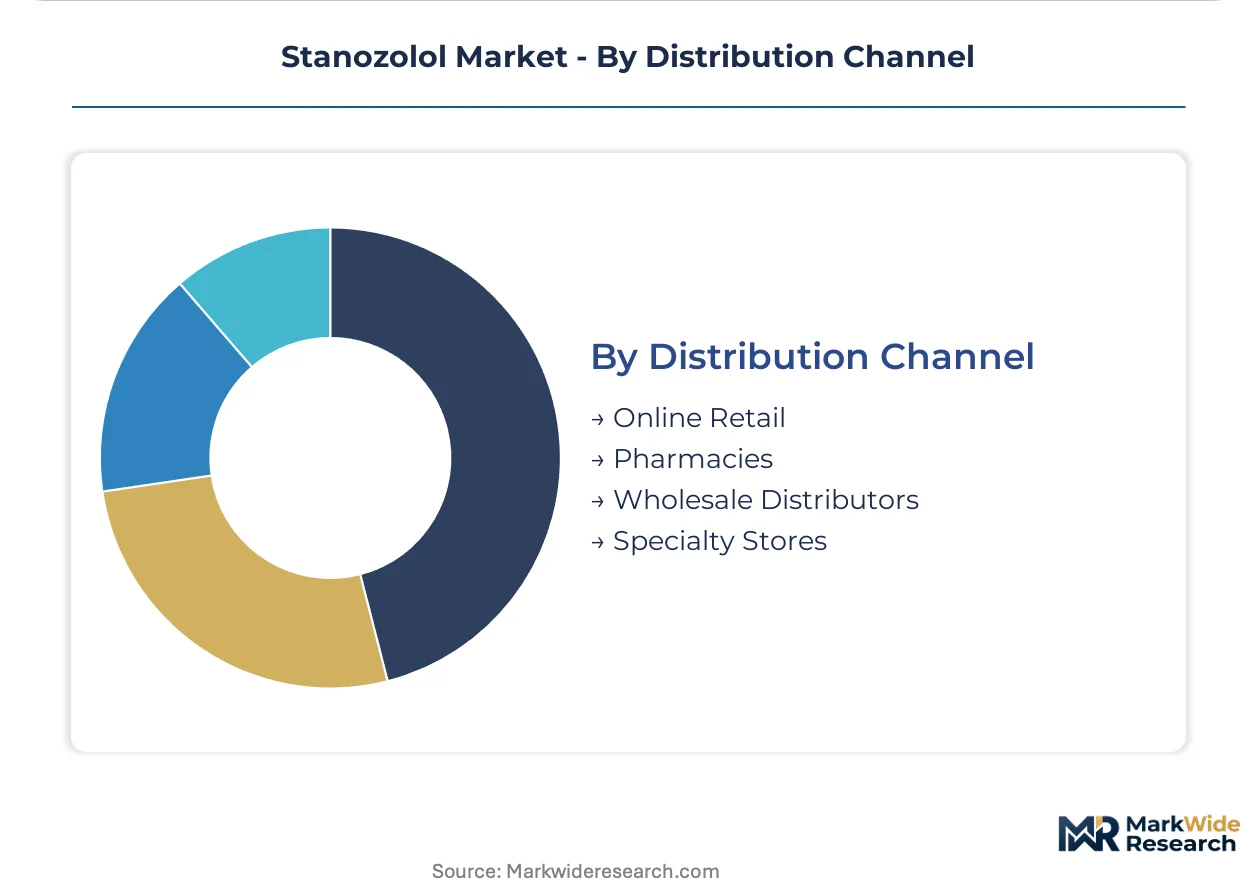
Channel segmentation tracks the displacement of physical brokerage by digital infrastructure and the persistence of institutional access points.
- Online Retail:Encrypted marketplace platforms with cryptocurrency settlement and verified laboratory documentation. Southeast Asian operators leverage microfluidic synthesis capabilities to reduce detection footprints; blockchain-secured provenance systems enable quality differentiation.
- Pharmacies:Licensed dispensing with prescription authorization and regulatory compliance infrastructure. EMA harmonization gaps across EU member states create cross-border arbitrage opportunities.
- Wholesale Distributors:Bulk procurement intermediaries serving compounding operations and veterinary supply chains. Indian CDSCO registration pathways sustain export-oriented positioning for regional formulators.
- Specialty Stores:Gym-adjacent retail with supplement portfolio diversification and community-based trust relationships. Eastern European networks in Bulgaria and Serbia maintain physical presence despite platform migration.
Online Retail holds installed capacity. Pharmacies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Southeast Asian buyers prioritize cost minimization above verification standards, while German and Australian demand clusters absorb substantial premiums for documented purity and provenance.
United States
Texas and Florida metropolitan clusters drive North American volume through direct-to-consumer platform migration. DEA Schedule III classification under the Anabolic Steroid Control Act imposes severe distribution penalties, compressing legitimate pharmaceutical pathways. Underground laboratory networks in Houston and Miami exploit veterinary supply chain gaps to feed bodybuilding demand.
Germany
Sports professional segments exhibit highest quality verification willingness among European buyers. EMA scheduling harmonization with national BfArM enforcement creates cross-border procurement arbitrage into Poland and Czechia. Berlin-Brandenburg chemical synthesis clusters serve as distribution nodes for Eastern European channel migration.
China
Raw material concentration dominates global precursor supply for pyrazole ring intermediates. NMPA pharmaceutical scheduling and precursor chemical controls under State Council regulations constrain domestic distribution. Zhejiang and Jiangsu province chemical parks anchor API manufacturing capacity for export-oriented positioning.
India
Veterinary therapeutic protocols sustain residual manufacturing authorization through CDSCO registration pathways. Maharashtra and Gujarat steroid synthesis infrastructure supports export-oriented formulators serving Middle Eastern and African demand. Domestic regulatory frameworks for veterinary steroids remain less restrictive than Western equivalents.
Brazil
Animal husbandry licensing creates diversion channels for emerging market supply. ANVISA pharmaceutical controls face enforcement capacity constraints in peripheral states. São Paulo and Paraná agricultural regions concentrate veterinary therapeutic demand that feeds regional redistribution networks.
Stanozolol Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Stanozolol landscape. Large-scale API manufacturers with captive fermentation or synthesis infrastructure command cost advantages in regulated European markets, while regional formulators compete on raw material sourcing agility and distribution network penetration. Two strategic archetypes dominate: vertically integrated pharmaceutical conglomerates with veterinary licensing portfolios, and agile underground laboratory operators exploiting precursor availability in Southeast Asian chemical clusters. Competitive moves concentrate on backward integration into pyrazole intermediate supply and geographic expansion through CDSCO-registered Indian manufacturing platforms.
Among integrated pharmaceutical conglomerates, Hikma Pharmaceuticals PLC and Sun Pharmaceutical Industries Ltd. occupy positions exemplifying the regulated-market archetype, with the former representing European-anchored veterinary licensing strategies and the latter anchoring Indian export-oriented steroid synthesis infrastructure. Zhejiang Xianju Pharmaceutical sits within the specialist tier, occupying a position that exemplifies Chinese raw material sourcing dominance through precursor supply chain control.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals PLC |
| Sun Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Organon |
| Zhejiang Xianju Pharmaceutical |
| Guangxi Nanning Baihui Pharmaceutical Group |
| Chifeng Mengxin Pharmaceutical |
| Guangzhou Baiyunshan Pharmaceutical |
| Actavis Pharma Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for palladium catalyst supply lock in both pyrazole intermediate access and cost predictability for API manufacturers navigating DEA scheduling constraints. These arrangements tether pricing power to raw material security across regulated veterinary channels and underground laboratory networks.
Pricing Analysis
After-sales documentation and blockchain-verified provenance systems drive lifetime value capture in encrypted distribution channels. Three-tier pricing structure across pharmaceutical-grade, verified-laboratory, and unverified economy levels stratifies buyer segments. Certification tier—WADA-compliant testing documentation versus informal quality claims—commands substantial premiums in German and Australian demand clusters. Cost compression in economy-tier powder segments intensifies as Southeast Asian microfluidic synthesis expands capacity. Fitness enthusiasts exhibit highest price sensitivity, while tested sports professionals absorb premiums for documented purity.
Supply Chain Analysis
Strategic stockpiling of pyrazole ring intermediates dominates inventory strategy as geopolitical friction threatens Chinese precursor continuity. Manufacturing concentration centers on China for raw material supply, India for CDSCO-registered veterinary formulation, and Thailand for underground laboratory conversion. Critical dependencies include palladium catalysts, specialized reagents, and gelatin capsule shells. Single-source vulnerability in pyrazole intermediate supply poses structural risk to synthesis economics. Distribution runs through encrypted direct-to-consumer platforms displacing traditional gym-based brokerage in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in documentation verification and cryptocurrency-settlement infrastructure expand faster than physical product throughput. Recurring revenue from blockchain-secured provenance subscriptions outpaces hardware margins in premium distribution channels.
For Market Incumbents: Secure backward integration into pyrazole intermediate supply chains to defend against Chinese precursor export restrictions. Lock in CDSCO-registered manufacturing capacity in Maharashtra and Gujarat to anchor export-oriented positioning. Threat substitution from bioidentical hormone convergence in US compounding pharmacy channels demands certification investment as defensive lever. For New Entrants and Emerging Players: Differentiate on microfluidic continuous-flow synthesis capabilities to reduce detection footprints and accelerate batch turnaround. Target veterinary therapeutic diversion from Brazilian animal husbandry operations as most penetrable supply corridor. Go-to-market angle leverages direct-to-consumer encrypted platforms with cryptocurrency settlement in Texas and Florida metropolitan clusters. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated API manufacturers with captive precursor supply and veterinary licensing portfolios. Long-term viability hinges on regulatory arbitrage sustainability across emerging market jurisdictions. Signal to watch: EMA harmonization enforcement tightening that would compress cross-border channel exploitation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive pyrazole intermediate production insulates margin from Chinese export volatility. |
| CDSCO Registration Expansion | Indian veterinary pathway enables export positioning with less restrictive domestic frameworks. |
| Microfluidic Synthesis Adoption | Continuous-flow systems compress timelines from weeks to days in Southeast Asian laboratories. |
| Blockchain Provenance Deployment | Verified documentation commands premium pricing in encrypted direct-to-consumer channels. |
| Veterinary Licensing Portfolio Buildout | Animal husbandry authorization in Brazil and Argentina sustains residual manufacturing capacity. |
Research Methodology
A standing panel of steroid synthesis chemists, veterinary supply chain managers, encrypted platform operators, and anti-doping enforcement officials provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA scheduling filings, DEA enforcement actions, WADA prohibited substance protocols, and EMA regulatory harmonization documents. Bottom-up volume estimates from underground laboratory capacity assessments triangulated against top-down veterinary diversion tracking.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product form, application intent, end-user professionalization level, and distribution channel structure. CAGRs were derived from trajectory fitting to historical enforcement pattern impacts and precursor availability cycles. Forecast inputs incorporated palladium price volatility indices and CDSCO registration pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained regulatory compression and precursor supply continuity would require recalibration. Forecasts reflect assumptions regarding enforcement intensity and underground laboratory proliferation rates. Revision becomes warranted when EMA harmonization enforcement or Chinese precursor export controls cross threshold intensities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market