
 US Restaurant Management Market | 2026-2036
US Restaurant Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Restaurant Management Market Insights
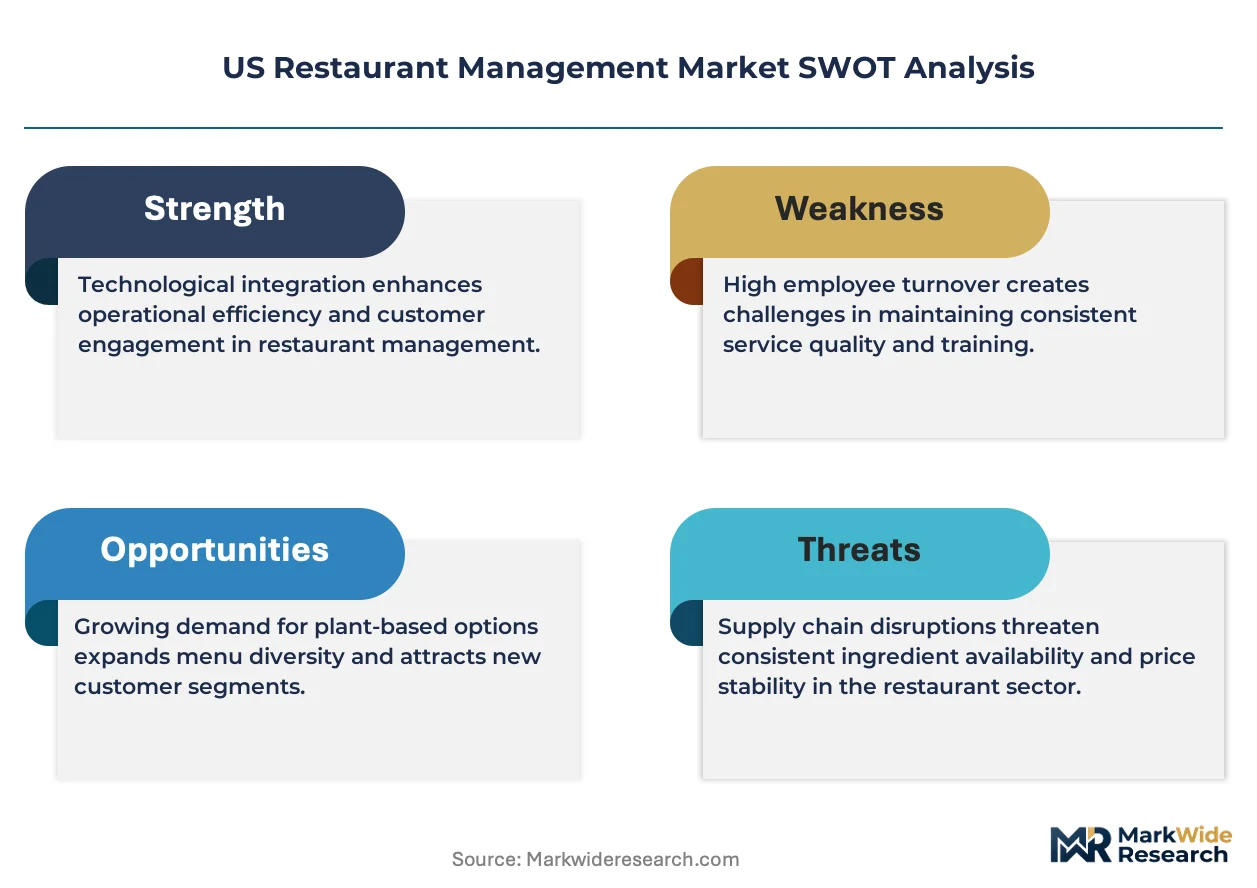
Quick service restaurants is consolidating as the dominant end-use vertical as drive-thru optimization and kiosk integration reshape operator priorities. Toast, Inc. leverages integrated payment-hardware ecosystems to anchor mid-market penetration. NCR Corporation sustains enterprise-scale kitchen display infrastructure across franchise networks. Oracle Corporation dominates cloud-native back-office analytics for multi-location operators seeking centralized labor and inventory control.
US Restaurant Management encompasses software platforms, hardware terminals, and connected services that orchestrate point-of-sale transactions, kitchen operations, staff scheduling, and supply chain procurement across foodservice establishments. These systems typically integrate touchscreen interfaces, cloud data synchronization, and API-based third-party marketplaces to reduce order latency and improve ticket accuracy. Cloud-based deployment models are capturing the fastest expansion as operators prioritize remote access and lower upfront capital requirements. Point of Sale solutions remain the largest revenue pool due to payment processing attach rates and recurring software fees. Workforce Management modules are gaining traction as minimum wage tracking and predictive scheduling laws multiply at the municipal level.
The FDA Food Code establishes baseline food safety record-keeping standards that management platforms must support through digital temperature logging and traceability dashboards. The Department of Labor's overtime and tip-credit enforcement through OSHA-aligned state labor agencies is pushing operators toward automated compliance reporting. Municipal health departments in cities like New York and Los Angeles now mandate electronic inspection readiness, accelerating replacement of paper-based systems. Stakeholders must weigh the trade-off between best-of-breed specialization and all-in-one platform consolidation as vendor ecosystems mature and switching costs compound.
Market Dynamics
Cloud-native point-of-sale infrastructure is compressing deployment cycles and forcing legacy hardware refresh decisions across independent and franchise operators. The shift from capital-intensive on-premise systems to subscription-based SaaS models is redistributing vendor power toward platforms with integrated payment processing ecosystems.
Growth Catalysts
- Fair Workweek Laws:Predictive scheduling mandates in cities like New York and San Francisco are forcing operators toward automated labor forecasting modules.
- Kitchen Display Systems:Full-service chains are accelerating adoption of cloud-connected KDS hardware to reduce ticket times and improve line coordination.
- EMV Compliance Deadlines:Liability shift rules from card networks are driving terminal replacement cycles even among cost-resistant independents.
Market Restraints
- Payment Processor Concentration:Three vendors control the majority of integrated processing APIs, creating switching friction and rate lock-in.
- Tablet Hardware Costs:Ruggedized Android and iOS devices for kitchen environments carry 40-60% premiums over consumer-grade equivalents.
- Tip-Pooling Complexity:Department of Labor FLSA interpretations create compliance uncertainty that slows feature rollout for pooled house models.
Strategic Opportunities
- Voice-Activated Ordering:Drive-thru chains in Texas and Florida are piloting NLP interfaces to reduce labor at the order station.
- Inventory-AI Convergence:Machine learning demand forecasting paired with IoT-enabled walk-in sensors is opening subscription revenue streams.
- State-Level Wage Transparency:California and Colorado posting mandates create compliance software attach opportunities for mid-market platforms.
Industry Challenges
- API Integration Debt:Operators running 15-20 disconnected systems face 6-12 month migration timelines to unified platforms.
- Certification Bottlenecks:PCI-DSS Level 1 validation for new payment entrants stretches 18-24 months, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Restaurant Management Market |
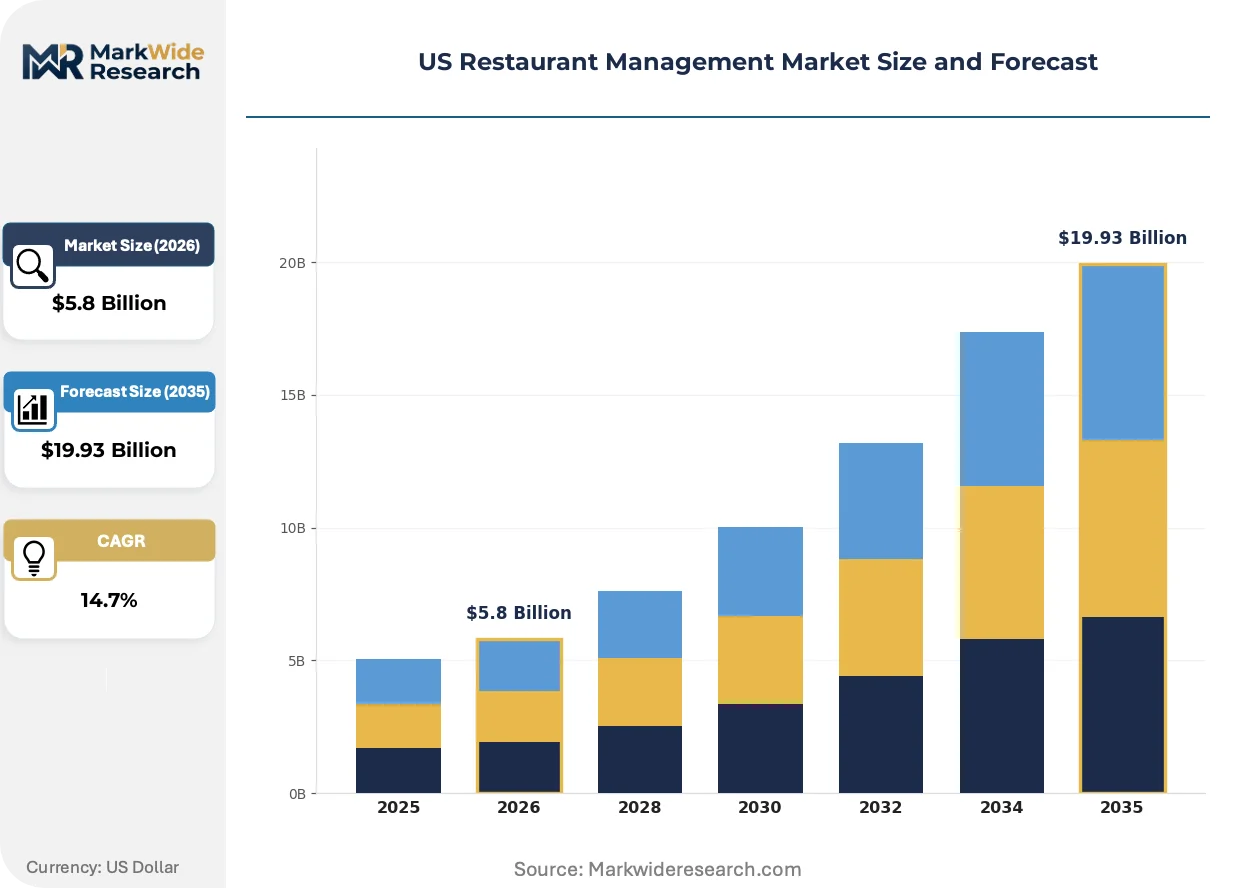
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.93 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Point of Sale, Inventory Management, Workforce Management, Customer Relationship Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile End User: Quick Service Restaurants, Full-Service Restaurants, Cafes, Food Trucks Service Type: Consulting, Technical Support, Training, Maintenance |
| Companies Covered | Toast, Inc., NCR Corporation, Oracle Corporation, Lightspeed Commerce Inc., Block, Inc., Fourth Enterprises LLC., Revel Systems, OpenTable, Inc., Jolt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Restaurant Management Market Trends and Innovations
Edge computing architectures are pushing transaction processing closer to the point of sale, reducing latency for high-volume quick-service environments. This infrastructure shift is enabling real-time decisioning that was previously locked to centralized data centers.
Kiosk-based ordering systems with integrated kitchen routing logic are decentralizing cashier labor deployment across quick-service and fast-casual footprints. Chains with 50-plus locations are rolling these units at 200-400 unit annual clips. The technology is decentralizing front-of-house staffing models and compressing average labor hours per transaction.
The FDA Food Code 2022 revision mandates digital temperature logging for Time/Temperature Control for Safety foods, forcing paper-based operators toward IoT sensor investments. State health departments in Illinois and Washington are aligning inspection protocols to this standard. Full-service independents with limited IT staff face the steepest compliance adaptation curves.
Subscription pricing for software modules is displacing perpetual license models among multi-location operators. Finance teams prefer OpEx treatment and bundled support costs. The shift is most visible in the Southeast, where private-equity-backed rollups are standardizing vendor stacks across acquired brands.
US Restaurant Management Market Segmentation
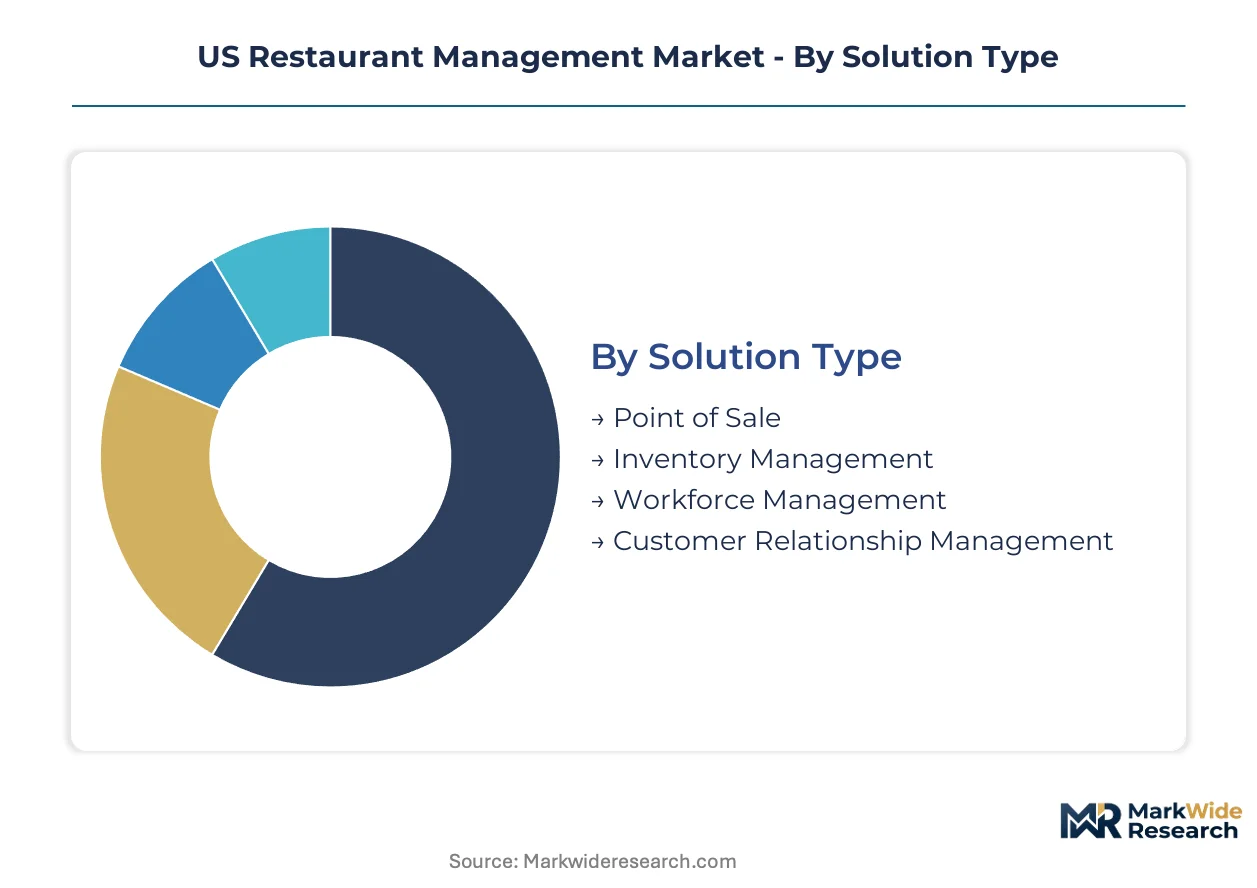
Segmentation in restaurant management platforms reveals how operator priorities diverge by scale, technical maturity, and compliance exposure. Upgrade cycles vary dramatically across these dimensions, with cloud migration and labor law automation driving replacement timelines.
Solution Type:
Replacement cycles accelerate where regulatory complexity intersects with revenue-critical operations, forcing earlier retirement of legacy modules.
- Point of Sale:Touchscreen terminals with integrated payment processing and API connectivity to third-party delivery marketplaces. Demand concentrates in quick-service chains across Texas and Florida as EMV liability rules and drive-thru throughput targets converge. Hardware refresh cycles compress to 3-4 years where payment processor contracts bundle equipment subsidies.
- Workforce Management:Predictive scheduling, time-clock integration, and tip-pooling compliance dashboards. California and New York operators lead adoption as Fair Workweek mandates and wage transparency laws multiply at the municipal level. Compliance automation justifies premium pricing even for mid-market independents.
- Inventory Management:Perpetual tracking with vendor integration and waste analytics.
- Customer Relationship Management:Loyalty programs, order history, and targeted promotion engines.
Point of Sale sits at the top of the volume ranking, with Workforce Management climbing the fastest.
Deployment Model:
Cost tier structures the competitive landscape, with capital constraints dictating adoption sequencing across independent and franchise operators.
- Cloud-Based:Browser-accessible platforms with automatic updates and subscription pricing. Urban coastal markets from Seattle to Miami show disproportionate uptake as operators prioritize remote multi-location oversight and lower upfront investment. The shift from CapEx to OpEx treatment appeals to private-equity-backed rollups standardizing tech stacks.
- On-Premises:Local server infrastructure with perpetual licensing and dedicated IT maintenance. Legacy installations persist in rural markets and established full-service independents with sunk hardware investments and limited broadband reliability.
- Hybrid:Core systems on-site with cloud backup and analytics layers.
- Mobile:Tablet-native operations for food trucks and pop-up formats.
Cloud-Based commands the largest installed base, while Mobile gains share fastest among emerging formats.
End User:
Application intensity varies by labor model complexity and transaction velocity, with kiosk integration and drive-thru optimization reshaping vendor priorities.
- Quick Service Restaurants:High-volume environments with standardized menus and drive-thru dependency. Chains with 50-plus locations deploy kiosk ordering at 200-400 unit annual clips, compressing front-of-house labor hours per transaction. Kitchen Display System integration reduces ticket times in high-throughput settings.
- Full-Service Restaurants:Table-service operations with complex scheduling and tip-pooling workflows. Independent operators in Chicago and Boston face steepest compliance adaptation curves as FDA Food Code digital logging mandates displace paper-based systems.
- Cafes:Limited-service coffee and beverage specialists with loyalty-heavy customer bases.
- Food Trucks:Mobile operators requiring ruggedized hardware and offline transaction capability.
Quick Service Restaurants sits at the top of the volume ranking, with Full-Service Restaurants climbing the fastest.
Service Type:
Customer sophistication determines attach rates, with multi-location operators demanding proactive support models that independents rarely purchase.
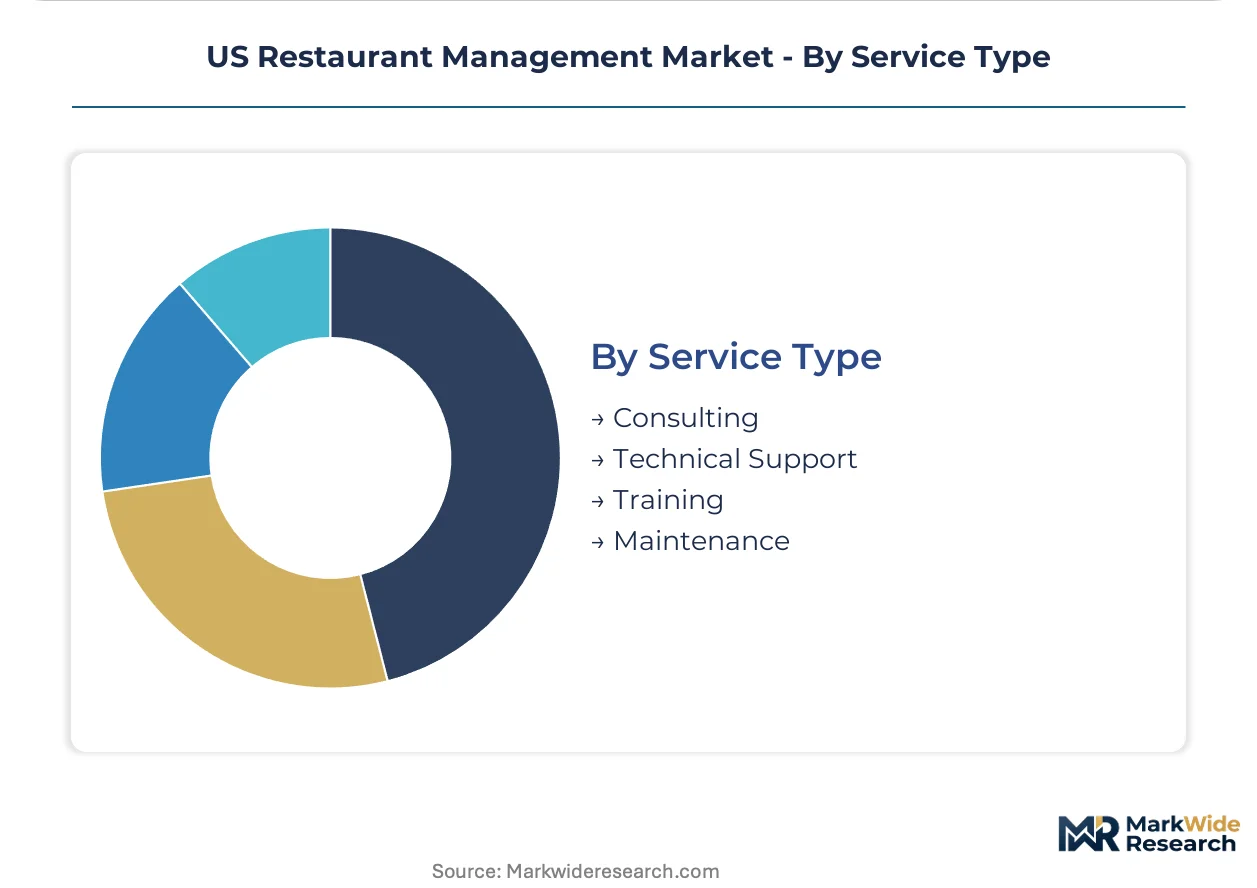
- Technical Support:24/7 system monitoring, remote troubleshooting, and escalation management. Enterprise franchise networks require guaranteed response times and dedicated account engineering that mid-market platforms struggle to staff profitably.
- Training:Onboarding programs for managers and hourly staff on scheduling, reporting, and compliance workflows. High-turnover environments in quick-service drive recurring demand for refresher modules and certification tracking.
- Consulting:Workflow optimization and vendor selection advisory.
- Maintenance:Preventive hardware service and replacement part logistics.
Technical Support sits at the top of the volume ranking, with Training climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pushing platform adoption toward jurisdictions with stricter labor compliance mandates, as operators in high-mandate states accelerate cloud migration to automate reporting workflows.
California
Fair Workweek ordinances in Los Angeles and San Francisco drive predictive scheduling module demand. State wage transparency posting requirements create compliance software attach opportunities. The Bay Area corridor concentrates venture-backed QSR rollouts testing voice-activated drive-thru interfaces.
New York
New York City predictive scheduling laws compress labor forecasting upgrade cycles. State Department of Labor tip-credit enforcement pushes automated compliance reporting adoption. Manhattan full-service independents face steepest FDA Food Code digital logging adaptation curves.
Texas
High-volume drive-thru chains pilot NLP ordering systems to reduce labor at the order station. Absence of state-level scheduling mandates slows workforce management module adoption relative to coastal markets. Dallas-Fort Worth corridor anchors franchise network standardization of kitchen display infrastructure.
Florida
Kiosk deployment accelerates across quick-service footprints as labor costs rise in Miami and Orlando metros. State health department alignment with FDA Food Code 2022 drives IoT sensor investments for temperature logging. Tampa-St. Petersburg cluster concentrates mid-market platform consolidation activity.
Illinois
Chicago municipal Fair Workweek enforcement triggers automated scheduling adoption among full-service operators. State health department inspection protocol digitization accelerates paper-based system replacement. The metro corridor sustains legacy on-premise installations among established independents with limited IT staffing.
US Restaurant Management Market Competitive Landscape
Platform consolidation dominates the current landscape as operators confront API integration debt across 15-20 disconnected systems. The vendor base organizes around three strategic tiers: integrated payment-hardware ecosystems anchoring mid-market penetration, enterprise-scale kitchen infrastructure sustaining franchise networks, and cloud-native back-office analytics serving multi-location operators. M&A activity and vertical capability expansion represent the dominant competitive vectors as switching costs compound.
Within the integrated ecosystem tier, Toast, Inc. and Block, Inc. occupy positions emphasizing payment processing attach rates and recurring software fees. Oracle Corporation anchors the enterprise analytics tier with cloud-native deployment models capturing demand from private-equity-backed rollups standardizing tech stacks. NCR Corporation exemplifies the infrastructure-focused archetype sustaining kitchen display system penetration across high-throughput franchise networks.
| Leading Market Players |
|---|
| Toast, Inc. |
| NCR Corporation |
| Oracle Corporation |
| Lightspeed Commerce Inc. |
| Block, Inc. |
| Fourth Enterprises LLC. |
| Revel Systems |
| OpenTable, Inc. |
| Jolt |
| Others |
Pricing and Supply Chain Analysis
DRAM pricing indices and semiconductor foundry utilization rates cascade through hardware terminal manufacturing into three-tier subscription pricing across cloud-native platforms, with ruggedized Android device premiums compressing margins for mid-market operators in high-labor-cost metros.
Pricing Analysis
Distributor margins on payment processing hardware range from 15 to 25 percent before value-added installation services. SaaS-tiered subscription models dominate, with price differentiation driven by EMV certification tier and integration complexity with third-party delivery marketplaces. Pricing pressure stems from payment processor concentration among three dominant API vendors. Quick-service franchise networks show least price sensitivity due to bundled equipment subsidies, while independent full-service operators in secondary markets resist premium workforce management modules.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale franchise network demand for kitchen display infrastructure, bypassing traditional distribution layers. Hardware assembly concentrates in Taiwan, China, and Mexico. Component dependencies include ARM-based chipsets, capacitive touchscreen panels, and PCI-compliant encryption modules. Single-source vulnerability runs through Taiwan semiconductor foundries serving payment terminal processors. Distribution runs through authorized reseller networks for mid-market independents requiring localized support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between California's wage transparency mandate compliance costs and Texas's absence of predictive scheduling laws, rewarding operators who standardize cloud platforms across mixed-regulatory footprints.
For Market Incumbents: Deploy payment-hardware ecosystem lock-in to anchor replacement cycles against Toast and Block's integrated attach rates. Consolidate kitchen display infrastructure share in high-throughput QSR networks before voice-activated ordering pilots scale. Defensive moves require API integration debt resolution for operators running 15-20 disconnected systems, plus PCI-DSS Level 1 certification investment to delay new entrant market entry.
For New Entrants and Emerging Players: The $40-60 monthly per-location gap between premium Oracle cloud analytics and economy-tier tablet-native solutions opens white-space targeting. Mid-market full-service independents in Chicago and Boston present most penetrable segment due to steepest FDA Food Code compliance adaptation curves. Go-to-market angle: IoT-enabled temperature logging bundled with predictive scheduling at standard-tier pricing.
For Investors and Strategic Acquirers: Asymmetric upside sits with workforce management specialists possessing Fair Workweek automation modules in California and New York municipal enforcement zones. Long-term viability over a 5-10 year horizon favors platforms with tip-pooling compliance architectures as Department of Labor FLSA interpretations stabilize. Signal to watch: private-equity rollup activity in the Southeast standardizing vendor stacks across acquired brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified POS-workforce-inventory stacks reduce API integration debt for multi-location operators. |
| Voice-Activated Ordering Pilot | NLP drive-thru interfaces in Texas and Florida compress labor hours per transaction for high-volume chains. |
| IoT Sensor Deployment | FDA Food Code 2022 temperature logging mandates force paper-based operator hardware refresh cycles. |
| Payment Processor API Expansion | Third-party marketplace connectivity anchors subscription retention against best-of-breed competitors. |
| Geographic Expansion | Coastal urban cloud adoption patterns guide Southeast private-equity rollup standardization opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged restaurant technology directors, franchise operations executives, municipal health department inspectors, and payment processor product managers. Secondary validation drew from FDA Food Code revision documents, state labor department enforcement bulletins, PCI-DSS certification registries, and SEC filings of publicly traded platform vendors. Bottom-up unit economics modeling triangulated against top-down market sizing across deployment models and end-use verticals.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include solution type, deployment architecture, end-user format, and service tier. CAGRs derived from installed base growth rates, replacement cycle compression, and attach rate expansion for workforce management modules. Forecast inputs incorporated Fair Workweek ordinance rollout timelines and EMV liability shift enforcement patterns.
Caveats apply where FDA Food Code state adoption delays or tip-pooling regulatory reversals could materially shift the outlook. Forecasts reflect assumptions on cloud migration velocity and private-equity consolidation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Catering Services Market