
 Smart Hospitality Management Market | 2026-2036
Smart Hospitality Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Hospitality Management Market Outlook
GDPR enforcement is restructuring data residency requirements for guest management platforms across European operations. Cloudbeds leverages cloud-native architecture to sustain compliance across fragmented national frameworks. Operto anchors its position through IoT hardware specialization in automated access and climate control. Agilysys competes on legacy property management system integration, extending incumbent relationships into smart-upgrade cycles.
Smart hospitality management denotes the deployment of networked sensors, cloud-based software, and algorithmic decision engines to automate guest services, optimize building systems, and unify revenue operations across lodging and food-service properties. Core infrastructure typically includes API-connected property management systems processing sub-second guest preference updates, edge-computing nodes for real-time energy load balancing, and machine-learning models forecasting occupancy-adjusted staffing. Artificial Intelligence segments command premium service fees due to predictive personalization complexity, while IoT Solutions segments face margin compression from commoditized sensor hardware. Hotels dominate end-user spending through multi-property rollout contracts, whereas Cruise Lines represent a concentrated but slower-adoption niche constrained by satellite bandwidth limitations.
EU AI Act classification rules, GDPR data-processing agreements, and FERC building-efficiency standards for commercial properties collectively elevate compliance costs for platform vendors seeking cross-border scale. FDA cybersecurity guidance for connected devices indirectly shapes IoT supplier qualification protocols in US hospitality deployments. Stakeholders must weigh regulatory divergence against standardization gains when selecting between regional point solutions and global platform architectures.
Market Dynamics
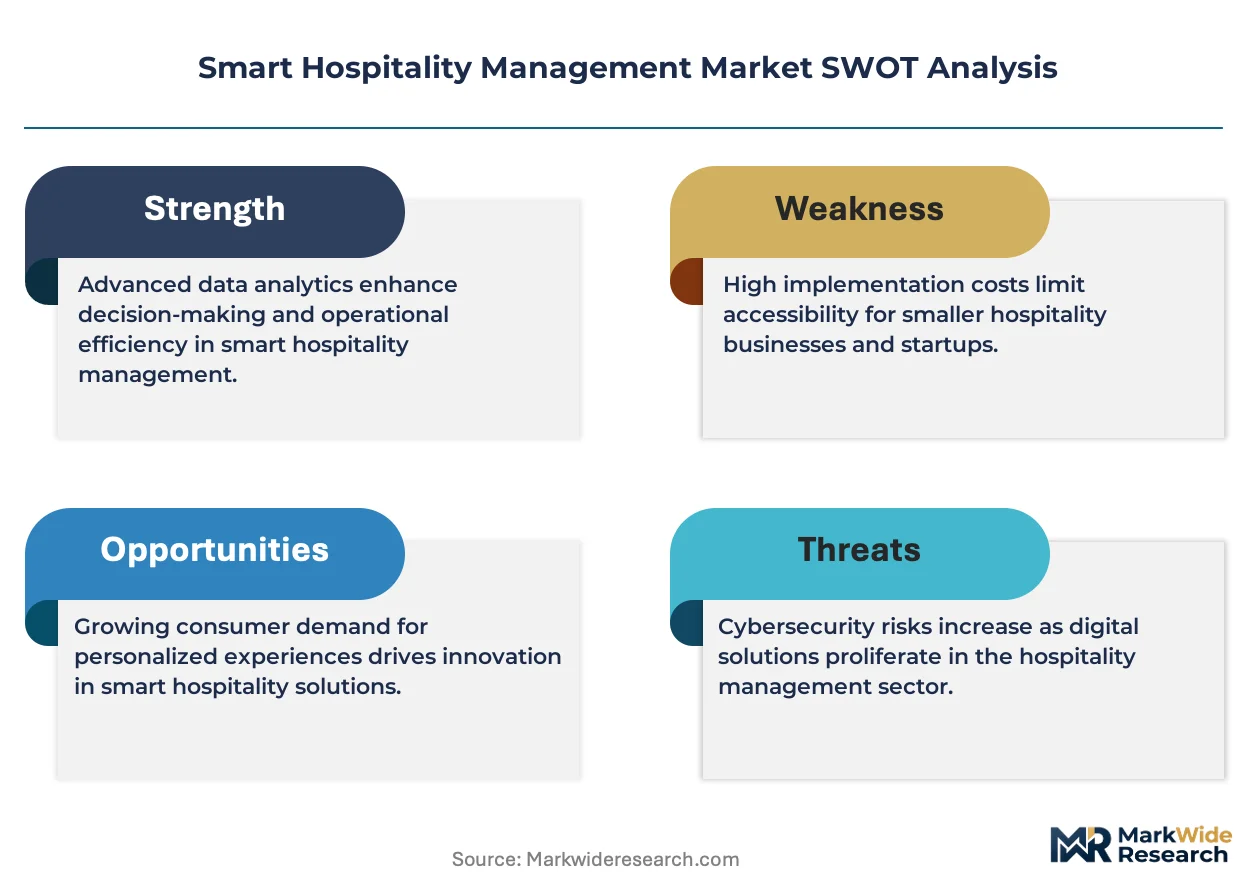
EU AI Act classification rules are forcing platform vendors to restructure algorithmic guest-facing systems, elevating compliance architecture from operational cost to competitive differentiator in cross-border hospitality deployments.
Growth Catalysts
- EU AI Act high-risk system mandates:Automated check-in and personalized pricing engines now require conformity assessments, creating procurement pull for certified vendors.
- Independent boutique hotel consolidation:Property-level operators seek revenue optimization without enterprise IT overhead, driving demand for modular cloud-native platforms.
- Edge computing for real-time energy balancing:IoT sensor networks processing sub-second climate adjustments reduce utility costs and support FERC building-efficiency compliance.
Market Restraints
- GDPR data-residency fragmentation:Cross-border guest data flows face divergent national implementation, complicating single-tenant cloud architectures.
- Commoditized sensor hardware:IoT Solutions segments confront margin compression as generic temperature and occupancy sensors flood procurement channels.
- Satellite bandwidth constraints:Cruise Lines encounter deployment delays for real-time guest service automation due to maritime connectivity limitations.
Strategic Opportunities
- German mid-scale chain consolidation:Technology procurement centralization creates volume contracts for integrated property management and smart-building platforms.
- API-connected legacy system bridges:Algorithmic decision engines converging with incumbent property management systems unlock upgrade cycles without rip-and-replace disruption.
- CSRD sustainability disclosure mandates:Corporate hotel groups require granular energy and water consumption tracking, expanding addressable market for building-automation analytics.
Industry Challenges
- Interoperability certification timelines:Multi-vendor IoT ecosystems face delays achieving unified cybersecurity protocols for connected access and climate devices.
- Guest data scientist scarcity:Predictive personalization models require hospitality-domain machine-learning expertise that competes with broader retail and finance sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Hospitality Management Market |
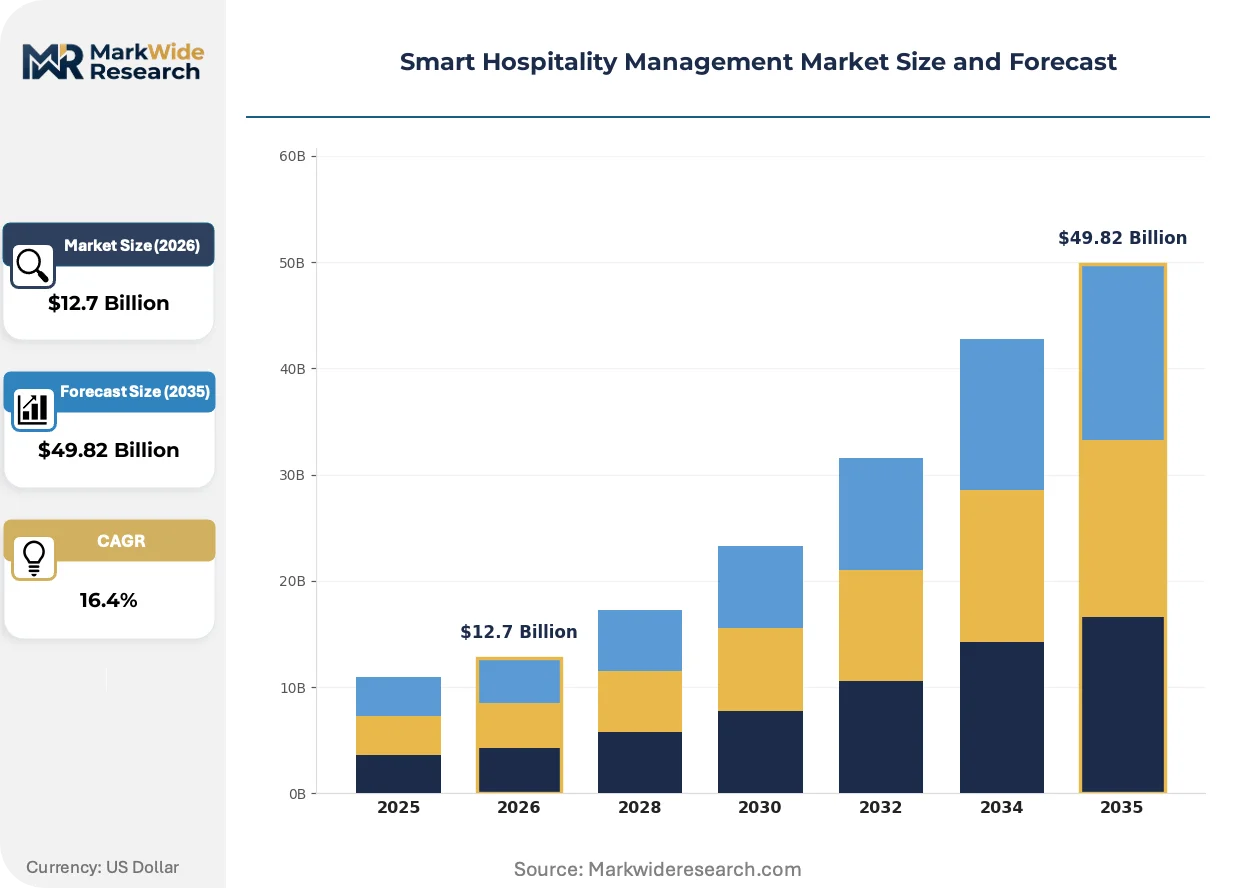
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Cloud Computing, Artificial Intelligence, Big Data Analytics End User: Hotels, Restaurants, Cruise Lines, Resorts Application: Room Management, Customer Engagement, Energy Management, Payment Solutions Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | eviivo, Optii, Cloudbeds, SEVENROOMS, Agilysys, Apaleo, Operto, igloohome, RMS Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Hospitality Management Market Strategic Shifts
Algorithmic personalization engines and regulatory compliance architectures are restructuring competitive positioning across guest service automation, with vendor differentiation shifting from feature breadth to certified cross-border deployment capability.
Machine-learning occupancy forecasting is expanding into staffing optimization and dynamic pricing orchestration. Mid-scale hotel chains in Germany and France deploy these models to align labor scheduling with predicted guest volume. The technology is compressing revenue management cycles from weekly to intraday adjustments.
EU AI Act high-risk system obligations now govern automated guest profiling and biometric access control. Vectors must maintain technical documentation and human oversight protocols for algorithmic decision systems. Boutique properties face steeper relative compliance costs than integrated resort operators with captive legal resources.
Subscription-based platform economics are displacing perpetual license models in property management system procurement. Independent hotels in Spain and Italy favor operational expenditure structures that bundle software, IoT hardware, and support services. Channel partners and hospitality technology consultants capture margin from implementation and change-management services previously retained by vendors.
Smart Hospitality Management Market Segmentation
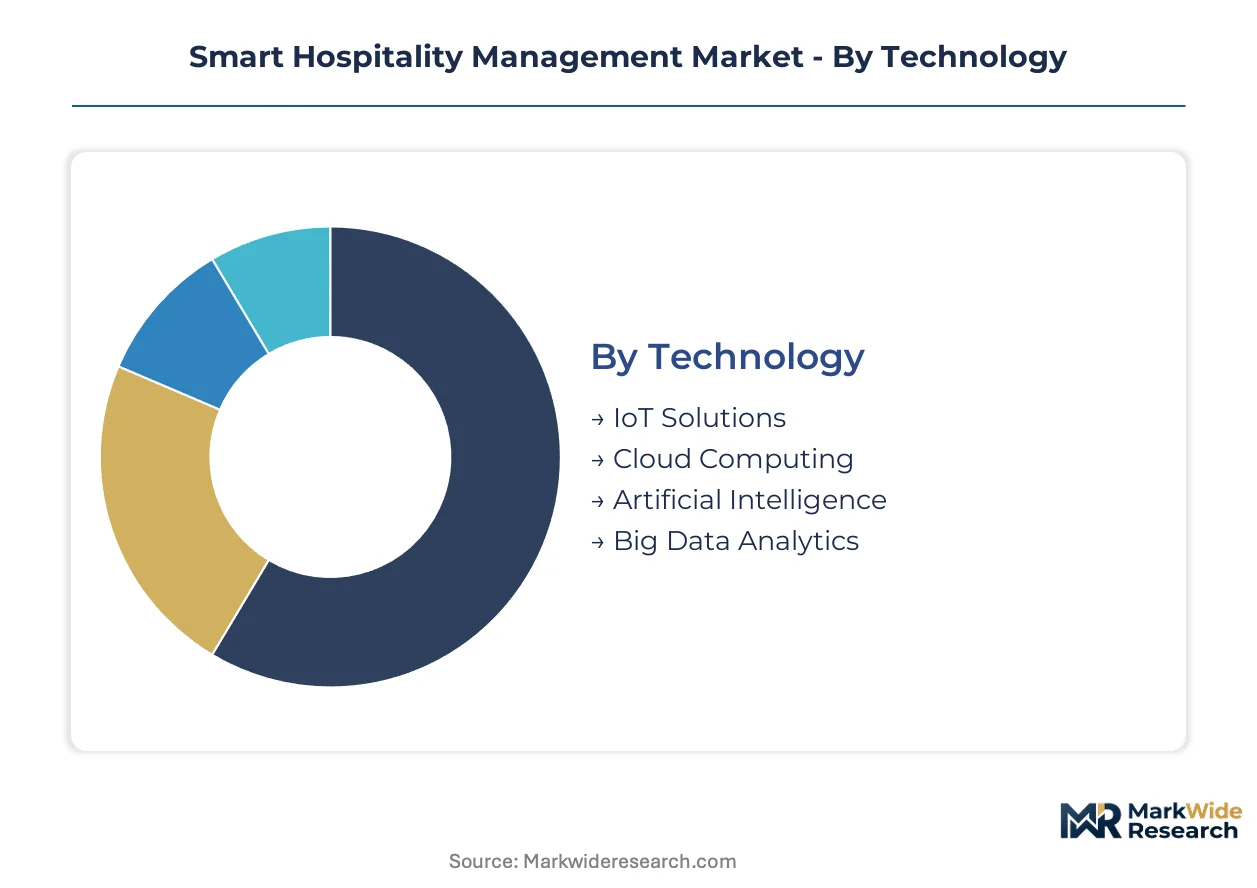
Segmentation in smart hospitality management reveals divergent capital requirements and deployment complexity across technology layers, with AI-driven systems demanding substantially higher upfront investment than sensor-based infrastructure. Understanding these cost gradients helps vendors calibrate go-to-market strategies and pricing architectures for distinct buyer profiles.
Technology:
Capital intensity varies dramatically across technology categories, with AI platforms requiring specialized talent and compute infrastructure while IoT deployments scale through commoditized hardware procurement.
- Artificial Intelligence:Machine-learning personalization engines and predictive revenue optimization models process sub-second guest preference updates. German mid-scale chains deploy these systems to compress pricing cycles from weekly to intraday adjustments, though EU AI Act conformity assessments add compliance overhead.
- IoT Solutions:Networked sensor arrays for climate control, access management, and occupancy detection anchor building automation at the property level. Edge-computing nodes enable real-time energy load balancing that satisfies FERC commercial building standards in US deployments.
- Cloud Computing:Cloud-native property management platforms sustain GDPR data-residency compliance across fragmented European national frameworks.
- Big Data Analytics:Granular consumption tracking tools address CSRD sustainability disclosure mandates for corporate hotel groups.
IoT Solutions absorbs the bulk of installed capacity; Artificial Intelligence is expanding most quickly.
End User:
Buyer sophistication and procurement centralization create distinct deployment patterns, with multi-property operators favoring integrated platforms over point solutions.
- Hotels:Multi-property rollout contracts dominate spending, spanning boutique independents seeking modular cloud-native platforms and integrated resort operators with captive legal resources for compliance navigation.
- Restaurants:Food-service properties deploy unified revenue operations systems that converge kitchen automation with guest-facing digital ordering.
- Cruise Lines:Maritime connectivity limitations constrain real-time guest service automation, creating concentrated but slower-adoption demand for satellite-optimized systems.
- Resorts:Mixed-use hospitality complexes require API-connected bridges between legacy property management systems and algorithmic decision engines.
Hotels command the dominant share of procurement volume; Cruise Lines present the steepest expansion trajectory once bandwidth constraints ease.
Application:
Functional deployment priority reflects operational pain points, with energy cost pressures and labor optimization driving fastest adoption in building systems and workforce management.
- Energy Management:IoT sensor networks processing sub-second climate adjustments reduce utility expenditures while supporting regulatory efficiency mandates. German properties leverage these systems to meet national building codes.
- Customer Engagement:Algorithmic personalization engines automate guest profiling and service recommendations, though EU AI Act high-risk system obligations now govern biometric access control deployments.
- Room Management:Automated check-in and digital key distribution streamline front-desk operations for labor-constrained properties.
- Payment Solutions:Integrated revenue operations unify lodging and food-service transactions across multi-venue hospitality complexes.
Energy Management captures the largest installed base; Customer Engagement climbs the fastest as personalization complexity becomes a competitive differentiator.
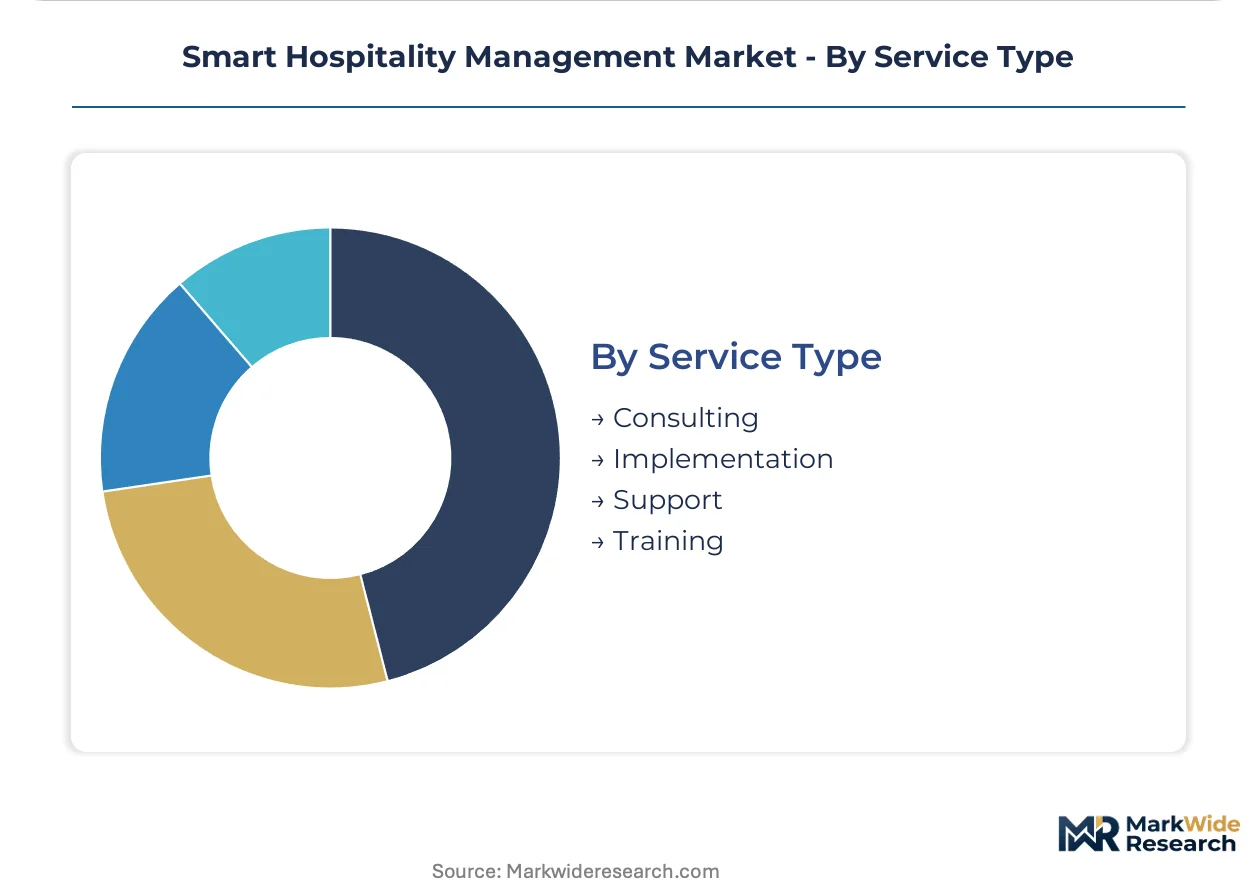
Service Type:
Recurring revenue models are displacing perpetual licenses, with subscription bundles capturing margin from implementation services previously retained by channel partners.
- Implementation:System integration and legacy migration services unlock upgrade cycles without rip-and-replace disruption for incumbent property management relationships.
- Support:Ongoing technical maintenance and compliance update management sustain platform performance across regulatory evolution.
- Consulting:Hospitality technology advisors guide procurement centralization for mid-scale chains consolidating vendor relationships.
- Training:Change-management services address guest data scientist scarcity by developing hospitality-domain machine-learning expertise internally.
Implementation services represent the largest revenue pool; Support contracts gain share fastest as operational expenditure structures displace capital purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent boutique hotels in Germany concentrate procurement demand for modular cloud-native platforms that optimize revenue without enterprise IT overhead. Mid-scale chains across France and Italy consolidate technology vendor relationships to satisfy EU AI Act compliance requirements. Maritime connectivity limitations constrain real-time automation deployment for cruise operators in Mediterranean and Baltic routes.
Germany
Mid-scale hotel chains in Munich and Frankfurt drive centralized technology procurement for integrated property management platforms. The EU AI Act mandates conformity assessments for automated check-in and biometric access systems, elevating compliance costs for independent operators. Bavaria's hospitality technology cluster concentrates vendor development activity for algorithmic revenue optimization tools.
United States
Multi-property resort operators in Florida and California deploy edge-computing networks for real-time energy load balancing. FERC commercial building-efficiency standards shape IoT sensor qualification protocols for climate automation systems. Greater Miami's hospitality corridor anchors development of satellite-optimized platforms for cruise line connectivity constraints.
France
Parisian boutique properties adopt subscription-based platform economics to displace perpetual license procurement structures. CNIL enforcement of GDPR data-residency requirements complicates single-tenant cloud architectures for cross-border guest data flows. The Île-de-France region concentrates hospitality technology consulting services for procurement centralization.
United Kingdom
London hotel groups integrate API-connected bridges between legacy property management systems and algorithmic decision engines. The UK Information Commissioner's Office enforces data processing agreements that parallel GDPR fragmentation across European operations. Scotland's hospitality automation sector specializes in building-system analytics for CSRD sustainability disclosure mandates.
Spain
Independent hotels in Barcelona and Madrid favor operational expenditure structures bundling software, IoT hardware, and support services. Spanish data protection authority implementation of GDPR national frameworks creates compliance complexity for single-tenant cloud deployments. Andalusia's resort complexes drive demand for unified revenue operations across lodging and food-service venues.
Smart Hospitality Management Market Competitive Environment
US-based cloud-native platform providers anchor the premium tier; European specialists hold compliance-adjacent positions. The vendor base concentrates around three strategic archetypes: legacy property management system extenders, IoT hardware specialists, and algorithmic personalization engine developers. Competitive dynamics center on M&A activity consolidating point solutions into integrated suites and strategic partnerships bridging incumbent relationships with smart-upgrade cycles.
Within the cloud-native platform tier, Cloudbeds and Agilysys exemplify divergent approaches to incumbent market penetration. Cloudbeds represents the architecture-first archetype leveraging multi-tenant infrastructure for cross-border compliance scalability. Agilysys occupies a position as legacy system extender, anchoring relationships through API-connected bridges rather than rip-and-replace disruption. Operto sits within the IoT specialization vector, concentrating on automated access and climate control hardware differentiation.
| Leading Market Players |
|---|
| eviivo |
| Optii |
| Cloudbeds |
| SEVENROOMS |
| Agilysys |
| Apaleo |
| Operto |
| igloohome |
| RMS Cloud |
| Others |
Value Chain & Pricing Dynamics
CSRD sustainability disclosure mandates gate qualified supply access and premium-tier pricing power for hospitality technology vendors serving corporate hotel groups across European operations. Compliance-certified platforms command service fee premiums while non-certified competitors face procurement exclusion from centralized mid-scale chain tenders.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployment premiums from standard-schedule discounts across property management system procurement. Subscription-based SaaS tiers dominate, with EU AI Act conformity assessments and GDPR data-residency compliance acting as price differentiation drivers between certified and uncertified vendors. Cost compression in IoT sensor hardware is intensifying because commoditized temperature and occupancy devices flood procurement channels. Independent boutique hotels exhibit highest price sensitivity; integrated resort operators with captive legal resources demonstrate lowest sensitivity to compliance-premium pricing.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific sensor manufacturing hubs elevates landed costs for European and North American hospitality deployments. Hardware supply concentrates in China, Taiwan, and South Korea for edge-computing nodes and networked sensor arrays. Component dependencies include semiconductor chips, lithium-ion power cells, and precision climate sensors. Single-source vulnerability persists for specialized biometric access control modules. Distribution runs through hospitality technology consultants and channel partners bundling implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native platform architectures are displacing legacy on-premise property management systems, restructuring competitive positioning around compliance-scalable infrastructure rather than feature breadth alone.
For Market Incumbents: Hedge against API-connected bridge commoditization by deepening in-house production of algorithmic personalization engines and securing captive supply of EU AI Act-certified compliance documentation. Vertical integration into edge-computing hardware development defends margin position against IoT sensor margin compression.
For New Entrants and Emerging Players: Enter via white-space targets in Spanish and Italian independent hotel segments favoring operational expenditure procurement structures. The most penetrable geography is Germany's mid-scale chain consolidation wave. A go-to-market angle bundling software, IoT hardware, and support services captures margin from channel partners.
For Investors and Strategic Acquirers: German mid-scale chain technology procurement centralization is the leading indicator that subscription-based platform economics will dominate perpetual license displacement. Long-term viability centers on vendors with cross-border compliance scalability. Acquisition target archetype: IoT hardware specialists with automated access and climate control differentiation. The signal to watch is satellite bandwidth cost reductions unlocking cruise line automation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Certified vendors capture procurement pull from automated check-in and biometric access mandates. |
| API-Connected Legacy System Bridges | Algorithmic decision engines unlock upgrade cycles without rip-and-replace disruption for incumbent relationships. |
| Edge-Computing Node Deployment | Real-time energy load balancing satisfies FERC commercial building-efficiency standards in US properties. |
| Subscription Platform Economics | Operational expenditure structures displace capital purchases across Spanish and Italian independent hotels. |
| IoT Hardware Specialization | Automated access and climate control differentiation anchors building automation at the property level. |
Study Parameters
Independent corroboration across property technology executives, hospitality procurement officers, cloud platform engineers, and regulatory compliance specialists underwrites the qualitative findings. Primary interviews with channel partners and integration specialists combined with secondary validation from SEC filings, EU AI Act implementation guidance, and hospitality technology consultant disclosures establish demand-side ground truth. Bottom-up property-level deployment tracking and top-down vendor revenue analysis triangulate market sizing.
Comparable-period anchoring to historical adoption curves across the analysis window structures the forecast framework. Segmentation dimensions modeled include technology layer, end-user category, application function, and service type. CAGRs derive from algorithmic personalization engine expansion rates and IoT sensor network deployment velocities. Forecast inputs incorporate EU AI Act compliance timeline acceleration and satellite bandwidth cost trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios and maritime connectivity breakthrough conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
Europe Casino Management Market