
 Chinese Restaurant Franchising Market | 2026-2036
Chinese Restaurant Franchising Market Size, Share, and Industry Trends Forecast 2026-2036
Chinese Restaurant Franchising Market Insights
China's dual carbon goals is pivoting franchise development toward energy-efficient kitchen equipment and renewable-powered locations. Panda Express leverages its standardized supply chain to accelerate store rollouts across provincial capitals. Mixue sustains aggressive expansion through rock-bottom unit economics and self-built distribution networks. Chagee differentiates via tea-centric menus that command higher margins than full-meal concepts.
Chinese restaurant franchising denotes a commercial arrangement where a franchisor licenses its brand, recipes, and operational protocols to independent operators in exchange for fees and royalties, typically requiring standardized kitchen layouts of 80-150 square meters and central commissary supply. The primary purpose is replicable brand penetration without capital-heavy corporate ownership. Multi-unit franchises dominate expansion velocity as operators amortize overhead across several locations. Fast casual formats capture the fastest-growing demand segment as consumers trade up from street food without accepting full-service prices. Traditional Chinese menu positioning remains the largest revenue pool but faces margin compression from rising ingredient costs.
China's SAMR enforces food safety audits and franchise disclosure rules that filter out undercapitalized entrants, while GB standards mandate commercial kitchen ventilation and fire suppression specifications. The country's dual carbon goals push local governments to tie retail permits to energy performance benchmarks. Franchise stakeholders must monitor how municipal implementation of national efficiency codes reshapes build-out costs and site selection criteria.
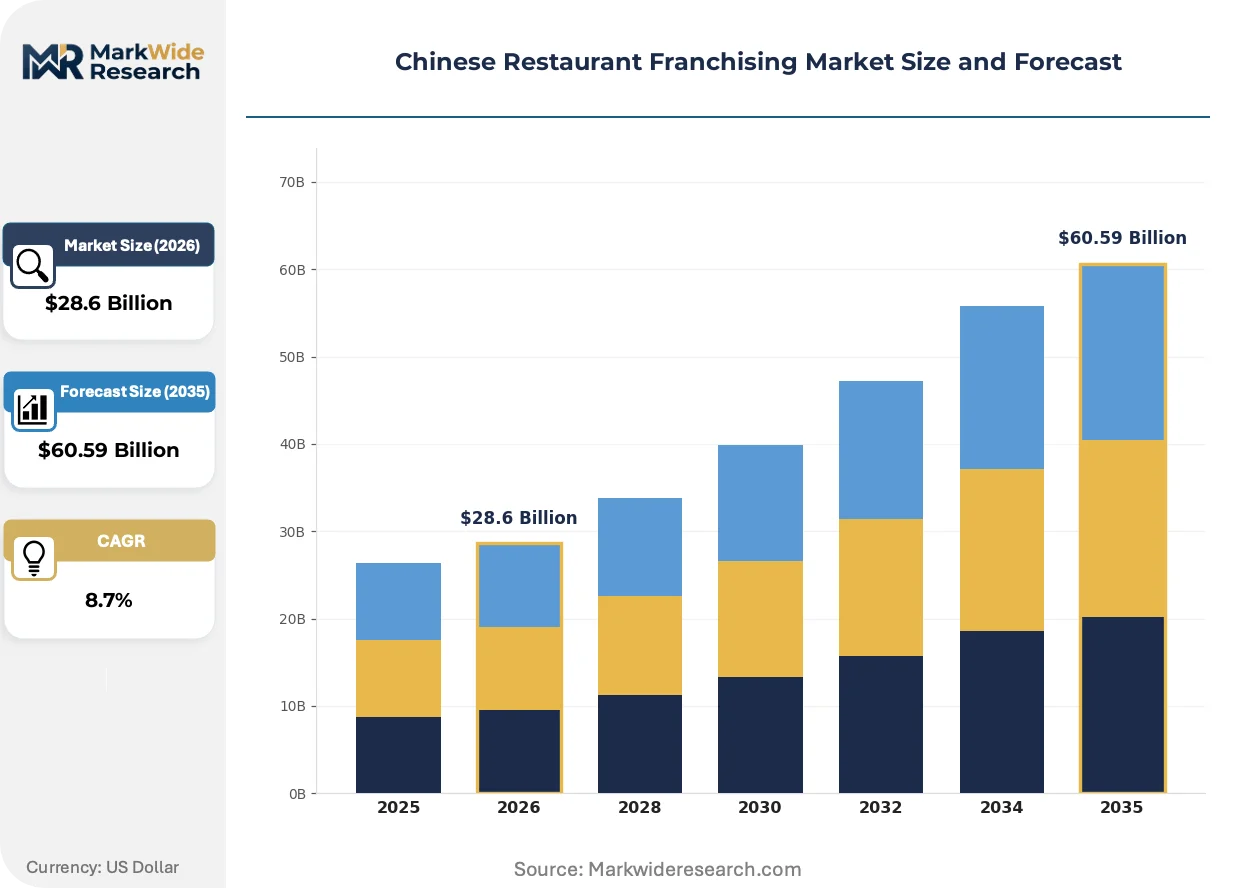
Market Dynamics
China's dual carbon goals are compressing franchise build-out timelines as municipal governments tie commercial retail permits to energy performance benchmarks. Provincial regulators now require renewable power sourcing and high-efficiency kitchen ventilation before issuing operating licenses.
Growth Catalysts
- Suburban retail development:Lower-tier cities in Henan and Sichuan provinces are approving mixed-use developments with dedicated food-service zones, reducing site acquisition friction for franchise operators.
- GB standards modernization:Updated national standards for commercial kitchen fire suppression and ventilation are streamlining permit approvals for compliant franchise formats.
- Younger consumer preference:Post-1995 cohorts in provincial capitals favor standardized, Instagram-friendly dining environments over traditional street food stalls.
Market Restraints
- Pork price volatility:Swine disease cycles and feed grain import costs create margin unpredictability for full-meal concepts dependent on protein-heavy menus.
- Central kitchen concentration:Franchise networks rely on single-commissary supply models that expose multi-unit operators to regional logistics disruptions.
- Real estate cost escalation:Tier-2 city commercial rents in prime retail corridors now consume 18-22% of unit revenue, compressing operator returns.
Strategic Opportunities
- Xinjiang and Tibet penetration:These underdeveloped autonomous regions show rising disposable incomes but minimal chain restaurant presence, offering first-mover positioning.
- Cloud kitchen integration:Delivery-optimized ghost kitchen formats reduce front-of-house capex while capturing off-premise demand growth.
- Dual carbon incentive programs:Municipal renewable energy rebates and green building certifications offset efficiency upgrade costs for early adopters.
Industry Challenges
- Line cook skill scarcity:Standardized wok techniques and sauce preparation protocols require training periods that exceed typical hourly worker retention cycles.
- Multi-brand franchisee complexity:Operators running both full-service and fast-casual concepts face conflicting supply chain and labor scheduling demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chinese Restaurant Franchising Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Franchise Model: Single-Unit Franchises, Multi-Unit Franchises, Area Development, Master Franchises Menu Type: Traditional Chinese, Fast Casual, Dim Sum, Vegan Options Market Positioning: Affordability, Premium Dining, Family Style, Fast Food Service Style: Dine-In, Takeout, Delivery, Catering |
| Companies Covered | Chagee, Panda Express, Mixue, Bonchon, Pei Wei, Luckin Coffee, Happy Lemon, Kura Sushi, Cotti Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chinese Restaurant Franchising Market Trends and Innovations
Digital ordering infrastructure and energy compliance systems are reconfiguring how franchise networks deploy capital and train workforces. Operational technology investments now precede location openings rather than following them.
Induction wok stations with precision temperature controls are overtaking traditional gas-fired equipment in new franchise builds. Quick-service chains in Chengdu and Wuhan are adopting these systems to meet municipal efficiency audits. The shift is overtaking conventional kitchen specifications and forcing equipment suppliers to retool their China product lines.
China's SAMR disclosure requirements now mandate 14-day franchise document review periods and audited food safety protocols before license issuance. The rules are filtering out undercapitalized entrants and elevating compliance costs for first-time franchisees. Multi-unit operators with existing SAMR relationships are accelerating expansion while single-store applicants face extended approval timelines.
Younger consumers are prioritizing tea-centric menu formats over full-meal concepts when selecting franchise destinations. Fast-casual tea houses in Changsha and Xi'an are capturing foot traffic that previously flowed to traditional Chinese restaurants. This behavioral pivot is visible most acutely in provincial capitals where disposable incomes support premium beverage pricing.
Chinese Restaurant Franchising Market Segmentation
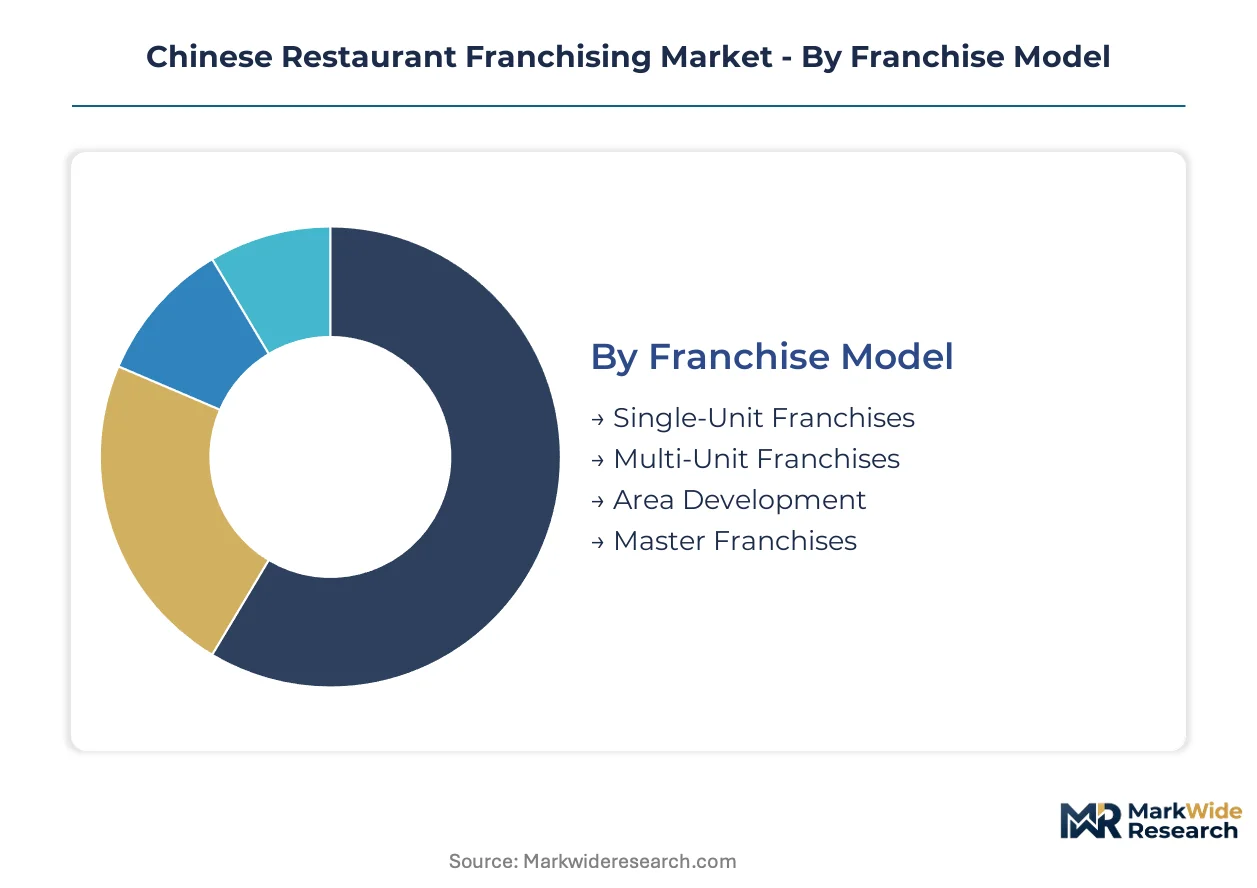
Franchise operators in China configure their expansion strategies around four distinct segmentation axes that determine capital intensity, regulatory exposure, and margin architecture. Each category reflects how supply chain concentration and consumer preference patterns allocate capital across the market.
Franchise Model:
Supply concentration in central kitchen infrastructure favors operators who can amortize fixed costs across multiple locations.
- Multi-Unit Franchises:Operators control three or more locations under unified management, leveraging centralized procurement and shared labor pools. Henan and Sichuan provinces see the densest concentration as developers prioritize proven operators for suburban retail allocations.
- Single-Unit Franchises:Independent operators run single locations with direct franchisor support. SAMR disclosure requirements and 14-day document review periods create compliance barriers that favor capitalized entrants in provincial capitals.
- Area Development:Franchisees secure exclusive territorial rights to open predetermined store counts within defined timelines. Lower-tier cities with rising disposable incomes attract these commitments as first-mover positioning becomes viable.
- Master Franchises:Sub-franchising rights for entire provinces or autonomous regions transfer to regional partners. Xinjiang and Tibet present untapped terrain where master franchise structures reduce direct operational complexity for national brands.
Multi-Unit Franchises absorb the bulk of installed capacity; Master Franchises are expanding most quickly.
Menu Type:
Margin architecture varies sharply across menu formats as ingredient cost structures and labor intensity diverge.
- Fast Casual:Streamlined service models with limited menus and counter ordering command higher throughput per square meter. Post-1995 cohorts in Changsha and Xi'an drive demand for standardized, Instagram-friendly environments over traditional stalls.
- Traditional Chinese:Full-meal concepts with wok-fired proteins and complex sauce preparations require skilled line cooks. Pork price volatility and rising feed grain import costs compress margins for operators dependent on protein-heavy offerings.
- Dim Sum:Steamed and fried small-plate formats with standardized prep protocols suit central kitchen production. Guangdong-origin concepts leverage this modularity for rapid provincial rollout.
- Vegan Options:Plant-forward menus address dual carbon compliance pressures while capturing health-conscious segments. Municipal green building certifications and renewable energy rebates offset equipment upgrade costs for early adopters.
Traditional Chinese retains the largest revenue pool; Fast Casual is climbing the fastest.
Market Positioning:
Price tier selection determines site selection criteria and build-out specifications under tightening efficiency mandates.
- Affordability:Rock-bottom unit economics with self-built distribution networks enable aggressive store density. Mixue's expansion model exemplifies how supply chain control sustains margin at price points below competitors.
- Fast Food:Quick-service formats with standardized kitchen layouts of 80-150 square meters dominate suburban retail developments. GB standards for ventilation and fire suppression streamline permit approvals for compliant builds.
- Family Style:Larger-format dining rooms with shared dishes and rotating lazy susan tables target multi-generational occasions. Tier-2 city commercial rents consuming 18-22% of unit revenue pressure returns in this space-intensive segment.
- Premium Dining:Elevated ingredients and service protocols command higher per-check averages with correspondingly longer payback periods. Tea-centric menu formats like Chagee demonstrate how beverage-forward positioning achieves premium margins without full-meal complexity.
Affordability absorbs the bulk of installed capacity; Premium Dining is gaining share fastest.
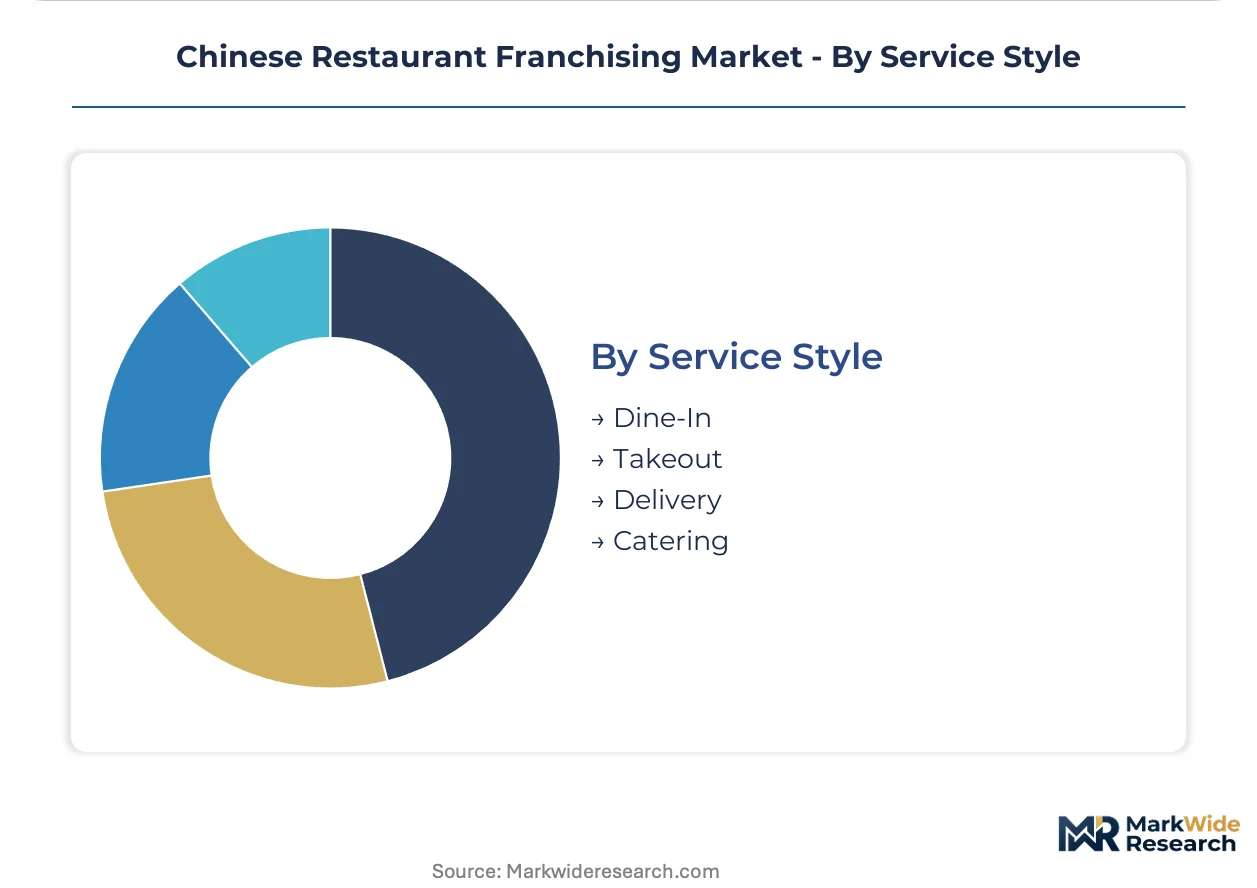
Service Style:
Channel mix decisions increasingly precede location selection as off-premise demand reshapes capital deployment.
- Delivery:Third-party platform integration and dedicated packaging protocols capture consumption outside physical locations. Cloud kitchen formats reduce front-of-house capex while maintaining brand presence in dense urban corridors.
- Takeout:Counter pickup with optimized packaging for transport quality suits high-traffic retail zones. Chengdu and Wuhan operators prioritize this channel for lunch-hour volume capture.
- Dine-In:Full-service experience with front-of-house labor and ambiance investments remains essential for occasion-driven visits. Energy-efficient induction wok stations now replace gas-fired equipment to meet municipal efficiency audits.
- Catering:Large-format production for corporate and event clients leverages existing central kitchen capacity. Seasonal demand spikes require flexible labor scheduling that conflicts with multi-brand franchisee operations.
Dine-In absorbs the bulk of installed capacity; Delivery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors franchise development activity through its Yangtze River Delta manufacturing corridor, where commercial kitchen equipment suppliers cluster to serve expanding quick-service networks. Provincial capitals and lower-tier cities now drive rollout velocity as suburban retail developers allocate dedicated food-service zones.
Guangdong Province
Dim sum concepts and tea-centric formats capture rising disposable incomes in Shenzhen and Guangzhou. SAMR enforces 14-day franchise disclosure review periods before license issuance. The Pearl River Delta hosts the densest concentration of central kitchen infrastructure serving multi-unit operators.
Sichuan Province
Spicy regional cuisine formats attract younger consumers seeking standardized dining environments. GB standards for commercial kitchen ventilation streamline permit approvals for compliant builds. Chengdu operators adopt induction wok stations to meet municipal efficiency audits.
Henan Province
Affordability-focused chains achieve aggressive store density through self-built distribution networks. Local governments tie retail permits to renewable power sourcing requirements. Zhengzhou suburban developments prioritize proven multi-unit franchisees for food-service zone allocations.
Zhejiang Province
Fast-casual concepts command premium positioning in Hangzhou's high-traffic retail corridors. Dual carbon incentive programs offset energy-efficient equipment upgrade costs. The Ningbo port cluster facilitates imported ingredient supply chains for full-meal concepts.
Xinjiang Autonomous Region
Minimal chain restaurant presence creates first-mover opportunities for master franchise structures. Municipal renewable energy rebates attract early adopters of green building certifications. Urumqi's rising disposable incomes support premium beverage-forward formats.
Chinese Restaurant Franchising Market Competitive Landscape
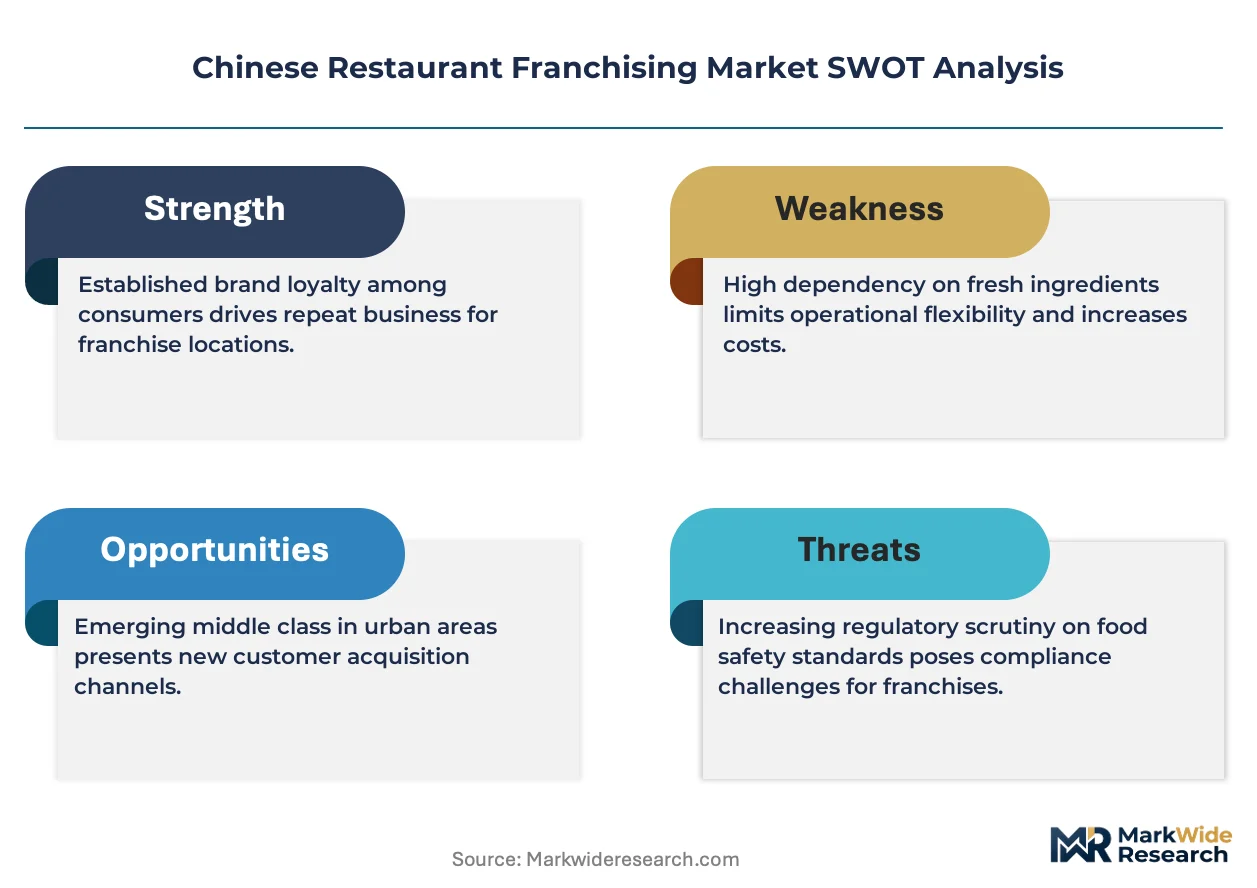
Premium-margin players sit above commodity-margin players across menu complexity and build-out efficiency dimensions. The vendor base organizes into three tiers: beverage-specialized chains with tea-centric positioning, full-meal operators with protein-heavy menus, and hybrid formats blending quick-service speed with fast-casual ambiance. Strategic moves concentrate on central kitchen consolidation and suburban retail site pre-commitments.
Among China-based operators, Chagee exemplifies premium-tier beverage specialization, Mixue anchors the affordability-driven mass-market segment, and Panda Express represents standardized full-meal expansion. These three occupy distinct competitive positions without direct overlap, each targeting separate consumer occasions and price thresholds. Chagee commands higher margins through simplified operations, Mixue sustains density through rock-bottom unit economics, and Panda Express leverages supply chain standardization for provincial capital penetration.
| Leading Market Players |
|---|
| Chagee |
| Panda Express |
| Mixue |
| Bonchon |
| Pei Wei |
| Luckin Coffee |
| Happy Lemon |
| Kura Sushi |
| Cotti Coffee |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate both qualified equipment supply and premium-tier pricing access, as municipal renewable power mandates and GB ventilation standards filter out non-compliant suppliers while elevating build-out costs for franchise operators seeking prime suburban retail allocations.
Pricing Analysis
Throughput-based pricing anchors franchise economics, with operators amortizing fixed central kitchen costs across unit volume to achieve viable returns. Three-tier pricing structure across premium, standard, and economy levels separates tea-centric beverage formats from full-meal wok concepts and rock-bottom soft-serve chains. Pricing pressure stems from real estate cost escalation in Tier-2 city corridors, where rents now consume disproportionate revenue shares. Multi-unit franchisees with proven SAMR track records exhibit lowest price sensitivity, while single-unit entrants face acute margin compression from compliance overhead.
Supply Chain Analysis
Dual-sourcing requirements for commercial kitchen equipment intensify as municipal efficiency audits mandate backup supplier qualification for induction wok stations and ventilation systems. Manufacturing concentrates in China's Yangtze River Delta corridor, with component sourcing from South Korea and Japan for precision temperature controls. Raw material dependencies span stainless steel for kitchen fabrication, rare earth elements for induction electronics, and imported feed grains for protein supply chains. Single-commissary concentration creates regional logistics vulnerability. Distribution runs through self-built networks for affordability chains and third-party cold-chain partners for premium formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, where SAMR's 14-day franchise disclosure review periods and audited food safety protocols create a barrier-to-entry moat that rewards capitalized incumbents while filtering undercapitalized applicants.
For Market Incumbents: Acquire suburban retail site pre-commitments in lower-tier cities before municipal energy performance benchmarks tighten further. Consolidate central kitchen capacity across provincial clusters to amortize fixed costs against logistics disruption risks. Defensive positioning requires locking in multi-year equipment supplier contracts before GB ventilation standard updates trigger price resets.
For New Entrants and Emerging Players: Cloud kitchen technology offers a capital-light wedge, reducing front-of-house capex while capturing delivery-optimized demand in dense urban corridors. Target Xinjiang and Tibet autonomous regions where master franchise structures reduce direct operational complexity and rising disposable incomes support premium beverage-forward formats. Go-to-market execution should prioritize tea-centric menu positioning over protein-heavy full-meal complexity.
For Investors and Strategic Acquirers: SAMR license issuance acceleration for existing multi-unit operators is the leading indicator that consolidation momentum is building. Long-term viability favors vertically integrated chains with captive supply networks and proven provincial expansion playbooks. Watch for municipal renewable energy rebate program expansions as the signal that green-certified build-outs are shifting from cost center to competitive advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Consolidation | Multi-unit operators amortize fixed costs across locations while reducing logistics exposure. |
| Suburban Retail Site Pre-Commitment | Developers in Henan and Sichuan prioritize proven franchisees for food-service zone allocations. |
| Induction Equipment Upgrade | Municipal efficiency audits in Chengdu and Wuhan reward early adopters with permit priority. |
| Master Franchise Structure Deployment | Xinjiang and Tibet penetration reduces direct operational complexity for national brands. |
| Cloud Kitchen Format Expansion | Delivery-optimized builds capture off-premise growth without front-of-house capex burden. |
Research Methodology
Franchise disclosure filings, municipal retail permit databases, and commercial kitchen equipment trade data formed the secondary backbone, cross-referenced with primary interviews spanning franchise development officers, suburban retail developers, SAMR compliance consultants, and central kitchen operations directors. Bottom-up location rollouts and top-down provincial market sizing were triangulated against equipment shipment records and energy audit filings.
Historical trendline analysis tracked outlet expansion velocity and permit approval timelines across the projection horizon. Segmentation dimensions modeled include franchise model type, menu format complexity, market positioning tier, and service style channel mix. CAGRs were derived from unit economics sensitivity testing against variable cost inputs including pork price cycles, commercial rent trajectories, and renewable energy rebate program participation rates.
Several conditions sit outside the modeled scope, including abrupt swine disease outbreaks, municipal permit moratoriums, and franchisor-franchisee litigation waves. Forecasts reflect assumptions around SAMR enforcement consistency and dual carbon goal implementation pacing. Deviation in provincial renewable energy rebate availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
US Catering Services Market