
 Global Offshore Catering Services Market | 2026-2036
Global Offshore Catering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Offshore Catering Services Market Outlook
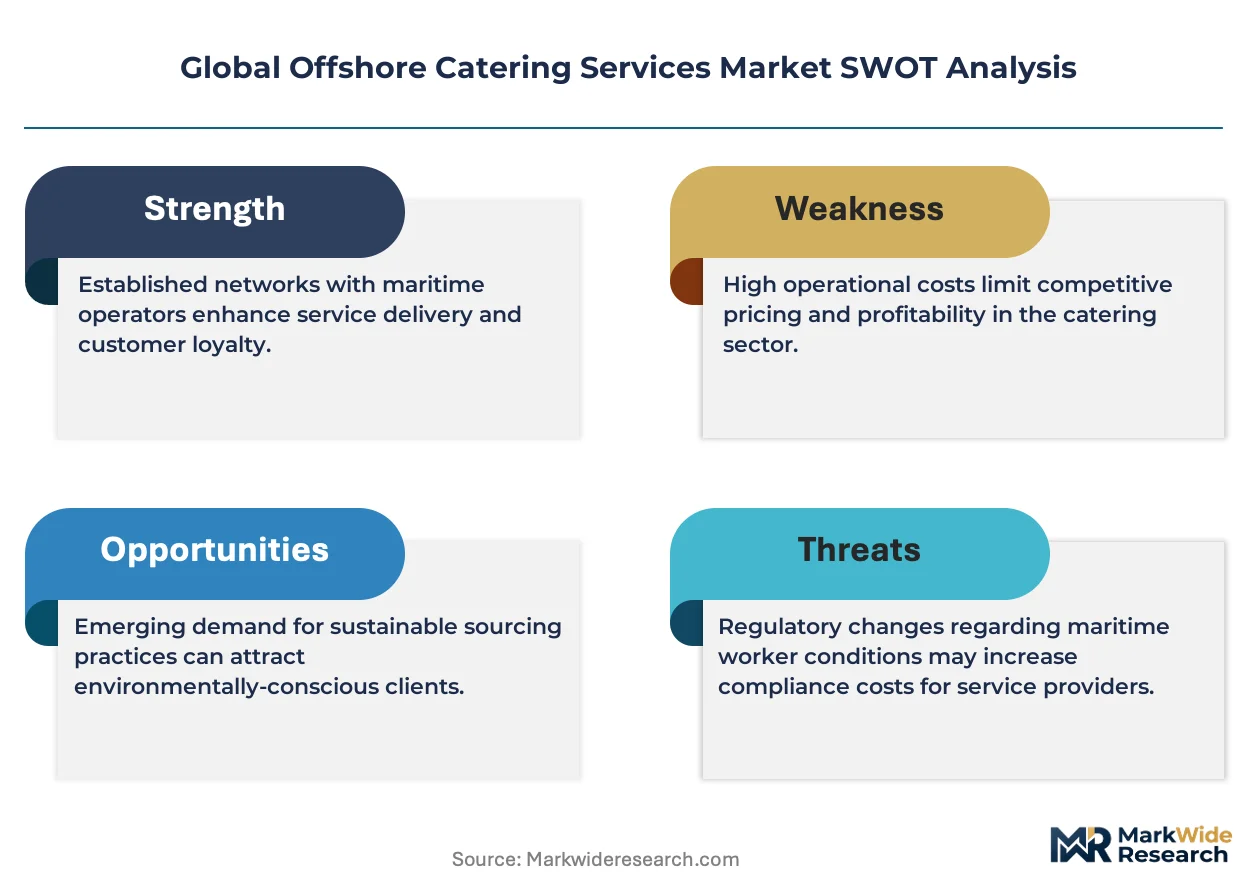
The EU Green Deal is repositioning vendor selection criteria across North Sea offshore catering contracts, forcing operators to verify carbon footprints in their food supply chains. Compass Group leverages integrated procurement platforms to secure multi-year platform contracts. Sodexo anchors its competitive stance through specialized nutrition programs designed for extended-shift offshore workers. Aramark differentiates by controlling cold-chain logistics across remote maritime zones.
Offshore catering services encompass the provision of prepared meals, beverage programs, accommodation management, and supply chain coordination for workers stationed on oil platforms, drilling rigs, marine vessels, and remote construction installations, typically operating under strict HACCP protocols and calorie-density specifications for high-exertion labor environments. Catering services and mess facility management represent the mature revenue core where contract renewals concentrate, while remote catering and mobile kitchen deployments are expanding fastest as marginal field developments multiply. Oil and gas companies dominate procurement volume, though marine operators and research institutions are diversifying the buyer base.
FDA maritime food safety guidelines, ECHA chemical traceability requirements under REACH, and Norway's Petroleum Safety Authority welfare regulations collectively shape operational compliance burdens and vendor certification thresholds. ISO 22000 and HACCP frameworks function as baseline market access credentials rather than competitive differentiators. Stakeholders must monitor how emerging offshore wind installation demand reshapes crew rotation patterns and catering procurement specifications.
Market Dynamics
Deepwater operators are extending crew rotations beyond traditional 14-day cycles, forcing catering contractors to redesign cold-chain logistics and calorie-density protocols for sustained high-exertion labor environments.
Growth Catalysts
- EU Green Deal procurement mandates:North Sea operators now require verified carbon footprint documentation across food supply chains, disqualifying vendors lacking traceability systems.
- Norway's offshore cluster expansion:Concentrated platform development around Stavanger and Bergen is generating bundled catering contracts spanning multiple installations.
- Extended-shift nutrition science:Specialized high-protein, low-glycemic meal programs are becoming standard specifications for 28-day rotation contracts.
Market Restraints
- Arctic logistics cost volatility:Fuel price swings and ice-class vessel availability constrain Barents Sea supply chain reliability.
- ECHA REACH chemical traceability:Cleaning agents and food-contact materials face expanded documentation burdens, extending vendor onboarding timelines.
- Platform catering duopoly:Two integrated procurement platforms control contract access for major North Sea operators, limiting new entrant pathways.
Strategic Opportunities
- Offshore wind installation catering:Floating turbine construction crews require mobile kitchen deployments with shorter setup cycles than oil platform contracts.
- ISO 22000 certification arbitrage:Mid-tier vendors achieving this baseline credential can access contracts previously reserved for integrated service providers.
- Brazil pre-salt field development:ANVISA maritime food safety protocols are creating demand for vendors with dual HACCP-ISO compliance capabilities.
Industry Challenges
- Maritime cold-chain engineer scarcity:Qualified technicians for remote refrigeration maintenance command premium wages, compressing contractor margins.
- HACCP audit timeline compression:Norway's Petroleum Safety Authority has shortened recertification windows, forcing more frequent third-party inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Offshore Catering Services Market |
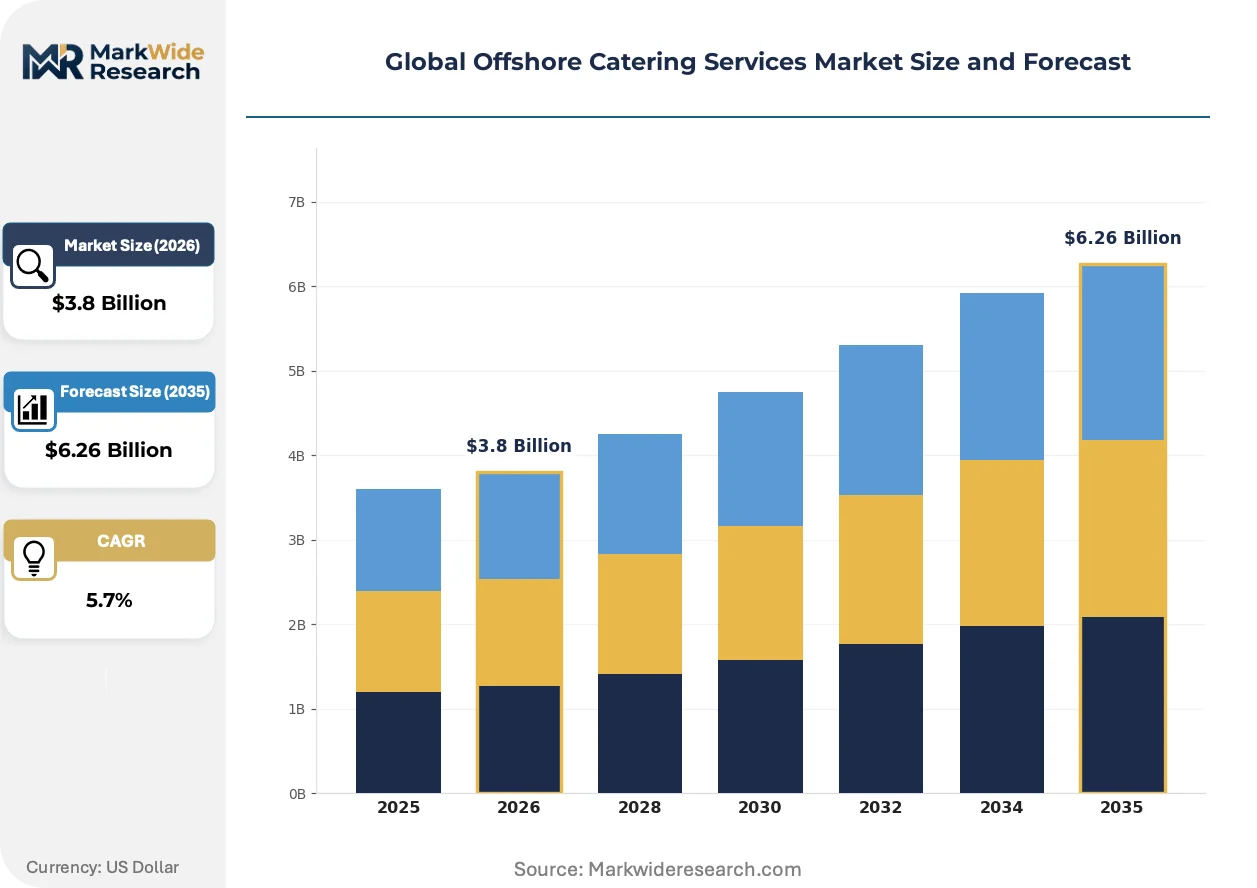
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Catering Services, Mess Facility Management, Food Supply Chain, Accommodation Services End User: Oil & Gas Companies, Marine Operators, Construction Firms, Research Institutions Delivery Model: Onboard Catering, Remote Catering, Mobile Catering, Centralized Kitchen Delivery Package Type: Beverage Packs, Meal Boxes, Disposable Kits, Gourmet Packages |
| Companies Covered | Compass Group, Sodexo, Aramark, Oceanwide Catering Limited, FOSS & ESG, Tsebo Solutions Group, Northern Marine Group, Al.Ma.Alimentari Marittimi, Global Offshore Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Offshore Catering Services Market Strategic Shifts
Automation and sustainability verification are restructuring how offshore catering contracts are awarded, with procurement teams prioritizing vendors that can document supply chain impact in real time.
Blockchain-enabled provenance tracking is rewriting vendor qualification protocols. Major North Sea operators now require immutable records from farm to platform mess hall. Contractors adopting distributed ledger systems are securing multi-year framework agreements while legacy paper-based traceability systems face exclusion from tender shortlists.
EU Green Deal sustainability mandates are reshuffling supplier eligibility across North Sea operations. Food miles documentation and packaging waste reduction targets now carry contractual weight. Norwegian operators are responding by consolidating procurement around vendors with integrated carbon accounting platforms, compressing the qualified supplier pool.
Buyer concentration around integrated facilities management contracts is displacing standalone catering agreements. Oil majors are bundling mess services with accommodation and logistics under single-source arrangements. This pattern is most visible in Norway's Stavanger-Bergen corridor, where platform operators seek administrative simplification through consolidated vendor relationships.
Global Offshore Catering Services Market Segmentation
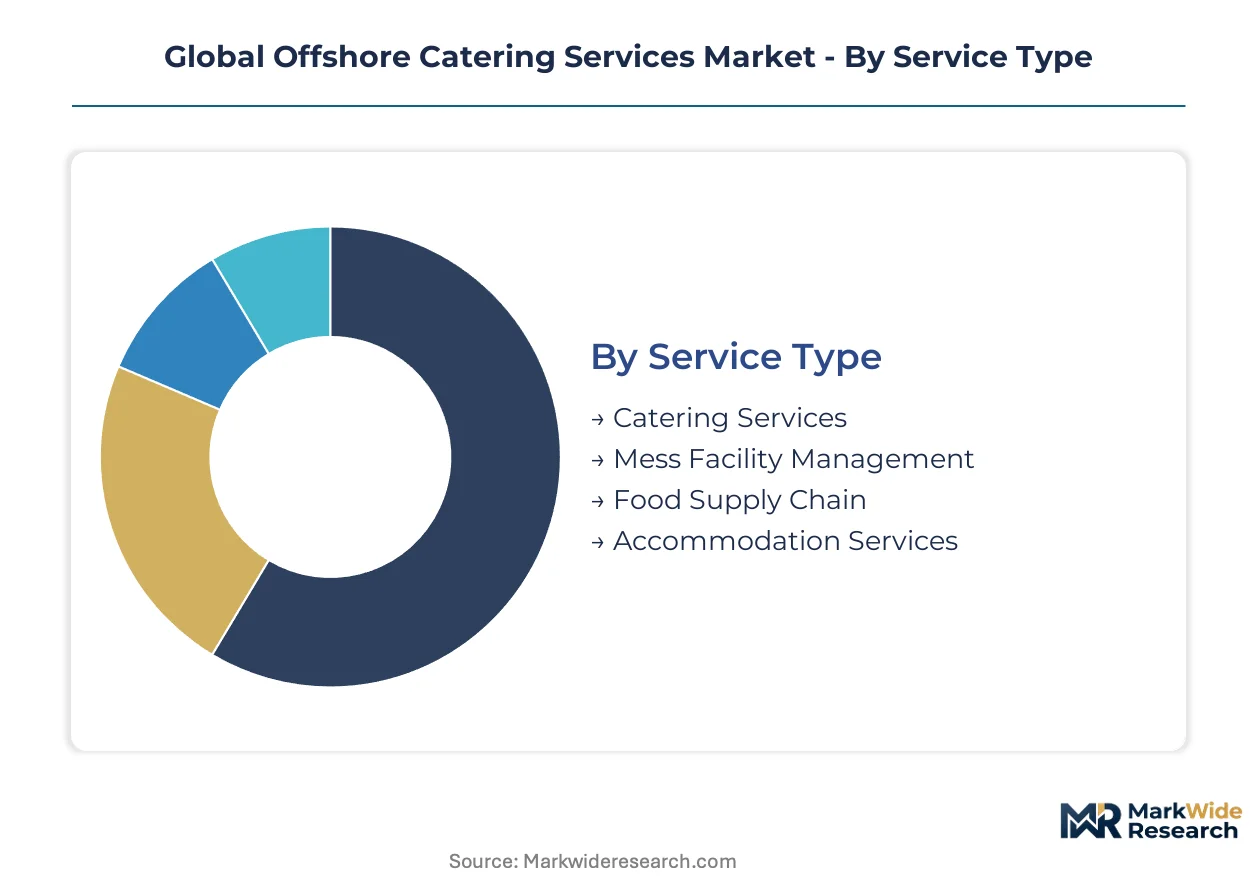
Offshore catering procurement specifications diverge sharply across service configurations, with contract structures and margin profiles varying by operational intensity and regulatory exposure. Understanding segment boundaries clarifies where vendor capabilities align with buyer requirements.
Service Type:
Technology intensity and labor specialization define competitive positioning across service categories, with cold-chain infrastructure investments separating integrated operators from commodity providers.
- Catering Services:Prepared meal production and mess hall operations under strict HACCP protocols, with calorie-density specifications for high-exertion labor. Demand concentrates in Norway's Stavanger-Bergen corridor where bundled platform contracts require 28-day rotation nutrition science.
- Mess Facility Management:Comprehensive dining infrastructure oversight including equipment maintenance, sanitation compliance, and staff supervision. Deepwater operators in Brazil's pre-salt fields are extending contract terms as rotation cycles lengthen beyond traditional 14-day windows.
- Food Supply Chain:Procurement coordination from shore-based distribution centers to offshore platforms, encompassing inventory management and waste reduction protocols. EU Green Deal carbon footprint documentation mandates are reshaping vendor qualifications across North Sea operations.
- Accommodation Services:Integrated lodging and welfare facility management alongside catering functions. Oil majors are consolidating these services under single-source arrangements to simplify administrative overhead.
Mature deployment sits with Catering Services. Newer deployment is concentrated in Accommodation Services as integrated facilities management contracts displace standalone agreements.
End User:
Procurement sophistication and contract scale vary by buyer category, with regulatory compliance burdens and rotation complexity driving vendor selection criteria.
- Oil & Gas Companies:Dominant procurement volume with multi-year framework agreements spanning multiple installations. Norway's Petroleum Safety Authority welfare regulations enforce strict welfare standards that filter vendor pools.
- Marine Operators:Specialized vessel-based catering with shorter setup cycles and mobility requirements. Demand is expanding in offshore wind installation corridors where floating turbine construction crews require rapid kitchen deployment.
- Construction Firms:Project-based contracts tied to specific infrastructure development timelines. Remote construction installations in marginal field developments are driving mobile catering specifications.
- Research Institutions:Smaller-scale contracts with specialized dietary requirements and extended expedition durations. Arctic logistics cost volatility constrains supply chain reliability for polar research stations.
Contract concentration remains heaviest with Oil & Gas Companies. Fastest volume expansion is occurring among Marine Operators as offshore wind installation activity accelerates.
Delivery Model:
Physical infrastructure requirements and setup velocity determine margin structures, with mobility investments commanding premium pricing against fixed installations.
- Onboard Catering:Permanent kitchen facilities integrated into platform or vessel architecture with dedicated cold-chain systems. Established installations in the North Sea and Gulf of Mexico represent the revenue baseline.
- Remote Catering:Shore-based preparation with helicopter or vessel transfer to offshore locations, requiring precise timing and temperature control. Barents Sea operations face fuel price volatility and ice-class vessel availability constraints.
- Mobile Catering:Containerized or modular kitchen units deployed to temporary installations with rapid assembly requirements. Offshore wind construction crews are driving specifications for shorter setup cycles than traditional oil platform contracts.
- Centralized Kitchen Delivery:Hub-and-spoke distribution from large-scale shore facilities to multiple offshore locations. Blockchain-enabled provenance tracking is becoming mandatory for vendors serving major North Sea operators.
Revenue stability anchors in Onboard Catering. Steepest expansion trajectory belongs to Mobile Catering as marginal field developments multiply.
Package Type:
Product format selection reflects labor intensity constraints and consumption occasion requirements, with premium differentiation emerging in extended-rotation contexts.
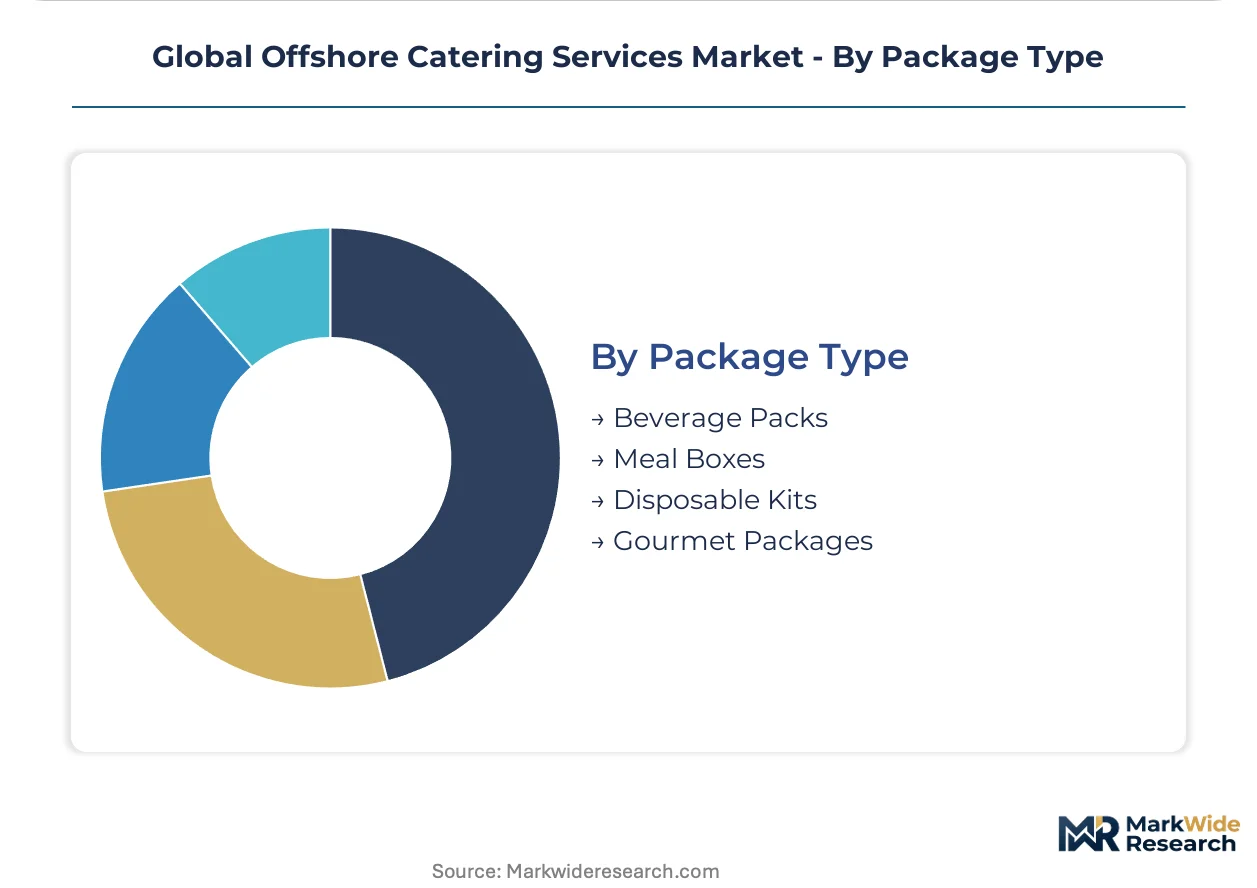
- Beverage Packs:Hydration programs including hot drink stations, cold beverage distribution, and specialized electrolyte replacement for high-exertion environments. Calorie-density specifications increasingly incorporate beverage macros into total nutrition planning.
- Meal Boxes:Pre-portioned individual meals optimized for helicopter transport and extended shelf stability. EU Green Deal packaging waste reduction targets are reshaping material specifications across North Sea contracts.
- Disposable Kits:Single-use utensil and container assemblies for mess hall operations with simplified sanitation requirements. ECHA REACH chemical traceability mandates extend documentation burdens to food-contact materials.
- Gourmet Packages:Elevated culinary offerings for senior personnel and client entertainment functions on major installations. Extended-shift contracts are incorporating morale and retention considerations into procurement specifications.
Volume concentration remains with Meal Boxes. Premium positioning is climbing fastest in Gourmet Packages as rotation extension intensifies crew welfare investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore catering production concentrates in Norway and the United Kingdom where North Sea platform density sustains integrated service providers, while consumption spreads across Brazil's pre-salt developments and emerging Asia-Pacific wind installation corridors.
Norway
Stavanger and Bergen anchor the densest offshore catering procurement cluster globally, with bundled platform contracts demanding 28-day rotation nutrition science. The country's Petroleum Safety Authority enforces strict welfare regulations that filter vendor pools through shortened HACCP recertification windows. Deepwater operators around these cities are consolidating procurement under single-source arrangements to simplify administrative overhead.
United Kingdom
Aberdeen and the broader Scottish North Sea basin generate substantial demand for cold-chain logistics specialists capable of extended-shift meal programs. EU Green Deal carbon footprint documentation mandates are reshuffling supplier qualifications, with blockchain-enabled provenance tracking becoming mandatory for major operator frameworks. The region's platform catering duopoly limits new entrant pathways through integrated procurement platforms.
Brazil
Pre-salt field developments off Rio de Janeiro and São Paulo states are extending crew rotation cycles beyond traditional 14-day windows, forcing calorie-density protocol redesigns. ANVISA maritime food safety protocols create demand for vendors with dual HACCP-ISO compliance capabilities. State-controlled Petrobras procurement is bundling catering with logistics under multi-year framework agreements.
United States
Gulf of Mexico deepwater installations sustain mature onboard catering infrastructure, with Louisiana and Texas coastal hubs supporting helicopter supply chains to platform complexes. FDA maritime food safety guidelines establish baseline operational protocols, though extended-shift nutrition science adoption lags North Sea standards. Shallow-water decommissioning is shifting procurement toward mobile catering for plug-and-abandon campaigns.
China
South China Sea drilling expansion and emerging offshore wind installation activity off Guangdong and Fujian provinces are diversifying buyer profiles beyond traditional oil and gas. The country's national maritime safety administration maintains food safety protocols for vessel-based operations. State-owned CNOOC procurement patterns favor integrated facilities management contracts over standalone catering agreements.
Global Offshore Catering Services Market Competitive Environment
The competitive structure tilts toward integrated facilities management specialists with cold-chain infrastructure investments. Two procurement platforms control contract access for major North Sea operators, compressing the qualified supplier pool. Strategic archetypes include nutrition science specialists, logistics-integrated providers, and mobile deployment contractors. Dominant competitive moves center on carbon accounting platform integration and multi-year framework agreement consolidation.
Among UK and European headquartered service providers, Compass Group and Sodexo occupy positions within the integrated procurement tier, while Aramark exemplifies the cold-chain logistics specialist archetype. These entities represent the consolidation pattern where bundled accommodation and catering contracts displace standalone agreements. Mid-tier vendors achieving ISO 22000 certification are accessing contracts previously reserved for integrated service providers, creating segmentation pressure at the qualification threshold.
| Leading Market Players |
|---|
| Compass Group |
| Sodexo |
| Aramark |
| Oceanwide Catering Limited |
| FOSS & ESG |
| Tsebo Solutions Group |
| Northern Marine Group |
| Al.Ma.Alimentari Marittimi |
| Global Offshore Logistics |
| Others |
Value Chain & Pricing Dynamics
Oil and gas procurement officers in Norway and the United Kingdom concentrate contract volume through integrated facilities management platforms, compressing vendor margins and forcing three-tier pricing stratification across premium, standard, and economy service levels.
Pricing Analysis
Margin tightening in standard-tier catering reflects buyer consolidation around multi-year framework agreements and the duopoly control exercised by two integrated procurement platforms. Pricing stratifies across premium nutrition-science contracts, standard HACCP-compliant services, and economy mobile deployments, with differentiation driven by certification grade and cold-chain infrastructure depth. Cost-down pressure on economy-tier vendors accelerates because Arctic logistics volatility and fuel price swings compress already-thin margins. Marine operators in offshore wind corridors exhibit highest price sensitivity due to shorter project durations, while deepwater oil majors in Brazil's pre-salt fields demonstrate lowest sensitivity given welfare retention priorities.
Supply Chain Analysis
Dual-sourcing requirements from Norway's Petroleum Safety Authority and major North Sea operators mandate qualified backup vendors for critical cold-chain components, preventing single-source dependencies. Supply concentration rests on Norway, the United Kingdom, and Brazil as primary hubs, with shore-based distribution centers in Stavanger, Aberdeen, and Rio de Janeiro feeding offshore installations. Raw material dependencies center on protein commodities, specialized cold-chain equipment, and cleaning agents subject to ECHA REACH documentation. Single-source vulnerability concentrates in qualified maritime refrigeration engineers commanding premium wages. Distribution runs through helicopter and ice-class vessel networks to platform complexes and floating turbine construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore catering is becoming a vertical-integration race where control over cold-chain logistics and carbon-accounting platforms determines contract access, with upstream certification investments and downstream procurement platform relationships as the decisive levers.
For Market Incumbents: Anchor market position by deepening backward integration into shore-based cold-chain infrastructure and securing exclusive relationships with the two dominant North Sea procurement platforms. Invest in blockchain-enabled provenance tracking to meet EU Green Deal mandates before recertification windows tighten further. Counter emerging ISO 22000-certified mid-tier vendors by bundling accommodation and catering under single-source arrangements that new entrants cannot replicate. For New Entrants and Emerging Players: The price-point gap between premium nutrition-science contracts and economy mobile deployments offers viable entry corridors for specialized players. Target offshore wind installation catering in Asia-Pacific corridors where setup-cycle requirements differ from established oil platform specifications. Pursue ANVISA dual-compliance certification to access Brazil's pre-salt field expansion where incumbent presence remains thinner. For Investors and Strategic Acquirers: The window for entry favors cold-chain logistics specialists with existing maritime refrigeration capabilities and carbon-accounting platform assets. Mid-tier vendors achieving ISO 22000 certification represent prime acquisition targets as they gain access to contracts previously reserved for integrated providers. Watch for inflection in offshore wind procurement volume as floating turbine construction accelerates and reshapes crew rotation patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Platform Integration | EU Green Deal mandates now require verified supply chain documentation for North Sea contract eligibility. |
| Cold-Chain Infrastructure Expansion | Extended 28-day rotations in Norway and Brazil demand enhanced refrigeration capacity and technician training. |
| ISO 22000 Certification Investment | Baseline credential unlocks contracts previously reserved for integrated facilities management providers. |
| Blockchain Provenance Tracking Deployment | Immutable farm-to-platform records are becoming mandatory for major operator framework agreements. |
| Mobile Kitchen Rapid Deployment Capability | Offshore wind construction crews require shorter setup cycles than traditional oil platform contracts. |
Study Parameters
Independent corroboration across catering operations executives, offshore platform managers, and marine procurement officers underwrites the qualitative findings, validated against Norway Petroleum Safety Authority welfare guidelines, ANVISA maritime protocols, and EU Green Deal procurement mandates. Bottom-up contract analysis across Stavanger-Bergen corridor installations triangulates with top-down market sizing from trade data and operator expenditure disclosures.
Rate-of-change decomposition across the projection horizon segments volume and value by service type, end-user category, and delivery model, with additional granularity on rotation-duration nutrition specifications. CAGRs derive from historical contract renewal patterns and announced field development timelines, incorporating offshore wind installation forecasts and pre-salt field expansion schedules as industry-specific demand drivers.
Underlying measurement precision varies by segment; established onboard catering in the North Sea carries tighter precision than emerging mobile deployments in Asia-Pacific wind corridors. Forecasts reflect assumptions about regulatory enforcement continuity, fuel price stability, and ice-class vessel availability. Deviation in EU Green Deal implementation timelines or Arctic logistics cost spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
France HRI Market