
 Catering Services Market | 2026-2036
Catering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Catering Services Market Analysis
Chef and hospitality labor shortages across North America and Western Europe is redrawing competitive dynamics in contract catering. Compass Group PLC leverages centralized procurement networks to sustain margin stability across fragmented regional markets. Sodexo S.A. anchors its position through technology-led workforce management platforms that reduce kitchen labor dependency. Aramark Corporation specializes in sports and entertainment venues, dominating concession and premium hospitality at major stadium complexes.
Catering services encompass the commercial preparation, delivery, and on-site service of food and beverage for events, institutions, and corporate clients, typically operating from centralized commissary kitchens with cold-chain logistics maintaining temperatures below 5°C for ready-to-serve items. The primary purpose is to replace in-house food operations with scalable, compliant meal programs for organizations lacking culinary infrastructure. Corporate events within the Event Type dimension lead contract value due to recurring procurement cycles and multi-year service agreements, while the Vegan cuisine category is expanding fastest as plant-based menu mandates penetrate educational and corporate accounts. Buffet service retains volume dominance in institutional settings where throughput efficiency outweighs customization needs.
FDA Food Code updates and HACCP compliance requirements shape operational standards for all US-based catering operators, while EU hygiene regulations under EFSA and national food safety authorities enforce cross-border service protocols for European contract caterers. OSHA workplace safety standards and local health department inspection regimes further constrain kitchen design and staffing models. Stakeholders must monitor labor automation thresholds and allergen-labeling enforcement as the primary variables determining facility investment priorities and contract profitability.
Market Dynamics
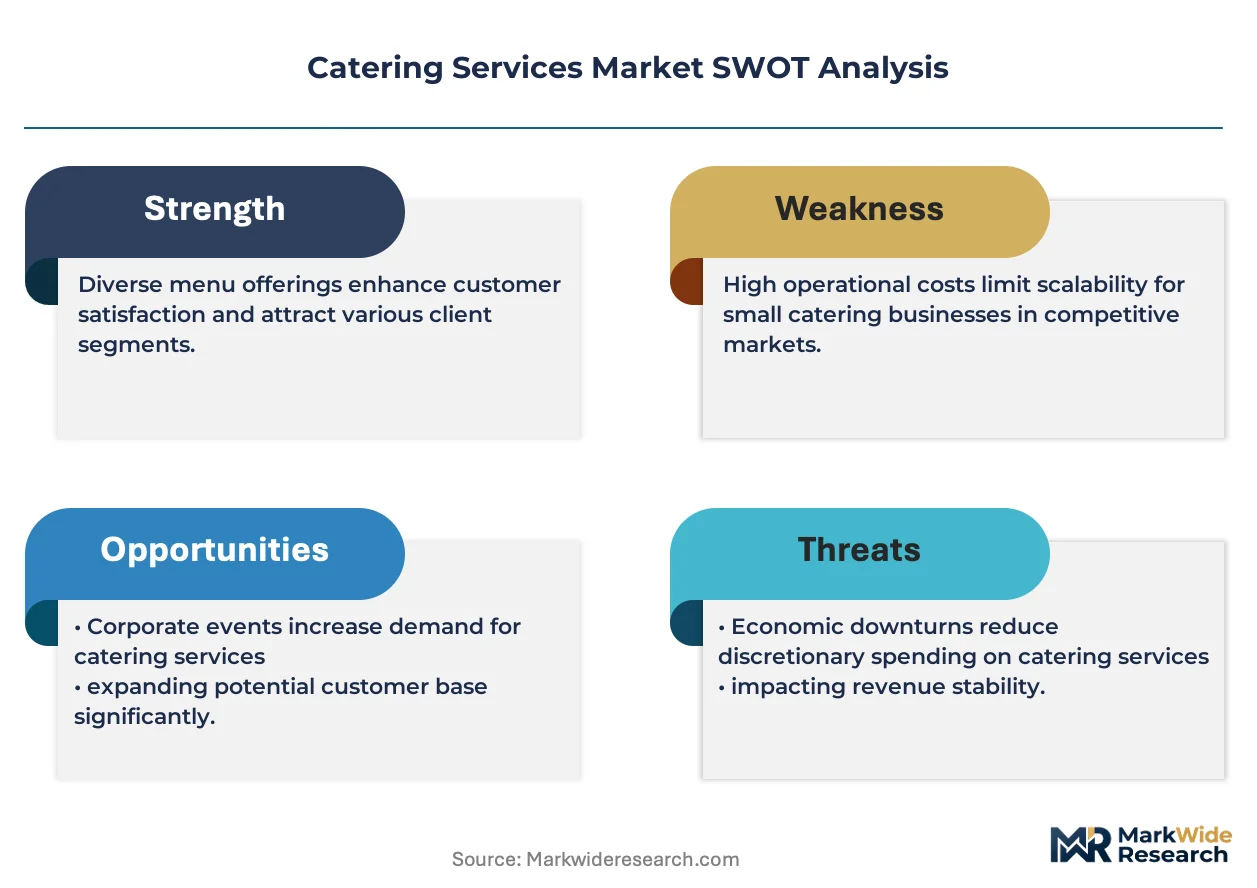
Hybrid work stabilization is compressing corporate dining contract renewal cycles while HACCP digitization mandates force kitchen infrastructure upgrades across institutional operators.
Growth Catalysts
- FDA Food Code modernization:Digitized temperature monitoring and automated compliance logging reduce inspection failure rates for contract caterers operating across state lines.
- Sports-venue premium hospitality:Stadium complexes and arena operators outsource entire food operations to capture concession revenue without capital-intensive kitchen builds.
- Plant-based protein processing:Advanced extrusion and fermentation technologies enable scalable vegan menu deployment for educational and healthcare accounts.
Market Restraints
- Protein input cost volatility:Beef and poultry price swings compress margin predictability for operators locked into fixed-price corporate contracts.
- Commissary kitchen concentration:Cold-chain logistics hubs cluster around major metropolitan corridors, creating service radius limitations for rural institutional clients.
- Substitution by ghost kitchens:Virtual restaurant operators capture event catering demand through direct-to-venue delivery models bypassing traditional contract structures.
Strategic Opportunities
- Underpenetrated K-12 districts:Rural and suburban school systems in the United States remain underserved by national contract caterers due to route density economics.
- EU Green Deal procurement mandates:Public sector foodservice contracts now require carbon footprint disclosure, favoring operators with verified supply chain transparency.
- AI-driven demand forecasting:Machine learning platforms converging with IoT inventory sensors reduce food waste and labor scheduling inefficiencies in high-volume institutional settings.
Industry Challenges
- Certified chef scarcity:Escalating wages for credentialed kitchen managers strain labor cost models in markets with unionized hospitality workforces.
- Legacy POS integration:Enterprise resource planning systems at major corporate clients resist API connectivity with modern catering management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catering Services Market |
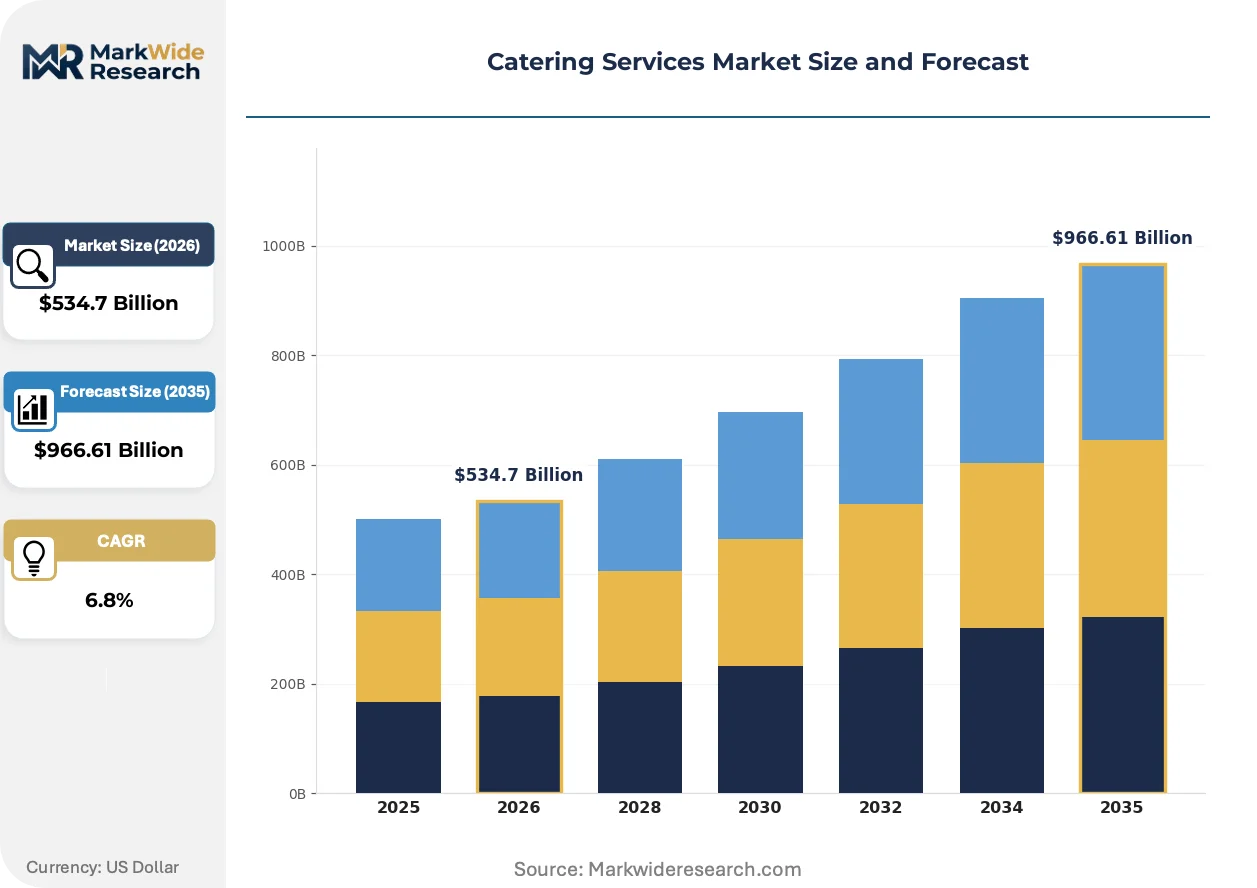
| Market Size in 2026 | $534.7 Billion |
| Market Size in 2035 | $966.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Buffet, Plated, Family Style, Hors D'oeuvres Event Type: Corporate Events, Weddings, Private Parties, Festivals Customer Segment: Individuals, Corporates, Non-profits, Educational Institutions Cuisine Type: Italian, Asian, Mexican, Vegan |
| Companies Covered | ISS A/S, Mitie Group PLC, Compass Group PLC, DO & CO Aktiengesellschaft, Hutten Catering BV, Sodexo S.A., AVI Foodsystems, Inc., Elior Group, Aramark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catering Services Market Emerging Trajectories
Automation and compliance technology are compressing operational models while procurement patterns favor vendors with transparent supply chain data.
Automated cooking equipment is displacing traditional line-cook staffing models in high-volume institutional kitchens. University dining services and healthcare systems deploy robotic fry stations and automated tray assembly lines to reduce headcount dependency. This equipment is displacing entry-level culinary positions while shifting operator investment toward maintenance technicians and software specialists.
EU hygiene regulations under EFSA now mandate digital traceability for allergen management across cross-border catering operations. Commercial kitchen operators must implement centralized ingredient databases accessible to health inspectors in real time. Multi-national contract caterers serving corporate campuses across Germany, France, and the Netherlands face the steepest compliance retrofit costs.
Corporate procurement departments now require third-party sustainability certification for all foodservice vendors. Educational institutions and healthcare systems prioritize suppliers with ISO 14001 environmental management credentials over uncertified competitors. This certification-driven preference shift concentrates contract awards among operators with established audit infrastructure, visible most acutely in United States metropolitan markets with active institutional outsourcing programs.
Catering Services Market Segmentation
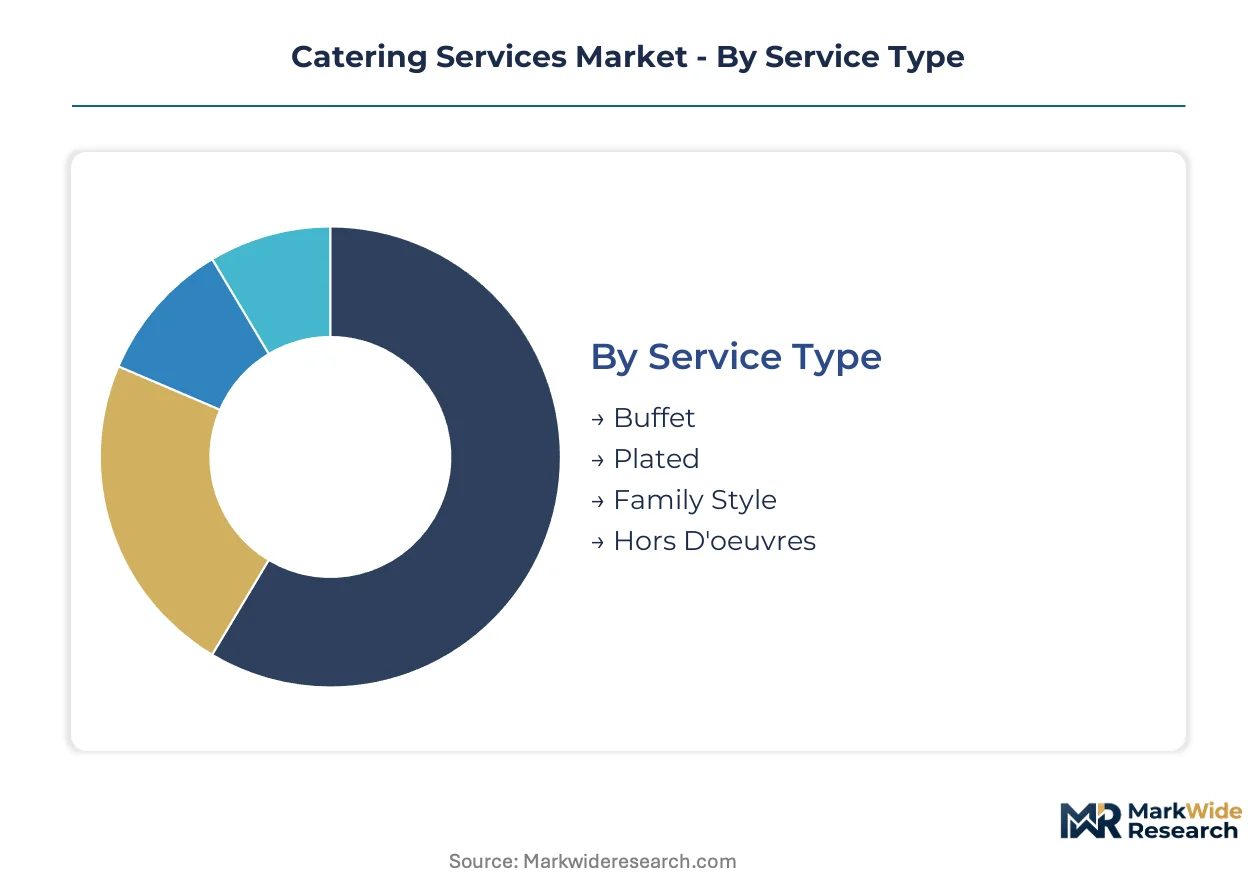
Catering operators configure service portfolios around contract renewal cycles and margin predictability. Segment selection determines cold-chain infrastructure investment, labor scheduling models, and compliance architecture across institutional and commercial accounts.
Service Type:
Domestic demand concentrates in buffet and plated formats for recurring corporate contracts, while export-oriented premium formats serve international event hospitality.
- Buffet:Self-service format with hot-holding equipment maintaining temperatures above 60°C for protein items. Demand clusters in United States healthcare systems and university dining halls where throughput efficiency overrides customization requirements; labor cost pressure accelerates tray-line automation adoption.
- Plated:Individual portion service requiring synchronized kitchen timing and formal service staff. Corporate headquarters in Manhattan, London, and Singapore sustain premium pricing for executive dining programs; white-tablecloth specifications demand credentialed chef oversight.
- Family Style:Shared platters delivered to table center for guest self-service. Casual wedding markets in Texas and Florida favor this format for cost control.
- Hors D'oeuvres:Bite-sized items served during reception periods without seated dining. Cocktail-hour formats dominate metropolitan gallery openings and luxury residential events.
Buffet holds the largest share; momentum sits with Plated as corporate clients restore pre-pandemic service standards.
Event Type:
Volume tiers separate recurring procurement from one-time celebration spend, with contract structures varying dramatically across renewal frequency.
- Corporate Events:Recurring business meals, conferences, and employee dining programs with multi-year service agreements. Technology sector campuses in Seattle and Austin drive contract value concentration; ESG reporting requirements now mandate carbon disclosure for vendor selection.
- Weddings:Single-occasion celebration catering with seasonal demand peaks. Destination wedding corridors in Mexico and Caribbean islands attract export-oriented premium operators.
- Private Parties:Residential and social club events for affluent individuals. Hamptons summer season and Aspen winter calendar sustain ultra-premium pricing tiers.
- Festivals:Large-scale temporary food operations at music and cultural events. Permit-heavy logistics favor operators with established health department relationships in California and Nevada.
Corporate Events anchor revenue stability; Weddings deliver the steepest expansion trajectory in experiential spending recovery.
Customer Segment:
Contract duration and pricing power diverge sharply between institutional procurement and discretionary consumer purchase.
- Corporates:Enterprise foodservice contracts with centralized procurement departments. Fortune 500 headquarters in Chicago and Boston prioritize ISO 14001-certified vendors; contract terms now embed diversity spending requirements.
- Educational Institutions:K-12 districts and university dining systems with USDA commodity program participation. Rural Midwest school systems remain underserved due to route density economics.
- Individuals:Direct-to-consumer event booking through digital platforms. Platform-mediated discovery is displacing traditional wedding planner intermediaries.
- Non-profits:Fundraising galas and mission-driven events with budget-constrained menus. Volunteer coordination complexity limits operator interest in sub-scale accounts.
Corporates command the deepest contract value; Educational Institutions are gaining share fastest as outsourcing accelerates.
Cuisine Type:
Menu specialization requirements shape supply chain sourcing radius and kitchen equipment configuration.
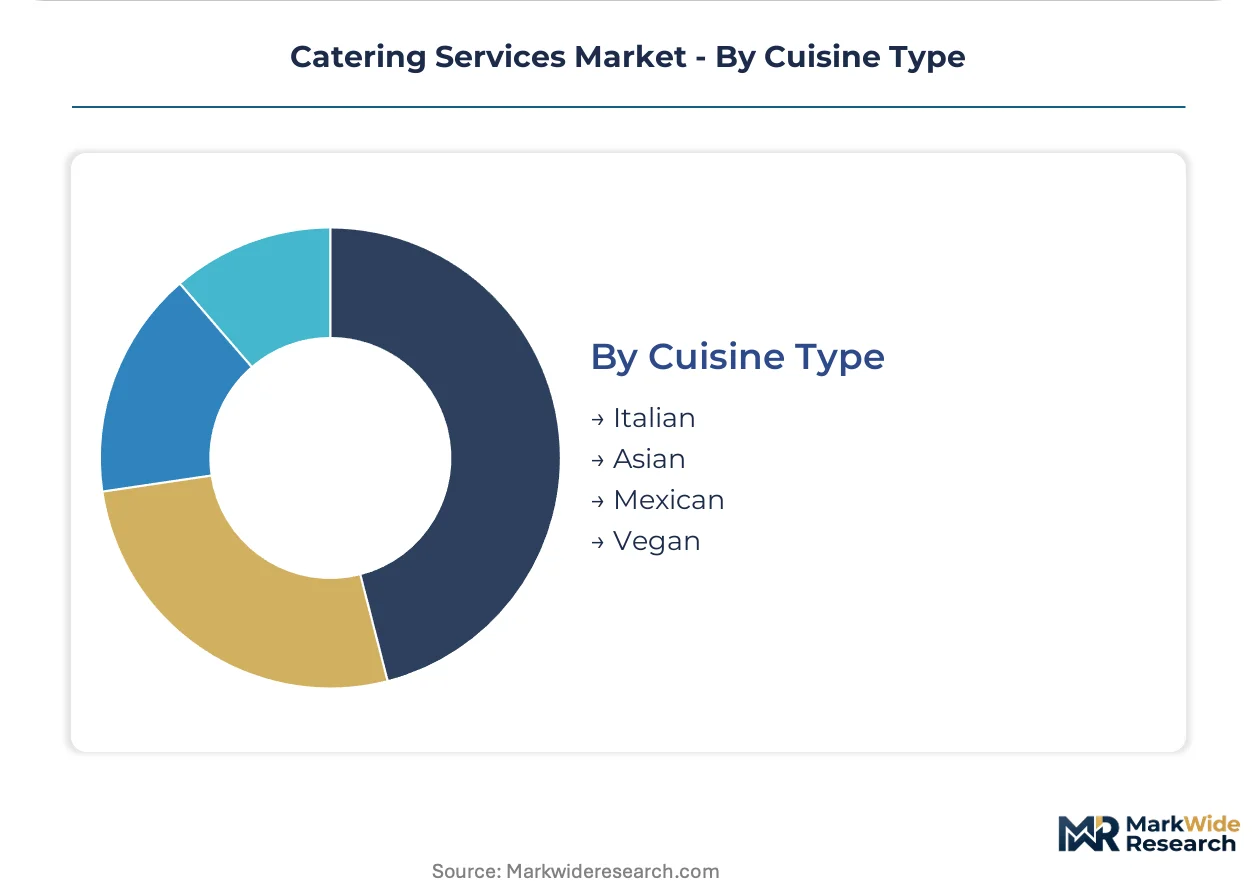
- Vegan:Plant-based menus excluding all animal products. Advanced extrusion technology enables scalable protein analog production; educational and healthcare accounts in California and Pacific Northwest now mandate vegan option availability.
- Asian:Regional formats spanning Chinese banquet, Japanese bento, and Southeast Asian street food. Wok stations and specialized ventilation requirements constrain kitchen retrofit options.
- Italian:Pasta-forward menus with regional specificity from Northern cream sauces to Southern seafood preparations. Commissary pasta production achieves cost parity with scratch preparation at volume thresholds above 500 covers.
- Mexican:Taqueria and full-service formats with masa preparation requirements. Fresh tortilla production distinguishes premium positioning from commodity catering.
Italian retains volume leadership; Vegan climbs the fastest as institutional procurement mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food safety modernization anchors operational standards in the United States, the largest contract catering geography. EFSA hygiene mandates and EU Green Deal procurement rules reshape competitive requirements across European markets. Demand concentration tracks institutional outsourcing intensity and sports-venue development cycles.
United States
Corporate dining programs and sports-venue hospitality sustain premium contract growth in major metropolitan corridors. FDA Food Code digitization mandates automated temperature monitoring and compliance logging across state lines. Chicago and Boston headquarters clusters drive Fortune 500 procurement volume with ISO 14001 certification requirements embedded in vendor selection.
Germany
Industrial canteen outsourcing and automotive sector dining contracts concentrate demand in Baden-Württemberg and Bavaria manufacturing belts. EU Green Deal procurement mandates now require carbon footprint disclosure for public sector foodservice awards. Frankfurt and Munich corporate campuses enforce cross-border service protocols under EFSA digital traceability requirements for allergen management.
United Kingdom
Financial services sector dining and educational institution outsourcing anchor contract stability in Greater London and Southeast England. Health and Safety Executive workplace standards constrain kitchen design alongside local authority inspection regimes. Manchester and Birmingham healthcare systems deploy automated tray assembly lines to reduce chef dependency in high-volume institutional settings.
France
Luxury event hospitality and corporate headquarters dining sustain premium pricing tiers in Île-de-France. ANSM enforces allergen-labeling standards that intersect with EFSA cross-border compliance protocols for multi-national operators. Lyon and Marseille educational accounts mandate vegan menu availability as plant-based procurement policies penetrate public sector contracts.
Japan
Corporate bento delivery and aged-care facility dining drive institutional contract growth in Tokyo and Osaka metropolitan areas. METI workplace safety standards and PMDA food hygiene regulations govern commercial kitchen certification requirements. Nagoya manufacturing corridor canteen operators face labor automation thresholds determining facility investment priorities.
Catering Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the contract catering sector. The market structure consolidates around multi-national operators with centralized procurement networks and regional specialists with localized labor management platforms. Three archetypes dominate: integrated facility managers with cross-service contracts, pure-play caterers with cuisine specialization, and technology-enabled disruptors with AI-driven demand forecasting. Competitive moves concentrate on strategic partnerships for cold-chain logistics and portfolio diversification into plant-based menu development.
Within the integrated facility management tier, Compass Group PLC and Sodexo S.A. exemplify operators with scale-driven procurement advantages across fragmented regional markets. Aramark Corporation anchors the sports and entertainment venue specialization archetype. Among European-based operators, Elior Group occupies a position representing institutional contract concentration in educational and healthcare accounts.
| Leading Market Players |
|---|
| ISS A/S |
| Mitie Group PLC |
| Compass Group PLC |
| DO & CO Aktiengesellschaft |
| Hutten Catering BV |
| Sodexo S.A. |
| AVI Foodsystems, Inc. |
| Elior Group |
| Aramark Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 14001 environmental management certification gates both vendor qualification and price premium capture in corporate foodservice procurement, forcing operators to absorb audit infrastructure costs before bidding while enabling certified players to command tier separation from uncertified competitors in Fortune 500 contract awards.
Pricing Analysis
Manhattan and London command 40-60% premiums over Midwestern US and Eastern European markets for equivalent plated service specifications. Three-tier pricing structure across premium white-tablecloth, standard buffet, and economy tray-line levels separates operators by chef credential requirements and service labor ratios. Pricing pressure stems from fixed-price corporate contract exposure to beef and poultry input volatility. Educational institutions exhibit highest price sensitivity due to USDA commodity program constraints, while private equity-backed event hospitality shows lowest sensitivity.
Supply Chain Analysis
Port congestion at Los Angeles and Long Beach elevates inbound logistics costs for imported specialty proteins and Asian cooking equipment. Supply concentrates in United States domestic beef and poultry processing, Brazilian soy protein for plant-based analogs, and Italian olive oil and specialty grains. Cold-chain logistics depend on refrigerated transport fleets and commissary kitchen networks within 150-mile service radii. Single-source vulnerability concentrates in specialized wok station manufacturing and automated cooking equipment components. Distribution runs through centralized commissary hubs to satellite kitchen operations and direct-to-venue cold transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract catering sits in early-cycle expansion as institutional outsourcing accelerates through K-12 district consolidation and healthcare system dining privatization, with plant-based menu mandates creating new procurement entry points for certified operators.
For Market Incumbents: Consolidate regional procurement networks to capture scale advantages against fragmented local competitors in underserved rural Midwest school districts. Invest in automated cooking equipment and IoT inventory sensors to reduce chef dependency and labor scheduling inefficiencies. Defensive priority centers on backward integration into plant-based protein processing to secure margin control against commodity input volatility.
For New Entrants and Emerging Players: ISO 14001 certification fast-track enables immediate qualification for corporate and educational procurement panels that filter on sustainability credentials. White-space targets cluster in rural K-12 districts with route density economics that national operators avoid, and in EU public sector contracts where Green Deal carbon disclosure requirements disadvantage uncertified incumbents. Go-to-market angle emphasizes AI-driven demand forecasting platforms that reduce food waste for budget-constrained institutional buyers.
For Investors and Strategic Acquirers: FDA Food Code digitization mandates reshape the acquisition landscape by elevating compliance technology infrastructure from cost center to competitive moat. Five-to-ten-year viability favors operators with established multi-state inspection track records and automated temperature monitoring systems already deployed. Acquisition target archetype: regional specialists with dense local health department relationships and underinvested technology stacks ripe for platform consolidation. Signal to watch: state-level HACCP enforcement variance that creates compliance cost asymmetries between operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Based Protein Processing | Captive supply of extruded protein analogs secures margin stability against commodity input volatility for institutional vegan mandates. |
| AI-Driven Demand Forecasting Platform Deployment | Machine learning convergence with IoT sensors reduces food waste and labor scheduling inefficiencies in high-volume healthcare and university settings. |
| ISO 14001 Certification Investment | Environmental management credentials unlock Fortune 500 and EU public sector procurement panels that filter on verified supply chain transparency. |
| Automated Cooking Equipment Retrofit | Robotic fry stations and tray assembly lines displace entry-level culinary positions while shifting operator investment toward maintenance technicians. |
| Rural K-12 District Route Density Expansion | Underserved suburban and Midwest school systems offer contract volume with limited national operator competition due to logistics economics. |
Methodological Framework
The analysis maps contract catering service types, event categories, customer segments, and cuisine specializations, each validated through executive interviews with contract catering operations directors, corporate procurement officers at Fortune 500 headquarters, K-12 district foodservice administrators, and healthcare system dining directors. Secondary validation draws from FDA Food Code enforcement records, USDA commodity program participation data, EU EFSA hygiene regulation filings, and corporate sustainability procurement disclosures. Bottom-up segment sizing triangulates against top-down market value estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models service type, event type, customer segment, and cuisine type dimensions alongside regional regulatory cluster variations. CAGRs derive from trend extrapolation of contract renewal cycle compression and institutional outsourcing penetration rates. Industry-specific forecast inputs include chef labor wage trajectories and cold-chain logistics capacity expansion.
Underlying assumptions cover hybrid work stabilization, HACCP digitization enforcement timelines, and plant-based procurement mandate proliferation, with deviation risk concentrated in protein input cost volatility and ghost kitchen substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Hospitality Market