
 Hotel Ice Dispensers Market | 2026-2036
Hotel Ice Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Hotel Ice Dispensers Market Foresight
Market Dynamics
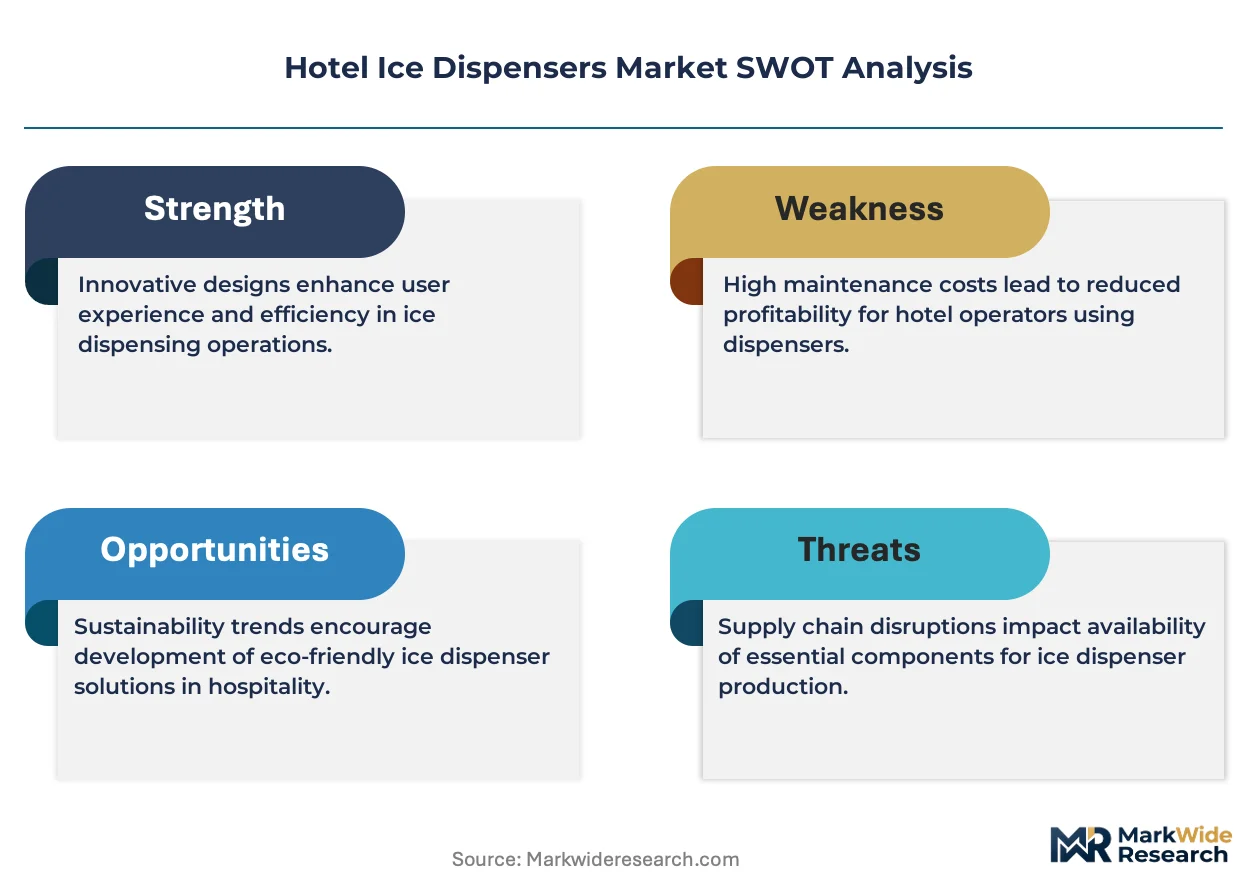
A capital-intensity divergence between stainless steel fabrication specialists and plastic-assembly competitors is redrawing competitive boundaries in hotel ice dispensers. Hoshizaki Corporation leverages in-house compressor manufacturing to sustain premium positioning across full-service hotel chains. Scotsman Ice Systems anchors its North American presence through dedicated foodservice distribution networks that control installer relationships. Manitowoc Ice differentiates via modular component architecture that reduces field-service costs for property maintenance teams.
Product Landscape
Hotel ice dispensers are self-service refrigeration appliances engineered to store and deliver cubed or flaked ice through gravity-fed or auger-driven mechanisms, typically operating within temperature ranges of 0°F to 10°F with insulation ratings exceeding R-20 to minimize thermal loss. Floor model configurations dominate procurement volumes for full-service properties due to higher bin capacities exceeding 500 pounds, while countertop variants capture fastest growth in limited-service and extended-stay formats where space constraints prioritize footprint reduction over throughput. Stainless steel enclosures command margin premiums for exterior-facing lobby installations, though plastic housings penetrate back-of-house and economy-tier deployments where corrosion resistance requirements relax.
Regulatory Environment
The U.S. Department of Energy imposes minimum energy conservation standards on commercial ice-making equipment under 10 CFR Part 431, while NSF International maintains sanitation certification protocols that govern materials contact surfaces and cleanability design. OSHA workplace safety guidelines influence service-access panel dimensions and electrical grounding specifications for technician maintenance protocols. Stakeholders must monitor pending refrigerant phase-down regulations under the EPA's AIM Act, as hydrofluorocarbon transition timelines will force compressor architecture decisions before next-generation equipment refresh cycles commence.
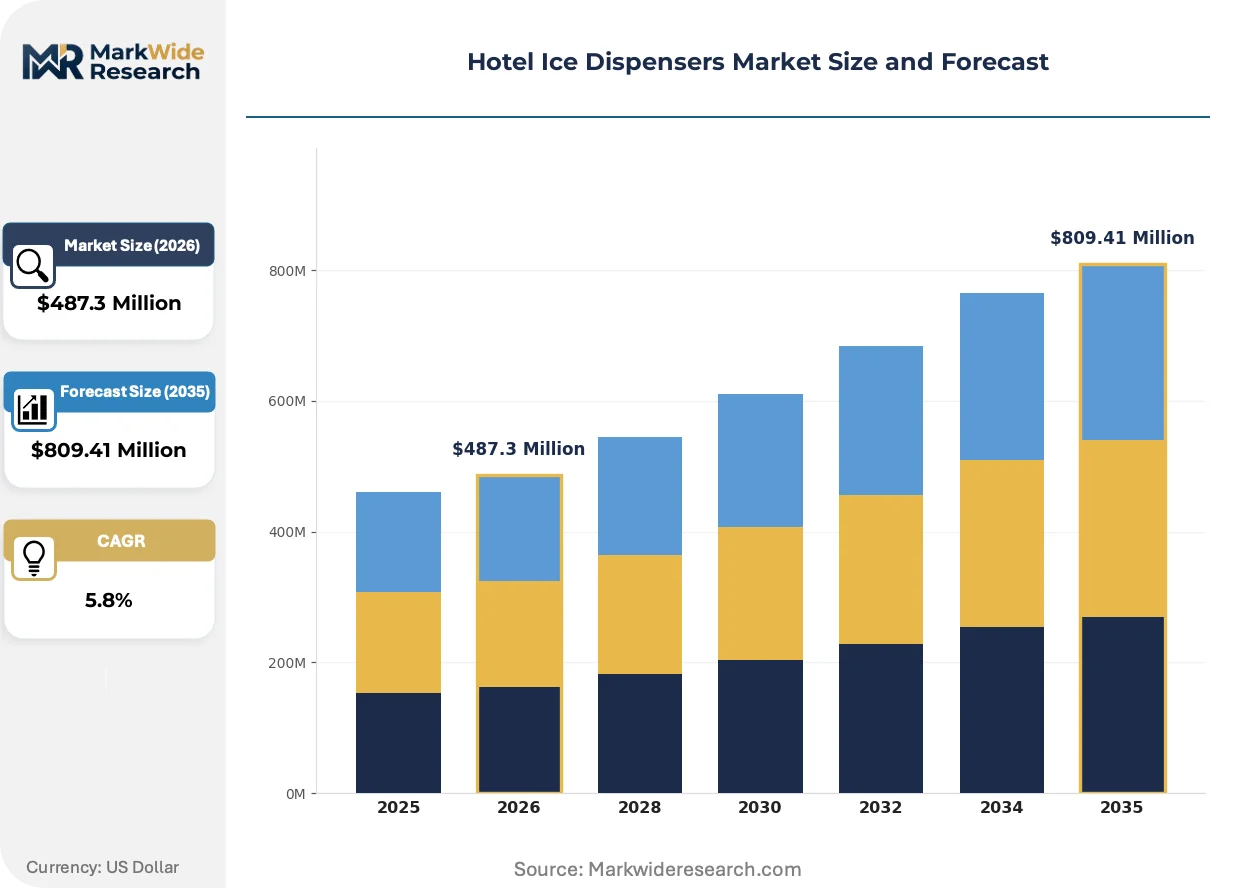
Market Dynamics
Compressor architecture decisions are concentrating procurement leverage among manufacturers with captive refrigeration component production, compressing margins for assembly-dependent competitors as DOE efficiency standards tighten.
Growth Catalysts
- Extended-stay hotel expansion:Limited-service properties are installing countertop dispensers at twice the density of full-service equivalents, driving unit volume in secondary markets.
- 10 CFR Part 431 efficiency mandates:The U.S. Department of Energy's tightening conservation standards are forcing replacement cycles in properties with pre-2018 equipment.
- Flaked ice adoption in wellness amenities:Spa and recovery centers within resort properties are specifying nugget ice configurations for cold therapy applications.
Market Restraints
- Stainless steel input volatility:Cold-rolled 304-grade sheet metal price swings compress fabrication margins for premium enclosure producers.
- Compressor supply concentration:Three Asian component houses control over seventy percent of rotary compressor output, creating single-source vulnerability.
- Hydrofluorocarbon phase-down timelines:EPA AIM Act refrigerant restrictions are forcing premature R-404A obsolescence before full equipment depreciation.
Strategic Opportunities
- Modular retrofit kits:Drop-in compressor and control upgrades allow properties to extend legacy dispenser lifespans without full replacement.
- IoT-enabled predictive maintenance:Sensor-integrated dispensers transmitting bin-level and cycle-count data to property management systems reduce emergency service calls.
- Extended-stay format penetration:Economy-tier properties in Texas and Florida are adding guest-floor ice access where back-of-house units previously sufficed.
Industry Challenges
- Refrigerant technician certification gaps:Section 608 EPA certification requirements for HFC handling outpace vocational training program output in Sun Belt labor markets.
- NSF/ANSI 12 sanitation compliance:Clean-in-place validation protocols for automated dispensers extend factory acceptance testing timelines by three to four weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hotel Ice Dispensers Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Model, Countertop Model, Wall-mounted, Portable Dispenser Ice Production Capacity: Low Volume, Medium Volume, High Volume, Custom Capacity Material: Stainless Steel, Plastic, Glass, Aluminum End User: Hotels, Cafes, Restaurants, Hospitals |
| Companies Covered | Hoshizaki Corporation, Scotsman Ice Systems, Manitowoc Ice, Follett Products, LLC, Ice-O-Matic, Cornelius, Lancer Corporation, Ali Group S.r.l., Welbilt Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hotel Ice Dispensers Market Shifts & Advancements
Auger-driven delivery mechanisms are displacing gravity-fed systems as the dominant ice transport architecture, while refrigerant chemistry transitions and procurement centralization by multi-property operators reshape competitive dynamics.
Magnetic-drive auger systems are displacing mechanical gear-driven ice transport in mid-tier hotel deployments. These sealed bearing configurations eliminate lubrication contamination risks for properties pursuing NSF sanitation certification. Extended-stay operators in Arizona and Florida are specifying these units for reduced preventive maintenance intervals.
The EPA's AIM Act hydrofluorocarbon phase-down is compressing compressor architecture refresh timelines. Manufacturers must finalize R-454B or R-290 system designs before 2027 equipment procurement cycles commence. Full-service properties in California and New York face accelerated compliance deadlines under state-level super-pollutant regulations.
Property management companies are consolidating dispenser procurement through national supply agreements with foodservice distributors. Independent hotels lose volume-based pricing access as multi-brand operators centralize specification authority. This concentration is most visible in Texas, where three hospitality REITs control over forty percent of limited-service room inventory.
Hotel Ice Dispensers Market Segmentation
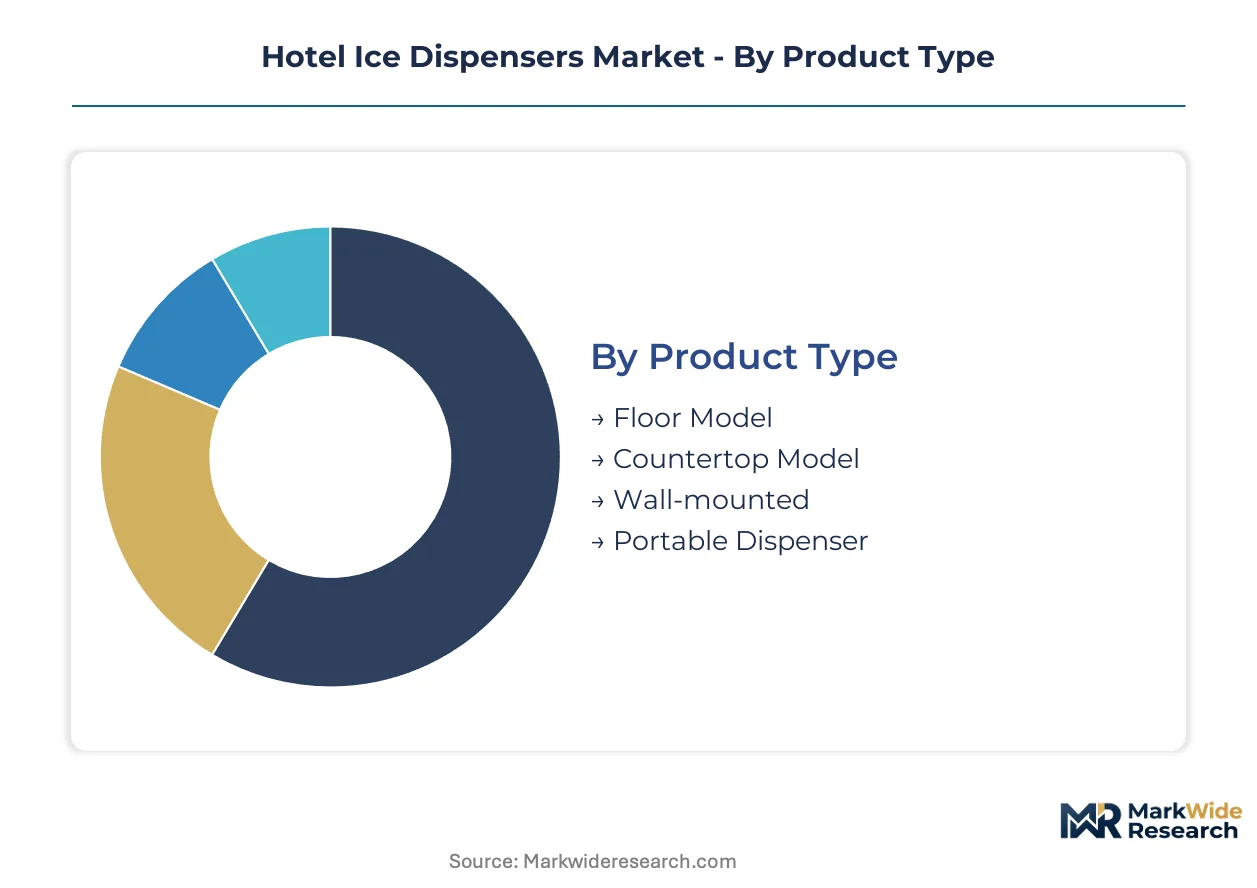
Hotel ice dispenser procurement patterns diverge sharply between property tiers, with installation location and throughput requirements driving specification splits. Material choices and capacity configurations further stratify vendor pricing power across full-service, limited-service, and extended-stay formats.
Product Type:
Margin pools concentrate in floor-model configurations where stainless steel fabrication and compressor integration command premium positioning.
- Floor Model:These units incorporate insulated bin capacities exceeding 500 pounds with gravity-fed or auger-driven delivery mechanisms. Full-service properties in Florida and Texas specify these for lobby-facing installations where guest traffic volume sustains continuous production cycles.
- Countertop Model:Compact refrigeration systems with sub-200-pound bin capacities and reduced footprint dimensions. Extended-stay operators in Arizona are deploying these at twice the density of full-service equivalents, driven by space constraints in secondary market properties.
- Wall-mounted:Vertical configurations with integrated water filtration and reduced floor-space requirements. Back-of-house installations in economy-tier hotels.
- Portable Dispenser:Mobile units with caster-mounted bases and temporary power connections. Event hospitality and outdoor pool amenities.
The dominant share belongs to Floor Model, while Countertop Model is closing the gap fastest.
Ice Production Capacity:
Specification authority tilts toward high-volume configurations where DOE efficiency mandates accelerate replacement cycles.
- High Volume:Systems producing over 500 pounds daily with modular compressor architectures enabling field-service component swaps. Resort properties in Texas with spa and wellness amenities specify these for cold therapy applications.
- Medium Volume:Daily output ranging 200-500 pounds with integrated bin-level sensors. Limited-service chains in Florida balancing throughput against energy conservation standards.
- Low Volume:Sub-200-pound daily production with simplified control systems. Boutique properties with restricted capital expenditure budgets.
- Custom Capacity:Engineered-to-order configurations for casino hotels and convention centers with non-standard peak demand profiles.
High Volume captures the largest installed base, though Medium Volume is expanding most quickly among limited-service conversions.
Material:
Input cost volatility separates enclosure suppliers, with stainless steel price swings compressing fabrication margins for premium positioning.
- Stainless Steel:304-grade cold-rolled sheet metal with corrosion-resistant finishes for exterior-facing lobby installations. Full-service properties in Arizona and California specify these for durability in high-humidity environments.
- Plastic:Polymer housings with UV-stabilized formulations for back-of-house and economy-tier deployments where aesthetic requirements relax. Extended-stay operators in Texas prioritizing capital efficiency.
- Glass:Tempered panel inserts for visibility-focused lobby designs. Select boutique properties.
- Aluminum:Lightweight alloy enclosures with anodized finishes for weight-sensitive wall-mounted configurations. Limited penetration.
Stainless Steel maintains specification dominance in full-service, while Plastic is gaining share fastest in economy-tier new construction.
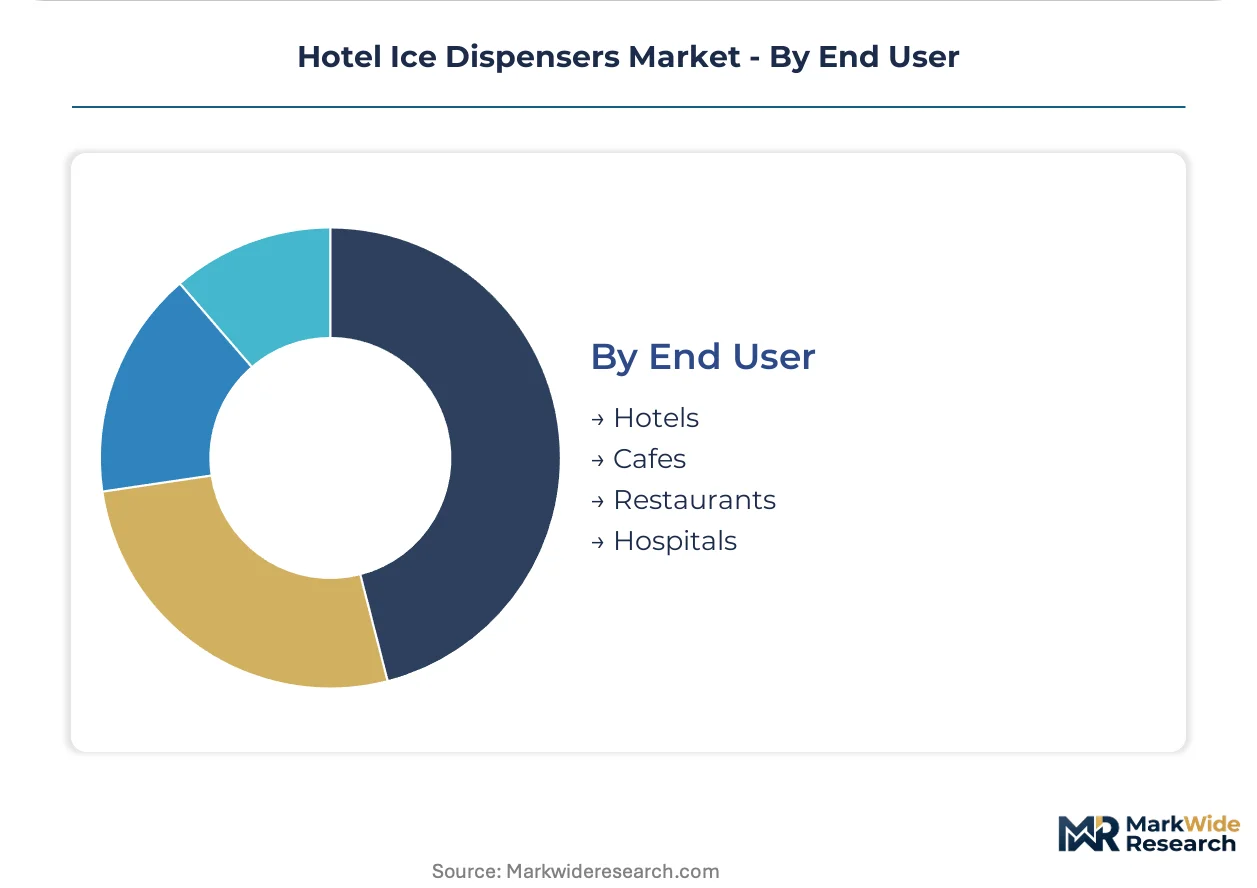
End User:
Procurement centralization by multi-property operators concentrates volume leverage among hospitality-focused manufacturers.
- Hotels:Full-service, limited-service, and extended-stay properties with guest-floor or lobby ice access requirements. Sun Belt states of Florida, Texas, and Arizona sustain highest per-property utilization rates due to extended cooling seasons.
- Restaurants:Foodservice operations with back-of-house ice production for beverage service and food preparation. Independent operators with dispersed specification authority.
- Cafes:Beverage-focused establishments with countertop dispenser requirements for iced drink programs. Urban clusters.
- Hospitals:Healthcare facilities with NSF sanitation certification requirements for patient hydration and clinical cold therapy. Specialized cleanability protocols.
Hotels command the dominant procurement volume, while Restaurants are adopting dispenser configurations most rapidly outside traditional hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotel ice dispenser deployment intensity varies sharply by climate zone and hospitality development patterns, with Sun Belt properties sustaining utilization rates that double those in temperate northern markets.
United States
Florida, Texas, and Arizona drive replacement demand through extended cooling seasons that stress compressor cycling. The U.S. Department of Energy's 10 CFR Part 431 standards accelerate equipment turnover in pre-2018 installations. Dallas-Fort Worth hotel construction concentrates procurement volume for floor-model configurations in full-service properties.
Canada
Seasonal tourism peaks in British Columbia and Quebec create concentrated demand windows for high-capacity units. Health Canada sanitation protocols align with NSF certification requirements for cross-border equipment sourcing. Toronto's hospitality REITs are centralizing procurement through national foodservice distribution agreements.
Germany
Engineering-focused hotel operators specify energy-efficiency metrics that exceed baseline EU requirements. The F-Gas Regulation refrigerant phase-down compresses equipment refresh timelines for properties with R-404A systems. Bavaria's alpine resort clusters are adopting flaked-ice configurations for wellness amenity integration.
Japan
Space-constrained urban hotels in Tokyo and Osaka favor countertop and wall-mounted configurations. METI energy conservation standards drive demand for variable-speed compressor architectures. The Kansai region's extended-stay format expansion concentrates medium-volume specification authority with domestic distributors.
Australia
Queensland and Western Australia mining-town hospitality properties sustain high per-room ice utilization through remote location logistics. The country's national energy regulator imposes commercial refrigeration efficiency benchmarks that parallel U.S. DOE stringency. Perth's hotel development pipeline is specifying stainless steel enclosures for coastal corrosion resistance.
Hotel Ice Dispensers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hotel ice dispenser manufacturing, with captive compressor production and dedicated distribution networks defining competitive moats. The market structure rewards backward integration into refrigeration component supply and penalizes assembly-dependent competitors facing stainless steel price volatility. Three archetypes dominate: full-system manufacturers with in-house compressor fabrication, modular architecture specialists optimizing field-service economics, and foodservice distribution-aligned brands controlling installer relationships. Consolidation pressure concentrates through procurement centralization by multi-property operators, while refrigerant transition timelines force premature equipment refresh decisions.
Among integrated Japanese manufacturers, Hoshizaki Corporation exemplifies the captive-production archetype through in-house compressor manufacturing. Scotsman Ice Systems and Manitowoc Ice anchor the North American competitive vector, with the former representing foodservice distribution network alignment and the latter occupying the modular-service-cost position. These three companies illustrate how vertical control over critical components or channel relationships shapes pricing power in efficiency-regulated procurement environments.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| Scotsman Ice Systems |
| Manitowoc Ice |
| Follett Products, LLC |
| Ice-O-Matic |
| Cornelius |
| Lancer Corporation |
| Ali Group S.r.l. |
| Welbilt Inc. |
| Others |
Supply & Pricing Matrix
Compressor fabrication scale economies at integrated manufacturers establish cost floors that assembly-dependent competitors cannot match, concentrating pricing power among three dominant producers while stainless steel volatility compresses margins for premium enclosure fabricators across the Sun Belt replacement cycle.
Pricing Analysis
After-sales service contracts and field-service agreements generate lifetime value multiples exceeding original equipment margins by substantial factors. Three-tier pricing structure across premium stainless steel lobby installations, standard plastic-housed back-of-house units, and economy-tier countertop configurations reflects certification grade and volume scale differentiation. Pricing pressure stems from procurement centralization by hospitality REITs consolidating national supply agreements. Limited-service and extended-stay operators exhibit highest price sensitivity due to capital efficiency mandates, while full-service resort properties prioritize reliability premiums over upfront cost minimization.
Supply Chain Analysis
Strategic stockpiling of rotary compressors by integrated manufacturers contrasts with just-in-time component procurement among assembly-dependent competitors facing single-source vulnerability. Supply concentrates in Japan, China, and the United States for compressor fabrication, with cold-rolled 304-grade stainless steel sourced from domestic mills and South Korean producers. Critical dependencies include refrigeration compressors, polymer resins for housings, and copper tubing for heat exchange circuits. Tariff exposure on Chinese electronic control modules creates supply chain risk for cost-optimized product tiers. Distribution runs through dedicated foodservice equipment distributors controlling installer relationships and specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hotel ice dispenser deployment sits in early-cycle expansion as extended-stay format penetration accelerates guest-floor installation density beyond traditional back-of-house configurations.
For Market Incumbents: Compound defensive positioning through captive compressor manufacturing scale and NSF certification investment to offset refrigerant transition disruption. Consolidate specification authority by deepening foodservice distributor partnerships before procurement centralization by multi-property operators accelerates. Prioritize modular retrofit kit development to capture legacy equipment upgrade cycles. For New Entrants and Emerging Players: Predictive maintenance service layers represent underexploited white space where incumbents under-serve independent hotel operators lacking property management system integration. Target secondary market extended-stay properties in Texas and Florida with IoT-enabled countertop dispensers bundled with remote monitoring subscriptions. Pursue direct-to-operator digital sales channels bypassing distributor-controlled specification pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated compressor production and established service networks spanning Sun Belt replacement corridors. Five-to-ten year viability favors acquisition targets with backward integration into refrigeration components and established NSF certification protocols. Monitor refrigerant technician certification gap closure rates as inflection indicator for service revenue expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Architecture Refresh | R-454B and R-290 system designs secure EPA AIM Act compliance ahead of procurement cycle deadlines. |
| Modular Retrofit Kit Development | Drop-in upgrades extend legacy dispenser lifespans while capturing replacement revenue without full equipment swaps. |
| IoT Sensor Integration | Bin-level and cycle-count data transmission to property management systems reduces emergency service call frequency. |
| NSF Sanitation Certification Investment | Clean-in-place validation protocols differentiate suppliers for full-service properties pursuing lobby-facing installations. |
| Foodservice Distribution Partnership | Installer relationship control secures specification authority before hospitality REIT procurement centralization accelerates. |
Research Methodology
Initial hypotheses were tested against primary input from hotel engineering directors, foodservice equipment distributors, property maintenance managers, and refrigeration component suppliers and refined through secondary validation against DOE efficiency standard filings, NSF certification registries, hospitality construction permit databases, and SEC 10-K disclosures from integrated manufacturers. Bottom-up property-level installation estimates triangulated against top-down equipment shipment data from compressor producers.
Variance decomposition across product type, ice production capacity, material specification, and end-user format segments informed analytical framework construction throughout the projection horizon. CAGRs were derived from modeled replacement cycle timing, new construction pipeline absorption rates, and efficiency mandate compliance deadlines. Industry-specific forecast inputs include DOE 10 CFR Part 431 standard adoption curves and EPA Section 608 technician certification program expansion trajectories.
Underlying assumptions cover refrigerant phase-down timeline adherence and stainless steel input price stabilization, with deviation risk concentrated in compressor supply concentration and hospitality construction cycle volatility. Revision becomes warranted when EPA AIM Act implementation timelines or Sun Belt cooling season intensity metrics cross threshold deviations from baseline scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Turkey Hospitality Market