
 Restaurant Furniture Market | 2026-2036
Restaurant Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Furniture Market Outlook
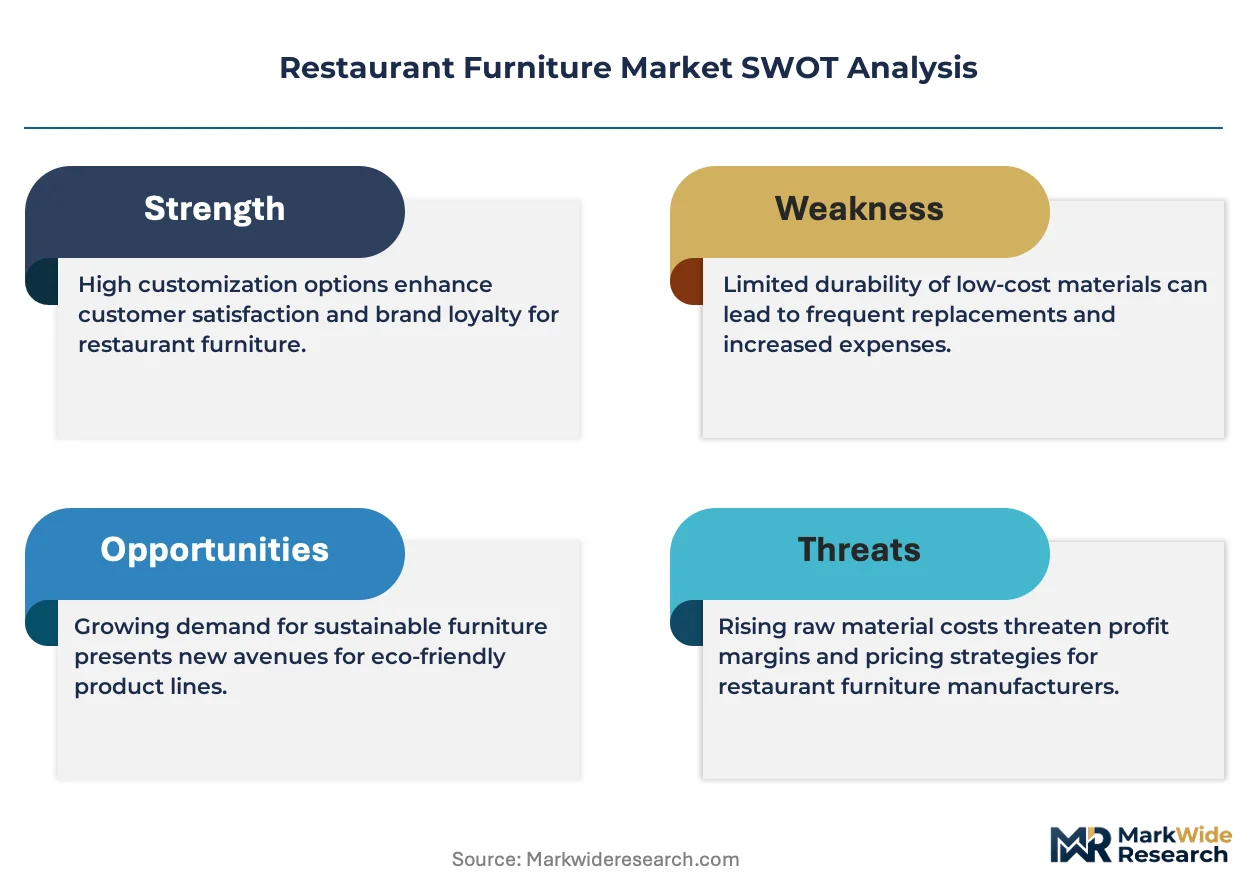
GREENGUARD Gold certification is bifurcating the competitive landscape between suppliers who meet indoor air quality standards and those confined to lower-tier bids. Grand Rapids Chair Co. leverages its Michigan manufacturing base to sustain rapid custom-order turnaround for regional chains. Herman Miller competes through design-forward seating that commands premium placement in upscale fast-casual concepts. Grosfillex dominates outdoor resin furniture through proprietary polymer formulations engineered for UV stability and stackability.
Restaurant furniture encompasses fixed and movable seating, surface, and storage systems engineered for high-frequency commercial use, typically rated for cycles exceeding 100,000 seat drops with materials selected for stain resistance, structural load tolerance, and compliance with CAL 117/133 flammability protocols. Its primary commercial purpose centers on optimizing guest throughput, brand atmosphere, and maintenance economics across foodservice environments. Wood material commands the largest revenue pool due to enduring preference in fine dining and fast-casual rebranding, while upholstered seating captures expanding share as acoustic comfort becomes a design priority. Metal frames anchor the fastest-growing specification segment as open-kitchen layouts expose structural elements to patron sightlines.
The Consumer Product Safety Commission governs stability and tip-over standards for restaurant seating, while EPA regulations on formaldehyde emissions from composite wood products constrain panel sourcing for domestic manufacturers. California's Bureau of Electronic and Appliance Repair, Home Furnishings and Thermal Insulation administers flammability testing that de facto sets the national upholstery compliance threshold for chain rollouts. Stakeholders must monitor evolving state-level chemical disclosure requirements that threaten to fragment specification standards across multi-location deployments.
Market Dynamics
Post-pandemic seating densification is reshaping specification priorities as operators balance throughput targets against acoustic comfort and dwell-time management in reconfigured dining rooms.
Growth Catalysts
- California Title 24 energy standards:These regulations mandate high-efficiency lighting and HVAC integration with fixed seating installations, creating specification pull for compliant furniture systems in new construction across the state.
- Fast-casual acoustic retrofit wave:Chains are replacing hard-surface seating with upholstered banquettes to dampen noise levels and extend average visit duration in competitive urban markets.
- Texas and Florida permit velocity:Restaurant construction approvals in these states are outpacing national averages, concentrating demand for rapid-turnaround furniture procurement.
Market Restraints
- Polymer resin feedstock volatility:Outdoor furniture manufacturers face margin compression from propylene and polyethylene price swings tied to petrochemical supply disruptions.
- Grand Rapids manufacturing cluster dependency:Custom wood seating capacity concentrates in western Michigan, creating geographic vulnerability for chains requiring short-lead customization.
- CAL 117/133 testing backlog:California's flammability certification queue extends project timelines by six to twelve weeks for multi-location rollouts.
Strategic Opportunities
- GREENGUARD Gold specification gap:Indoor air quality certification remains sparse among mid-tier suppliers, opening premium positioning for early certifiers in healthcare-adjacent foodservice.
- Modular banquette systems:Reconfigurable seating platforms that adapt from two-top to communal configurations address operator demand for event-flexible dining rooms.
- Metal frame aesthetic exposure:Open-kitchen designs are elevating structural seating elements to visual prominence, rewarding suppliers with architectural metal finishing capabilities.
Industry Challenges
- Commercial upholstery craft shortage:Skilled sewing and pattern-making talent for high-cycle contract seating has not rebounded from pandemic-era workforce exits.
- Multi-state chemical disclosure fragmentation:Emerging state-level requirements beyond California are complicating specification standardization for national chain procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Furniture Market |
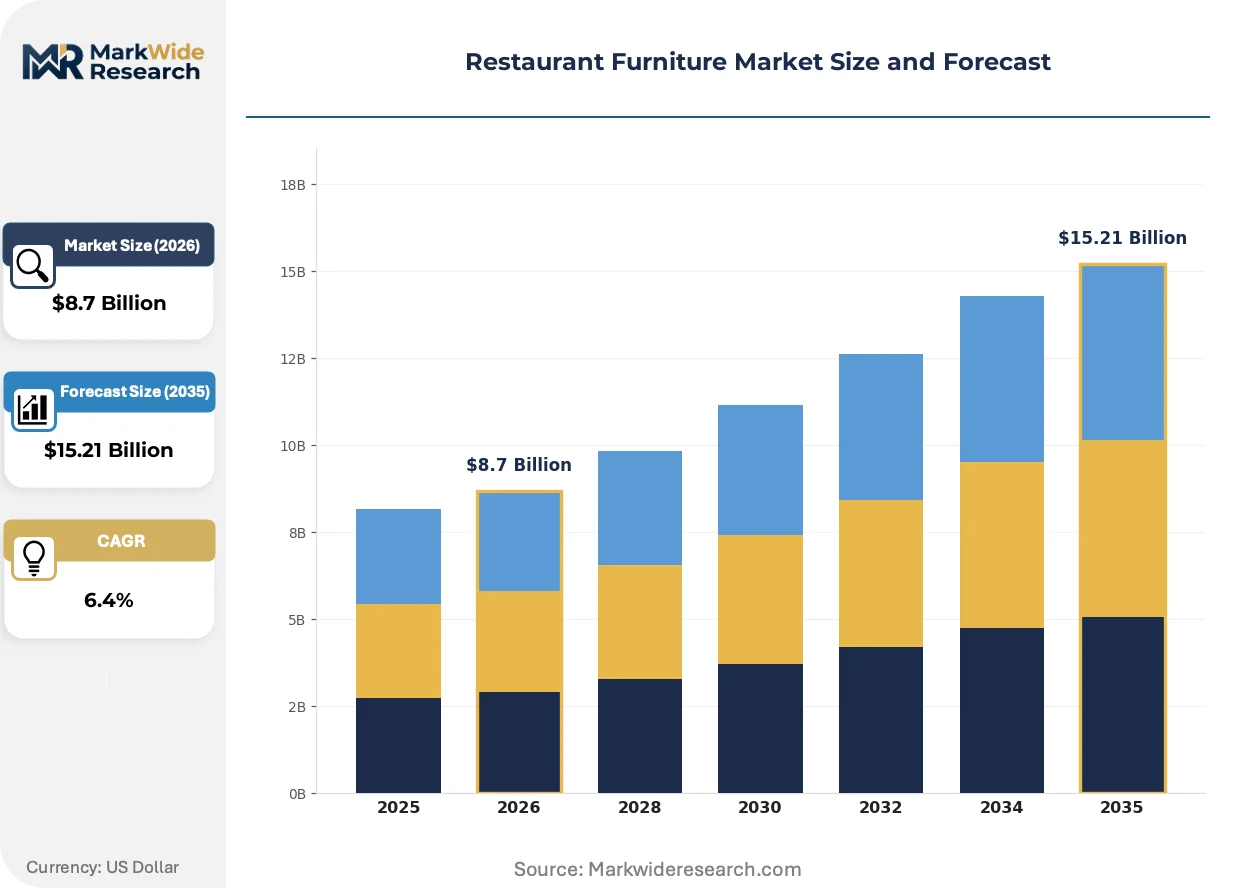
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tables, Chairs, Booths, Bar Stools Material: Wood, Metal, Plastic, Upholstered End User: Fast Casual, Fine Dining, Cafés, Pubs Style: Contemporary, Traditional, Rustic, Industrial |
| Companies Covered | Ashley Furniture Industries, Beaufurn, Merrick Seating, Grand Rapids Chair Co., Herman Miller, Plymold Seating, Grosfillex, Steelcase, CHI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Furniture Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine performance benchmarks across seating, surfaces, and storage categories in commercial foodservice environments.
Antimicrobial additive integration is fragmenting the surface materials landscape as operators specify copper-ion and silver-based compounds for high-touch zones. Fast-casual chains with high table-turn environments are adopting these treatments fastest. The technology is fragmenting supplier tiers between those with polymer chemistry partnerships and commodity laminate producers.
EPA formaldehyde emission rules for composite wood products are constraining panel sourcing flexibility for domestic seating manufacturers. The regulation forces verification of supply chain compliance back to substrate mills. California-based producers have adapted fastest, while Midwest suppliers face reformulation costs.
Direct-to-operator digital specification tools are compressing the traditional dealer-intermediary channel for standard product lines. Regional chain buyers are configuring and pricing modular systems through manufacturer portals. This pattern is most visible in Texas and Florida markets where construction velocity rewards procurement speed.
Restaurant Furniture Market Segmentation
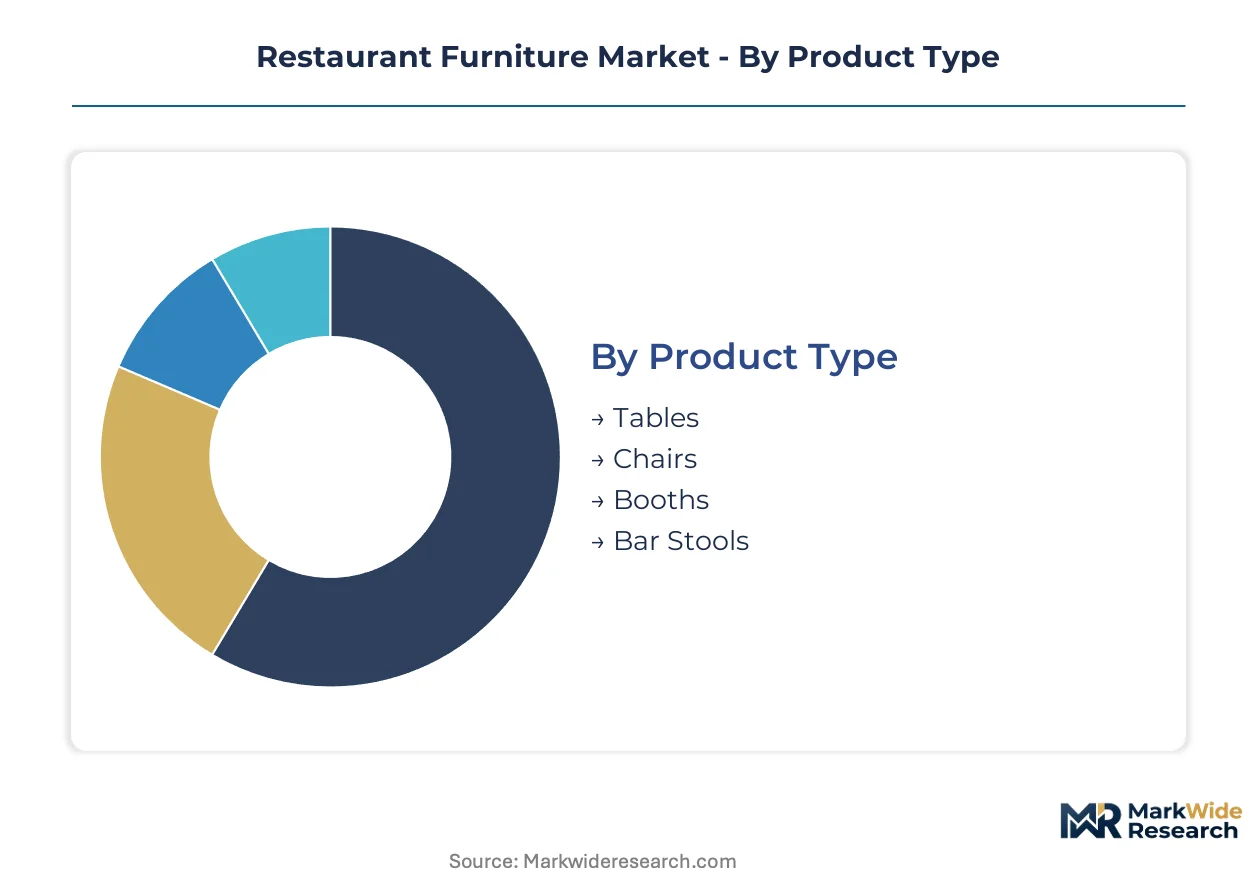
Segmentation in restaurant furniture reveals how specification priorities diverge across procurement channels. Dealer networks, direct manufacturer portals, and contract furniture specialists each favor distinct product configurations that reshape competitive positioning.
Product Type:
Chairs and tables move through high-volume dealer channels for standard rollouts, while booths and custom bar stools route through direct manufacturer relationships for specification-heavy projects.
- Tables:Engineered for load tolerance exceeding commercial duty cycles with laminate, solid surface, or reclaimed wood tops. Demand concentrates in Texas and Florida construction corridors where rapid-turn procurement favors standardized dimension programs.
- Chairs:Stackable and fixed-frame configurations dominate, rated for 100,000-plus seat drops with metal or wood structural elements. Fast-casual chains in urban markets are driving upholstered seat pad retrofits to manage acoustic comfort and extend dwell time.
- Booths:Custom banquette systems requiring pattern-matching and site-specific dimensioning.
- Bar Stools:Counter-height and bar-height specifications for open-kitchen sightline exposure.
Chairs dominate installed base. Booths are where expansion concentrates.
Material:
Cost tier stratification separates premium specification grades from bid-tier procurement, with certification status acting as the primary price differentiator.
- Wood:Hard maple, oak, and walnut species selected for grain consistency and CAL 117/133 substrate compliance. Fine dining rebranding across California and Pacific Northwest markets sustains demand for solid wood frames over veneer alternatives.
- Metal:Steel and aluminum frames with powder-coat or plated finishes engineered for UV stability and structural load. Open-kitchen layouts are elevating metal frame visibility to design prominence, rewarding suppliers with architectural finishing capabilities.
- Plastic:Polypropylene and resin formulations for outdoor stackability and weather resistance.
- Upholstered:Foam-core construction with commercial-grade textiles meeting flammability protocols.
Wood holds the largest revenue pool. Metal is climbing the fastest as exposed structural elements gain design currency.
End User:
Application-specific durability requirements and brand atmosphere targets create distinct procurement velocities across foodservice formats.
- Fast Casual:High-turn seating rated for rapid cycle counts with modular reconfiguration capability. Chains are replacing hard-surface seating with upholstered banquettes to dampen noise levels in competitive urban markets.
- Fine Dining:Custom millwork and premium upholstery specifying acoustic comfort and extended dwell time. California's Title 24 energy standards are reshaping fixed seating installations with integrated HVAC and lighting compliance.
- Cafés:Mixed seating configurations balancing laptop-work durability with residential aesthetic appeal.
- Pubs:High-abuse-rated frames and stain-resistant surfaces for beverage-service environments.
Fast casual commands procurement volume. Fine dining is where margin expansion concentrates.
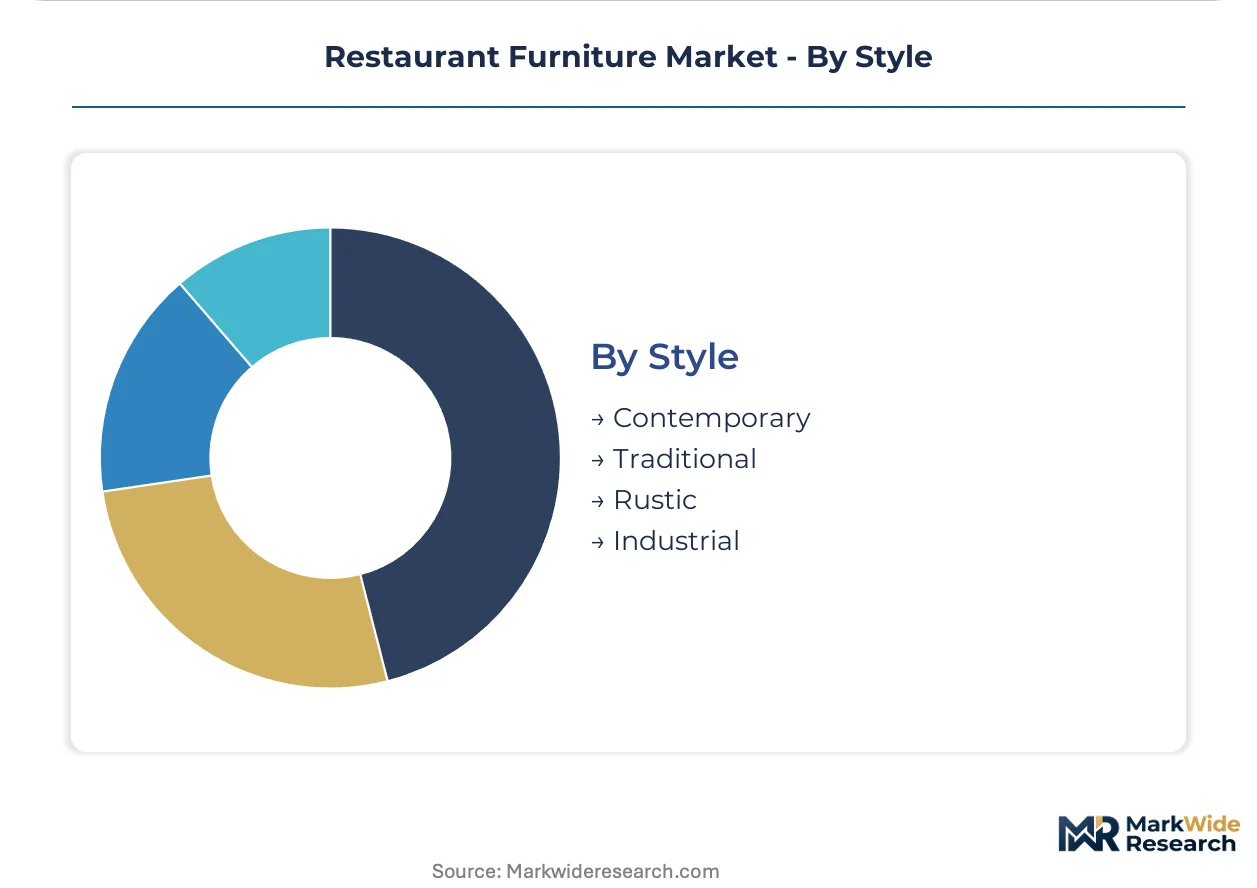
Style:
Geographic design preferences and brand positioning strategies segment specification patterns across regional markets.
- Contemporary:Clean-lined profiles with metal and mixed-material construction. Urban fast-casual concepts in Texas and Florida markets specify contemporary frames through direct-to-operator digital portals to compress procurement timelines.
- Traditional:Ornate wood framing and classic upholstery silhouettes for established hospitality brands.
- Rustic:Reclaimed wood and distressed finishes for regional identity concepts.
- Industrial:Exposed metal structure and raw material aesthetic for converted-warehouse locations.
Contemporary leads new construction specification. Industrial is gaining share fastest in adaptive reuse projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Full-service chains and fast-casual operators concentrate procurement authority in North America and Western Europe, while construction velocity in the southern United States and Gulf states is accelerating specification timelines. Regulatory divergence across jurisdictions is fragmenting compliance requirements for multi-location rollouts.
United States
Texas and Florida construction permits are outpacing national averages, concentrating demand for rapid-turnaround furniture procurement in Dallas-Fort Worth and Miami-Dade corridors. The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, constraining panel sourcing flexibility for domestic seating manufacturers. Grand Rapids, Michigan anchors custom wood seating capacity, though geographic concentration creates vulnerability for chains requiring short-lead customization.
Canada
Fast-casual expansion in Toronto and Vancouver is driving specification for acoustic-comfort seating as operators compete for urban dwell-time. Health Canada administers product safety standards for commercial furniture stability and tip-over prevention, aligning closely with CPSC protocols but maintaining separate certification queues. The Quebec manufacturing corridor around Montreal supplies upholstered banquettes for eastern Canadian and cross-border US deployments.
Germany
Fine dining rebranding in Berlin and Munich sustains demand for solid wood frames meeting EU Ecolabel and Blue Angel environmental standards. The ECHA REACH regulation restricts chemical substances in upholstery foams and surface coatings, forcing reformulation costs on suppliers serving pan-European chains. The North Rhine-Westphalia furniture cluster around Cologne and Düsseldorf specializes in metal frame engineering for open-kitchen sightline exposure.
United Kingdom
Adaptive reuse projects in London and Manchester are elevating industrial-style seating specifications for converted-warehouse hospitality concepts. The UK's Furniture and Furnishings (Fire Safety) Regulations 1988 mandate flammability testing for upholstered commercial seating, with post-Brexit divergence from EU harmonized standards complicating cross-border procurement. The East Midlands manufacturing base around Nottingham supplies contract seating for pub and casual dining chains.
France
Parisian fast-casual concepts are specifying contemporary metal-and-wood mixed frames through direct manufacturer relationships to compress procurement timelines. The ANSM and DGCCRF oversee chemical disclosure and product safety compliance, with emerging requirements for per- and polyfluoroalkyl substance (PFAS) restrictions in stain-resistant textiles. The Auvergne-Rhône-Alpes region around Lyon hosts specialized upholstery craft capacity for premium contract seating.
Restaurant Furniture Market Competitive Environment
Player mix skews toward mid-cap regional specialists with captive manufacturing capacity rather than diversified conglomerates. The vendor base separates into three tiers: certified premium suppliers capturing healthcare-adjacent foodservice, rapid-turn regional fabricators serving construction corridors, and commodity producers competing on price for standard rollouts. Consolidation pressure is minimal; competitive dynamics center on certification acquisition, geographic proximity to high-velocity construction markets, and custom-order turnaround speed rather than scale-driven M&A or vertical integration into raw material supply.
Among Michigan-based wood seating specialists, Grand Rapids Chair Co. occupies a position exemplifying rapid custom-order turnaround for regional chains. Herman Miller represents the design-forward archetype commanding premium placement in upscale fast-casual concepts. Grosfillex anchors the outdoor resin furniture segment through proprietary polymer formulations. These three companies illustrate the competitive spectrum: regional fabrication speed, aesthetic premium positioning, and material science specialization respectively.
| Leading Market Players |
|---|
| Ashley Furniture Industries |
| Beaufurn |
| Merrick Seating |
| Grand Rapids Chair Co. |
| Herman Miller |
| Plymold Seating |
| Grosfillex |
| Steelcase |
| CHI |
| Others |
Value Chain & Pricing Dynamics
Eight-to-twelve-week lead times for CAL 117/133 flammability certification concentrate pricing power with California Bureau-certified suppliers while compressing margins for Midwest manufacturers facing reformulation costs. This temporal chokepoint amplifies geographic supply concentration effects across the upholstered seating tier.
Pricing Analysis
Cost-plus contracts indexed to propylene and polyethylene spot markets dominate outdoor resin furniture procurement, with polymer feedstock volatility passing through to operators within 30-60 day adjustment windows. Price differentiation hinges on GREENGUARD Gold certification status and custom-order turnaround speed, with certified premium suppliers commanding placement in healthcare-adjacent foodservice while commodity producers compete for standard fast-casual rollouts. Cost compression in mid-tier upholstered seating is intensifying because skilled sewing craft shortages constrain output expansion. National chain procurement teams exhibit lowest price sensitivity for rapid-turn custom banquette systems, while independent operators in Texas and Florida construction corridors prioritize per-unit economy.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites petrochemical feedstock security for Grosfillex's proprietary polymer formulations, though the Grand Rapids manufacturing cluster anchors North American custom wood seating capacity. Raw material flows draw from Appalachian hardwood forests, Chinese textile mills for commercial-grade fabrics, and Gulf Coast resin production. Single-source vulnerability concentrates in western Michigan for short-lead customization, with CAL 117/133 testing backlog extending project timelines. Distribution runs through dealer networks for standard chairs and tables, while direct manufacturer portals compress procurement timelines for modular systems in high-velocity construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national fast-casual chains with multi-location rollout schedules, fragmenting procurement authority previously held by regional dealer networks.
For Market Incumbents: Secure GREENGUARD Gold certification to defend placement in healthcare-adjacent foodservice against emerging indoor air quality mandates. Anchor captive upholstery craft capacity through apprenticeship pipelines or acquisition of distressed Quebec manufacturers, as commercial sewing talent scarcity threatens output expansion. For New Entrants and Emerging Players: Anchor in Texas and Florida construction corridors where permit velocity rewards rapid-turn procurement through direct-to-operator digital portals. Target modular banquette systems for event-flexible dining rooms, penetrating the acoustic retrofit wave with reconfigurable seating platforms that adapt from two-top to communal configurations. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence across state-level chemical disclosure requirements fragments compliance standards and rewards multi-certification capacity. Monitor CAL 117/133 testing queue length as inflection indicator for pricing power shifts between certified and non-certified supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| GREENGUARD Gold Certification Investment | Captures healthcare-adjacent foodservice placement as indoor air quality standards tighten across California and emerging state jurisdictions. |
| Modular Banquette System Development | Addresses operator demand for event-flexible dining rooms in competitive urban fast-casual markets. |
| Apprenticeship Pipeline for Upholstery Craft | Mitigates commercial sewing talent scarcity constraining high-cycle contract seating output expansion. |
| Direct-to-Operator Digital Portal Launch | Compresses procurement timelines for Texas and Florida construction corridors where permit velocity concentrates demand. |
| Proprietary Polymer Formulation R&D | Defends outdoor resin furniture margins against propylene and polyethylene feedstock volatility through UV stability and stackability differentiation. |
Study Parameters
Operator-level perspectives from fast-casual chain procurement directors, fine dining concept developers, furniture dealer network principals, and California Bureau compliance officers anchored the qualitative base. Primary interview data triangulated against EPA formaldehyde emission filings, California Title 24 construction permit databases, customs records for hardwood and textile imports, and SEC 10-K disclosures from listed furniture manufacturers. Bottom-up unit economics across product type, material, and end-use segments reconciled with top-down construction spending and foodservice establishment growth projections.
Sensitivity analysis tested forecast robustness across polymer feedstock price bands, certification queue length scenarios, and regional construction permit velocity variations over the projection horizon. Segmentation modeling incorporated product type, material grade, end-use format, and geographic regulatory cluster dimensions. CAGRs derived from installation base turnover rates, new construction furniture intensity ratios, and replacement cycle compression in high-turn fast-casual environments. Industry-specific inputs included CAL 117/133 certification throughput capacity and skilled upholstery craft workforce recovery trajectories.
Material uncertainties — pandemic-era workforce exit persistence, state-level chemical disclosure fragmentation, and petrochemical supply disruption recurrence — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization stability and construction permit velocity sustainability. Practitioners should keep alternative scenarios live as California Bureau testing capacity and emerging state flammability standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
Smart Hospitality Management Market