
 Tech Savvy Hotel Chains Market | 2026-2036
Tech Savvy Hotel Chains Market Size, Share, and Industry Trends Forecast 2026-2036
Tech Savvy Hotel Chains Market Analytics
The United Arab Emirates is narrowing its competitive gap with legacy hospitality markets through sovereign wealth-backed smart city developments and technology-forward hotel clusters. Marriott International leverages extensive loyalty program data to sustain personalized digital guest experiences across its portfolio. Hilton Worldwide anchors its growth strategy in proprietary mobile key and room automation platforms that reduce front-desk dependency.
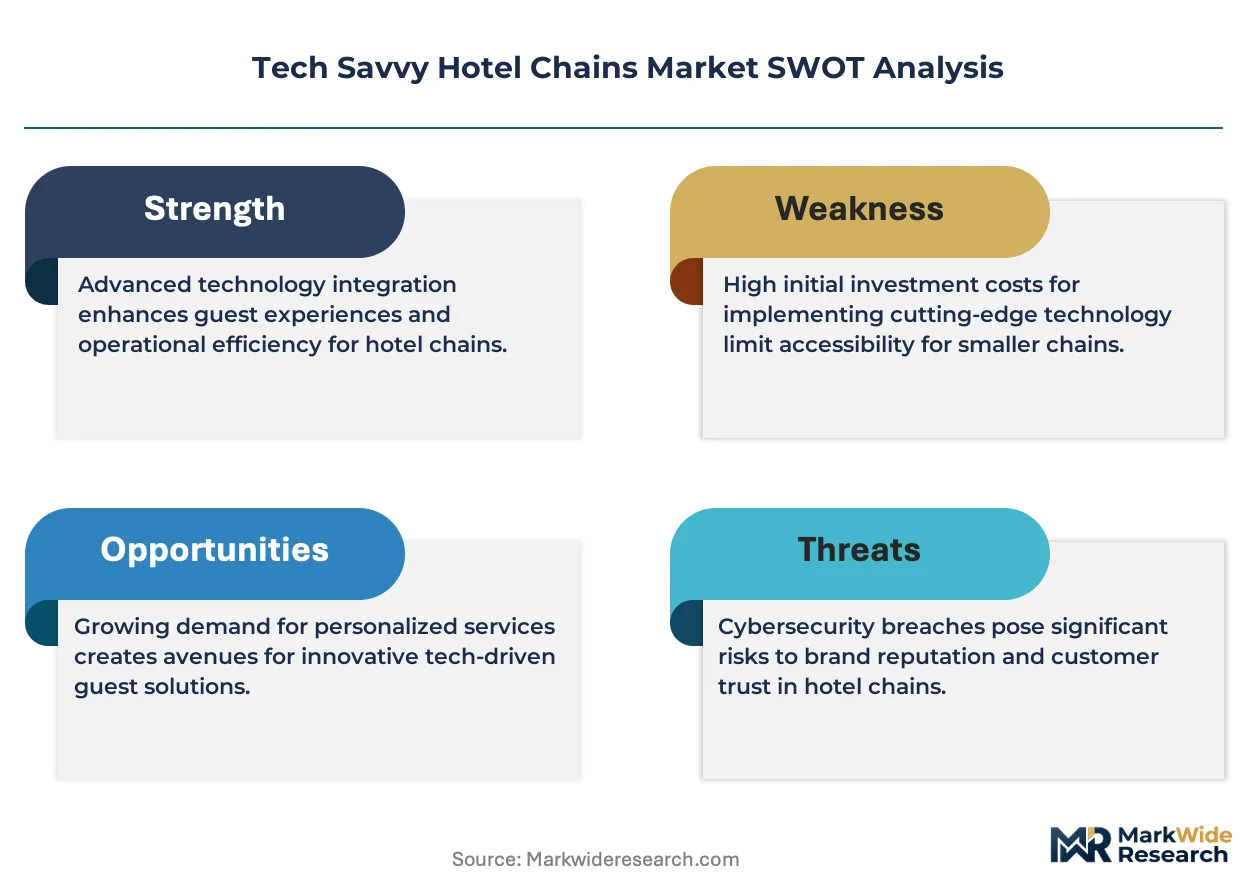
Tech savvy hotel chains integrate IoT-enabled room controls, cloud-based property management systems, and AI-driven guest service interfaces to optimize operational efficiency and personalize stays. These establishments deploy mobile check-in, smart room features, and Wi-Fi solutions as core infrastructure rather than ancillary amenities. The technology dimension shows smart room features capturing premium pricing power while mobile check-in becomes baseline expectation across budget and extended stay segments. Service type segmentation reveals luxury and boutique categories driving margin expansion through bespoke digital experiences, whereas budget chains compete on scalable Wi-Fi solutions and automated operational workflows.
The EU AI Act and GDPR framework in Europe, alongside the FTC's data security enforcement in the United States, compel hotel chains to embed privacy-by-design architecture into guest-facing technology stacks. China's SAMR and MIIT set interoperability standards for smart building systems that influence supplier selection for international chains operating in Asia. India's TRAI guidelines on data localization add compliance layers for cloud-based property management platforms serving domestic properties. Stakeholders must weigh regulatory fragmentation against the cost of unified global technology platforms.
Market Dynamics
EU AI Act and GDPR compliance requirements are forcing hotel chains to re-architect guest data infrastructure, creating a bifurcation between privacy-forward operators and those facing operational friction.
Growth Catalysts
- GDPR and EU AI Act mandates:European regulatory pressure accelerates investment in privacy-by-design property management systems, creating upgrade cycles across legacy portfolios.
- Business traveler preference for mobile-first stays:Corporate booking platforms now weight mobile check-in and smart room features as selection criteria, pulling chains toward technology investment.
- IoT-enabled operational efficiency:Cloud-based property management systems reduce front-desk labor intensity while enabling predictive maintenance across room inventories.
Market Restraints
- Cloud infrastructure cost volatility:Energy price fluctuations and data center concentration in Northern Virginia and Frankfurt inflate operational technology budgets unpredictably.
- Smart hardware supplier concentration:IoT room control modules depend on a limited base of Chinese and Taiwanese component manufacturers, creating procurement vulnerability.
- Interoperability fragmentation:China's SAMR and MIIT standards diverge from European CE marking requirements, forcing dual certification paths for global chains.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea Development Authority mandates for technology-integrated hospitality create greenfield deployment opportunities without legacy system burden.
- AI-driven concierge convergence:Natural language processing and property management system APIs enable automated guest service interfaces that reduce labor cost per occupied room.
- India's data localization requirements:TRAI guidelines on domestic data storage create first-mover advantage for chains establishing India-specific cloud infrastructure ahead of enforcement tightening.
Industry Challenges
- Cybersecurity talent scarcity:Hotel chains compete with financial services and technology sectors for specialists capable of securing guest-facing IoT networks and payment systems.
- Legacy property management system integration:Decades-old on-premise software architectures resist API connectivity with modern mobile check-in and smart room platforms, requiring costly middleware development.
- GDPR compliance timeline compression:European regulators reduce grace periods for AI Act implementation, forcing simultaneous technology procurement and staff retraining across multi-property portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tech Savvy Hotel Chains Market |
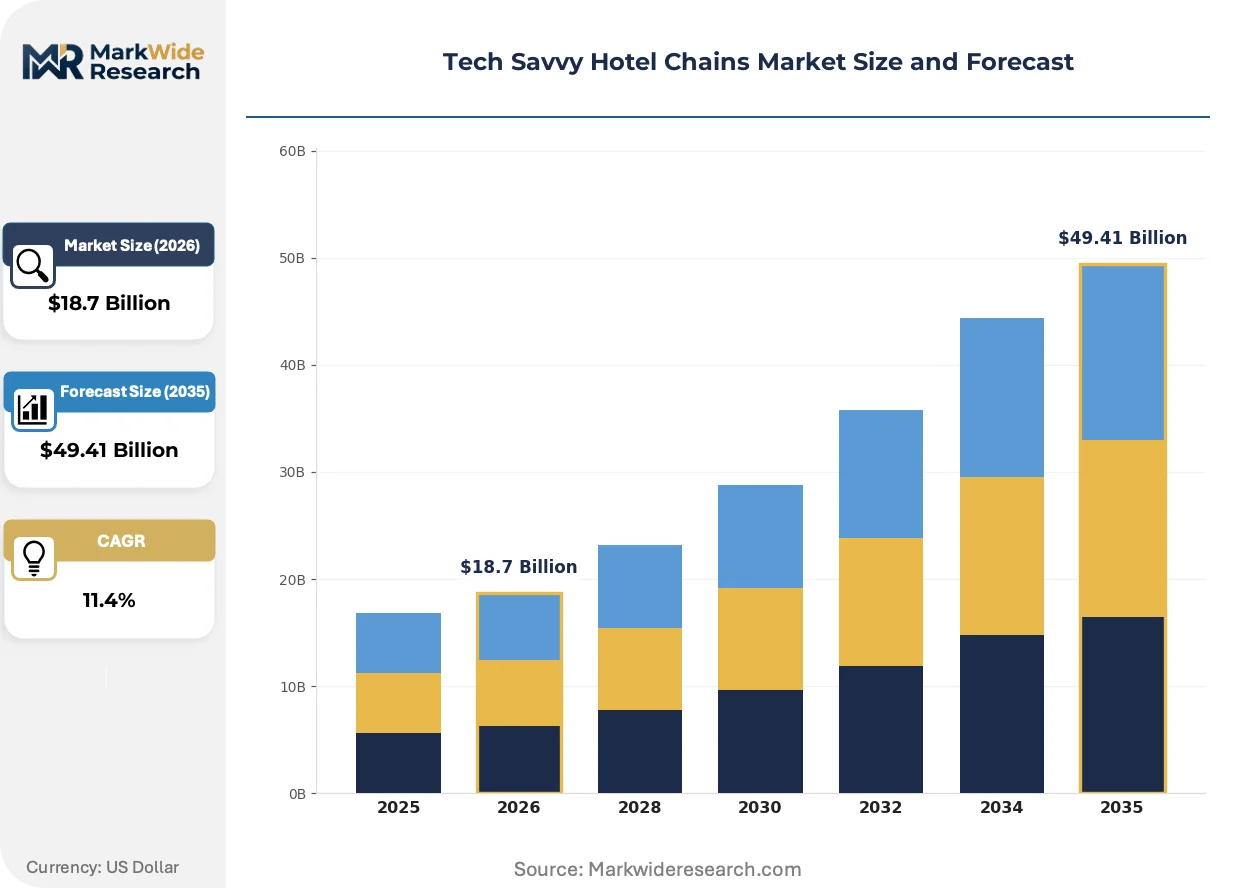
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury, Boutique, Extended Stay, Budget Technology: Mobile Check-In, Room Automation, Wi-Fi Solutions, Smart Room Features Customer Type: Business Travelers, Vacationers, Groups, Conference Attendees End User: Corporate Clients, Leisure Guests, Travel Agencies, Online Booking Platforms |
| Companies Covered | InterContinental Hotels Group, Oracle Hospitality, Marriott International, Mews, Cloudbeds, Hilton Worldwide, Jin Jiang International, Amadeus Hospitality, Accor Hotels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tech Savvy Hotel Chains Market Evolving Landscape
Guest-facing technology is shifting from amenity to infrastructure, with mobile key deployment and room automation now baseline expectations rather than differentiation points.
Voice-activated room controls are collapsing the interface layer between guests and property systems. Hilton and Marriott franchisees deploy Amazon Alexa and Google Nest Hub integrations at scale across premium and select-service portfolios. This compression eliminates physical switch panels and remote controls, reducing hardware procurement and maintenance while generating behavioral data streams for service personalization.
EU AI Act algorithmic transparency requirements are reshaping how chains deploy recommendation engines and dynamic pricing models. European properties must now document automated decision-making logic for guest-facing AI, including chatbots and personalized marketing systems. Luxury and boutique segments face the steepest compliance burden given their reliance on bespoke guest profiling.
Corporate travel managers now mandate sustainability data disclosure alongside technology amenities in RFP processes. Large enterprise accounts in the United States and Germany require proof of energy-efficient smart building systems and carbon reporting through cloud-based property management platforms. This procurement pattern favors chains with integrated IoT metering and automated environmental certification documentation.
Tech Savvy Hotel Chains Market Segmentation
Technology deployment patterns in hospitality diverge sharply across service tiers and guest profiles. Chains must align capital allocation with segment-specific digital maturity and pricing power.
Service Type:
Cost tier determines technology investment intensity and payback horizons across property portfolios.
- Luxury:Properties deploy fully integrated IoT ecosystems with predictive personalization engines and biometric access control. Demand concentrates in Dubai, Miami, and Singapore where sovereign wealth and ultra-high-net-worth visitation justify capital-intensive smart room infrastructure.
- Boutique:Curated technology stacks emphasize design-forward interfaces and localized app experiences rather than standardized enterprise platforms. Independent operators in Lisbon, Mexico City, and Melbourne differentiate through bespoke digital storytelling and neighborhood-integrated service apps.
- Extended Stay:Kitchen automation, connected appliance monitoring, and long-term guest preference memory systems dominate capex allocation. Corporate housing contracts in Houston, Bangalore, and Frankfurt drive standardization over customization.
- Budget:Scalable Wi-Fi backbone and automated check-in kiosks constitute the technology floor. Operators in Warsaw, São Paulo, and Jakarta compete on connectivity reliability and labor substitution rather than experiential innovation.
Luxury holds installed capacity. Boutique is rotating up the share rankings.
Technology:
Application maturity separates baseline infrastructure from revenue-generating differentiators in guest-facing systems.
- Mobile Check-In:Digital key distribution and bypass lobby protocols now function as table stakes across all service tiers. Hilton's proprietary platform and Marriott's Bonvoy app set interoperability benchmarks that franchisees must adopt or risk corporate account displacement.
- Smart Room Features:Voice-activated climate, lighting, and entertainment controls command measurable rate premiums in urban gateway markets. Deployment concentrates in newly constructed or fully renovated assets where electrical infrastructure supports sensor density.
- Room Automation:Occupancy-based energy management and predictive maintenance alerts reduce operational expenditure per key. European properties face GDPR complexity when automation systems capture guest behavioral data for efficiency optimization.
- Wi-Fi Solutions:Bandwidth scalability and low-latency connectivity support streaming, video conferencing, and IoT device density. Budget chains treat this as the sole technology line item, while luxury properties embed it within comprehensive digital infrastructure.
Mobile Check-In anchors current deployment volumes. Smart Room Features is climbing the fastest.
Customer Type:
Volume concentration and technology utilization rates vary dramatically across guest motivation profiles.
- Business Travelers:Mobile-first workflows, seamless expense integration, and loyalty program connectivity drive selection criteria. Corporate travel managers at technology and financial services firms mandate digital check-in and room control capabilities in RFP processes.
- Vacationers:Leisure guests prioritize streaming bandwidth, mobile concierge access, and social media-optimized room aesthetics. Family segments in Orlando, Bali, and the Canary Islands demand multi-device connectivity and parental control features.
- Groups:Wedding and reunion planners require group billing automation, mass check-in protocols, and shared space reservation systems. Technology investment focuses on back-of-house efficiency rather than individual room innovation.
- Conference Attendees:Hybrid event infrastructure, broadcast-quality in-room video, and seamless platform integration dominate requirements. Convention hotels in Las Vegas, London, and Singapore compete on audiovisual latency and redundant connectivity.
Business Travelers sustain technology ROI. Vacationers is gaining share fastest.
End User:
Procurement channel influence shapes technology specification and deployment prioritization across the value chain.
- Corporate Clients:Managed travel programs negotiate enterprise rates contingent on standardized digital amenities and consolidated reporting. Multinational accounts in Germany, the United States, and Japan require ESG data disclosure through cloud-based property management platforms.
- Leisure Guests:Direct booking incentives and personalized pre-arrival communication build loyalty independent of online travel agency intermediation. Mobile app engagement drives ancillary revenue capture in resort and urban leisure properties.
- Travel Agencies:Consortium and agency partners filter property selection through technology amenity databases. American Express and Virtuoso advisors prioritize mobile key availability and chatbot concierge responsiveness for high-value client placement.
- Online Booking Platforms:Expedia and Booking.com algorithmic ranking factors increasingly weight verified guest reviews mentioning technology functionality. Properties with systematic mobile check-in complaints face search result demotion.
Corporate Clients hold contract value concentration. Online Booking Platforms is rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart city investments and sovereign wealth deployment concentrate technology-forward hospitality development in specific national markets. Regulatory divergence across data protection regimes fragments deployment strategies for multinational chains. Premium property pipelines in the United States, China, United Arab Emirates, Germany, and Saudi Arabia absorb the majority of capital allocated to guest-facing digital infrastructure.
United States
Corporate travel managers at technology and financial services firms mandate mobile check-in and smart room capabilities in procurement processes. The FTC enforces data security standards that compel privacy-by-design architecture in guest-facing systems. Miami and New York City anchor luxury development where biometric access control and predictive personalization engines command rate premiums.
China
Domestic business traveler volume and outbound tourism recovery drive demand for integrated mobile key platforms. SAMR and MIIT interoperability standards for smart building systems influence supplier selection for international chains operating domestically. Shanghai and Shenzhen hotel clusters deploy voice-activated room controls at scale across newly constructed assets.
United Arab Emirates
Sovereign wealth-backed developments in Dubai and Abu Dhabi mandate technology-integrated hospitality without legacy system burden. MOHAP data governance frameworks align with broader federal digital transformation objectives. The Dubai Design District and Expo City clusters concentrate boutique properties with curated technology stacks emphasizing localized app experiences.
Germany
Corporate housing contracts in Frankfurt and Munich drive standardization in extended-stay technology infrastructure. GDPR and EU AI Act compliance timelines compress procurement cycles for algorithmic transparency in recommendation engines. Berlin boutique operators differentiate through bespoke digital storytelling rather than standardized enterprise platforms.
Saudi Arabia
NEOM and Red Sea Development Authority mandates for technology-integrated hospitality create greenfield deployment opportunities. SFDA data protection guidelines add compliance layers for guest health monitoring systems in wellness-focused properties. The Kingdom's northwest corridor attracts chains establishing cloud infrastructure ahead of enforcement tightening.
Tech Savvy Hotel Chains Market Competitive Landscape
Global hospitality conglomerates and specialized property technology providers split the market between integrated platform control and modular service delivery. Consolidation pressure favors operators with captive loyalty program data and proprietary mobile infrastructure. Three archetypes dominate: legacy chains with in-house technology stacks, franchise-heavy networks relying on vendor ecosystems, and cloud-native hospitality software platforms. Competitive moves center on API consolidation to reduce middleware complexity and direct booking incentives that bypass online travel agency intermediation.
Within the integrated-chain archetype, Marriott International and Hilton Worldwide exemplify operators leveraging extensive loyalty program databases to sustain personalized digital guest experiences across dispersed portfolios. Oracle Hospitality and Amadeus Hospitality occupy positions as vendor-agnostic platform providers serving franchise operators without captive technology development. Cloudbeds and Mews represent cloud-native alternatives targeting independent boutique properties with modular deployment options that reduce capital intensity.
| Leading Market Players |
|---|
| InterContinental Hotels Group |
| Oracle Hospitality |
| Marriott International |
| Mews |
| Cloudbeds |
| Hilton Worldwide |
| Jin Jiang International |
| Amadeus Hospitality |
| Accor Hotels |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors linking Shenzhen and Los Angeles transmit cost volatility through IoT hardware procurement, compressing margins for budget chains while enabling premium operators to capture rate spreads through smart room feature bundling.
Pricing Analysis
GDPR and EU AI Act compliance mandates dictate the pricing tier structure across the market, forcing privacy-by-design architecture investments that stratify costs across premium, standard, and economy property tiers. Certification level for data protection infrastructure and brand premium for loyalty program integration serve as primary price differentiation drivers. Pricing pressure stems from cloud infrastructure cost volatility in Northern Virginia and Frankfurt data center clusters. Budget chains exhibit highest price sensitivity, while luxury properties maintain pricing power through experiential smart room premiums.
Supply Chain Analysis
Extended payment terms from Taiwanese and Chinese component manufacturers now stretch to 90-120 days, straining working capital for property technology integrators deploying at scale. IoT room control modules draw from concentrated manufacturing bases in Taiwan, China, and South Korea. Critical dependencies include semiconductor chipsets, sensor arrays, and wireless communication modules. Single-source vulnerability in Chinese component suppliers creates procurement risk amid geopolitical friction. Distribution runs through hospitality technology integrators and direct OEM relationships with major chain procurement divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property management system SaaS subscriptions and predictive maintenance service contracts expand faster than hardware deployment, creating recurring revenue attach opportunities that outperform capital equipment sales cycles.
For Market Incumbents: Insulate loyalty program data assets through API consolidation that reduces middleware complexity and captive cloud infrastructure investment. Defend against cloud-native hospitality software platforms by embedding proprietary mobile key architecture deeper into franchisee operating standards. Vertical integration into guest-facing IoT network security addresses cybersecurity talent scarcity threatening operational continuity. For New Entrants and Emerging Players: Establish a beachhead in India's extended-stay corporate housing segment ahead of TRAI data localization enforcement tightening. Target boutique properties in Lisbon, Mexico City, and Melbourne with modular deployment options that reduce capital intensity versus enterprise platform replacement. Go-to-market leverage rests on design-forward interface customization absent from standardized chain technology stacks. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency requirements reshape the acquisition landscape, elevating properties with documented automated decision-making infrastructure above legacy portfolios facing compliance retrofit costs. Long-term viability favors operators with captive loyalty data and India-specific cloud infrastructure. Target acquisition archetype: cloud-native hospitality platforms with modular API architecture. Signal to watch: corporate travel manager RFP weighting shifts toward ESG data disclosure through integrated IoT metering.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Architecture Deployment | GDPR and EU AI Act compliance creates competitive moat for early adopters in European portfolios. |
| Proprietary Mobile Key Platform Expansion | Hilton and Marriott franchisee standards pull vendor ecosystems toward interoperability benchmarks. |
| India-Specific Cloud Infrastructure Buildout | TRAI data localization guidelines reward first-mover chains establishing domestic server capacity. |
| AI-Driven Concierge Convergence | Natural language processing APIs reduce labor cost per occupied room through automated guest service interfaces. |
| NEOM Greenfield Technology Integration | Saudi giga-project mandates eliminate legacy system burden for technology-forward hospitality deployment. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hotel chain technology officers, property management system vendors, and corporate travel procurement managers; and secondary validation through hospitality technology trade filings, cloud infrastructure capex disclosures, and regulatory compliance databases. Bottom-up property-level technology deployment estimates triangulated against top-down chain-level capital allocation disclosures. Primary fieldwork captured franchisee technology adoption friction and interoperability constraints across Hilton, Marriott, and independent boutique portfolios.
Forecast inputs span service type segmentation across luxury, boutique, extended-stay, and budget tiers; technology deployment patterns including mobile check-in, smart room features, room automation, and Wi-Fi infrastructure; and customer type utilization rates for business travelers, vacationers, groups, and conference attendees. CAGRs derive from technology replacement cycle analysis and regulatory compliance-driven upgrade timelines. Industry-specific inputs include corporate travel manager RFP weighting shifts and sovereign wealth project pipeline commitments.
Stress conditions across cloud infrastructure cost volatility, Chinese component supply disruption, and EU AI Act enforcement timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation pacing. Macroeconomic contraction in corporate travel, accelerated GDPR enforcement, or breakthrough hospitality automation platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Catering Services Market