
 Europe Casino Management Market | 2026-2036
Europe Casino Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Casino Management Market Foresight
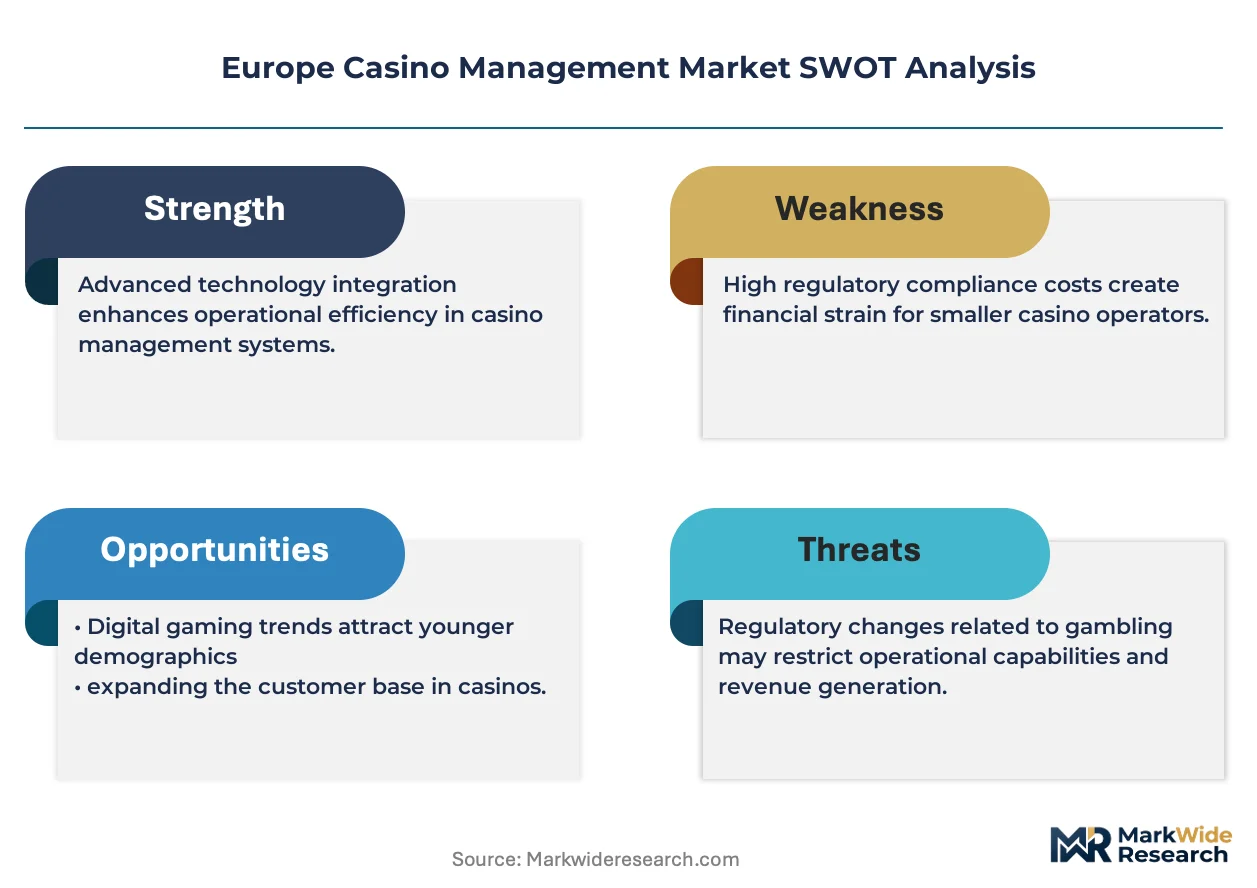
GDPR is hardening data residency requirements for player tracking and loyalty systems, forcing operators to rebuild on-premises data architectures. Novomatic AG leverages its manufacturing scale to supply integrated hardware-software bundles across Central European casinos. International Game Technology PLC anchors its competitive position through extensive patent portfolios in slot management systems.
Casino management systems encompass software platforms that monitor gaming floor activity, optimize table and slot utilization, manage player loyalty programs, and enforce regulatory compliance through real-time audit logging. These systems typically integrate RFID-enabled chips, biometric authentication modules, and centralized reporting dashboards to streamline operations across multi-property portfolios. Slot management and payment processing solutions lead current deployment value, while cloud-based deployment models are expanding fastest as operators seek to reduce capital expenditure on server infrastructure. Customer relationship management modules capture disproportionate margin pools due to recurring subscription structures and high switching costs for integrated loyalty databases.
EU member state gambling regulators, the EU AI Act framework, and GDPR compliance mandates collectively determine product certification pathways and cross-border service eligibility for casino technology vendors. EGBA standards and national licensing boards in jurisdictions such as Malta and the United Kingdom impose additional technical auditing requirements on gaming software. Stakeholders must weigh the pace of cloud migration against evolving data sovereignty rules that could fragment platform architectures across national boundaries.
Market Dynamics
The EU AI Act's algorithmic audit mandates are forcing casino operators to rebuild their gaming floor architectures around explainable decision logs and real-time compliance telemetry.
Growth Catalysts
- GDPR data residency mandates:Operators must localize player tracking databases, driving replacement demand for on-premise server infrastructure across German and Italian casino networks.
- RFID-enabled chip systems:Table game operators deploy contactless wagering technology to accelerate bet resolution and reduce cash-handling labor costs.
- Integrated resort expansion:Multi-property operators in the United Kingdom unify loyalty programs and floor analytics across regional casino portfolios.
Market Restraints
- Cloud sovereignty fragmentation:National data localization laws prevent standardized SaaS deployment across EU member states, inflating platform engineering costs.
- Semiconductor supply concentration:Gaming hardware manufacturers depend on concentrated Asian foundry capacity for RFID chipsets and biometric sensors.
- Legacy system technical debt:Decades-old slot machine protocols lack API compatibility with modern analytics platforms, constraining integration velocity.
Strategic Opportunities
- Central European greenfield casinos:Poland and Romania license new integrated resorts requiring full-stack management system deployments without legacy migration burdens.
- Biometric authentication convergence:Facial recognition and behavioral analytics merge to enable frictionless player entry and automated responsible gaming interventions.
- EGBA technical standard harmonization:Unified certification pathways across Malta, Gibraltar, and the United Kingdom reduce vendor compliance duplication costs.
Industry Challenges
- Cybersecurity engineering talent scarcity:Operators struggle to recruit specialists capable of securing real-time payment processing networks against ransomware targeting.
- Legacy protocol integration complexity:Proprietary slot communication standards from 1990s-era manufacturers resist interoperability with cloud-native management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Casino Management Market |
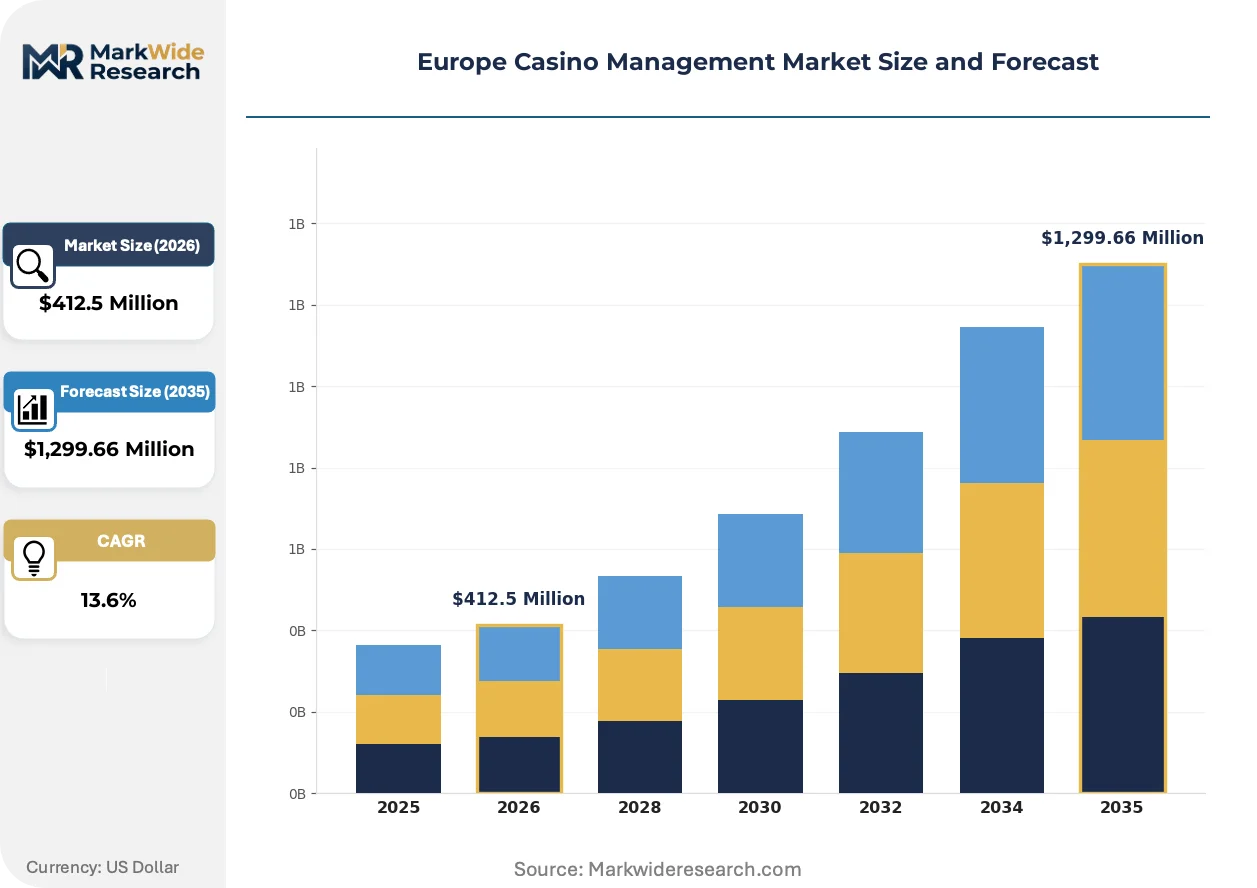
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,299.66 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Table Management, Slot Management, Customer Relationship Management, Payment Processing Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile End User: Casinos, Online Gaming, Sports Betting, Lottery Operators Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | Amatic Industries GmbH, Euro Games Technology Ltd, International Game Technology PLC, Advansys d.o.o., Ensico CMS d.o.o., Novomatic AG, Decart Ltd, Synectics plc, Apex Gaming Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Casino Management Market Shifts & Advancements
Cloud-native architectures are displacing on-premise server farms as operators prioritize operational flexibility over capital-intensive infrastructure ownership. Three developments dominate vendor R&D roadmaps.
Edge computing nodes deployed directly on gaming floors is unifying transaction processing with real-time player behavior analytics. Integrated resort operators in Italy and Spain pilot these distributed architectures to eliminate latency between bet placement and loyalty point accrual. The technology compresses data center footprints while satisfying GDPR data residency requirements through localized processing.
REACH substance restrictions and EU AI Act algorithmic transparency rules now govern gaming hardware certification pathways. Slot machine manufacturers must document supply chain chemical compliance and submit decision-tree logic for regulatory pre-approval. German state gambling boards enforce these dual mandates most stringently, delaying product launches by six to twelve months relative to other European jurisdictions.
Subscription-based software licensing displaces perpetual purchase contracts across mid-tier casino operators. Vendors bundle floor analytics, player relationship management, and compliance reporting into recurring revenue packages. This shift concentrates most visibly in the United Kingdom, where private equity-backed casino groups prioritize predictable operating expenditures over capital deployment flexibility.
Europe Casino Management Market Segmentation
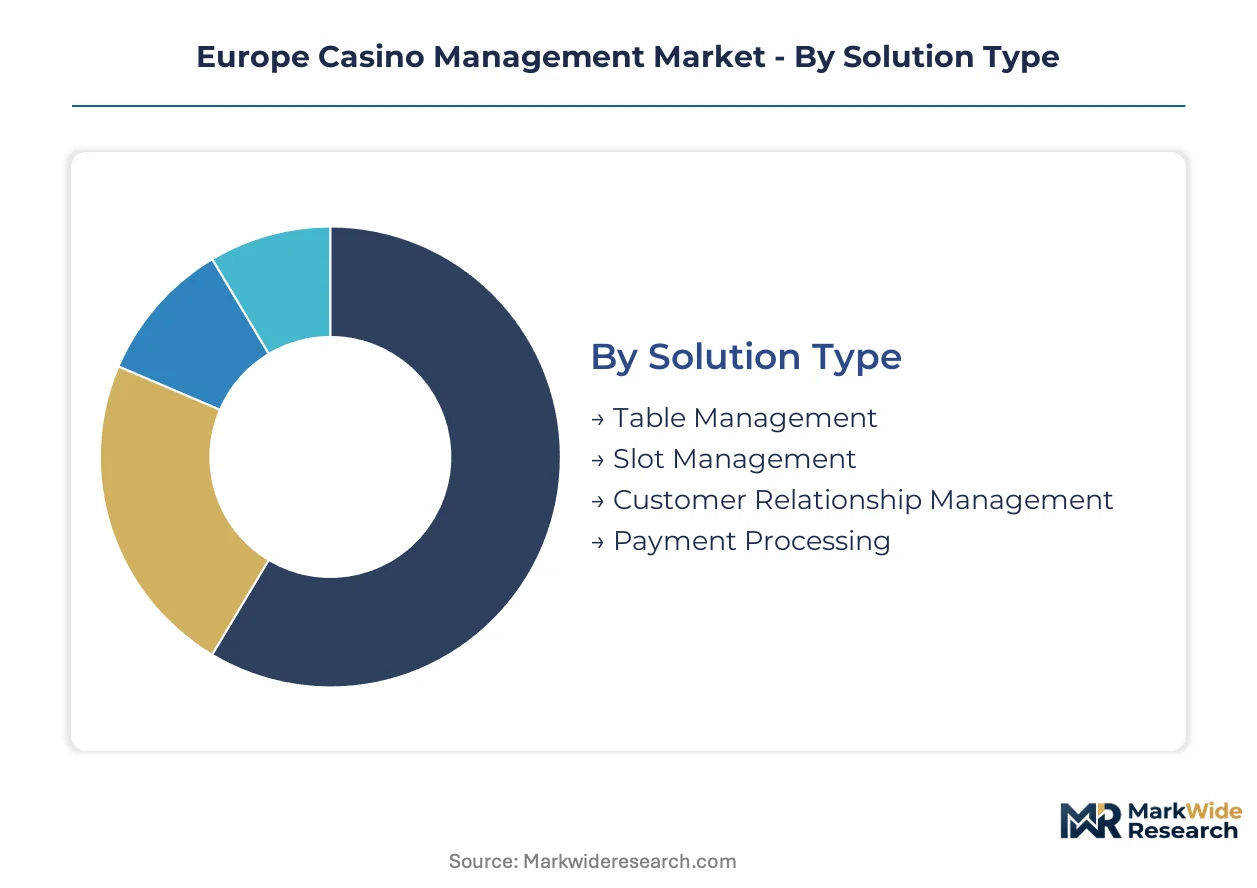
Casino management systems fragment across solution architectures, infrastructure models, and operator types. Each segment carries distinct compliance burdens under the EU AI Act and national gambling commission frameworks.
Solution Type:
GDPR data residency rules and EGBA technical standards impose divergent certification timelines across software modules, with real-time audit logging requirements heaviest on transaction-heavy systems.
- Slot Management:Hardware-software bundles track machine performance, player session duration, and jackpot events through embedded RFID telemetry. German state gambling boards mandate six-to-twelve-month pre-approval cycles for these systems, slowing vendor deployment velocity across Central European casino networks.
- Payment Processing:Real-time transaction engines integrate with banking networks and digital wallet providers to accelerate cashless wagering. Italian integrated resort operators prioritize PCI-DSS Level 1 certification alongside GDPR compliance, driving replacement demand for legacy chip-and-PIN infrastructure.
- Table Management:Chip tracking and dealer performance analytics optimize pit floor utilization.
- Customer Relationship Management:Loyalty databases capture player value metrics and behavioral triggers for targeted marketing.
Slot Management sits at the top of the volume ranking, with Payment Processing climbing the fastest.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models, with hybrid architectures commanding premium engineering fees for sovereignty-compliant configurations.
- Cloud-Based:SaaS platforms deliver floor analytics and compliance reporting through subscription contracts. United Kingdom private equity-backed casino groups favor these arrangements to preserve balance sheet flexibility, though German data localization laws force redundant in-country server deployments.
- On-Premises:Dedicated server farms maintain complete data custody within operator facilities. Legacy installations across Italian and Spanish casino networks resist migration due to sunk infrastructure costs and staff technical competencies.
- Hybrid:Sensitive player data remains local while analytics processing shifts to distributed cloud nodes.
- Mobile:Smartphone-accessible management dashboards enable executive oversight of multi-property portfolios.
On-Premises retains the largest installed base, though Cloud-Based deployments are expanding most quickly as vendors localize processing to satisfy GDPR mandates.
End User:
Application intensity varies by regulatory scrutiny depth, with physical casinos facing the most intensive algorithmic audit requirements under EU AI Act implementation.
- Casinos:Integrated resort operators deploy full-stack management ecosystems spanning slots, tables, loyalty, and payments. Multi-property groups in the United Kingdom and Germany unify these systems across regional portfolios to centralize procurement and compliance reporting.
- Sports Betting:Real-time odds management and in-play wagering platforms require sub-second latency architectures.
- Online Gaming:Virtual casino environments demand identity verification and geolocation compliance modules.
- Lottery Operators:State-contracted distributors prioritize fraud detection and retail network management capabilities.
Casinos dominate absolute spending, with Sports Betting gaining share fastest as mobile wagering liberalization spreads across EU member states.
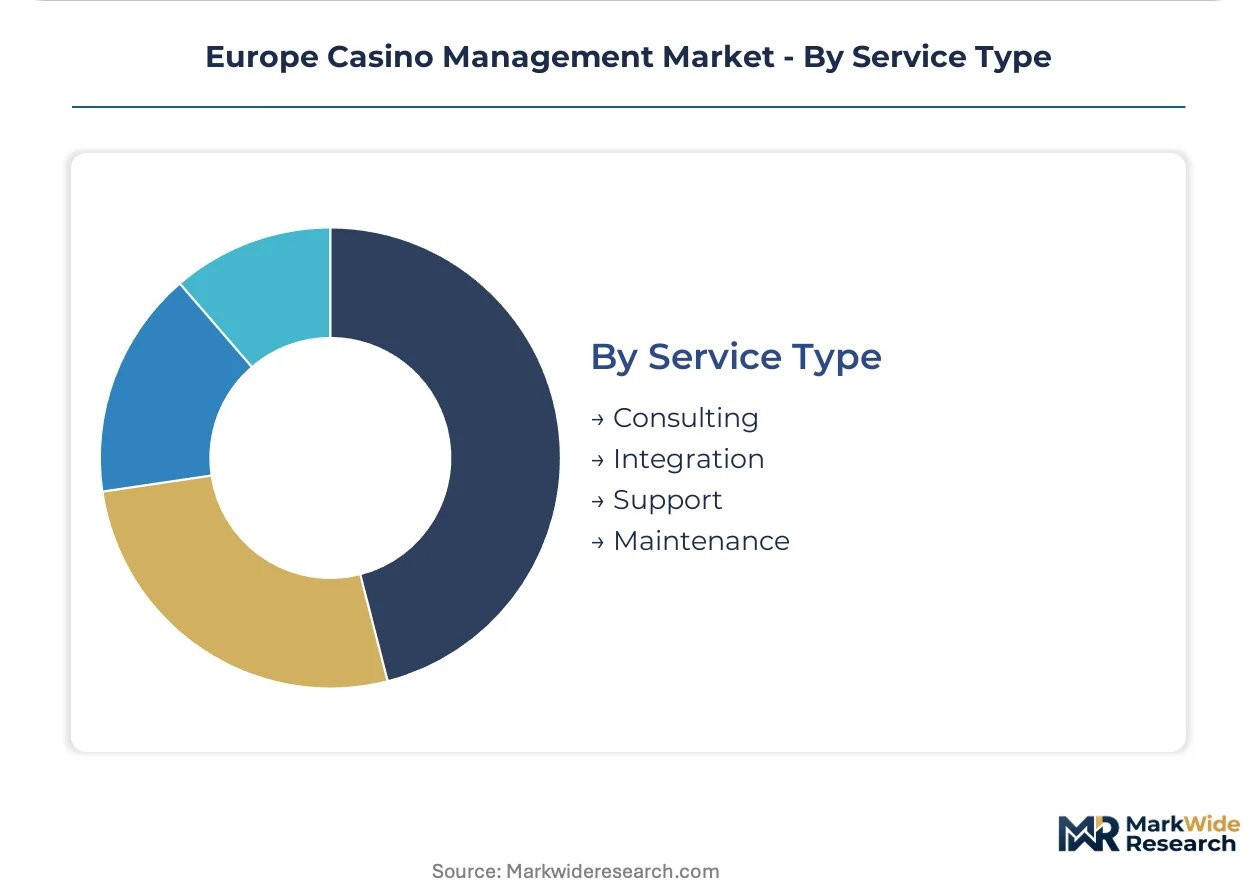
Service Type:
Margin concentration follows recurring revenue predictability, with maintenance contracts capturing the most stable cash flows as integration projects remain lumpy and consulting engagement-bound.
- Maintenance:Ongoing software updates, security patching, and regulatory compliance refresh cycles lock in long-term vendor relationships. Subscription structures here resist competitive displacement due to embedded operational knowledge and staff training investments.
- Integration:Legacy system migration and API connectivity projects bridge proprietary slot protocols with modern analytics platforms. Polish and Romanian greenfield casinos bypass these costs entirely through full-stack fresh deployments.
- Consulting:Regulatory readiness assessments and floor optimization studies deliver project-based fees.
- Support:Help desk and field engineering services resolve operational incidents under SLA contracts.
Maintenance commands the steadiest revenue streams, while Integration shows the steepest expansion trajectory as legacy overhaul demand concentrates in Germany, Italy, and Spain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent clusters in Vienna and London anchor the continent's casino technology development. These workforce concentrations support both legacy system overhauls and greenfield integrated resort deployments across Central and Southern Europe.
Germany
State gambling boards in Bavaria and North Rhine-Westphalia enforce stringent six-to-twelve-month pre-approval cycles for slot management systems. The EU AI Act's algorithmic transparency mandates require operators to rebuild gaming floor architectures around explainable decision logs. Frankfurt's financial technology corridor supplies payment processing engineering talent to casino operators modernizing cashless wagering infrastructure.
United Kingdom
Private equity-backed casino groups prioritize subscription-based software licensing to preserve balance sheet flexibility. The UK Gambling Commission mandates real-time audit logging for algorithmic gaming systems under national licensing frameworks. London's integrated resort operators unify loyalty programs and floor analytics across regional casino portfolios spanning Greater London and the Midlands.
Italy
Legacy casino infrastructure in Milan and Rome undergoes digital overhaul to satisfy GDPR data residency requirements for player tracking databases. Italian integrated resort operators pilot edge computing nodes to eliminate latency between bet placement and loyalty point accrual. The country's state gambling regulator imposes PCI-DSS Level 1 certification alongside GDPR compliance for payment processing replacements.
Spain
Barcelona and Madrid casino operators deploy cloud-native architectures with localized processing to satisfy data sovereignty rules. Spanish gambling authorities align technical auditing requirements with EGBA standards to reduce vendor compliance duplication costs. The Mediterranean cruise ship casino hub in Barcelona drives demand for compact, multi-property management system deployments.
Poland
New integrated resort licenses in Warsaw and Krakow require full-stack management system deployments without legacy migration burdens. Polish operators bypass integration costs entirely through greenfield fresh deployments spanning slots, tables, and loyalty systems. The country's national gambling regulator adopts EU AI Act frameworks ahead of neighboring jurisdictions to attract technology vendor investment.
Europe Casino Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, software platforms, and integrated service bundles. Market structure consolidates around three strategic tiers: manufacturing-anchored conglomerates with captive distribution networks, software-centric specialists monetizing through recurring subscription structures, and regional system integrators serving national casino operators. Dominant competitive moves include portfolio diversification into adjacent payment processing modules and geographic expansion through EGBA certification harmonization.
Within the manufacturing-anchored tier, Novomatic AG and International Game Technology PLC exemplify scale-driven competitive positioning. Novomatic AG leverages its Austrian manufacturing base to supply integrated hardware-software bundles across Central European casino networks. International Game Technology PLC anchors its market presence through extensive patent portfolios in slot management systems. Euro Games Technology Ltd and Amatic Industries GmbH occupy positions within the regional specialist tier, serving national operators with localized compliance expertise.
| Leading Market Players |
|---|
| Amatic Industries GmbH |
| Euro Games Technology Ltd |
| International Game Technology PLC |
| Advansys d.o.o. |
| Ensico CMS d.o.o. |
| Novomatic AG |
| Decart Ltd |
| Synectics plc |
| Apex Gaming Technology |
| Others |
Supply & Pricing Matrix
GDPR data residency mandates from German and Italian regulators are forcing casino operators to rebuild on-premise server architectures, compelling hardware vendors to localize manufacturing footprints and inflating platform engineering costs across tiered service bundles.
Pricing Analysis
Bundled hardware-software subscriptions from Novomatic AG and International Game Technology PLC dominate enterprise accounts, while unbundled module licensing persists among mid-tier operators. Price differentiation hinges on EU AI Act certification grade and volume scale across multi-property portfolios. Cost compression in cloud-native tiers is intensifying because German data localization laws force redundant in-country server deployments. Mid-tier casino groups in Poland and Romania exhibit the highest price sensitivity, whereas United Kingdom private equity-backed operators prioritize predictable operating expenditures over capital deployment flexibility.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and South Korean foundry capacity for RFID chipsets and biometric sensors that power table management systems. Gaming hardware manufacturers draw from concentrated Asian semiconductor supply for embedded telemetry modules and edge computing processors. Tariff exposure on gaming components imported through Rotterdam and Hamburg logistics hubs creates margin pressure for Central European deployments. Distribution runs through Vienna and London engineering clusters that anchor continental technology development and system integration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Casino Management Market functions as a geographic-arbitrage play where Polish and Romanian greenfield deployments bypass German and Italian legacy migration costs entirely.
For Market Incumbents: Cement captive distribution networks across Central European casino networks through integrated hardware-software bundles that lock in long-term maintenance contracts. Novomatic AG's Austrian manufacturing scale anchors this defensive posture against cloud-native entrants. Vertical integration into payment processing modules captures additional margin pools as Italian operators prioritize PCI-DSS Level 1 certification alongside GDPR compliance.
For New Entrants and Emerging Players: Biometric authentication convergence offers a technology-first wedge into United Kingdom and Spanish markets where facial recognition and behavioral analytics enable frictionless player entry. Polish greenfield integrated resorts present the most penetrable geography, requiring full-stack deployments without legacy protocol integration burdens. Lead with edge computing pilot programs that eliminate latency between bet placement and loyalty point accrual.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional system integrators possessing EGBA certification harmonization expertise across Malta, Gibraltar, and the United Kingdom. Long-term viability over a multi-year horizon favors software-centric specialists monetizing through recurring subscription structures rather than hardware-dependent conglomerates. Watch for EU AI Act enforcement intensity as the inflection indicator that accelerates replacement demand for non-compliant legacy architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies slot management, payment processing, and loyalty systems across multi-property portfolios in Germany and Italy. |
| Geographic Expansion | Captures Polish and Romanian greenfield integrated resort licenses requiring full-stack deployments without legacy burdens. |
| Regulatory Certification Investment | Accelerates EU AI Act algorithmic transparency approval and GDPR data residency compliance for German state gambling boards. |
| Strategic Partnership | Aligns with Vienna and London engineering clusters to secure scarce cybersecurity talent for real-time payment networks. |
| Acquisition of Specialist Firm | Consolidates biometric authentication and edge computing capabilities for frictionless player entry systems in Spain. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with casino operations directors, regulatory compliance officers, gaming technology procurement leads, and system integration engineers with secondary validation from EU gambling commission filings, EGBA technical standards documentation, and national licensing board records. Bottom-up property-level deployment estimates triangulated against top-down vendor revenue segmentation across solution types and deployment models.
Historical reference periods anchored the forecast window to established replacement cycles in legacy casino infrastructure, with projections developed across the analysis window using modeled segmentation across solution architecture, deployment model, operator type, and service category. CAGRs derived from slope-intercept regression against technology adoption curves, incorporating GDPR enforcement intensity and EU AI Act implementation timelines as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and continued private equity sponsorship of United Kingdom casino groups; deviation in semiconductor supply chain disruptions or accelerated German data localization requirements would shift deployment velocity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
US Wedding Services Market