
 Smart Hospitality and Coworking Spaces Market | 2026-2036
Smart Hospitality and Coworking Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Hospitality and Coworking Spaces Market Analytics
Buyer concentration among enterprise accounts is expanding as Fortune 500 technology and financial services firms consolidate vendor relationships with fewer managed workspace providers. IWG leverages its geographic density across secondary cities to sustain account stickiness through multi-location contracts. Industrious differentiates by embedding hospitality-grade service layers into its workplace product, while WeWork competes on flexible lease structures and rapid space configuration turnaround.
Smart hospitality and coworking spaces integrate sensor networks, building management software, and occupant-facing mobile interfaces to automate environmental controls, security protocols, and service delivery in commercial real estate assets. HVAC systems and IoT devices constitute the core hardware layer, with AI-powered analytics and cloud computing forming the intelligence backbone that enables predictive maintenance and dynamic space utilization. Room automation and guest experience management services capture premium pricing as hotels and managed workspaces seek operational labor reduction alongside personalized occupant journeys.
Building codes under the EU Green Deal, CE marking requirements for electrical installations, and FCC Part 15 regulations governing unlicensed radio-frequency devices in the United States collectively shape product certification pathways and deployment timelines. ESG disclosure mandates through the EU CSRD and emerging SEC climate rules are pressuring asset owners to document energy performance, directly stimulating smart building investment. Stakeholders must weigh interoperability standards against vendor lock-in risk as platform consolidation accelerates across the technology stack.
Market Dynamics
Hybrid work stabilization is compressing lease structures and forcing asset owners to deploy sensor networks for real-time space utilization tracking. The EU Green Deal's building efficiency mandates are accelerating capital allocation toward retrofit-ready IoT infrastructure.
Growth Catalysts
- EU CSRD disclosure mandates:Asset owners in Germany and France must document building energy performance, directly stimulating smart HVAC and lighting system procurement.
- Financial services vertical expansion:Fortune 500 banks and insurance firms are consolidating vendor relationships with managed workspace providers offering multi-location contracts.
- Sensor-to-cloud integration:IoT device density in commercial buildings is rising as edge computing architectures enable predictive maintenance at lower latency.
Market Restraints
- Semiconductor supply concentration:IoT sensor chip fabrication relies heavily on Taiwan and South Korea foundries, creating vulnerability to geopolitical disruption.
- Cybersecurity certification friction:CE marking requirements for connected devices in Europe add months to product launch timelines.
- Legacy building stock:Pre-2000 commercial real estate in the United States and United Kingdom lacks the electrical infrastructure for native IoT deployment without costly rewiring.
Strategic Opportunities
- India secondary cities:Bangalore and Hyderabad are seeing demand for flexible workspace outpace supply, creating entry points for technology-embedded operators.
- AI-powered space optimization:Machine learning algorithms analyzing occupancy patterns are converging with building management software to automate climate and lighting.
- US IRA clean building incentives:Tax credits for energy-efficient retrofits are lowering payback periods for smart building system investments.
Industry Challenges
- Interoperability standardization delays:Competing protocols from BACnet, LonWorks, and proprietary cloud platforms force asset owners into premature vendor lock-in decisions.
- Building automation engineering talent scarcity:The shortage of technicians certified in both HVAC systems and network administration is extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Hospitality and Coworking Spaces Market |
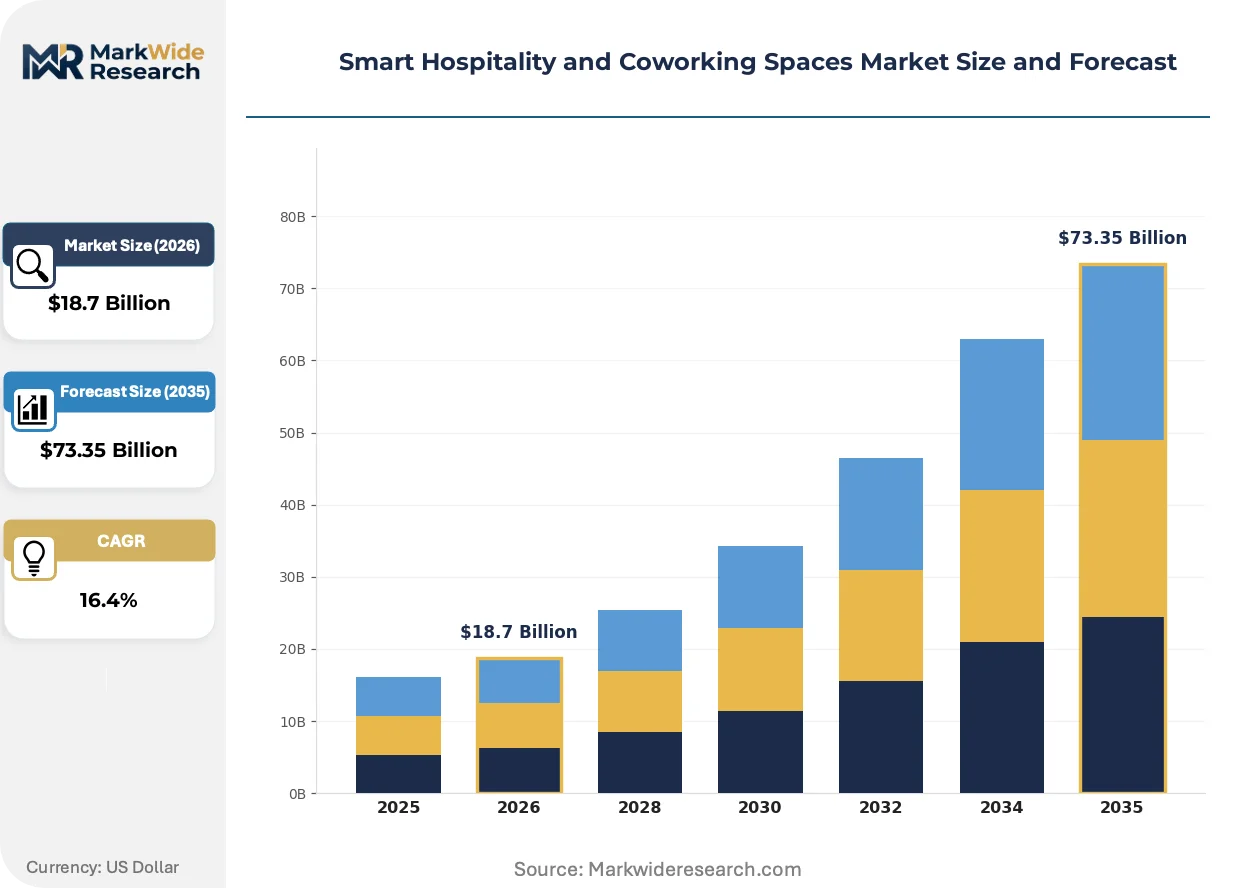
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, HVAC Systems, Security Solutions, IoT Devices Service Type: Room Automation, Guest Experience Management, Integrated Systems, Maintenance Services Technology: AI-Powered Analytics, Cloud Computing, Mobile Applications, Data Management Customer Type: Hotels, Managed Workspaces, Event Venues, Business Centers |
| Companies Covered | IWG, WeWork, Industrious, Servcorp, JustCo, Mindspace, Accor Hotels, Selina, The Executive Centre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Hospitality and Coworking Spaces Market Evolving Landscape
Building intelligence is migrating from centralized control rooms to distributed edge nodes, enabling faster response loops and reducing cloud dependency. This architectural shift is compressing hardware refresh cycles and reshaping vendor competitive positioning.
Wireless sensor networks using LoRaWAN and Zigbee protocols are modularizing building automation deployment. Mid-size property managers in the United Kingdom are adopting these systems for phased retrofits rather than full-building overhauls. The technology is modularizing capital expenditure into smaller, scalable increments that align with lease renewal cycles.
The EU AI Act's risk classification framework is tightening compliance requirements for automated decision-making in building security and access control. System integrators must now document algorithmic transparency for facial recognition and predictive occupancy analytics. Hotels and corporate campuses in Germany are responding by segregating AI-enabled functions into standalone modules that can be isolated during audits.
Enterprise procurement teams are consolidating workspace vendor relationships into multi-year framework agreements with embedded service-level guarantees. Technology and financial services firms in the United States are displacing transaction-based leasing with outcome-based contracts tied to utilization rates and employee satisfaction scores. This shift is most visible in Manhattan and San Francisco, where account consolidation has reduced active supplier lists by half.
Smart Hospitality and Coworking Spaces Market Segmentation
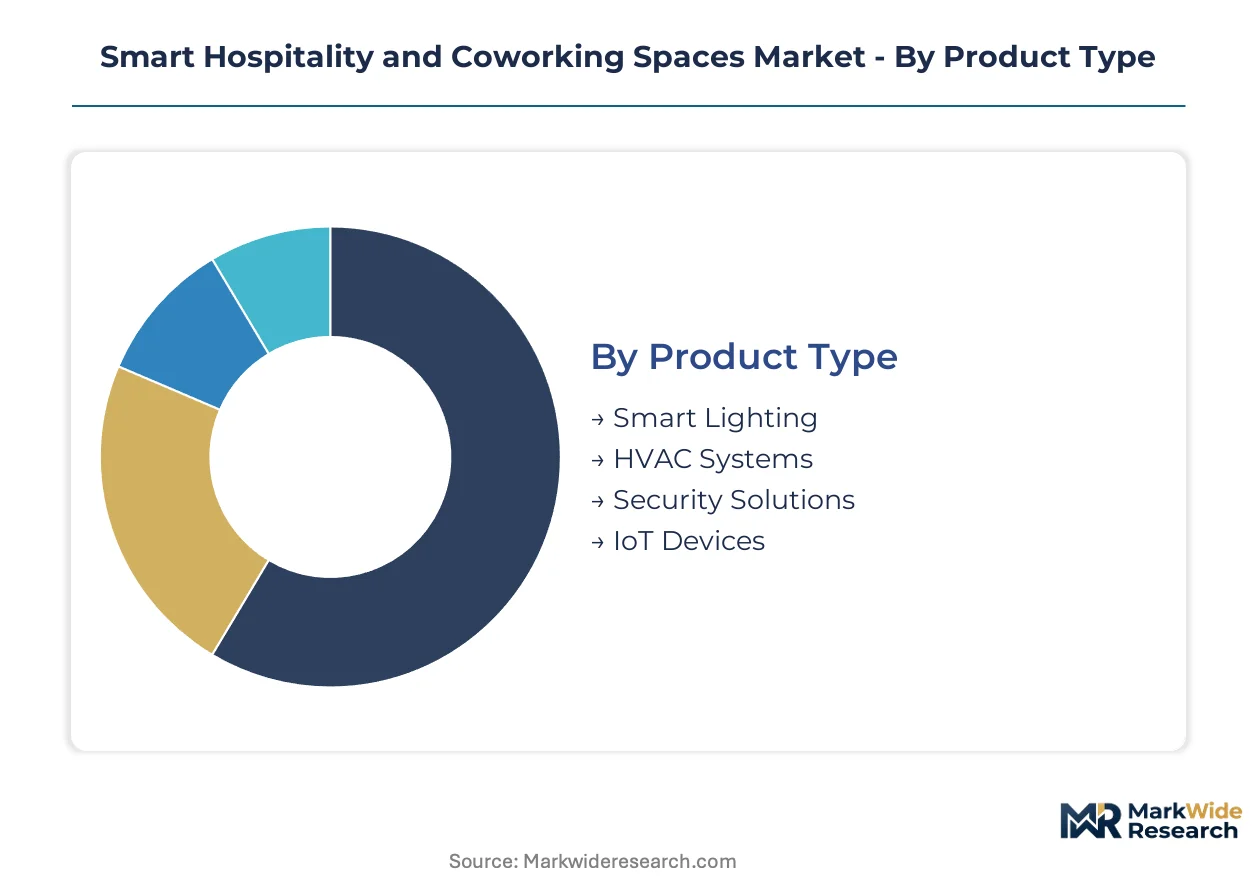
Smart hospitality and coworking spaces require modular segmentation that captures both infrastructure hardware and service delivery layers. Technology buyers prioritize retrofit compatibility alongside predictive maintenance capabilities as hybrid occupancy patterns destabilize traditional building management assumptions.
Product Type:
HVAC Systems and IoT Devices dominate procurement volumes, while Smart Lighting and Security Solutions command premium pricing tiers.
- HVAC Systems:Climate control hardware with embedded sensor networks enabling zone-based temperature modulation and predictive filter replacement. Demand concentrates in Germany and the United Kingdom where EU Green Deal retrofit mandates accelerate replacement cycles for pre-2000 commercial stock.
- IoT Devices:Distributed sensor arrays measuring occupancy, air quality, and energy consumption with wireless connectivity protocols. Financial services firms in Manhattan and San Francisco deploy these at density for real-time space utilization analytics that inform lease restructuring decisions.
- Smart Lighting:LED fixtures with daylight harvesting and circadian rhythm programming.
- Security Solutions:Access control systems integrating biometric authentication with visitor management platforms.
Today's leader: HVAC Systems. Tomorrow's challenger: IoT Devices.
Service Type:
Integrated Systems capture enterprise accounts, while Guest Experience Management and Room Automation fragment across boutique hospitality operators.
- Integrated Systems:Unified building management platforms consolidating HVAC, lighting, security, and occupancy data into single-pane dashboards. Technology firms in Bangalore and Hyderabad demand these for multi-location standardization as flexible workspace supply tightens.
- Guest Experience Management:Mobile-enabled service delivery covering check-in, concierge requests, and personalized environmental preferences. Hotels in Germany deploy these modules to reduce front-desk labor while navigating EU AI Act audit requirements for automated decision systems.
- Room Automation:In-unit controls for lighting, climate, and entertainment systems.
- Maintenance Services:Predictive upkeep contracts tied to sensor-generated equipment health scores.
Integrated Systems anchor current procurement budgets. Guest Experience Management is climbing the fastest as hospitality operators seek labor arbitrage.
Technology:
Cloud Computing underpins deployment scale, while AI-Powered Analytics and Mobile Applications differentiate vendor positioning.
- Cloud Computing:Centralized data infrastructure enabling remote building management and cross-portfolio performance benchmarking. US IRA clean building tax credits accelerate adoption as asset owners document energy efficiency gains through cloud-stored telemetry.
- AI-Powered Analytics:Machine learning models predicting equipment failure and optimizing space allocation based on occupancy patterns. Managed workspace providers in the United Kingdom use these to automate climate and lighting adjustments, though CE marking requirements extend implementation timelines.
- Mobile Applications:Occupant-facing interfaces for service requests and environmental control.
- Data Management:Governance frameworks for sensor data collection, retention, and third-party sharing compliance.
Cloud Computing delivers current infrastructure savings. AI-Powered Analytics shows the steepest expansion trajectory as edge computing architectures mature.
Customer Type:
Managed Workspaces and Hotels drive capital deployment, while Event Venues and Business Centers represent opportunistic retrofit targets.
- Managed Workspaces:Flexible office operators requiring scalable building automation across distributed locations. IWG and Industrious consolidate multi-year framework agreements with embedded service-level guarantees tied to utilization rates and employee satisfaction metrics.
- Hotels:Full-service and limited-service properties automating guest touchpoints and back-of-house operations. Properties in Germany segregate AI-enabled security functions into standalone modules for EU AI Act compliance isolation during audits.
- Event Venues:Conference centers and exhibition halls with variable occupancy patterns demanding rapid space reconfiguration.
- Business Centers:Traditional serviced office facilities upgrading legacy infrastructure for competitive parity.
Managed Workspaces dominate current contract values. Hotels are gaining share fastest as labor cost pressures intensify across hospitality verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in smart building retrofit velocity, while the United States generates higher absolute contract values through enterprise workspace consolidation. Geographic concentration reflects regulatory stringency, capital availability, and hybrid work policy maturity across distinct national contexts.
United States
Enterprise technology and financial services firms in Manhattan and San Francisco are consolidating vendor relationships into multi-year framework agreements. The SEC's emerging climate disclosure rules pressure asset owners to document building energy performance through sensor-generated telemetry. Chicago and Austin secondary markets see flexible workspace supply tightening as operators deploy IoT infrastructure for utilization-based pricing.
Germany
The EU Green Deal's building efficiency mandates accelerate HVAC replacement cycles for pre-2000 commercial stock in Frankfurt and Munich. CE marking requirements for connected devices extend product launch timelines, forcing system integrators to front-load certification costs. Berlin hospitality operators segregate AI-enabled security functions into standalone modules for EU AI Act compliance isolation during audits.
United Kingdom
Mid-size property managers in London adopt LoRaWAN and Zigbee wireless sensor networks for phased retrofits aligned with lease renewal cycles. The EU CSRD disclosure framework applies to UK-based multinationals with European operations, stimulating smart lighting procurement. Manchester and Birmingham secondary cities attract flexible workspace expansion as IWG leverages geographic density for multi-location enterprise contracts.
India
Technology firms in Bangalore and Hyderabad drive demand for integrated building management platforms as flexible workspace supply fails to keep pace. The country's national building code authorities are developing smart infrastructure standards for commercial real estate. Mumbai's financial district sees hospitality operators piloting guest experience management modules to reduce front-desk labor costs.
Japan
Corporate real estate teams in Tokyo deploy edge computing architectures to enable predictive maintenance at lower latency than cloud-dependent alternatives. METI's building energy efficiency guidelines incentivize sensor-to-cloud integration for portfolio-wide performance benchmarking. Osaka hospitality clusters adopt room automation systems to address labor scarcity in service delivery roles.
Smart Hospitality and Coworking Spaces Market Competitive Landscape
North American operators anchor the scale-driven tier; European specialists hold position through hospitality-grade service differentiation. Market structure concentrates among three global platforms with secondary-city density advantages, mid-market hospitality-embedded operators, and asset-light technology licensors. Strategic archetypes include geographic consolidators, service-layer differentiators, and flexible-lease innovators. Dominant competitive moves comprise multi-location framework agreements with embedded service-level guarantees and rapid space configuration turnaround capabilities.
Within the geographic consolidator tier, IWG leverages multi-location contracts across secondary cities to sustain enterprise account stickiness. Industrious exemplifies the hospitality-embedded archetype through service-layer differentiation in workplace delivery. WeWork occupies a position characterized by flexible lease structures and rapid deployment velocity for space reconfiguration.
| Leading Market Players |
|---|
| IWG |
| WeWork |
| Industrious |
| Servcorp |
| JustCo |
| Mindspace |
| Accor Hotels |
| Selina |
| The Executive Centre |
| Others |
Value Network & Pricing Analysis
Building automation engineering talent scarcity in Germany and the United Kingdom widens pricing-tier spreads between premium certified installations and standard retrofit deployments. Labor-cost differentials between these markets and Eastern European sourcing hubs compress margins on mid-tier integrated systems while inflating premiums for EU AI Act-compliant security modules.
Pricing Analysis
Capacity additions in China's sensor manufacturing clusters are reshaping price floors for IoT device procurement across European and North American markets. Three-tier pricing structure across premium certified, standard compliant, and economy unbundled levels dominates HVAC and lighting system sales, with CE marking and FCC Part 15 certification tiers commanding 15-25 point spreads. Cost compression in economy wireless sensor networks is intensifying because LoRaWAN module commoditization accelerates, while enterprise buyers in financial services verticals show lowest price sensitivity due to multi-year framework agreement structures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated building management platforms, while distributor networks serve fragmented mid-size property managers. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, with sensor chip supply drawing from these nodes. Raw material dependencies span silicon wafers, rare earth magnets for HVAC motors, and lithium-ion cells for wireless device power. Single-source vulnerability in Taiwan foundry capacity threatens deployment timelines for predictive maintenance systems. Distribution runs through system integrators who bundle hardware with installation and compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Enterprise procurement teams are consolidating vendor relationships toward premium specifications with embedded service-level guarantees and EU AI Act audit-ready system architectures.
For Market Incumbents: Anchor multi-location contract density across secondary cities to sustain account stickiness against flexible-lease innovators. Defend margin position by deepening backward integration into edge computing hardware and segregating AI-enabled security functions into standalone compliance modules. Threat substitution from asset-light technology licensors pressures pricing power in standardized sensor deployments.
For New Entrants and Emerging Players: Digital-native direct sales channels offer the lowest customer acquisition cost path into India's secondary cities, where flexible workspace supply fails to match technology firm demand. White-space targets include Bangalore and Hyderabad integrated platform deployments and US IRA tax credit-optimized retrofit bundling. Target hospitality operators in Germany seeking labor arbitrage through guest experience management modules.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market system integrators with CE marking certification capabilities and regional installer networks. Long-term viability across the analysis window hinges on regulatory compliance moats deepening as EU CSRD and SEC climate disclosure mandates expand. Signal to monitor: consolidation velocity among Manhattan and San Francisco enterprise workspace providers as framework agreement terms lengthen.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Location Framework Agreements | Enterprise technology firms in Manhattan consolidate vendor relationships into embedded service-level guarantee structures. |
| EU AI Act Compliance Modularization | German hospitality operators segregate automated decision systems into standalone audit-isolatable security modules. |
| Edge Computing Architecture Migration | Tokyo corporate real estate teams deploy predictive maintenance at lower latency than cloud-dependent alternatives. |
| Wireless Sensor Network Phased Retrofits | United Kingdom mid-size property managers align LoRaWAN deployments with lease renewal cycles. |
| Backward Integration into IoT Hardware | Managed workspace providers captive-produce sensor arrays to defend margin against technology licensors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research engaged building automation engineering directors, flexible workspace procurement leads, hospitality technology officers, system integration firm principals, and commercial real estate asset managers. Secondary validation drew from SEC climate disclosure filings, EU CSRD implementation guidance, FCC Part 15 equipment authorization databases, and commercial building energy performance registries. Bottom-up sensor deployment tallies and top-down real estate investment flow estimates were triangulated to anchor market sizing.
Segment-weighted modeling distributed value across HVAC systems, IoT devices, smart lighting, and security hardware product categories, with service-type overlays for integrated platforms and guest experience management. Technology dimensions including cloud computing, AI-powered analytics, and mobile application layers were cross-tabulated against customer types spanning managed workspaces, hotels, event venues, and business centers. CAGRs were derived from regression analysis of retrofit cycle acceleration and hybrid work policy stabilization curves, with regulatory mandate enforcement timelines and semiconductor supply elasticity as key forecast inputs.
Geopolitical disruption in Taiwan foundry capacity, delays in EU AI Act audit protocol finalization, and US IRA tax credit program administrative bottlenecks are the dominant revision risks to deployment velocity assumptions. Forecasts reflect documented base-case assumptions regarding hybrid work permanence and building code stringency trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market