
 US Hospitality Market | 2026-2036
US Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
US Hospitality Market Insights
Multi-source procurement of food and beverage supplies is repositioning operational risk management across mid-scale and luxury properties. Marriott International leverages its scale to negotiate direct agricultural contracts, reducing intermediary dependency. Hilton Worldwide anchors its supply strategy through regional distribution hubs that buffer against localized disruptions. Wyndham Hotels & Resorts competes on cost efficiency by consolidating procurement across its franchise-heavy portfolio.
US Hospitality encompasses lodging, foodservice, and event hosting operations characterized by perishable inventory, high fixed-cost structures, and real-time yield management systems. The sector functions through physical assets—guest rooms, commercial kitchens, banquet facilities—optimized for occupancy rate maximization and average daily rate capture. Hotels and restaurants together represent the dominant service type pairing, with luxury and mid-range price tiers commanding the majority of revenue pools while budget operations compete on asset turnover speed. Online travel agencies and direct booking channels now split reservation volume, forcing property operators to balance commission costs against brand control.
OSHA workplace safety standards, Department of Labor wage-and-hour rules, and state-level health department codes collectively shape staffing models and operational compliance costs across US hospitality assets. The EPA's energy efficiency guidelines influence capital expenditure decisions for property renovations and new construction. Stakeholders must weigh labor automation investments against regulatory compliance thresholds as wage and safety mandates continue tightening.
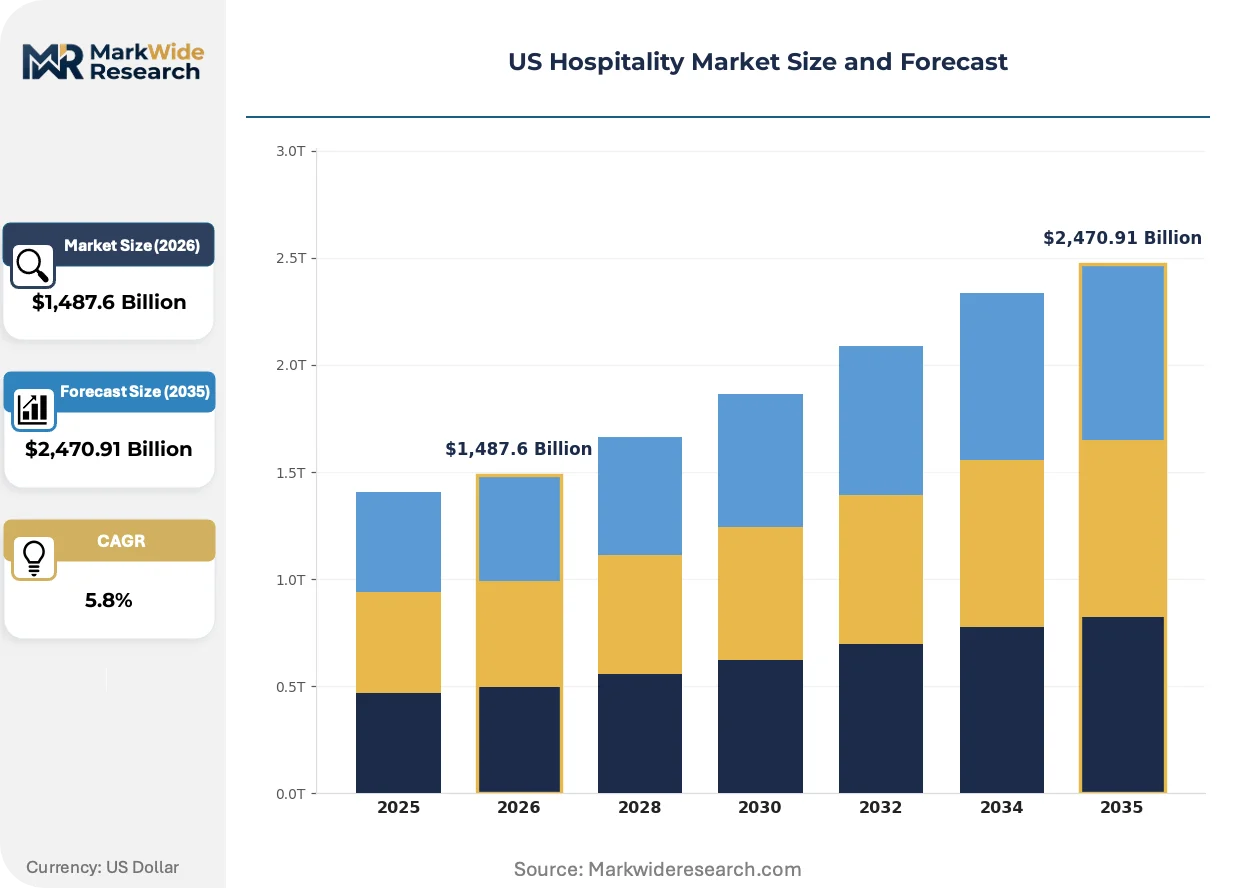
Market Dynamics
Labor cost pressures from Department of Labor overtime threshold adjustments are forcing US hospitality operators to restructure staffing models while Sun Belt migration concentrates demand in Florida, Texas, and Arizona markets.
Growth Catalysts
- Convention Infrastructure Investment:Florida, Texas, and Arizona are expanding meeting and event facilities, drawing corporate group business away from legacy Northeast markets.
- OSHA Workplace Safety Compliance:Stricter enforcement is accelerating automation adoption in back-of-house operations, reducing injury liability exposure.
- Direct Agricultural Contracting:Large hotel operators are bypassing foodservice distributors to secure produce and protein supplies at stabilized pricing.
Market Restraints
- Wage Compression from Overtime Rules:The Department of Labor's expanded eligibility threshold is inflating payroll costs faster than rate increases can absorb.
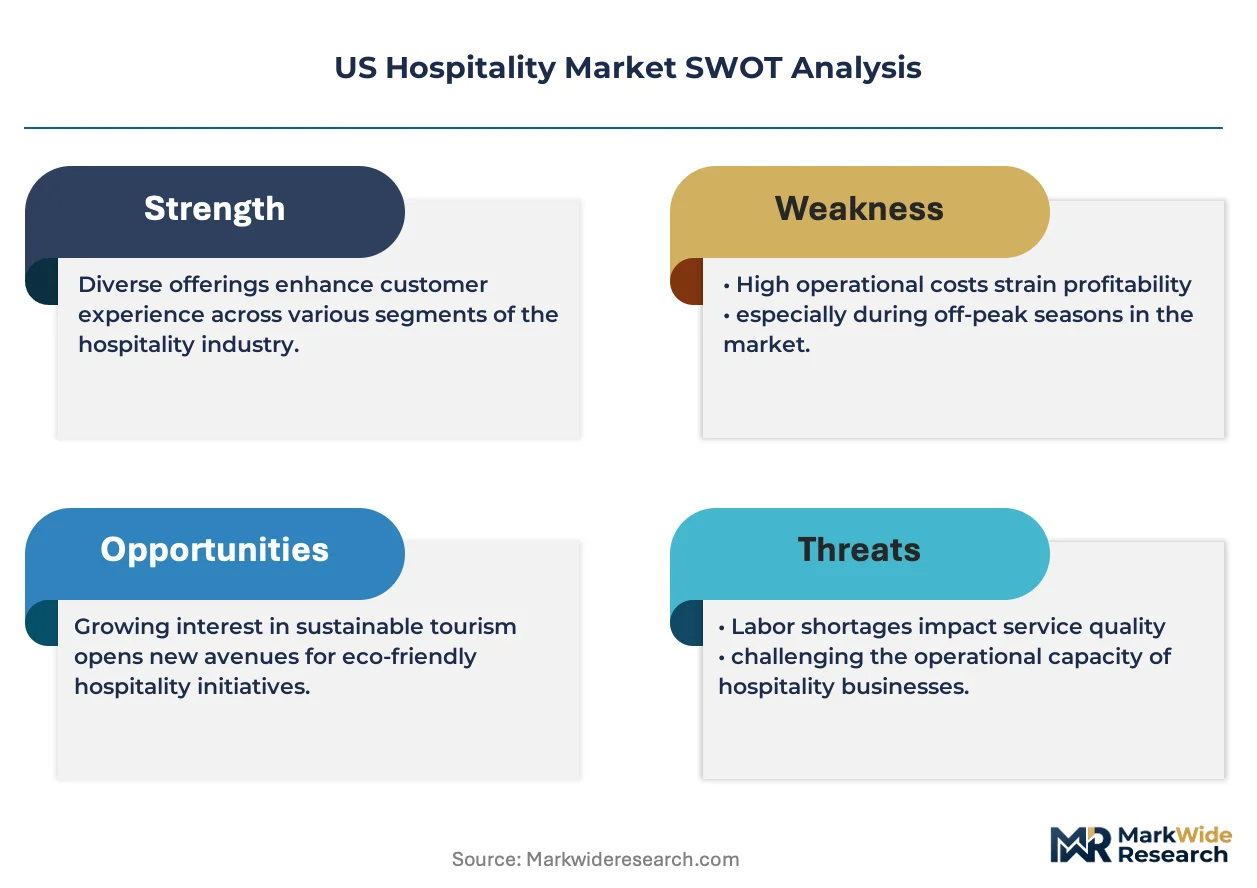
- Regional Labor Pool Concentration:Sun Belt markets face acute shortages of certified kitchen staff and licensed hospitality managers.
- Online Travel Agency Commission Burden:Booking.com and Expedia extract 15-25% of room revenue, eroding property-level profitability.
Strategic Opportunities
- Franchise Consolidation in Secondary Markets:Mid-scale brands can capture underpenetrated demand in Ohio, Indiana, and Michigan where supply growth lags population shifts.
- Energy Efficiency Retrofit Incentives:EPA guidelines and state utility rebates are subsidizing HVAC and lighting upgrades that reduce operating expenditures.
- Hybrid Event Technology Integration:Properties combining physical banquet space with broadcast infrastructure can serve simultaneous in-person and virtual attendees.
Industry Challenges
- Legacy Property Management System Migration:Independent operators struggle to integrate cloud-based reservation platforms with decades-old on-premise infrastructure.
- Health Department Certification Bottlenecks:Backlogs in food handler licensing and alcohol service permits delay new restaurant openings by 60-90 days in high-growth counties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hospitality Market |
| Market Size in 2026 | $1,487.6 Billion |
| Market Size in 2035 | $2,470.91 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotels, Restaurants, Bars, Catering End User: Business Travelers, Leisure Guests, Event Planners, Tour Groups Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Corporate Contracts Price Tier: Luxury, Mid-Range, Budget, Economy |
| Companies Covered | Marriott International, Hilton Worldwide, Wyndham Hotels & Resorts, InterContinental Hotels Group (IHG), Choice Hotels International, Hyatt Hotels Corporation, Best Western Hotels & Resorts, Aimbridge Hospitality, Highgate, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hospitality Market Trends and Innovations
Digital tools and regulatory mandates are compressing operational timelines while reshaping how US hospitality assets acquire guests and manage perishable inventory.
Artificial intelligence revenue management systems are rewriting pricing authority across hotel portfolios. Mid-scale and luxury properties now deploy algorithms that adjust room rates hourly based on competitor positioning and search demand signals. Revenue managers at independent properties are losing pricing control to centralized platforms.
Department of Labor wage-and-hour enforcement is intensifying audit frequency across multi-unit restaurant operators. Franchisors are imposing stricter time-tracking technology mandates on franchisees to mitigate joint-employer liability. Quick-service and casual-dining segments in California and New York are accelerating kiosk and mobile-order deployment.
Corporate travel procurement is consolidating booking volume through managed travel platforms. Employers are restricting employee use of consumer-facing travel sites to enforce policy compliance and capture negotiated rate discounts. This shift is most pronounced among technology and financial services firms with headquarters in Austin, Dallas, and Miami.
US Hospitality Market Segmentation
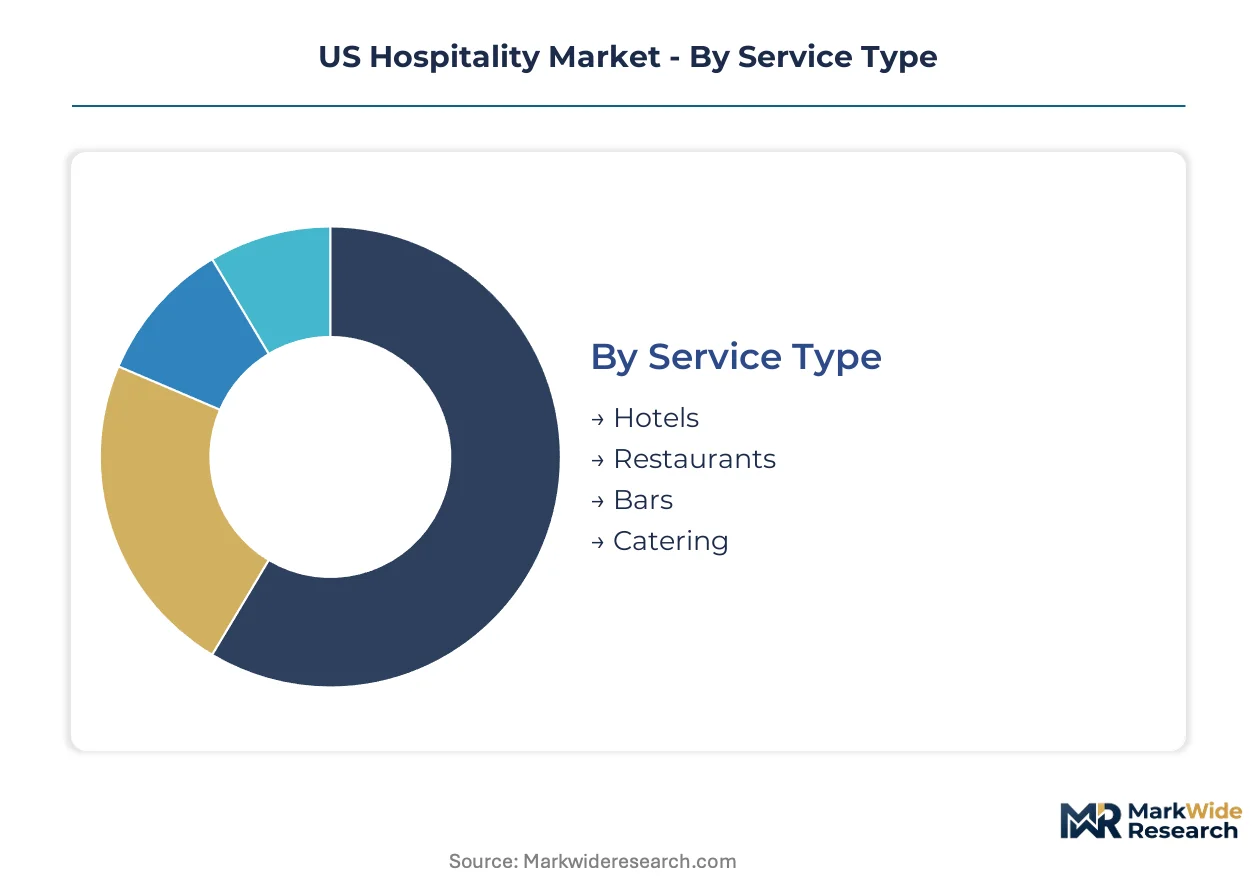
US hospitality operators segment their assets and service configurations to match distinct demand profiles, each requiring differentiated pricing architecture, staffing models, and distribution channel weightings. Proper segmentation alignment determines whether properties capture rate premiums or compete on asset velocity.
Service Type:
Physical asset configuration and revenue model architecture define competitive positioning across hospitality service formats.
- Hotels:Inventory-intensive lodging operations with high fixed-cost structures optimized for occupancy rate maximization and average daily rate capture. Demand concentrates in Sun Belt states including Florida, Texas, and Arizona where population migration and convention infrastructure investment are accelerating development pipelines.
- Restaurants:Perishable inventory operations characterized by real-time yield management, commercial kitchen throughput constraints, and table-turn velocity optimization. OSHA workplace safety standards and Department of Labor wage-and-hour rules are reshaping staffing models across multi-unit operators.
- Bars:Beverage-forward formats with lower labor intensity but heightened regulatory exposure around alcohol service permits and health department certification.
- Catering:Event-based production with demand tied to corporate group business and institutional contract cycles.
Mature deployment sits with Hotels. Newer deployment is concentrated in Catering as hybrid event formats expand.
End User:
Customer procurement behavior and rate sensitivity patterns segment hospitality demand into distinct booking profiles.
- Business Travelers:Corporate-account travelers with employer-mandated booking channel restrictions and negotiated rate access. Employers are tightening travel policy compliance and consolidating volume through managed travel platforms, particularly technology and financial services firms headquartered in Austin, Dallas, and Miami.
- Leisure Guests:Price-sensitive individual travelers with high platform loyalty to online travel agencies and direct-to-consumer booking tools.
- Event Planners:B2B procurement professionals sourcing group room blocks and banquet capacity with extended decision cycles.
- Tour Groups:Packaged travel operators negotiating volume discounts and commission structures.
Revenue concentration favors Business Travelers in urban gateway markets. Leisure Guest volume is expanding fastest in resort and drive-to destinations.
Booking Channel:
Distribution economics and customer acquisition cost structures vary sharply across reservation pathways.
- Online Travel Agencies:Third-party platforms extracting 15-25% commission on room revenue while delivering demand visibility. Booking.com and Expedia dominate this channel, forcing property operators to balance commission costs against brand control.
- Direct Booking:Brand-controlled reservations with zero commission burden but higher marketing acquisition costs. Large operators like Marriott International and Hilton Worldwide invest heavily in loyalty program infrastructure to shift share toward this channel.
- Travel Agents:Intermediary-served bookings concentrated in luxury and complex itinerary segments.
- Corporate Contracts:Negotiated rate agreements tied to annual room night commitments and preferred supplier status.
Channel mix is tilting toward Direct Booking as loyalty technology investments mature. Corporate Contracts are gaining share fastest among business travel segments.
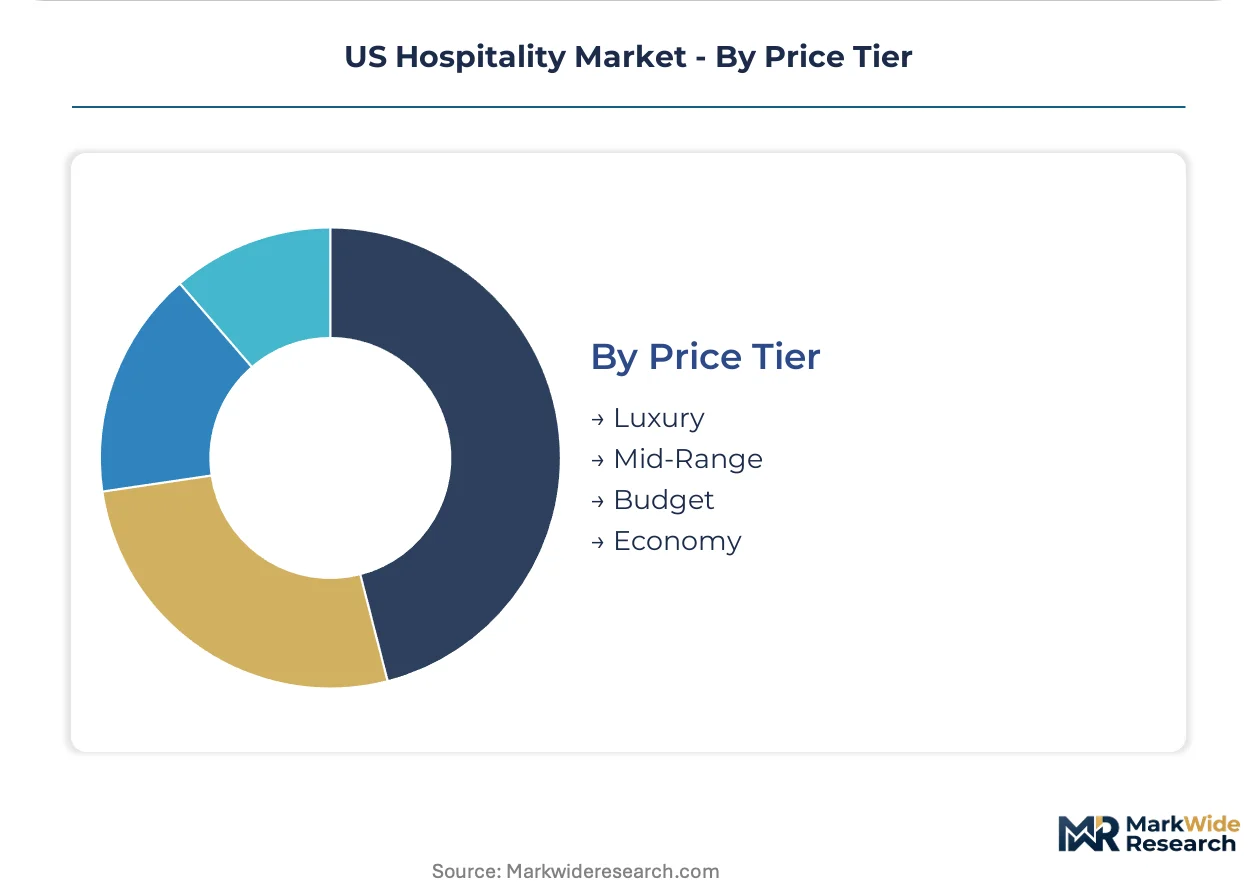
Price Tier:
Capital intensity and service amenity levels stratify hospitality assets into distinct competitive arenas.
- Luxury:Full-service properties with substantial food and beverage operations, spa amenities, and personalized service staffing ratios. These assets command rate premiums through brand heritage and location scarcity.
- Mid-Range:Select-service formats balancing limited amenity sets with competitive positioning. Wyndham Hotels & Resorts competes in this tier through franchise-heavy portfolio consolidation and cost-efficient procurement.
- Budget:Asset-light operations competing on turnover speed and minimal service overhead.
- Economy:Price-floor positioning with stripped-back amenities and self-service operational models.
Development activity clusters in Mid-Range formats for capital efficiency. Luxury supply is expanding most quickly in Sun Belt convention markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand is concentrating in Sun Belt states where population migration and convention infrastructure investment are accelerating hospitality development pipelines. Florida, Texas, and Arizona anchor this expansion, though secondary markets in the Midwest and Mountain West present consolidation opportunities.
Florida
Convention infrastructure investment in Orlando and Miami is drawing corporate group business away from legacy Northeast markets. The state's health department certification backlogs delay new restaurant openings by 60-90 days in high-growth counties. Tampa Bay and Greater Orlando are expanding meeting facilities to capture technology and financial services firm headquarters relocating from higher-tax jurisdictions.
Texas
Austin, Dallas, and Miami-headquartered employers are tightening travel policy compliance and consolidating volume through managed travel platforms. The Department of Labor's overtime threshold adjustments are pressuring labor cost structures across Dallas-Fort Worth hotel and restaurant operations. Houston's energy sector recovery is driving demand for extended-stay properties and corporate contract channels.
Arizona
Population migration from California is accelerating Phoenix and Tucson hospitality development with mid-range and luxury supply expanding fastest. EPA energy efficiency guidelines are influencing capital expenditure decisions for property renovations across the state. Scottsdale's resort corridor is retrofitting banquet facilities with hybrid event technology to serve simultaneous in-person and virtual attendees.
Southeast
Georgia and the Carolinas are capturing underpenetrated demand where supply growth lags population shifts from the Northeast. OSHA workplace safety standards are reshaping staffing models across multi-unit restaurant operators in Atlanta and Charlotte. Nashville's music tourism infrastructure is driving food and beverage supply chain consolidation through direct agricultural contracting.
Mountain West
Denver and Salt Lake City are emerging as secondary convention markets with lower operating cost structures than coastal alternatives. State utility rebates are subsidizing HVAC and lighting upgrades that reduce operating expenditures across independent properties. Colorado's ski resort corridors are deploying artificial intelligence revenue management systems to adjust room rates hourly based on competitor positioning.
US Hospitality Market Competitive Landscape
Franchise consolidation dominates the current landscape as operators capture underpenetrated demand in secondary markets. The vendor base organizes around three strategic archetypes: scale-driven franchisors negotiating direct agricultural contracts, asset-light operators competing on turnover speed, and hybrid event technology integrators serving simultaneous in-person and virtual attendees. M&A activity and portfolio diversification are the dominant competitive moves reshaping market share distribution.
Within the scale-driven franchisor tier, Marriott International and Hilton Worldwide exemplify operators leveraging loyalty program infrastructure to shift reservation share toward direct booking channels. Wyndham Hotels & Resorts occupies a position in the cost-efficiency archetype, consolidating procurement across franchise-heavy portfolios. These three entities represent the competitive tension between commission cost reduction and brand control that defines current distribution economics.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Wyndham Hotels & Resorts |
| InterContinental Hotels Group (IHG) |
| Choice Hotels International |
| Hyatt Hotels Corporation |
| Best Western Hotels & Resorts |
| Aimbridge Hospitality |
| Highgate |
| Others |
Pricing and Supply Chain Analysis
Captive procurement of food and beverage supplies anchors both cost positioning and rate-setting flexibility across US hospitality portfolios. Large operators negotiating direct agricultural contracts capture margin insulation unavailable to franchise-dependent competitors, while independent properties absorb distributor markups that compress pricing latitude.
Pricing Analysis
Service bundling separates all-inclusive resort rates from unbundled select-service pricing across the US hospitality sector. Three-tier pricing structure across premium, standard, and economy levels reflects amenity density and loyalty program integration depth. Price differentiation hinges on location scarcity and brand heritage certification. Cost compression in mid-range segments is intensifying because online travel agency commissions extract 15-25% of room revenue. Leisure travelers booking through consumer-facing platforms exhibit highest price sensitivity, while corporate contract travelers with employer-mandated channels show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with specialized foodservice equipment manufacturers concentrated in domestic production clusters. Geographic supply concentration spans Mexico for produce proximity, California for specialty agriculture, and Midwest processing centers for protein aggregation. Raw material dependencies include perishable inventory logistics, commercial kitchen equipment, and banquet furnishings. Supply chain risk centers on tariff exposure for imported linens and glassware. Distribution runs through regional distribution hubs that buffer against localized disruptions while enabling just-in-time banquet staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US hospitality is consolidating around operators with scale to absorb Department of Labor wage mandates and negotiate direct supplier contracts. Weaker independents face exit pressure from compliance cost inflation and technology modernization requirements.
For Market Incumbents: Deploy loyalty program infrastructure to shift reservation share toward direct booking channels and reduce online travel agency commission burden. Marriott International and Hilton Worldwide exemplify this lever, capturing rate premiums through brand-controlled distribution. Incumbents should accelerate property management system cloud migration to defend against revenue management platform centralization. Automation investments in back-of-house operations mitigate OSHA workplace safety exposure while containing payroll cost inflation from overtime rule expansion. For New Entrants and Emerging Players: Begin with franchise consolidation in secondary Midwest markets where supply growth lags population shifts from the Northeast. Ohio, Indiana, and Michigan present underpenetrated demand with lower competitive density than Sun Belt corridors. New entrants should target mid-range select-service formats for capital efficiency, leveraging state utility rebates for energy efficiency retrofits as a go-to-market differentiator against legacy independent properties. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by scale-driven franchisors seeking regional footprint expansion. Long-term viability favors operators with captive supply relationships and hybrid event technology infrastructure. Acquisition targets should demonstrate direct agricultural contracting capabilities or hybrid banquet broadcast integration. The signal to watch is corporate travel procurement consolidation through managed travel platforms, which will accelerate share capture by properties with negotiated rate agreements and loyalty program density.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Agricultural Contracting | Marriott International bypasses distributors to secure produce at stabilized pricing, reducing intermediary dependency. |
| Hybrid Event Technology Integration | Scottsdale resort corridor retrofits banquet facilities to serve simultaneous in-person and virtual attendees. |
| Franchise Consolidation in Secondary Markets | Mid-scale brands capture underpenetrated demand in Ohio, Indiana, and Michigan where supply growth lags migration. |
| Loyalty Program Infrastructure Investment | Hilton Worldwide shifts reservation share toward direct booking channels, reducing online travel agency commission exposure. |
| Energy Efficiency Retrofit Deployment | EPA guidelines and state utility rebates subsidize HVAC upgrades that reduce operating expenditures across independent properties. |
Research Methodology
Independent corroboration across property-level financial disclosures, state health department certification records, and Department of Labor enforcement data underwrites the qualitative findings in this study. Primary interviews with revenue management directors, franchise operations executives, food and beverage procurement leads, and hospitality labor compliance officers combined with secondary validation from STR lodging reports, Bureau of Labor Statistics wage data, and EPA energy efficiency filings. Bottom-up property count aggregation and top-down market sizing triangulation anchored volume estimates.
Comparable-period anchoring referenced historical occupancy and average daily rate patterns across the projection horizon to calibrate demand recovery assumptions. Segmentation dimensions modeled include service type, price tier, booking channel, and end-user procurement behavior. CAGRs derived from trend extrapolation of Sun Belt migration flows and convention infrastructure investment pipelines. Forecast inputs incorporated Department of Labor overtime threshold adjustments and online travel agency commission rate trajectories.
Underlying measurement precision varies by segment; luxury and mid-range property counts carry tighter precision than budget operations with fragmented independent ownership. Forecasts reflect assumptions around population migration velocity, corporate travel policy enforcement, and regulatory compliance cost pass-through. Specific risk factors that could revise projections include accelerated automation adoption altering labor demand, online travel agency commission renegotiation, and health department certification backlog resolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
Airport Lounge Operation Services Market