
 US Laundry Facilities and Dry-Cleaning Service Market | 2026-2036
US Laundry Facilities and Dry-Cleaning Service Market Size, Share, and Industry Trends Forecast 2026-2036
US Laundry Facilities and Dry-Cleaning Service Market Intelligence
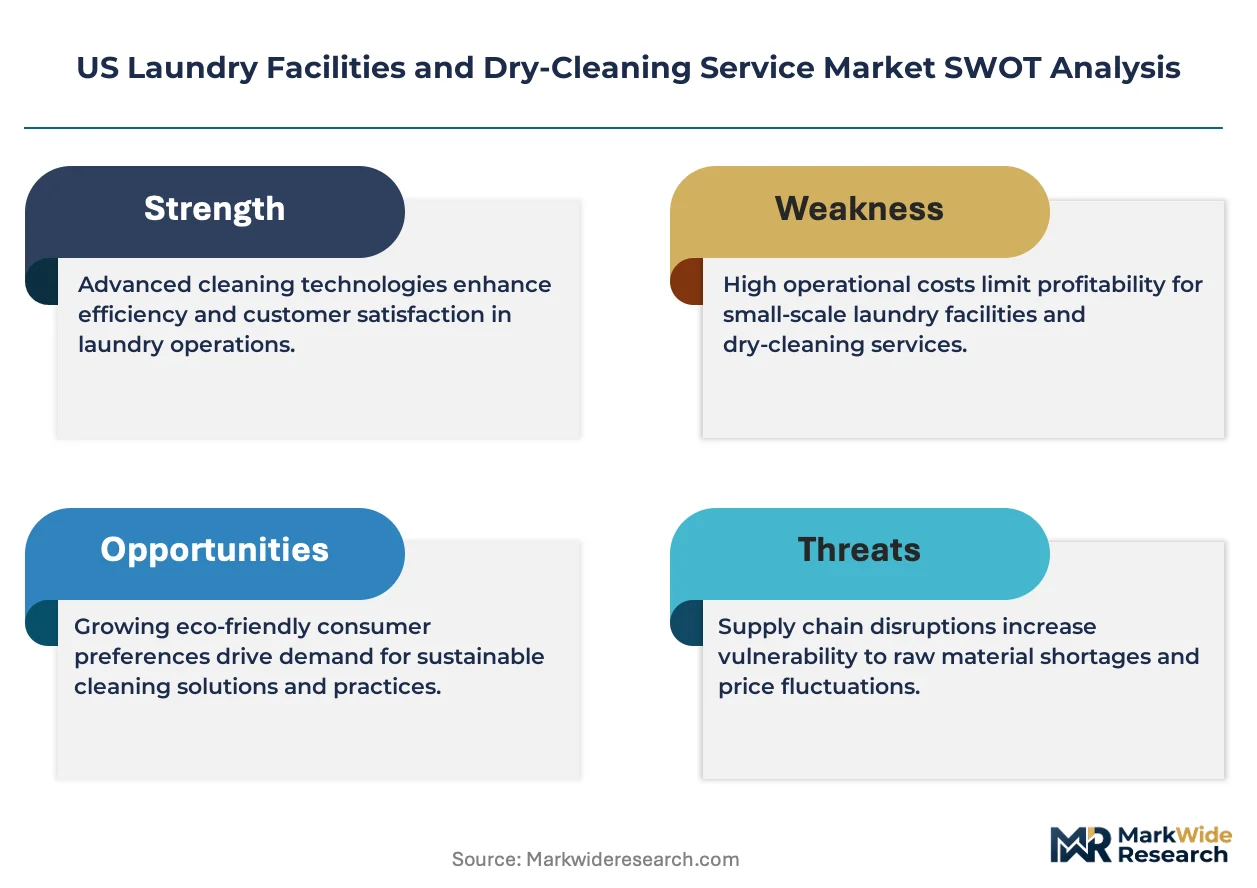
The capital-intensity divergence between industrial tunnel washers and boutique dry-cleaning operations is unwinding as mid-scale operators consolidate. CSC ServiceWorks leverages its national infrastructure of coin-operated and smart-machine networks to sustain route density across multifamily properties. WASH Multifamily Laundry Systems LLC anchors its position through exclusive service contracts with apartment operators in Sun Belt metros. Tide Cleaners differentiates via app-integrated pickup logistics that compete with traditional storefront models.
US laundry facilities and dry-cleaning services encompass commercial establishments processing garments, linens, and textiles through aqueous washing, solvent-based cleaning, or specialized finishing with equipment rated from 20-pound dry-cleaning machines to 400-pound continuous-batch tunnel systems. The sector serves hygiene, appearance, and fabric-preservation needs across consumer and commercial markets. Full-service laundries and self-service laundromats dominate transaction volume, while specialty cleaning services command premium pricing for leather, wedding gown, and archival textile restoration. Smart washer deployments through IoT-enabled payment and cycle-management platforms represent the fastest-growing technology segment, though coin-operated machines still occupy the majority of installed base in lower-income zip codes.
EPA oversight of perchloroethylene emissions under the Clean Air Act shapes solvent choice and equipment retirement timelines for dry-cleaning operators. OSHA workplace exposure limits and state-level environmental regulations in California and New York further constrain traditional chemical processes. Franchise operators and facility owners must monitor NHTSA-linked commercial fleet regulations as route-based delivery expands, while FTC consumer protection standards govern pricing transparency in online booking channels.
Market Dynamics
EPA phase-out mandates for perchloroethylene under the Clean Air Act are forcing capital rotation across dry-cleaning operations, compressing equipment replacement timelines while accelerating solvent substitution investments.
Growth Catalysts
- Multifamily housing density:Sun Belt metropolitan corridors in Texas, Florida, and California sustain route-based pickup model economics through concentrated delivery zones.
- Clean Air Act amendments:EPA emission standards for perchloroethylene accelerate wet-cleaning and liquid carbon dioxide technology deployment among legacy operators.
- Hospitality outsourcing:Hotels and restaurants expand contracted linen management, shifting capital burden from property owners to specialized service providers.
Market Restraints
- Equipment capital intensity:Tunnel washer systems rated above 200 pounds require substantial upfront investment, limiting mid-scale operator expansion.
- Input cost volatility:Solvent prices fluctuate with petrochemical feedstock markets, squeezing margin predictability for traditional dry-cleaning establishments.
- Regulatory friction:OSHA workplace exposure limits and state-level environmental rules in California and New York constrain chemical process choices.
Strategic Opportunities
- Smart machine deployment:IoT-enabled payment and cycle-management platforms penetrate lower-income zip codes where coin-operated machines dominate installed base.
- Specialty restoration services:Wedding gown, leather, and archival textile cleaning command premium pricing with limited competitive saturation.
- Route density optimization:NHTSA-linked commercial fleet regulations create compliance frameworks that favor scaled operators with dedicated logistics infrastructure.
Industry Challenges
- Technical workforce scarcity:Equipment maintenance and solvent handling certifications require specialized training that outpaces labor pipeline development.
- Legacy system integration:Smart machine networks must interface with existing payment infrastructure, creating deployment friction for retrofitted facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Laundry Facilities and Dry-Cleaning Service Market |
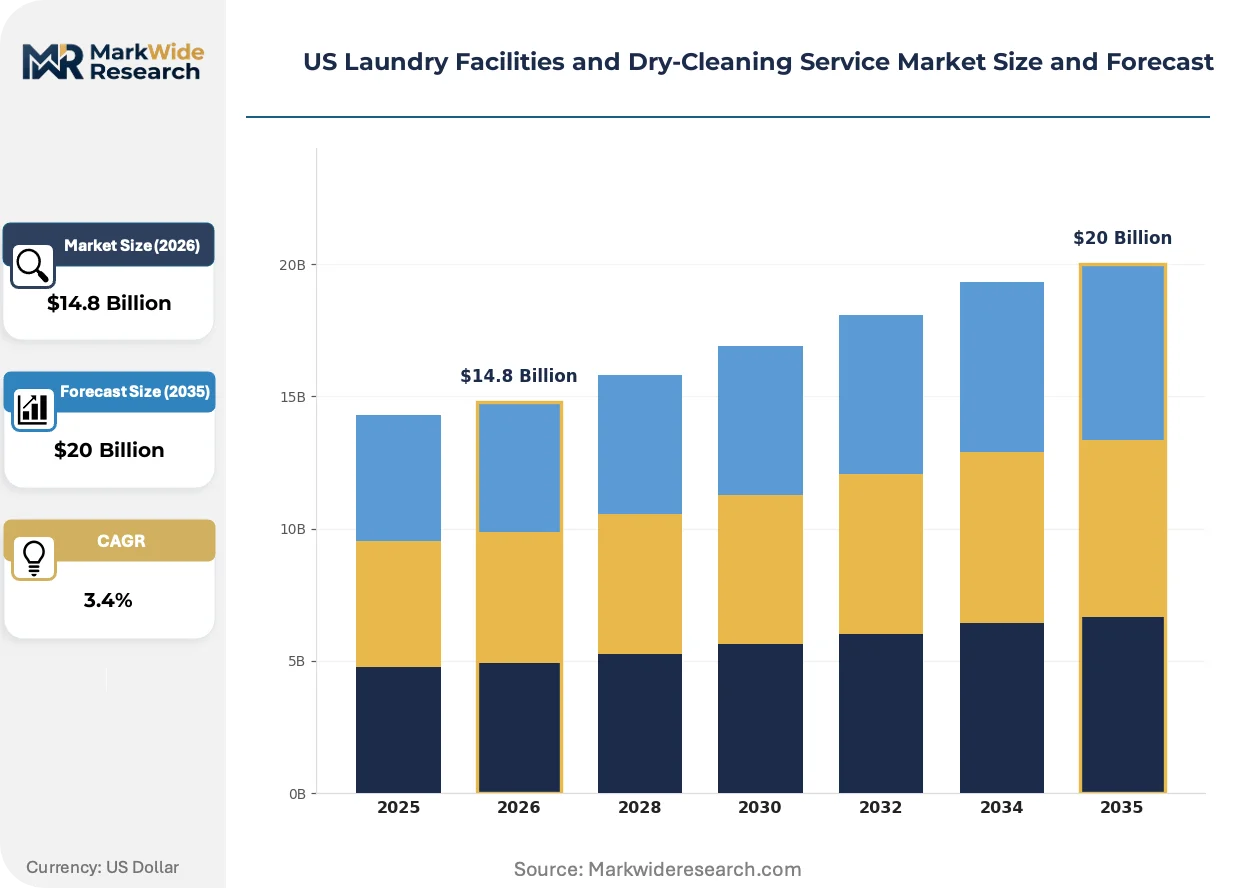
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Service Laundromats, Full-Service Laundries, Dry-Cleaning Boutiques, Specialty Cleaning Services Customer Type: Residential Customers, Commercial Businesses, Institutional Clients, Hospitality Sector Technology: Coin-Operated Machines, Smart Washers, Eco-Friendly Cleaners, Automated Drying Systems Distribution Channel: Online Booking Platforms, Physical Stores, Mobile Apps, Franchise Outlets |
| Companies Covered | Rinse, Inc., Mulberrys Garment Care, Tide Cleaners, ByNext Inc., CSC ServiceWorks Inc., Lapels Dry Cleaning, CD One Price Cleaners, WASH Multifamily Laundry Systems LLC, Martinizing International LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Laundry Facilities and Dry-Cleaning Service Market Strategic Shifts & Innovations
Wet-cleaning technology is advancing aqueous processing capabilities that match solvent-based performance for delicate fabrics, reshaping capital allocation across equipment categories.
Liquid carbon dioxide cleaning systems is supplanting perchloroethylene in commercial dry-cleaning operations. Boutique operators in California and New York metropolitan areas adopt these systems to preempt regulatory enforcement. The technology is supplanting conventional solvent infrastructure by eliminating hazardous waste disposal liabilities and reducing ventilation retrofit requirements.
EPA oversight of perchloroethylene emissions tightens equipment retirement timelines and solvent handling protocols. Dry-cleaning operators face compressed compliance windows for emission control upgrades. Specialty cleaning services serving leather and archival textile segments absorb higher compliance costs through premium pricing structures.
App-integrated pickup logistics compress customer acquisition cycles and reorder frequency. Traditional storefront models in dense metropolitan markets lose transaction volume to route-based operators with digital booking interfaces. Texas and Florida multifamily corridors exhibit the fastest channel migration as apartment operators consolidate vendor relationships through exclusive service contracts.
US Laundry Facilities and Dry-Cleaning Service Market Segmentation
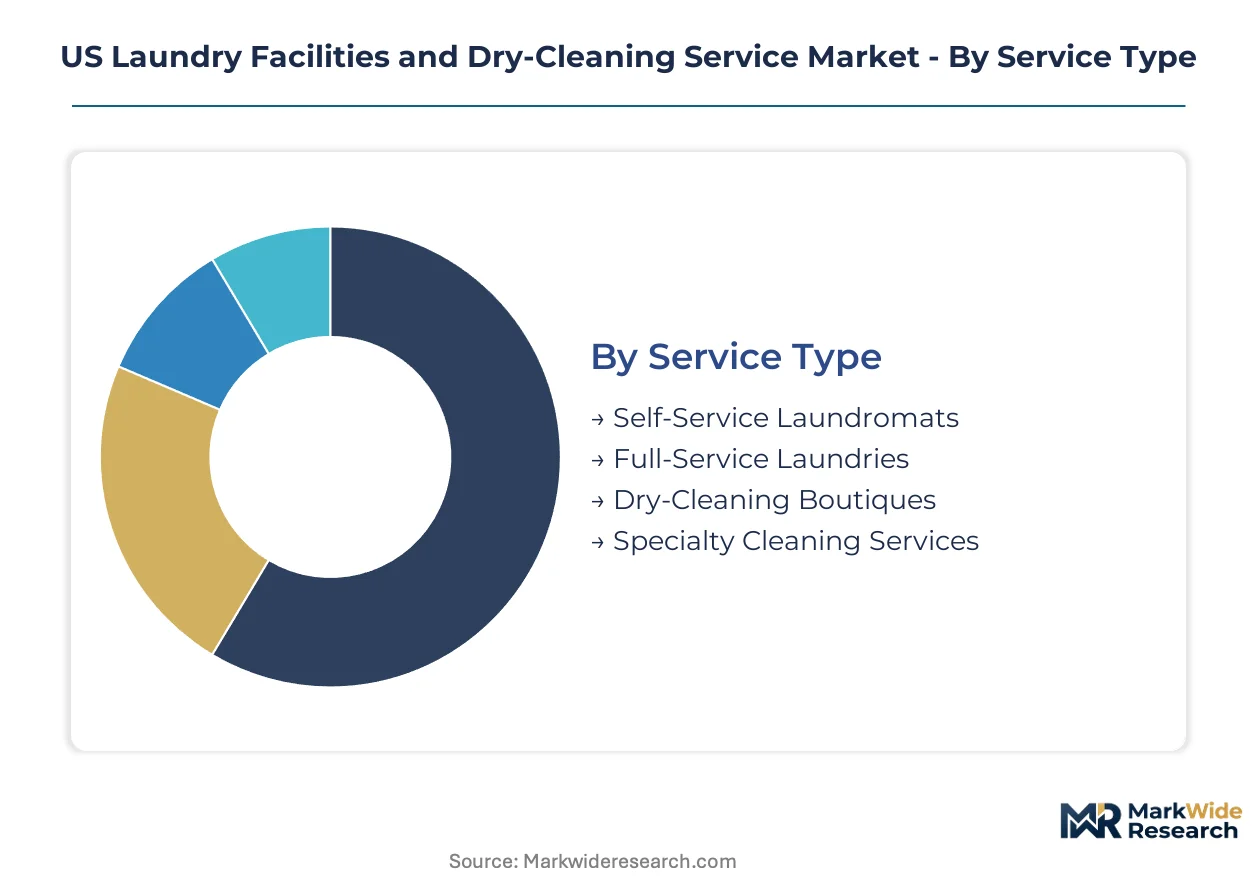
Segmentation reveals how capital intensity and regulatory pressure fragment competitive positioning across the US laundry facilities and dry-cleaning service market. Each dimension exposes distinct vulnerability to wet-cleaning substitution, route-based disruption, or smart-machine displacement.
Service Type:
Substitution pressure from wet-cleaning and liquid carbon dioxide systems weighs most heavily on solvent-dependent segments, while aqueous-based operations face lighter compliance burdens.
- Self-Service Laundromats:Coin-operated and smart-machine facilities process standard garments through aqueous washing with equipment rated 20-80 pounds. Demand concentrates in lower-income zip codes across Texas and Florida metropolitan corridors where multifamily housing density supports walk-in traffic. These locations absorb less regulatory pressure than solvent-based alternatives.
- Full-Service Laundries:Industrial tunnel washer systems rated 200-400 pounds handle bulk linen processing for commercial accounts. Hotels and restaurants in California metropolitan areas increasingly outsource to these operators, shifting capital burden from property owners. EPA emission standards do not constrain aqueous chemistry.
- Dry-Cleaning Boutiques:Solvent-based operations using perchloroethylene or hydrocarbon chemistry face compressed equipment retirement timelines under Clean Air Act mandates.
- Specialty Cleaning Services:Leather, wedding gown, and archival textile restoration commands premium pricing with limited competitive saturation.
Full-Service Laundries anchors the volume base while Smart Washers gains share at the steepest rate.
Customer Type:
Margin structure varies sharply across customer tiers, with institutional contracts delivering volume stability and hospitality accounts yielding the highest per-pound revenue.
- Residential Customers:Individual households accessing laundromats, pickup services, or subscription models through mobile apps. Florida and Texas Sun Belt metros exhibit fastest channel migration as apartment operators consolidate vendor relationships.
- Commercial Businesses:Restaurants, healthcare clinics, and fitness centers contracting linen supply and processing. These accounts prioritize route density and delivery reliability over price.
- Institutional Clients:Government facilities, educational institutions, and correctional operations with long-term service contracts.
- Hospitality Sector:Hotels and resorts expanding outsourced linen management to specialized providers. California operators absorb higher compliance costs through premium pricing structures.
Commercial Businesses anchors the volume base while Hospitality Sector climbs the fastest.
Technology:
Capital deployment patterns diverge between legacy infrastructure and connected equipment, with retrofit friction slowing smart-machine penetration in established facilities.
- Coin-Operated Machines:Legacy payment infrastructure dominates installed base in lower-income zip codes where upfront replacement costs deter upgrade cycles. These systems require no network connectivity or software maintenance.
- Smart Washers:IoT-enabled payment and cycle-management platforms represent the fastest-growing technology segment. Texas and Florida multifamily corridors drive deployment as property managers seek operational visibility and reduced cash handling.
- Eco-Friendly Cleaners:Wet-cleaning and liquid carbon dioxide systems supplanting perchloroethylene in California and New York metropolitan areas.
- Automated Drying Systems:Continuous-batch tunnel dryers integrated with tunnel washer lines for high-volume commercial operations.
Coin-Operated Machines anchors the volume base while Eco-Friendly Cleaners expands most quickly.
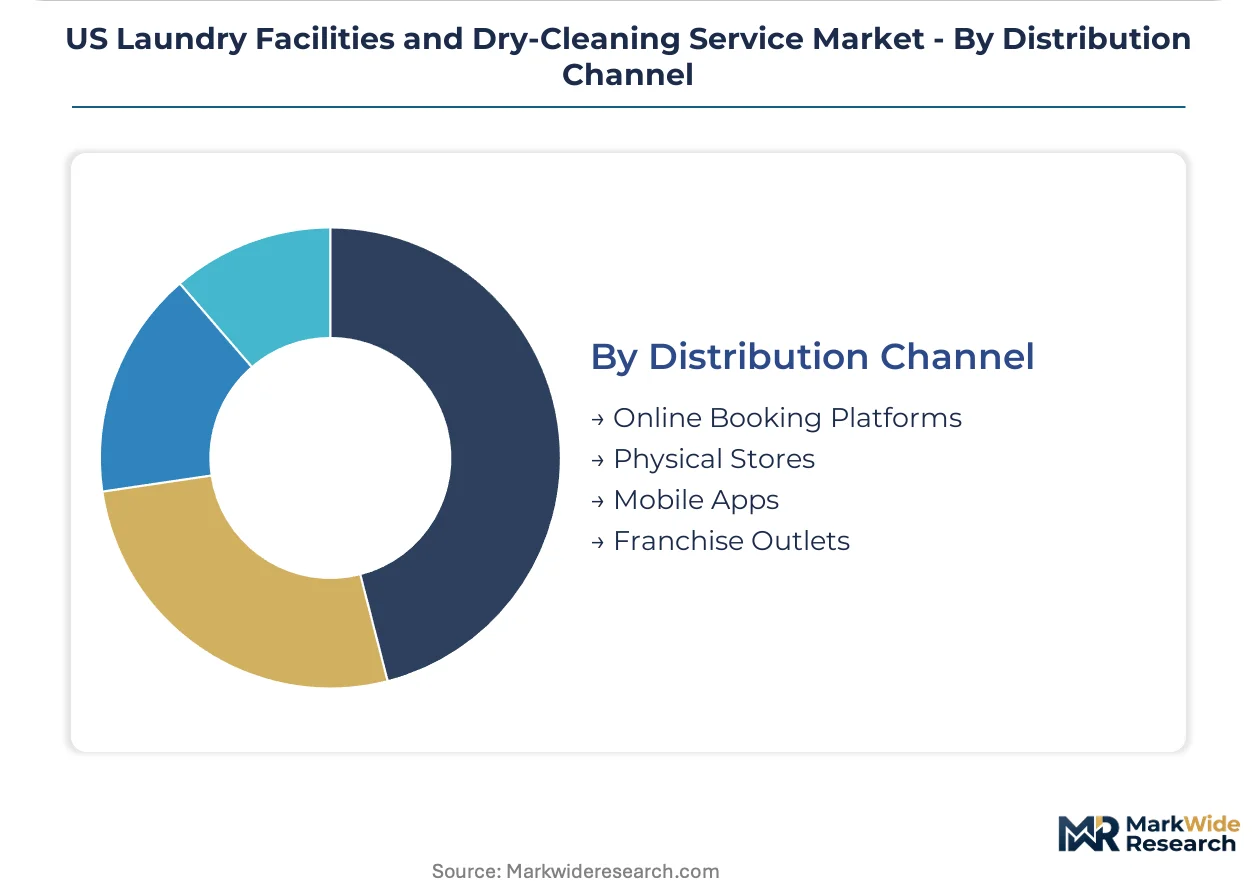
Distribution Channel:
Customer acquisition economics favor digital interfaces in dense metropolitan markets, though franchise networks retain strength in suburban and exurban geographies.
- Online Booking Platforms:Web-based scheduling interfaces compress customer acquisition cycles for route-based operators. These channels lose transaction volume to mobile-native alternatives in younger demographics.
- Physical Stores:Traditional storefront models in dense metropolitan markets face volume erosion from pickup logistics. California and New York retain higher storefront density due to regulatory complexity favoring established operators.
- Mobile Apps:App-integrated pickup logistics compete directly with storefront models. Texas and Florida exhibit fastest adoption as apartment operators consolidate through exclusive service contracts.
- Franchise Outlets:Branded networks providing standardized service protocols and centralized marketing support.
Physical Stores anchors the volume base while Mobile Apps gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in California metropolitan corridors exceeds Texas Sun Belt markets by roughly 20-25% due to stricter EPA compliance costs and premium service positioning. Texas and Florida operators compensate through route density and volume scale across multifamily housing clusters.
California
Los Angeles and San Francisco metropolitan areas absorb the nation's highest per-pound processing costs as EPA emission standards compress equipment retirement timelines. The state's Air Resources Board enforces solvent handling protocols that accelerate wet-cleaning substitution. San Diego's hospitality corridor expands outsourced linen contracts to specialized providers managing compliance burdens.
Texas
Dallas-Fort Worth and Houston multifamily density sustains route-based pickup economics with concentrated delivery zones across apartment complexes. OSHA workplace exposure limits apply less stringently than coastal states, preserving traditional chemical process options. Austin's tech-sector workforce drives fastest adoption of app-integrated booking platforms among Sun Belt metros.
Florida
Miami and Tampa Bay hospitality sectors yield highest per-pound revenue as hotels shift capital burden to specialized linen managers. The state environmental regulator monitors solvent discharge with lighter enforcement than California or New York. Orlando's tourism corridor concentrates industrial tunnel washer deployment for bulk textile processing.
New York
New York City storefront density retains strength despite digital channel migration, as regulatory complexity favors established operators with legacy compliance infrastructure. The state's Department of Environmental Conservation enforces perchloroethylene handling rules that accelerate equipment turnover. Buffalo and Rochester industrial laundries serve institutional contracts with long-term stability.
Illinois
Chicago metropolitan area anchors Midwest volume with balanced exposure to commercial, institutional, and residential demand tiers. EPA Region 5 oversight shapes solvent choice for dry-cleaning operators across Cook County. The city's logistics infrastructure supports route-based operators optimizing fleet density under NHTSA commercial vehicle regulations.
US Laundry Facilities and Dry-Cleaning Service Market Key Industry Players
Concentration sits with national route-based networks and multifamily service specialists rather than fragmented storefront operators. The market structure reveals three distinct tiers: scaled infrastructure players controlling coin-operated machine networks, app-integrated pickup services compressing customer acquisition cycles, and specialty restoration boutiques commanding premium pricing. Consolidation pressure favors operators with dedicated logistics infrastructure and exclusive property management contracts. M&A activity targets mid-scale dry-cleaning operations facing compressed EPA compliance windows.
Within the infrastructure-heavy tier, CSC ServiceWorks Inc. and WASH Multifamily Laundry Systems LLC anchor national presence through machine network scale and exclusive service contracts. Tide Cleaners occupies the digital-native vector with app-integrated logistics competing against traditional storefront models. These three exemplify how capital deployment diverges between legacy equipment networks and technology-enabled route optimization.
| Leading Market Players |
|---|
| Rinse, Inc. |
| Mulberrys Garment Care |
| Tide Cleaners |
| ByNext Inc. |
| CSC ServiceWorks Inc. |
| Lapels Dry Cleaning |
| CD One Price Cleaners |
| WASH Multifamily Laundry Systems LLC |
| Martinizing International LLC |
| Others |
Cost & Logistics Intelligence
Thirty-to-forty-five day equipment procurement lead times for industrial tunnel washer systems concentrate capital deployment among scaled operators with balance-sheet capacity, compressing pricing power for mid-scale dry-cleaning boutiques facing simultaneous EPA compliance cost absorption. This inventory-to-pricing feedback loop favors route-based networks with exclusive multifamily contracts over fragmented storefront models.
Pricing Analysis
The customization-premium spread between standard per-pound linen processing and specialized wedding gown or archival textile restoration spans roughly 3-4x in metropolitan California corridors, where EPA compliance costs embed in rate structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by service speed, fabric complexity, and pickup logistics integration. Pricing pressure stems from wet-cleaning technology cost compression as aqueous systems achieve solvent-comparable performance for delicate fabrics. Hospitality sector buyers exhibit lowest price sensitivity due to outsourced capital burden shifting, while residential laundromat customers in lower-income zip codes face highest elasticity.
Supply Chain Analysis
Just-in-time solvent inventory management dominates traditional dry-cleaning operations, though liquid carbon dioxide system operators maintain strategic stockpiles of pressurized feedstock to preempt supply interruption. Equipment manufacturing concentrates in Italy, Germany, and China for industrial tunnel washer systems, while petrochemical solvent production draws from Texas Gulf Coast and Rotterdam refining clusters. Raw material dependencies span perchloroethylene feedstocks, stainless steel for washer construction, and IoT sensor components for smart machine networks. Single-source vulnerability sits with European tunnel washer OEMs for 400-pound continuous-batch systems. Distribution runs through regional equipment distributors and direct manufacturer relationships for large-scale hospitality installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate wet-cleaning substitution that threatens solvent-dependent revenue streams while consolidating route density to defend margin structures. The EPA perchloroethylene phase-out compresses strategic response windows.
For Market Incumbents: Secure exclusive service contracts with Sun Belt multifamily property operators to lock in route density before digital-native competitors achieve critical mass. Acquire mid-scale dry-cleaning operations facing compressed EPA compliance timelines to consolidate market position and retrofit with wet-cleaning infrastructure. Vertical integration into fleet logistics under NHTSA compliance frameworks creates sustainable cost advantages over fragmented storefront competitors. For New Entrants and Emerging Players: Differentiate on app-integrated pickup logistics targeting Texas and Florida metropolitan corridors where apartment operator consolidation favors digital booking interfaces. Target specialty restoration services for wedding gown and archival textile segments where premium pricing and limited competitive saturation enable margin capture. Pursue white-label linen management partnerships with regional hospitality chains seeking capital burden shifting without national vendor scale requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from private-equity-owned hospitality service platforms seeking to divest non-core linen management divisions. Long-term viability hinges on technology transition completion from solvent-based to aqueous and liquid carbon dioxide systems over the coming decade. Monitor EPA enforcement acceleration in California and New York metropolitan areas as inflection indicator for distressed asset availability and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Wet-Cleaning Technology Deployment | EPA perchloroethylene phase-out mandates accelerate capital rotation toward aqueous systems. |
| Route Density Optimization | NHTSA fleet compliance frameworks favor scaled operators with dedicated logistics infrastructure. |
| Smart Machine Network Expansion | IoT-enabled payment platforms penetrate lower-income zip codes with operational visibility gains. |
| Exclusive Property Contracting | Apartment operator consolidation in Sun Belt metros locks in stable volume bases. |
| Specialty Service Premium Positioning | Wedding gown and archival restoration segments command pricing power with limited saturation. |
Research Approach
Initial hypotheses were tested against primary input from laundry facility operators, hospitality procurement directors, multifamily property managers, and EPA compliance officers, then refined through secondary validation across SEC filings, EPA enforcement databases, hospitality industry trade publications, and multifamily housing construction permits. Bottom-up triangulation combined equipment shipment data with route-density mapping, while top-down validation referenced national employment statistics and solvent import records.
Variance decomposition across service type, customer tier, technology platform, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory compliance timeline modeling, and hospitality outsourcing penetration curves. Forecast inputs incorporated EPA perchloroethylene phase-out schedules and smart machine installation trajectories in Sun Belt metropolitan corridors.
Material uncertainties — EPA enforcement acceleration, petrochemical feedstock price volatility, multifamily construction cycle downturns — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory compliance cost pass-through. Revision becomes warranted when wet-cleaning performance certification crosses thresholds triggering accelerated solvent system retirement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Bowling Centers Market