
 Luxury Hospitality Market | 2026-2036
Luxury Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Hospitality Market Analysis
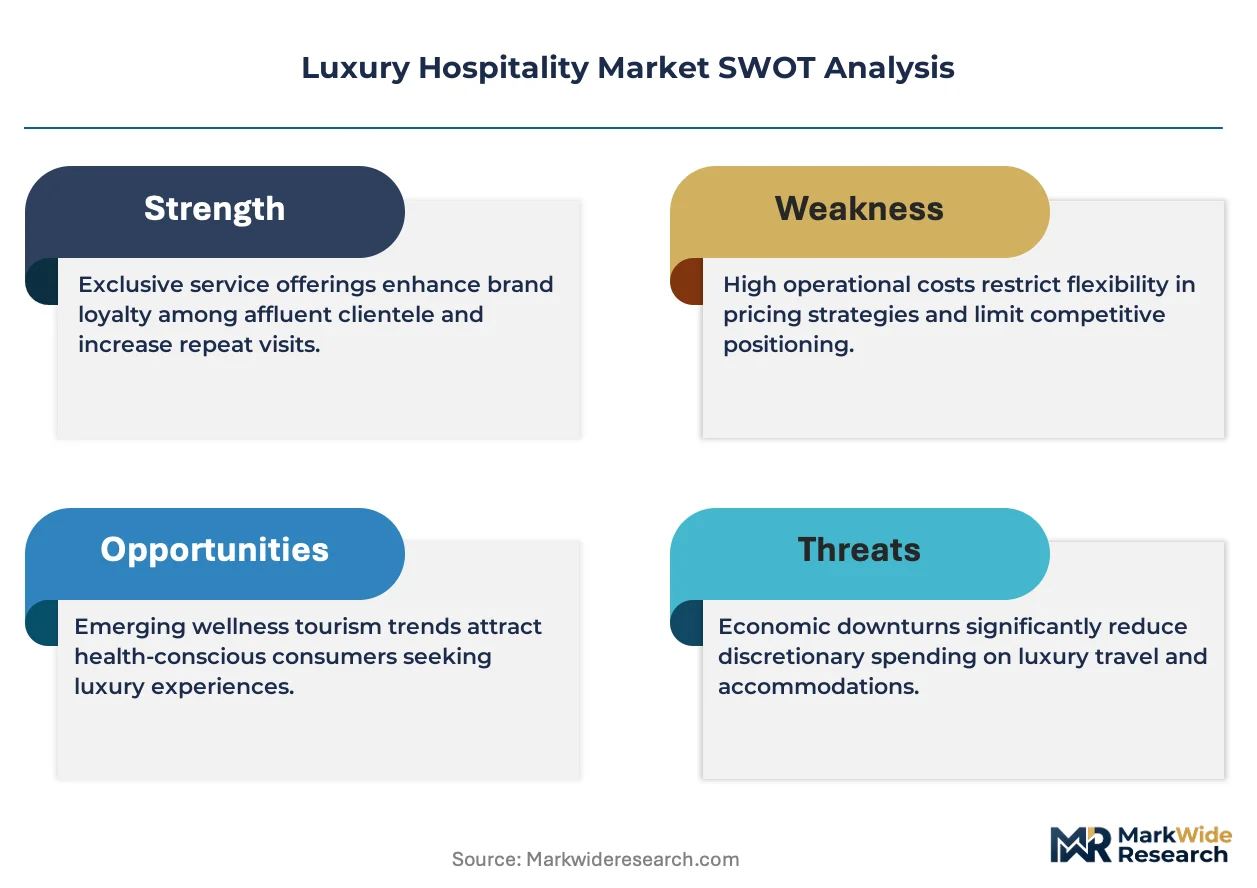
Artificial intelligence-driven personalization is rewriting guest journey orchestration across the luxury hospitality technology stack. Marriott International leverages predictive analytics to anticipate guest preferences before check-in, while Four Seasons Hotels and Resorts anchors its competitive stance on proprietary mobile concierge platforms. Hilton Worldwide differentiates through integrated smart-room ecosystems that unify climate, entertainment, and service requests.
Luxury hospitality encompasses premium accommodation and experiential services characterized by staff-to-guest ratios exceeding one-to-one, bespoke amenity programming, and architectural distinction designed to deliver exceptional comfort and status affirmation. The sector serves affluent individuals and corporate clients seeking exclusivity, privacy, and cultural authenticity beyond standard lodging utility. Hotel and resort properties within the service type dimension dominate current revenue pools, while wellness packages and fine dining offerings command the highest margin contributions. Cultural immersion experiences represent the fastest-growing segment as affluent travelers prioritize authentic local engagement over standardized luxury tropes.
The U.S. Food and Drug Administration and Occupational Safety and Health Administration shape operational standards for spa and wellness facilities within U.S. luxury properties, while the EU Green Deal and CSRD reporting requirements drive sustainability capital allocation across European portfolios. These frameworks elevate compliance costs but simultaneously create competitive separation for properties achieving third-party environmental certification. Stakeholders must evaluate whether to prioritize scale-driven technology standardization or preserve boutique operational autonomy as guest expectations polarize between seamless digital integration and handcrafted service irreproducibility.
Market Dynamics
Ultra-high-net-worth leisure travelers now concentrate demand in experiential luxury retreats across the Maldives, French Riviera, and Japanese alpine regions, compressing booking windows and elevating staff-to-guest ratio requirements as the defining operational metric.
Growth Catalysts
- EU Corporate Sustainability Reporting Directive:Mandatory environmental disclosure requirements compel major hotel groups to pursue third-party certification, creating competitive separation for early adopters across European portfolios.
- Wellness programming:Spa and integrative health offerings command the highest margin contributions within ancillary revenue pools, with affluent travelers extending average length of stay to access multi-day treatment protocols.
- Experiential travel concentration:Cultural immersion experiences represent accelerating demand as guests prioritize authentic local engagement over standardized luxury amenities in Maldives, Kyoto, and Provence properties.
Market Restraints
- Specialized hospitality labor scarcity:Trained butlers, sommeliers, and wellness practitioners command premium compensation that compresses operating margins at properties maintaining one-to-one staff ratios.
- Architectural distinction requirements:Bespoke design mandates and heritage preservation constraints in European and Japanese markets extend development timelines and elevate capital intensity per key.
- Wellness facility compliance:FDA and OSHA operational standards for U.S. spa facilities impose ongoing inspection protocols and documentation burdens that elevate administrative overhead.
Strategic Opportunities
- Japanese alpine expansion:Underdeveloped ryokan-adjacent luxury positioning in Nagano and Hokkaido prefectures offers white space for properties integrating onsen thermal bathing with contemporary service standards.
- Smart-room convergence:Unified climate, entertainment, and service request platforms enable predictive personalization that reduces friction while preserving operational autonomy at boutique properties.
- EU Green Deal alignment:Sustainability capital allocation incentives reward properties achieving energy efficiency benchmarks, with preferential financing terms available for certified new developments.
Industry Challenges
- Digital-handcrafted service balance:Guest expectations polarize between seamless mobile concierge integration and irreproducible human-delivered experiences, forcing capital allocation trade-offs between technology stacks and artisan staffing.
- Third-party certification timelines:Environmental verification processes for LEED, BREEAM, and Green Key credentials extend pre-opening schedules by 8-14 months, compressing revenue realization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Hospitality Market |
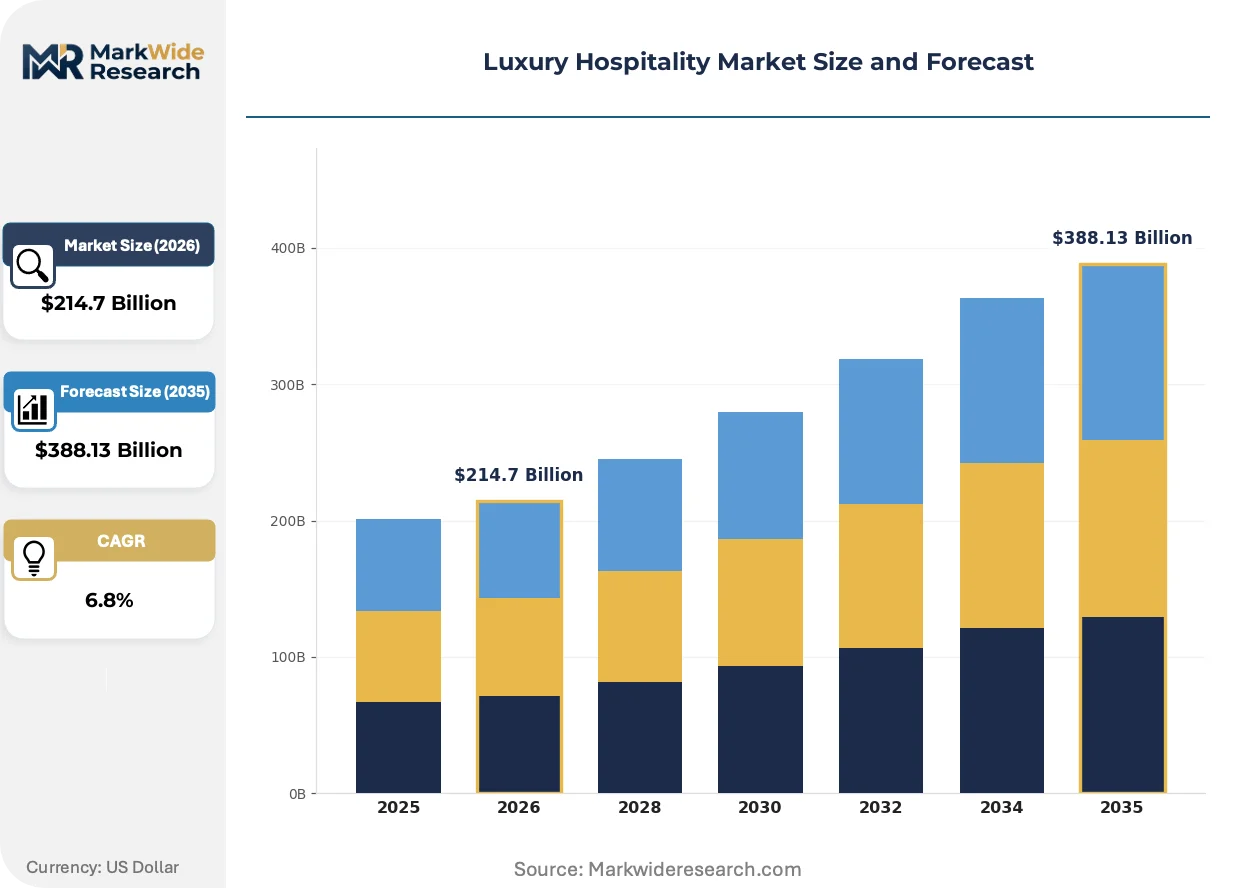
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotel, Resort, Spa, Lodging Customer Type: Business Traveler, Leisure Traveler, Event Organizer, Travel Agency Offering: Room Service, Concierge, Fine Dining, Wellness Packages Experience Type: Luxury Retreat, Urban Escape, Destination Experience, Cultural Immersion |
| Companies Covered | InterContinental Hotels Group (IHG Hotels & Resorts), Jin Jiang International, Marriott International, Hyatt Hotels Corporation, H World Group, Accor Group, Wyndham Hotels & Resorts, Four Seasons Hotels and Resorts, Hilton Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Hospitality Market Emerging Trajectories
Artificial intelligence-driven personalization is rewriting guest journey orchestration across the luxury hospitality technology stack, compressing the gap between predictive capability and handcrafted service delivery while regulatory sustainability mandates reshape capital allocation priorities.
Predictive analytics platforms are migrating from post-booking preference surveys to pre-arrival behavioral inference based on historical stay patterns, social signal analysis, and third-party data partnerships. Ultra-high-net-worth travelers now expect anticipatory service configuration before property contact, with affluent corporate accounts demanding seamless itinerary integration across multi-property portfolios. This capability compression is eliminating the traditional discovery phase of guest-staff interaction, forcing properties to invest in data infrastructure or cede positioning to technology-forward competitors.
CSRD reporting requirements and EU Green Deal implementation are mandating granular environmental impact disclosure across European luxury portfolios. Properties must now document Scope 1-3 emissions, water consumption intensity, and biodiversity impact metrics in audited annual filings. European resort developments in the Maldives and French Riviera are responding by embedding renewable energy microgrids and closed-loop water systems into architectural specifications from conception rather than retrofit.
Affluent travelers are consolidating booking authority with specialized luxury travel advisors and direct property relationships, bypassing traditional online travel aggregators for high-complexity multi-destination itineraries. This channel compression privileges properties maintaining dedicated reservation teams capable of bespoke itinerary construction over standardized booking engine interfaces. The Maldives and Japanese alpine markets exhibit the most pronounced advisor dependency, with ultra-high-net-worth segments rarely completing transactions through third-party platforms.
Luxury Hospitality Market Segmentation
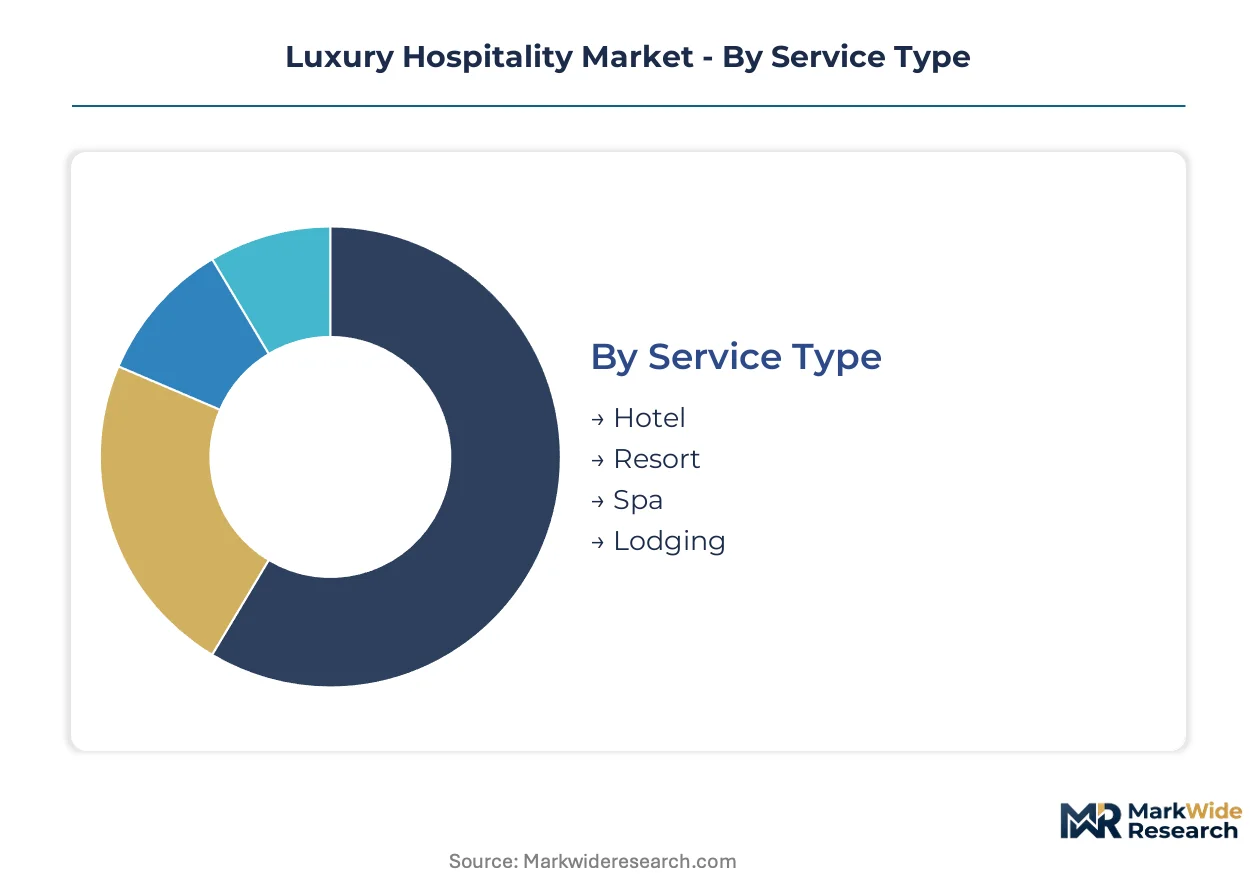
Luxury hospitality segmentation reveals divergent capital intensity and guest lifecycle patterns across service formats. Distinct operational models govern how properties allocate resources between fixed infrastructure and programmable experiences.
Service Type:
Booking velocity varies dramatically across physical formats, with extended-stay resort assets turning inventory slower than urban transient properties while commanding premium rate premiums per night.
- Hotel:Vertical structures in gateway cities concentrate corporate account volume and short-break leisure demand. Metropolitan properties in New York, London, and Tokyo optimize revenue per available room through dynamic pricing algorithms and loyalty program integration.
- Resort:Sprawling leisure compounds across Maldives atolls and French Riviera coastlines anchor experiential programming with multi-night minimums. These assets carry higher capital costs per key but generate superior ancillary spend through captive dining and recreation ecosystems.
- Spa:Dedicated wellness facilities command day-visitor revenue and property-hotel hybrid models.
- Lodging:Boutique inventory in heritage structures and alpine chalets serves niche privacy requirements.
Hotel properties dominate installed base across urban centers worldwide. Resort assets are where expansion concentrates as developers chase experiential demand in coastal and alpine clusters.
Customer Type:
Spend concentration tilts toward individuals booking direct rather than intermediated channels, with procurement authority fragmenting across corporate travel managers and independent advisors.
- Business Traveler:Corporate account road warriors prioritize location efficiency and seamless expense integration over amenity depth. Urban luxury properties in financial districts capture this volume through negotiated rate structures and meeting facility access.
- Leisure Traveler:Ultra-high-net-worth individuals drive rate integrity through direct booking relationships and advisor-mediated itinerary construction. Maldives and Japanese alpine markets exhibit near-total advisor dependency for this segment.
- Event Organizer:Group procurement specialists negotiate block commitments for weddings, corporate retreats, and milestone celebrations.
- Travel Agency:Intermediary advisors retain influence in complex multi-destination luxury construction.
Leisure travelers dominate rate premium realization. Business travelers are where volume stability concentrates for urban portfolio operators.
Offering:
Margin contribution stratifies sharply between commoditized room nights and high-touch programmed services requiring specialized labor deployment.
- Room Service:In-suite dining operations leverage existing kitchen infrastructure with premium pricing multipliers. Properties in Dubai and Singapore differentiate through 24-hour chef availability and personalized menu curation.
- Concierge:Human-delivered itinerary construction and access brokerage commands outsized guest satisfaction scores. Four Seasons and Mandarin Oriental properties invest disproportionately in concierge headcount to secure irreproducible local relationships.
- Fine Dining:Chef-driven restaurant concepts attract non-resident revenue and media positioning.
- Wellness Packages:Integrative health programming extends length of stay through multi-day treatment protocols.
Room service dominates transaction frequency. Wellness packages are where margin expansion concentrates as travelers extend stays for sequential treatments.
Experience Type:
Development capital flows toward formats enabling territorial exclusivity and programmable narrative depth rather than standardized luxury replication.
- Luxury Retreat:Secluded compounds emphasizing privacy and disconnection command the highest rate premiums per square meter. Properties in Maldives private atolls and Bhutanese valleys restrict guest counts below fifty to preserve intimacy thresholds.
- Urban Escape:Metropolitan properties curate sanctuary positioning within dense commercial districts. Aman Tokyo and Park Hyatt properties exemplify this format through vertical spatial design and acoustic isolation engineering.
- Destination Experience:Location-centric programming builds itineraries around singular natural or architectural features.
- Cultural Immersion:Authentic local engagement replaces standardized amenities with craft workshops, indigenous cuisine, and community access.
Urban escape properties dominate geographic coverage density. Cultural immersion is where development interest concentrates as guests reject homogenized luxury tropes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth leisure travelers concentrate demand in experiential luxury retreats across specific coastal and alpine clusters worldwide, compressing booking windows and elevating staff-to-guest ratio requirements as the defining operational metric.
United States
Corporate account volume and short-break leisure demand drive urban luxury performance in New York, Miami, and Los Angeles. FDA and OSHA operational standards for spa facilities impose ongoing inspection protocols that elevate administrative overhead. Aspen and Napa Valley anchor experiential resort development where wellness programming extends average length of stay.
France
Heritage preservation constraints in Provence and the French Riviera extend development timelines while commanding rate premiums for architectural distinction. EU Green Deal implementation and CSRD reporting requirements mandate granular environmental impact disclosure across Parisian and coastal portfolios. Cannes and Saint-Tropez concentrate ultra-high-net-worth leisure demand through exclusive beach club and yacht-accessible properties.
Japan
Underdeveloped ryokan-adjacent luxury positioning in Nagano and Hokkaido prefectures offers white space for properties integrating onsen thermal bathing with contemporary service standards. METI energy efficiency benchmarks incentivize renewable energy microgrids in new alpine developments. Kyoto properties anchor cultural immersion demand as affluent travelers prioritize authentic local engagement.
Maldives
Private atoll resorts restrict guest counts below fifty to preserve intimacy thresholds while generating superior ancillary spend through captive dining ecosystems. Environmental verification processes for Green Key credentials extend pre-opening schedules. Malé and Baa Atoll concentrate development interest where closed-loop water systems address freshwater scarcity constraints.
United Arab Emirates
Dubai and Abu Dhabi optimize revenue per available room through dynamic pricing algorithms and loyalty program integration targeting corporate road warriors. MOHAP wellness facility standards shape spa operational compliance across beachfront and desert resort portfolios. Palm Jumeirah and Saadiyat Island anchor architectural distinction requirements with bespoke design mandates.
Luxury Hospitality Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. The vendor base spans multinational hotel groups, regional luxury operators, and independent boutique properties. Three archetypes dominate: scale-driven technology standardizers, boutique operational autonomy preservers, and wellness-anchored experience curators. Portfolio diversification and geographic expansion constitute the dominant competitive moves as groups chase experiential demand in underdeveloped alpine and coastal clusters.
Within the scale-driven tier, Marriott International, Hilton Worldwide, and InterContinental Hotels Group exemplify channel-controlling positioning through loyalty program integration and multi-property portfolio construction. These multinational operators sit alongside boutique specialists like Four Seasons Hotels and Resorts, which anchors competitive stance on proprietary mobile concierge platforms and irreproducible human-delivered experiences. Hyatt Hotels Corporation occupies a position between these archetypes, balancing technology infrastructure with artisan staffing ratios.
| Leading Market Players |
|---|
| InterContinental Hotels Group (IHG Hotels & Resorts) |
| Jin Jiang International |
| Marriott International |
| Hyatt Hotels Corporation |
| H World Group |
| Accor Group |
| Wyndham Hotels & Resorts |
| Four Seasons Hotels and Resorts |
| Hilton Worldwide |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Maldives resort development compresses rate premiums while elevating capital intensity per key, forcing developers to choose between extended payback periods or reduced amenity specifications. This utilization dynamic simultaneously pressures procurement timelines for bespoke furnishings and specialized wellness equipment.
Pricing Analysis
Cost-plus contracts with labor indexation dominate resort construction agreements, particularly for European and Japanese alpine developments where heritage preservation mandates extend build schedules. Three-tier pricing structure across ultra-luxury, premium, and selective-service levels separates properties by staff-to-guest ratios and certification status. Pricing pressure stems from compressed booking windows in Maldives and French Riviera markets as ultra-high-net-worth travelers consolidate authority with specialized advisors. Corporate road warriors exhibit highest price sensitivity through negotiated rate structures, while leisure travelers booking direct demonstrate lowest sensitivity to rate premiums.
Supply Chain Analysis
Tariff exposure between Italy and China for marble and stone finishes dominates procurement risk matrices for architectural distinction mandates. Supply draws from Italy, India, and Turkey for premium surface materials, with Portugal and Spain anchoring bespoke textile sourcing. Specialized hospitality labor scarcity in France and Japan constrains operational ramp schedules. Single-source vulnerability concentrates in Maldives desalination equipment and Japanese alpine geothermal infrastructure. Distribution runs through direct property relationships and specialized luxury travel advisors, bypassing traditional online travel aggregators for high-complexity itineraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxury hospitality sits in early-cycle expansion as experiential travel concentration accelerates cultural immersion programming across underdeveloped alpine and coastal clusters. Ultra-high-net-worth leisure travelers now drive substantial booking volume through advisor-mediated channels.
For Market Incumbents: Entrench competitive position through proprietary mobile concierge platform investment and third-party environmental certification acceleration ahead of CSRD disclosure mandates. Defend against boutique operational autonomy preservers by embedding predictive analytics across multi-property portfolios. Prioritize vertical integration into wellness programming and fine dining concepts to capture highest-margin ancillary revenue pools. For New Entrants and Emerging Players: Underdeveloped ryokan-adjacent luxury positioning in Nagano and Hokkaido prefectures represents the most penetrable entry point, combining onsen thermal bathing with contemporary service standards. Maldives private atoll development with sub-fifty guest counts offers white space for territorial exclusivity plays. Target direct advisor relationships and dedicated reservation teams capable of bespoke itinerary construction rather than standardized booking engines. For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because EU Green Deal alignment and CSRD reporting requirements will structurally reward early environmental adopters with preferential financing terms. Acquisition targets should demonstrate third-party credentials and energy efficiency benchmarks. The signal to watch is compressed pre-opening timelines as certification processes accelerate or delay revenue realization windows.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Environmental Certification | CSRD mandates create competitive separation for LEED and Green Key achievers across European portfolios. |
| Proprietary Mobile Concierge Platform | Four Seasons and Mandarin Oriental anchor differentiation through irreproducible human-delivered digital integration. |
| Wellness Programming Expansion | Spa and integrative health offerings command highest margin contributions within ancillary revenue pools. |
| Japanese Alpine Development | Nagano and Hokkaido prefectures offer white space for onsen-integrated contemporary luxury positioning. |
| Direct Advisor Relationship Investment | Maldives and Japanese markets exhibit near-total advisor dependency for ultra-high-net-worth segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of property development filings, EU regulatory disclosure databases, and hospitality trade association reports. Primary interviews engaged resort development executives, luxury travel advisors, spa operations directors, and sustainability certification specialists. Secondary validation drew from CSRD implementation guidance, METI energy efficiency benchmarks, FDA spa facility standards, and Maldives environmental ministry records. Bottom-up property-level data triangulates against top-down market sizing from installed base analysis.
Forecast inputs include service type segmentation across hotel, resort, spa, and lodging formats; customer type differentiation between business and leisure travelers; and experience type stratification from urban escape to cultural immersion. CAGRs derive from capacity expansion pipelines, booking velocity trends, and ancillary spend per guest night across the projection horizon. Industry-specific inputs incorporate staff-to-guest ratio requirements, heritage preservation timeline constraints, and wellness facility compliance burdens.
Stress conditions across labor scarcity intensity, certification timeline extensions, and advisor channel consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on sustained ultra-high-net-worth travel demand and regulatory adherence trajectories. Material shifts in EU Green Deal implementation scope or Maldives freshwater scarcity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Catering Services Market