
 US Wedding Services Market | 2026-2036
US Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Wedding Services Market Insights
Destination wedding demand is expanding as couples prioritize experiential travel over traditional hometown ceremonies. The Knot Worldwide Inc. leverages its digital platform ecosystem to control vendor discovery and booking workflows across fragmented local markets. Zola, Inc. sustains brand strength through integrated registry and planning tools that reduce vendor coordination friction. XO Group Inc. anchors competitive positioning in content-rich wedding media that shapes couple preferences upstream of purchase decisions.
US Wedding Services encompass coordinated professional activities spanning event design, vendor orchestration, logistics management, and guest experience execution, typically delivered through project-based contracts with 12-18 month planning horizons. Catering and venue rental segments represent mature revenue pools with established pricing benchmarks, while videography services capture expanding margin contributions as social media deliverables become standard contract inclusions. Photography maintains structural leadership in per-couple spend allocation, though day-of coordination offerings grow fastest as couples seek professional oversight without full planning retainers.
Federal labor regulations through the Department of Labor shape vendor employment classifications and overtime obligations across catering and venue staffing. State-level alcohol beverage control boards govern catering licensing requirements that vary across California, Florida, and Texas jurisdictions. The Internal Revenue Service oversees 1099 contractor classification rules affecting freelance photographer and videographer engagement structures. Stakeholders must monitor evolving gig-economy regulatory interpretations that could restructure vendor cost models and service delivery architectures.
Market Dynamics
Social media content creation requirements are restructuring vendor selection criteria across the US Wedding Services Market, forcing photography and videography providers to bundle digital deliverables into standard service contracts.
Growth Catalysts
- Destination Wedding Expansion:Millennial and Gen-Z couples are prioritizing experiential travel ceremonies over traditional hometown events, creating demand for full-service destination coordination packages in California, Florida, and Texas metropolitan clusters.
- IRA Tax Incentives:The Inflation Reduction Act's energy efficiency credits are prompting venue operators to upgrade lighting and HVAC systems, accelerating venue modernization investments that elevate service pricing power.
- Drone Videography:Aerial capture technology is integrating into standard wedding packages, enabling cinematic outdoor coverage that commands premium positioning against traditional ground-based cinematography.
Market Restraints
- Labor Classification Uncertainty:Internal Revenue Service 1099 contractor rules create compliance friction for freelance photographer and videographer engagement structures, elevating administrative overhead for multi-vendor event coordination.
- Supply Concentration Risk:Premium venue density concentrates in California, Florida, and Texas metropolitan corridors, limiting accessible inventory in secondary markets and inflating regional pricing disparities.
- Substitution Threat:AI-powered photo editing and automated highlight reel generation tools threaten commoditization of post-production services, compressing margins for editing-intensive vendors.
Strategic Opportunities
- Micro-Wedding Specialization:Intimate ceremony formats under 50 guests represent underpenetrated white space in Texas secondary cities, enabling turnkey package development with reduced vendor coordination complexity.
- OSHA Workplace Safety Alignment:Enhanced Occupational Safety and Health Administration guidelines for event staffing create differentiation pathways for caterers and venues investing in certified safety protocols.
- Livestreaming-Physical Hybrid:Real-time broadcast technology convergence with in-person execution is enabling destination-quality guest participation without travel requirements, expanding addressable guest counts per event.
Industry Challenges
- Day-of Coordination Talent Scarcity:Professional oversight services without full planning retainers face capacity constraints as demand outpaces certified coordinator supply in high-volume Florida markets.
- State Alcohol Licensing Fragmentation:California, Florida, and Texas beverage control boards maintain divergent catering licensing requirements, complicating multi-state vendor expansion and compliance standardization.
- Digital Asset Delivery Complexity:Social media platform format specifications multiply deliverable requirements, forcing videographers to maintain parallel editing workflows for TikTok, Instagram Reels, and traditional long-form outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wedding Services Market |
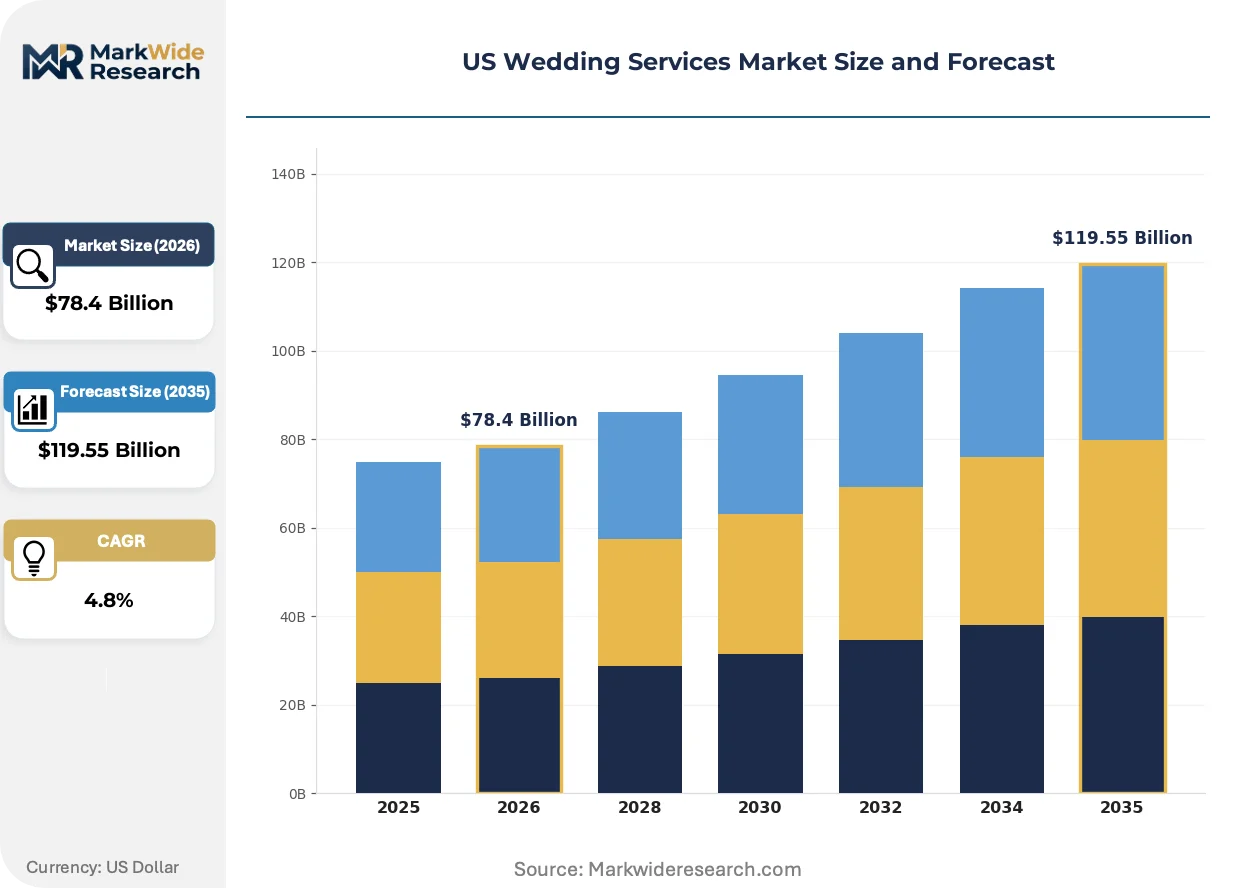
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Catering, Photography, Videography, Venue Rental Client Type: Couples, Wedding Planners, Families, Vendors Offering: Full-Service Planning, Partial Planning, Day-of Coordination, Venue Management Theme: Traditional, Modern, Destination, Themed |
| Companies Covered | The Knot Worldwide Inc., Zola, Inc., XO Group Inc., Bodas.net, Luxe Atlanta Events, Bustle Events, Mae&Co Creative, HauteFetes, Marcy Blum Associates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wedding Services Market Trends and Innovations
Technology adoption is compressing planning timelines while elevating digital deliverable expectations. Regulatory pressure on vendor employment structures is reshaping cost models. Couples are fragmenting service procurement across specialized providers rather than consolidated packages.
Drone cinematography is integrating into mainstream wedding videography packages, enabling aerial venue reveals and dynamic processional coverage previously reserved for luxury budgets. California and Florida outdoor venues are adopting this capability fastest, requiring FAA Part 107 certification for operators. The technology is compressing differentiation timelines as aerial footage becomes table stakes rather than premium positioning.
OSHA workplace safety enforcement is intensifying scrutiny of catering and venue staffing classifications, particularly around overtime obligations for multi-day destination events. California labor regulators are leading enforcement actions against misclassified event staff. Caterers operating across state lines face compliance complexity as Texas and Florida maintain divergent threshold calculations.
Guest list fragmentation is driving unbundled service procurement, with couples purchasing photography, videography, and coordination from separate specialists rather than consolidated planning agencies. Texas markets exhibit this pattern most acutely, where vendor specialization density enables competitive shopping. Digital-native couples are managing coordination through self-directed platform tools, reducing reliance on full-service planning retainers.
US Wedding Services Market Segmentation
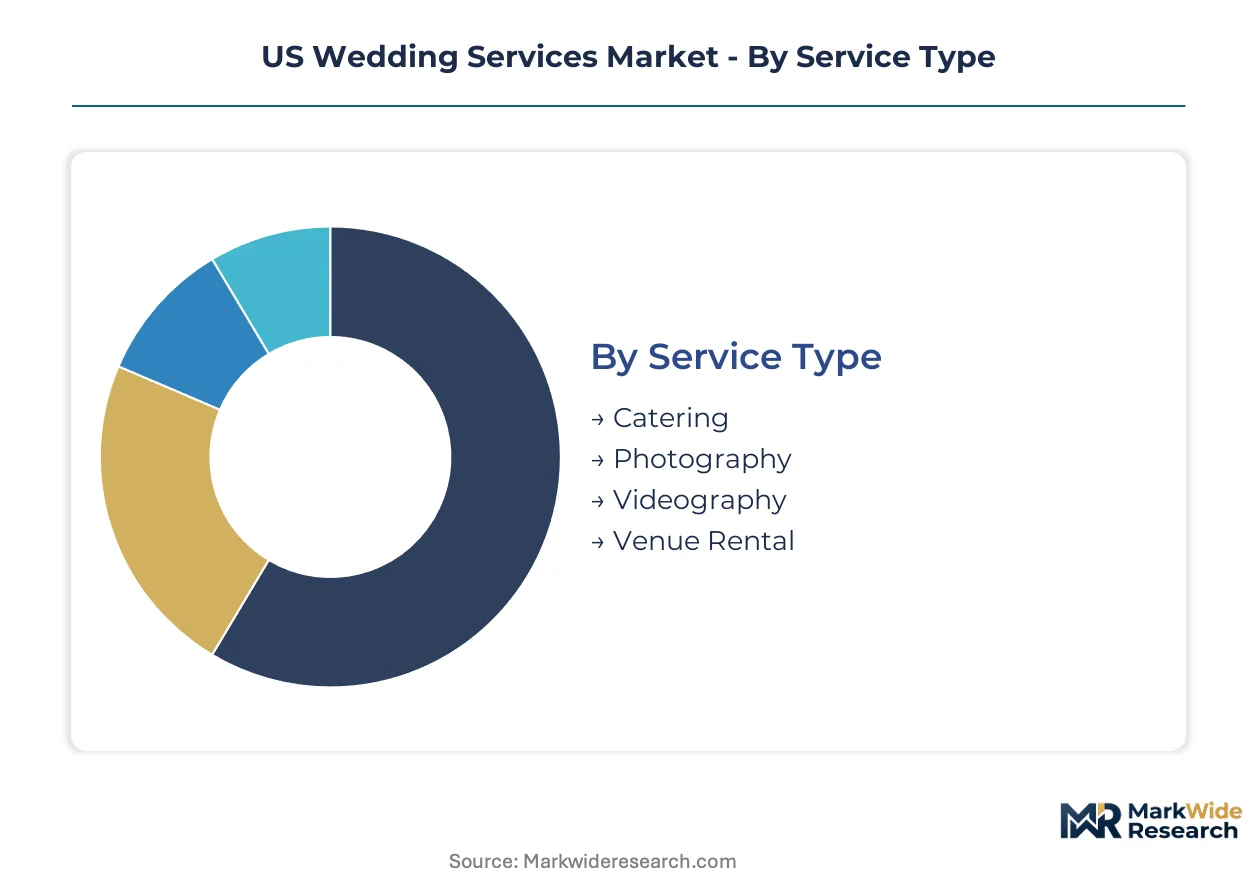
Service fragmentation across the US Wedding Services Market creates distinct procurement patterns. Couples now unbundle offerings across specialized providers rather than accepting consolidated packages. Vendor selection criteria vary sharply by segment, with digital deliverables reshaping photography and videography contracts.
Service Type:
Culinary execution and visual documentation technologies define competitive differentiation across professional wedding services.
- Catering:Menu engineering spans plated service, buffet formats, and station-based dining with dietary accommodation protocols. California and Florida metropolitan clusters concentrate premium catering demand where per-guest spending benchmarks exceed national averages. OSHA workplace safety enforcement intensifies staffing cost structures for multi-day destination events.
- Photography:Digital capture workflows now mandate same-day editing suites and social media-optimized deliverables. Texas secondary cities exhibit fastest adoption of unbundled photography procurement as couples bypass full-service agencies. FAA Part 107 certification requirements for drone operators compress margin structures for aerial coverage specialists.
- Videography:Cinematic editing packages integrate TikTok and Instagram Reels formats alongside traditional long-form outputs. Demand concentrates in destination wedding corridors where aerial venue reveals command premium positioning.
- Venue Rental:Inventory scarcity in California, Florida, and Texas metropolitan clusters inflates regional pricing disparities. IRA tax incentives accelerate HVAC and lighting modernization investments that elevate service pricing power.
Catering leads on scale; videography leads on momentum.
Client Type:
Procurement authority distributes across direct consumers and intermediary coordinators with divergent contract structures.
- Couples:Digital-native millennials and Gen-Z partners self-direct vendor discovery through platform tools, reducing traditional planner intermediation. California and Florida exhibit highest direct-to-vendor booking rates.
- Wedding Planners:Full-service coordinators maintain preferred vendor networks that streamline multi-contract orchestration. Texas markets show planner consolidation as vendor specialization density enables competitive package assembly.
- Families:Multi-generational funding participation expands budget ceilings but complicates decision authority. Secondary market penetration lags where planner density remains thin.
- Vendors:Subcontractor relationships between primary service providers and specialty operators create layered liability structures. IRS 1099 classification rules elevate administrative overhead for freelance engagement models.
Couples lead on volume expansion; wedding planners lead on contract value concentration.
Offering:
Service depth tiers align with couple time availability and coordination confidence levels.
- Full-Service Planning:Twelve-to-eighteen month horizon contracts encompass vendor curation, design conceptualization, and day-of execution oversight. Premium pricing corridors concentrate in California metropolitan clusters.
- Partial Planning:Mid-engagement entry points address couples who initiated self-directed procurement but require professional intervention. Florida markets exhibit fastest uptake as destination complexity overwhelms initial DIY approaches.
- Day-of Coordination:Professional oversight without planning retainers represents the steepest expansion trajectory across Texas high-volume markets. Certified coordinator supply constraints create capacity bottlenecks.
- Venue Management:On-site coordination bundled with rental contracts reduces vendor count but limits customization flexibility. Secondary city penetration remains underdeveloped relative to metropolitan corridors.
Full-service planning leads on revenue per contract; day-of coordination leads on volume growth velocity.
Theme:
Aesthetic positioning drives vendor specialization requirements and location selection criteria.
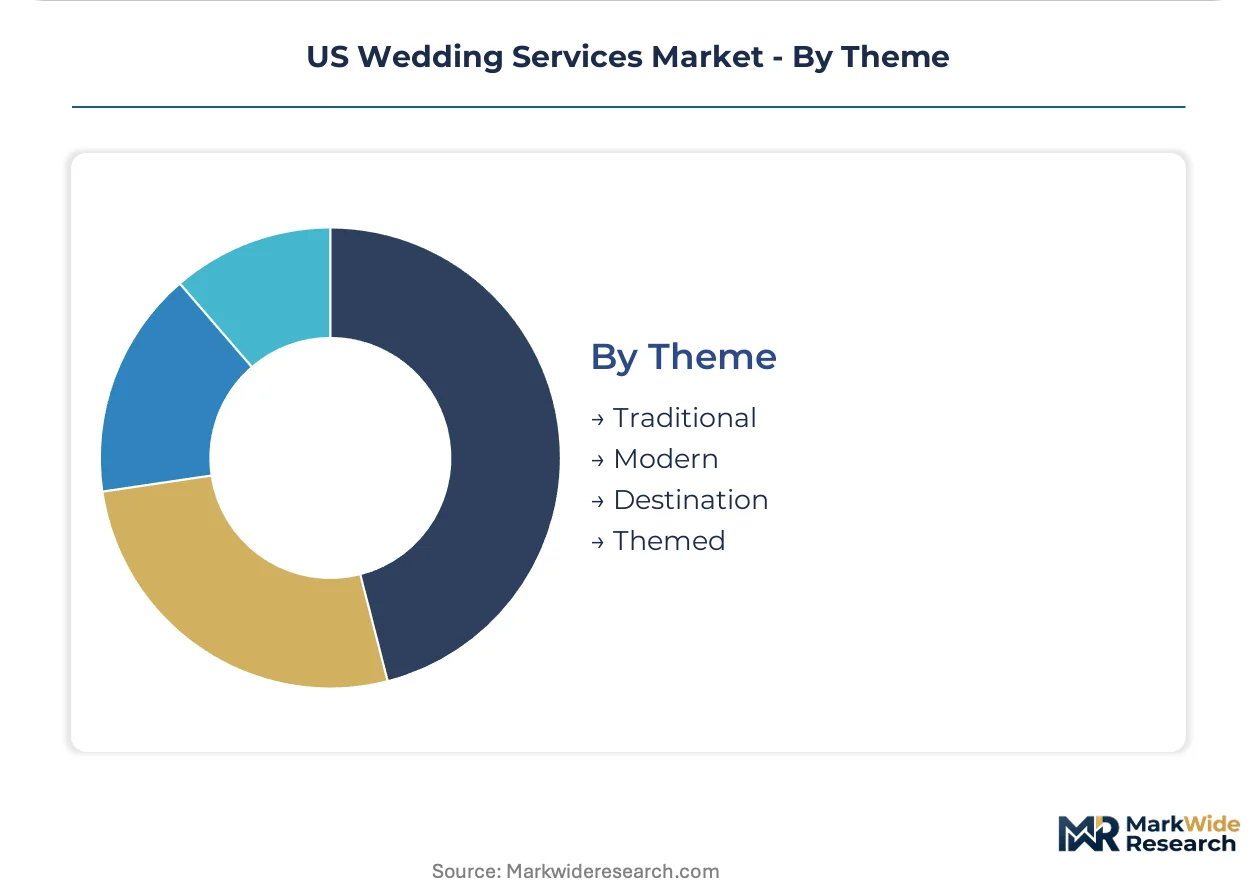
- Traditional:Ceremony-reception sequencing with formal attire and conventional venue typologies maintains stable demand across all US regions. Religious institution partnerships anchor vendor network development.
- Modern:Minimalist design palettes and non-traditional venue selections require specialized styling expertise. California urban markets concentrate modern aesthetic demand.
- Destination:Experiential travel ceremonies prioritize full-service coordination packages in Florida and Texas metropolitan clusters. Multi-day event structures intensify OSHA staffing compliance complexity.
- Themed:Concept-driven execution demands custom fabrication and entertainment procurement that extends planning timelines. Niche vendor scarcity elevates pricing premiums.
Traditional ceremonies lead on absolute volume; destination formats lead on per-event spending expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California, Florida, and Texas metropolitan clusters concentrate premium venue inventory and vendor specialization density that shapes national pricing benchmarks.
California
Destination wedding demand and experiential travel ceremonies drive premium service procurement in Los Angeles and San Francisco Bay Area corridors. OSHA workplace safety enforcement intensifies staffing cost structures for multi-day events. Napa Valley and Southern California coastal venues command the highest per-couple spending benchmarks nationally.
Florida
Day-of coordination services face acute capacity constraints as certified coordinator supply lags demand expansion in Miami and Orlando markets. State alcohol beverage control boards maintain divergent catering licensing requirements that complicate vendor mobility. Tampa and Palm Beach metropolitan clusters exhibit fastest uptake of partial planning interventions.
Texas
Micro-wedding formats under 50 guests represent underpenetrated white space in Austin and Dallas secondary markets. IRS 1099 contractor classification rules elevate administrative overhead for freelance photographer and videographer engagement. Houston's vendor specialization density enables competitive shopping and unbundled service procurement.
New York Metro
Modern aesthetic positioning and minimalist design palettes concentrate demand in Brooklyn and Manhattan urban venues. FAA Part 107 certification requirements for drone operators compress margin structures for aerial coverage specialists. Hudson Valley and Long Island destination venues capture weekend escape ceremonies from city-based couples.
Pacific Northwest
Outdoor venue adoption and nature-integrated ceremony formats drive seasonal demand concentration in Seattle and Portland metropolitan areas. IRA tax incentives accelerate HVAC and lighting modernization investments at legacy venue properties. Oregon wine country and Washington coastal venues develop multi-day destination packages.
US Wedding Services Market Competitive Landscape
Platform ecosystem expansion dominates the current landscape as digital intermediaries consolidate vendor discovery and booking workflows. The market structure exhibits tiered fragmentation with national platform operators, regional planning agencies, and specialized independent vendors occupying distinct competitive layers. Three strategic archetypes define positioning: digital-native platform orchestrators, full-service planning agencies with preferred vendor networks, and unbundled specialty vendors. M&A activity concentrates on platform technology acquisitions and geographic expansion through regional agency purchases.
Among platform-based intermediaries, The Knot Worldwide Inc., Zola, Inc., and XO Group Inc. occupy positions as digital ecosystem anchors. The Knot Worldwide Inc. exemplifies the vendor discovery and booking workflow consolidation archetype. Zola, Inc. represents integrated registry and planning tool convergence. XO Group Inc. sits within content-rich wedding media positioning that shapes couple preferences upstream of purchase decisions.
| Leading Market Players |
|---|
| The Knot Worldwide Inc. |
| Zola, Inc. |
| XO Group Inc. |
| Bodas.net |
| Luxe Atlanta Events |
| Bustle Events |
| Mae&Co Creative |
| HauteFetes |
| Marcy Blum Associates |
| Others |
Pricing and Supply Chain Analysis
Catering commodity indices and venue rental benchmarks cascade through vendor coordination layers into project-based contract tiers that stratify by guest count thresholds and service depth. California, Florida, and Texas metropolitan clusters anchor premium pricing corridors where venue scarcity inflates base rates and OSHA compliance costs compound staffing overhead.
Pricing Analysis
Input-cost pass-through from FAA Part 107 certification requirements and OSHA workplace safety investments flows into project-based contract structures that separate full-service planning from day-of coordination tiers. Price differentiation hinges on vendor certification density and digital deliverable bundling, with social media-optimized videography packages commanding premiums over standard photography. Pricing pressure stems from AI-powered editing tools compressing post-production margins, forcing manual-intensive vendors toward value-added coordination services. DIY platform users in Texas secondary markets exhibit highest price sensitivity, while destination wedding couples in California coastal corridors show lowest elasticity.
Supply Chain Analysis
FAA Part 107 certification and OSHA workplace safety credentials gate vendor participation in premium metropolitan corridors, concentrating qualified drone operators and certified coordinators in California, Florida, and Texas markets. Raw material dependencies span catering provisions, audiovisual equipment, and floral imports, with seasonal availability fluctuations affecting inventory positioning. Supply chain risk centers on single-source vulnerability for specialized destination venues in Napa Valley and Palm Beach corridors. Distribution runs through digital platform intermediaries that consolidate vendor discovery alongside direct-to-couple booking channels in unbundled procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA workplace safety enforcement acts as a regulatory compounder, elevating compliance investments that differentiate certified vendors from uninsured competitors and reshape cost structures across multi-day destination events.
For Market Incumbents: To counter AI-powered photo editing commoditization, established videography providers should deepen in-house production of drone cinematography capabilities and secure exclusive venue partnerships in supply-constrained California coastal markets. Preferred vendor network consolidation with certified safety protocols creates defensive moats against freelance platform competitors.
For New Entrants and Emerging Players: Platform-native discovery tools offer the lowest-friction entry vector for micro-wedding specialization in Texas secondary cities, where turnkey packages under 50 guests face limited incumbent coverage. Direct-to-couple content marketing through TikTok and Instagram Reels bypasses traditional planner intermediation in Florida high-volume corridors.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional planning agencies possessing dense preferred vendor networks and OSHA-compliant staffing infrastructure. Long-term viability favors acquisition targets with demonstrated cross-selling capability from day-of coordination into full-service retainers. The signal to watch is IRA tax incentive uptake accelerating venue modernization investments that elevate pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 107 Certification Investment | Drone cinematography capability unlocks premium positioning in California outdoor venues. |
| OSHA Workplace Safety Alignment | Certified protocols differentiate caterers facing intensified multi-day event enforcement. |
| Micro-Wedding Package Development | Turnkey offerings under 50 guests capture white space in Texas secondary markets. |
| Platform Ecosystem Integration | API connectivity with The Knot and Zola streamlines vendor discovery workflows. |
| Livestreaming-Physical Hybrid Buildout | Real-time broadcast technology expands addressable guest counts for destination ceremonies. |
Research Methodology
Bottom-up couple-budget modeling reconciled against top-down vendor-revenue tracking forms the analytical core of this study. Primary interviews with wedding planners, venue operators, catering directors, and FAA-certified drone cinematographers combined with secondary validation from SEC filings of platform operators, OSHA enforcement databases, and FAA Part 107 registration records. Trade association disclosures from the National Association of Wedding Professionals and regional catering guilds supplemented customs data on floral and equipment imports.
Historical trendline analysis of per-couple spending patterns across service categories informed projection frameworks over the analysis window. Segmentation dimensions modeled include service type, client procurement authority, planning depth tier, and aesthetic positioning. CAGRs derived from vendor-reported booking volumes and platform transaction disclosures, with IRA tax incentive uptake and OSHA enforcement intensity as scenario-weighting inputs.
Labor reclassification rulings, platform commission structure shifts, and destination travel demand volatility are the dominant revision risks warranting model sensitivity. Forecasts embed assumptions regarding regulatory stability and digital-native couple preference evolution. A model refresh is warranted upon material change in IRS 1099 contractor classification interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
US Restaurant Management Market
Hospitality Management and Services
Hospitality Furniture Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Saudi Arabia Wedding Services Market