
 Catering Management Market | 2026-2036
Catering Management Market Size, Share, and Industry Trends Forecast 2026-2036
Catering Management Market Outlook
The shift from in-house food operations to outsourced catering management is broadening across institutional buyers. Compass Group sustains global scale through centralized procurement networks spanning multiple continents. Sodexo differentiates through technology-integrated service platforms that streamline kitchen logistics for enterprise clients. ezCater competes in digital marketplace aggregation, connecting regional vendors to corporate accounts through proprietary ordering interfaces.
Catering management encompasses the end-to-end coordination of food service operations, including menu planning, vendor procurement, dietary compliance tracking, and real-time event logistics orchestration through software dashboards. Its primary commercial purpose is to reduce per-meal operational overhead while ensuring consistent quality across distributed service locations. Corporate Events commands the largest revenue share within service type segmentation, though Food Truck Services is expanding fastest among delivery modes as employers seek flexible, low-capacity dining formats. The Businesses customer segment anchors volume, while Educational Institutions represents the fastest-growing contract category as K-12 and university systems outsource cafeteria operations.
The United States Department of Agriculture administers nutritional standards that shape K-12 catering contract requirements, while the FDA's Food Safety Modernization Act mandates hazard-control documentation across all commercial food preparation. The EU's General Food Law Regulation imposes traceability obligations on caterers operating across European member states. Stakeholders must monitor how evolving allergen-labeling mandates and carbon-disclosure rules reshape procurement criteria and vendor qualification thresholds.
Market Dynamics
Cloud-based kitchen management platforms are displacing legacy scheduling infrastructure across institutional food service operations, compressing coordination overhead while fragmenting vendor relationships through digital marketplace intermediation.
Growth Catalysts
- USDA Nutritional Standards:Federal mandates for K-12 meal composition create recurring contract renewal cycles for compliant catering operators. School districts outsource cafeteria management to specialized vendors who maintain documentation systems.
- Food Truck Services:Mobile kitchen formats reduce real estate capital requirements for corporate clients seeking flexible dining capacity. Employers deploy rotating vendor schedules across distributed campus locations.
- Cloud-Based Platforms:Real-time dashboard systems synchronize menu planning, dietary tracking, and logistics orchestration across multiple service sites. Technology-integrated procurement networks lower per-meal operational overhead.
Market Restraints
- Ingredient Cost Volatility:Protein and produce input prices fluctuate with climate-driven supply disruptions. Caterers face margin compression when long-term contracts lock in pricing below spot market movements.
- EU Traceability Mandates:The General Food Law Regulation imposes documentation burdens on cross-border European operations. Multi-national operators must maintain parallel compliance systems for member state variations.
- Allergen Labeling Complexity:Evolving disclosure requirements for major food allergens increase kitchen staff training intensity and liability exposure. Mislabeling incidents trigger regulatory enforcement and contract termination.
Strategic Opportunities
- United Kingdom Metropolitan Districts:London and Manchester business corridors concentrate demand for outsourced corporate meal programs. Cloud platform providers target financial services and technology sector headquarters.
- Carbon Disclosure Rules:Emerging emissions reporting mandates reshape procurement criteria toward lower-carbon supply chains. Caterers with verified sustainable sourcing credentials qualify for premium contract tiers.
- AI-Driven Demand Forecasting:Machine learning algorithms converging with inventory management systems reduce food waste and overproduction. Enterprise clients prioritize vendors demonstrating measurable waste reduction metrics.
Industry Challenges
- Certified Food Safety Manager Scarcity:FDA Food Safety Modernization Act hazard-control documentation requires specialized personnel. Operators compete for limited talent pools in tight labor markets.
- Legacy System Integration Friction:Enterprise clients maintain entrenched procurement and payment workflows. Cloud platform vendors absorb implementation costs to displace incumbent relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catering Management Market |
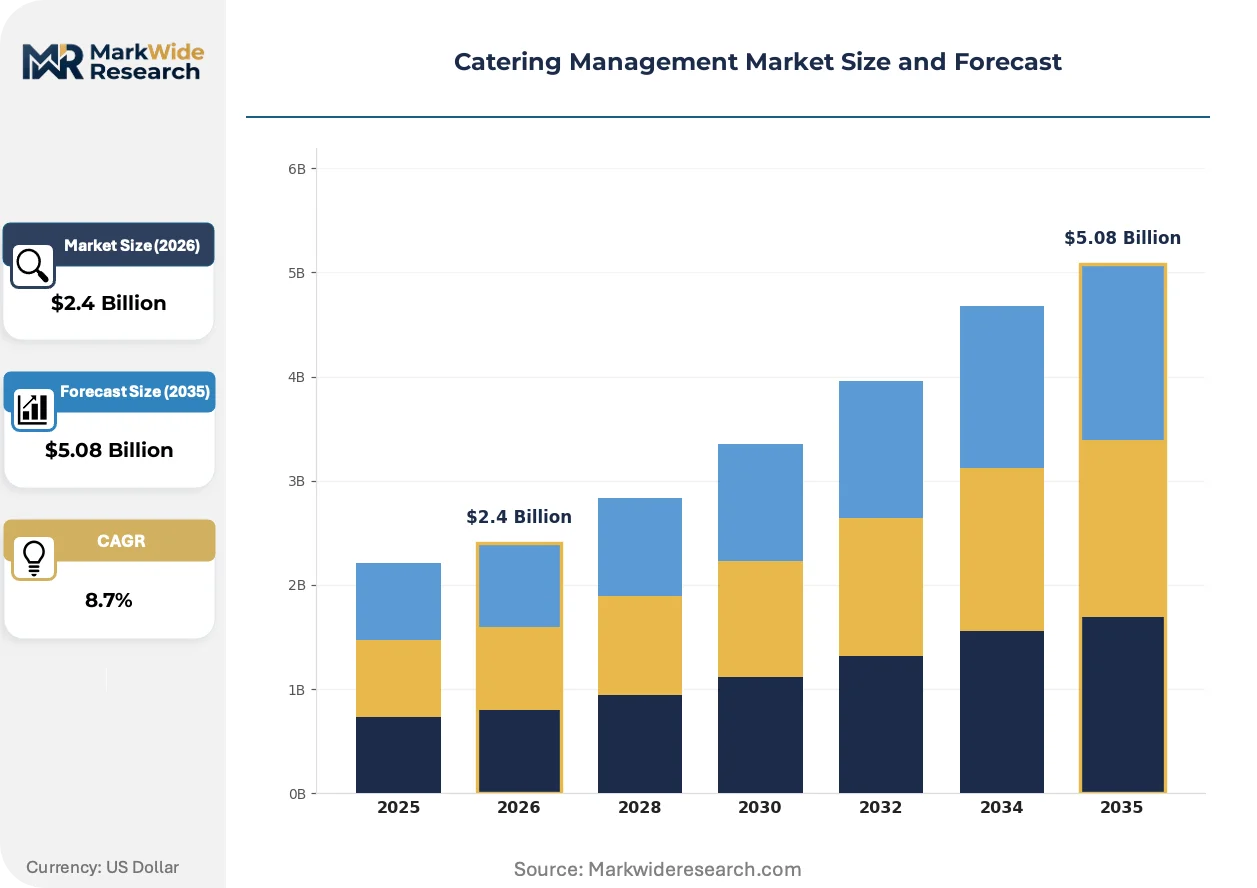
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Events, Weddings, Social Gatherings, Private Parties Delivery Mode: On-site Catering, Off-site Catering, Food Truck Services, Meal Delivery Customer Type: Businesses, Individuals, Non-profits, Educational Institutions Menu Type: Vegetarian, Vegan, Gluten-free, Traditional |
| Companies Covered | ezCater, Hungry, Compass Group, Scratch Catering and Fine Foods, CaterCow, Aramark, Tripleseat, Club Feast, Sodexo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catering Management Market Strategic Shifts
Digital infrastructure is compressing coordination layers between food preparation facilities and end-consumers, while regulatory pressure and shifting workplace consumption patterns reshape competitive requirements.
Internet-of-Things sensor networks are integrating temperature monitoring, equipment performance tracking, and predictive maintenance across commercial kitchen operations. Large-scale corporate catering contracts now mandate real-time visibility into cold-chain integrity. This capability is integrating food safety documentation with automated compliance reporting, reducing manual audit preparation.
The FDA's Food Safety Modernization Act mandates hazard analysis and preventive controls for human food across all commercial preparation facilities. Caterers must maintain written food safety plans with supply-chain verification protocols. Small and mid-size regional operators face disproportionate compliance documentation burdens relative to centralized national competitors.
Employer-sponsored meal programs are consolidating purchasing authority through digital marketplace platforms rather than direct vendor relationships. Corporate procurement teams negotiate master service agreements with aggregator intermediaries who manage regional vendor qualification. This channel shift concentrates buyer power and compresses margins for independent catering operators in United States technology and financial services corridors.
Catering Management Market Segmentation
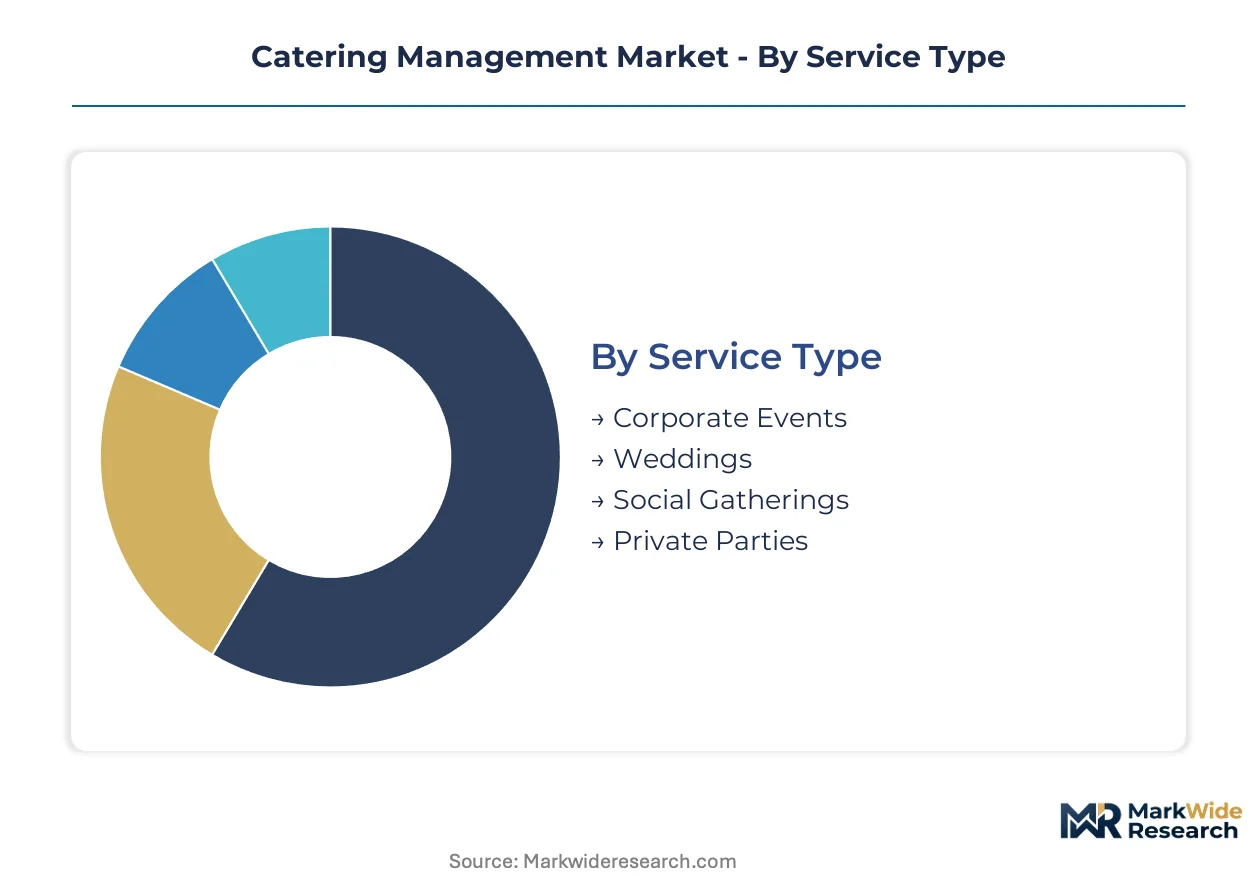
Catering management vendors configure service portfolios around distinct operational economics and contractual relationships. Each segmentation dimension reveals divergent margin structures, technology requirements, and procurement pathways that shape competitive positioning.
Service Type:
Contract value and frequency separate institutional buyers from occasional consumers in this category.
- Corporate Events:Recurring high-volume contracts with enterprise procurement teams. Demand concentrates in United States technology and financial services corridors where cloud-based platform integration reduces per-meal coordination overhead.
- Weddings:Premium per-guest spending with seasonal demand volatility. United Kingdom metropolitan districts anchor volume as couples prioritize verified sustainable sourcing credentials under emerging carbon disclosure rules.
- Social Gatherings:Mid-tier event formats with fragmented vendor selection.
- Private Parties:Small-scale occasions with direct consumer relationships.
Corporate Events leads volumes today; Weddings is gaining share fastest.
Delivery Mode:
Capital intensity and real estate requirements determine which formats attract institutional versus occasional demand.
- On-site Catering:Full-service kitchen operations at client facilities. K-12 school districts in the United States outsource cafeteria management to specialized vendors who maintain USDA nutritional compliance documentation systems.
- Food Truck Services:Mobile kitchen formats with minimal fixed asset requirements. Employers deploy rotating vendor schedules across distributed campus locations to reduce real estate capital commitments.
- Off-site Catering:Centralized preparation with transport logistics.
- Meal Delivery:Individual portion distribution through digital ordering interfaces.
On-site Catering dominates contract value; Food Truck Services shows the steepest expansion trajectory.
Customer Type:
Procurement sophistication and contract duration separate recurring institutional relationships from transactional consumer purchases.
- Businesses:Enterprise accounts with multi-year master service agreements. Corporate procurement teams negotiate through aggregator intermediaries who manage regional vendor qualification, compressing margins for independent operators.
- Educational Institutions:K-12 and university systems outsourcing cafeteria operations. Federal mandates for meal composition create recurring contract renewal cycles for compliant catering operators maintaining hazard-control documentation.
- Individuals:Direct consumers with event-driven purchasing patterns.
- Non-profits:Budget-constrained organizations with mission-aligned vendor preferences.
Businesses anchors revenue concentration; Educational Institutions is expanding most quickly.
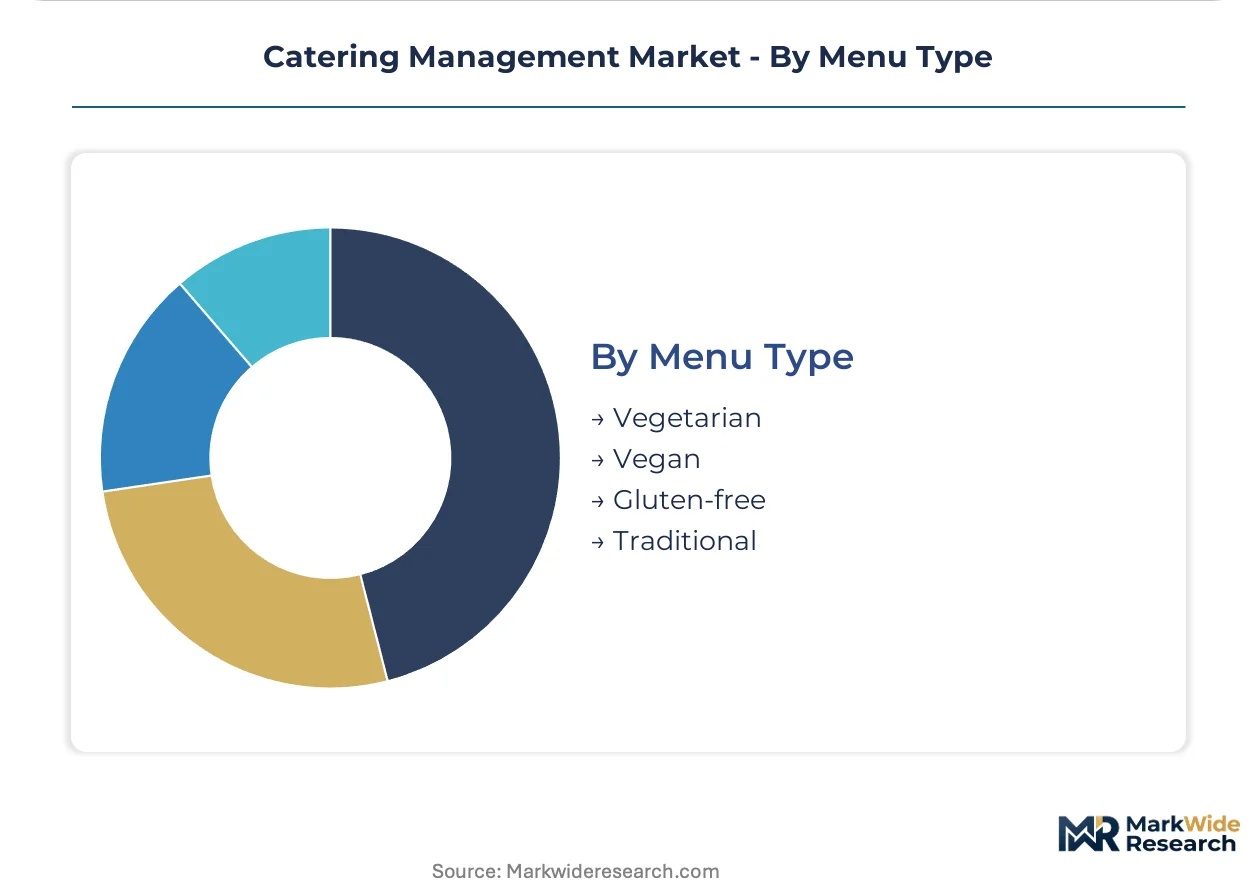
Menu Type:
Dietary compliance burden and ingredient cost volatility differentiate operational requirements across kitchen teams.
- Traditional:Standard ingredient profiles with established supply chains.
- Vegetarian:Plant-forward menus with lower protein cost exposure.
- Gluten-free:Strict allergen-control protocols with liability documentation. Kitchen staff training intensity increases under evolving disclosure requirements, raising operational overhead.
- Vegan:Elimination of all animal products with supply-chain verification. EU General Food Law Regulation traceability obligations impose documentation burdens on cross-border European operations sourcing specialty ingredients.
Traditional leads current production volumes; Vegan is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting catering management investment toward jurisdictions with streamlined compliance frameworks. Operators migrate procurement networks to minimize documentation burdens while maintaining quality standards across distributed service locations.
United States
Corporate campuses in technology and financial services corridors drive outsourced meal program expansion. The FDA's Food Safety Modernization Act mandates hazard-control documentation that favors centralized national operators over regional competitors. Silicon Valley and Manhattan business districts concentrate demand for cloud-integrated catering platforms.
United Kingdom
Metropolitan business districts in London and Manchester anchor corporate catering contract volume. EU General Food Law Regulation traceability obligations persist post-Brexit, shaping cross-border procurement documentation requirements. The City of London financial cluster generates premium demand for verified sustainable sourcing credentials under emerging carbon disclosure rules.
Germany
Industrial manufacturing hubs sustain institutional catering contracts with multi-year service agreements. REACH chemical safety regulations influence cleaning supply procurement for commercial kitchen operations. The Rhine-Ruhr metropolitan region concentrates demand for technology-integrated food service management across automotive and engineering corporate facilities.
France
Luxury hospitality traditions intersect with corporate catering modernization in Paris business districts. ANSM and CNIL oversight extends to food service data privacy in digital ordering platforms. La Défense financial district drives demand for premium event catering with stringent allergen-control protocols.
Japan
Corporate bento culture transitions toward outsourced catering management in Tokyo and Osaka metropolitan areas. METI industrial standards shape commercial kitchen equipment specifications and energy efficiency requirements. The Kanto region concentrates demand for precision logistics in just-in-time meal delivery systems.
Catering Management Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital marketplace aggregation and technology-integrated service platforms. The market exhibits tiered concentration with multinational operators leveraging centralized procurement networks against regional specialists competing on local relationships. Three archetypes dominate: global facilities management conglomerates, digital marketplace intermediaries, and specialized event catering operators. Consolidation pressure manifests through strategic partnerships between cloud platform providers and traditional food service vendors, alongside geographic expansion into underserved metropolitan corridors.
Among technology-integrated service providers, ezCater occupies a position exemplifying digital marketplace aggregation, connecting regional vendors to corporate accounts through proprietary ordering interfaces. Compass Group and Sodexo represent the global facilities management archetype, anchoring scale-driven competitive positioning through multi-continent procurement networks and enterprise master service agreements. These three entities collectively illustrate the strategic divergence between platform-based intermediation and vertically integrated service delivery in contemporary catering management.
| Leading Market Players |
|---|
| ezCater |
| Hungry |
| Compass Group |
| Scratch Catering and Fine Foods |
| CaterCow |
| Aramark |
| Tripleseat |
| Club Feast |
| Sodexo |
| Others |
Value Chain & Pricing Dynamics
Protein and produce input costs transmit directly from commodity markets through to per-meal contract rates, with USDA-compliant K-12 operators absorbing margin compression when long-term agreements lock pricing below spot movements. Enterprise procurement teams leverage digital marketplace aggregation to compress vendor margins across United States technology corridors, while carbon disclosure rules in the United Kingdom introduce premium tiering for verified sustainable sourcing credentials.
Pricing Analysis
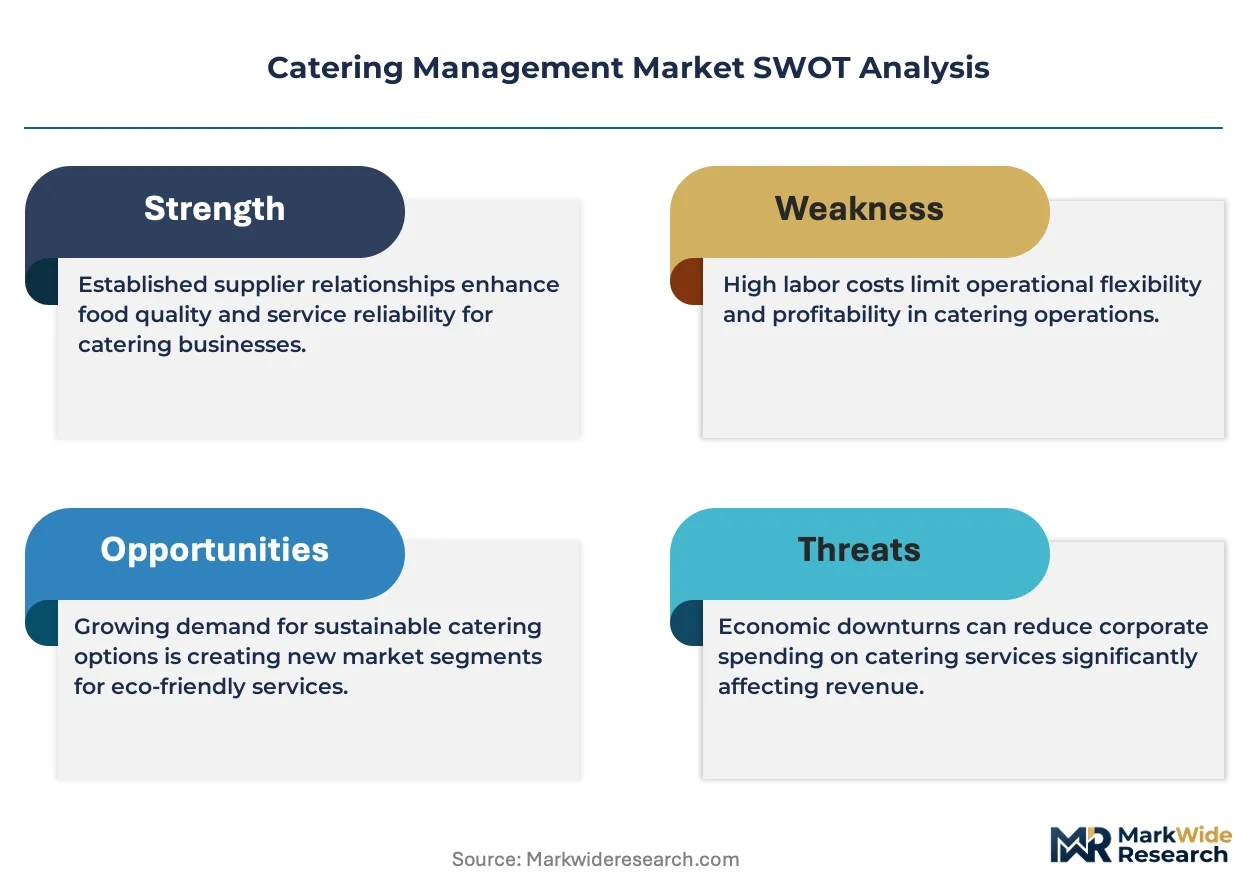
Input-cost pass-through operates through contract-based long-term offtake agreements for institutional accounts, with spot-market exposure concentrated in food truck services and event catering. Price differentiation separates USDA-certified K-12 operators from uncertified competitors, while volume scale and geographic delivery cost stratify enterprise contracts. Pricing pressure stems from ingredient cost volatility as climate-driven supply disruptions compress margins in locked-rate agreements. Educational Institutions demonstrate highest price sensitivity due to budget-constrained procurement processes, whereas Corporate Events clients prioritize technology integration over per-meal cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with specialized allergen-free ingredient suppliers concentrated in United States and European Union markets, where EU General Food Law Regulation traceability mandates impose parallel documentation systems. Raw material dependencies center on protein commodities, specialty produce for dietary compliance, and sustainable-certified supply chains for carbon disclosure eligibility. Supply chain risk manifests through regulatory restriction as evolving allergen-labeling requirements increase kitchen staff training intensity and liability exposure. Distribution runs through centralized procurement networks for multinational operators and digital marketplace intermediaries for regional vendor aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as corporate procurement teams prioritize cloud-integrated platforms and verified sustainable sourcing over lowest-cost vendor selection. The shift toward premium specifications in carbon disclosure compliance and real-time food safety documentation favors operators with capital-intensive technology infrastructure.
For Market Incumbents: Extend technology platform capabilities into predictive demand forecasting and automated compliance reporting to defend against digital marketplace intermediaries eroding direct vendor relationships. Deepen backward integration into specialty ingredient sourcing to secure supply chain resilience against climate-driven volatility. Prioritize certification investment in ISO 22000 food safety management and carbon accounting standards to qualify for premium contract tiers under emerging disclosure mandates. For New Entrants and Emerging Players: AI-driven kitchen logistics platforms offer a technology-first wedge into mid-market corporate accounts underserved by multinational operators. Target United Kingdom metropolitan business districts where financial services headquarters concentrate demand for outsourced meal programs with sustainability credentials. Pursue white-space expansion in K-12 cafeteria management across United States school districts facing certified food safety manager scarcity, deploying cloud-based documentation systems as go-to-market differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where regional operators lack capital to deploy IoT sensor networks and automated compliance infrastructure required by large-scale corporate contracts. Long-term viability favors vertically integrated platforms with captive supply chains and technology-integrated service delivery over pure-play event caterers. Target acquisition archetypes include cloud platform providers with established vendor networks and regional specialists with deep institutional relationships in underpenetrated metropolitan corridors. Monitor carbon disclosure rule adoption velocity as inflection indicator for premium pricing power migration toward certified sustainable operators.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Reduces per-meal coordination overhead for enterprise clients across distributed campus locations. |
| Sustainable Sourcing Certification | Qualifies operators for premium contract tiers under emerging carbon disclosure rules in United Kingdom. |
| AI-Driven Demand Forecasting | Converges with inventory management to reduce food waste metrics prioritized by corporate procurement teams. |
| Backward Integration into Specialty Ingredients | Secures supply chain resilience against allergen-control documentation burdens and climate-driven volatility. |
| Geographic Expansion into Metropolitan Corridors | Targets London and Manchester business districts concentrating demand for outsourced corporate meal programs. |
Study Parameters
Direct dialogue with catering operations directors, corporate procurement managers, K-12 food service administrators, and cloud platform product leads grounded qualitative insights in operational realities. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, USDA nutritional standards filings, EU General Food Law Regulation texts, and corporate sustainability disclosure reports. Bottom-up and top-down triangulation reconciled vendor-reported contract values with enterprise procurement spend patterns across technology and financial services sectors.
Bottom-up modeling aggregated individual service contract values by segment, while top-down analysis calibrated aggregate market scaling against macroeconomic indicators. Segmentation dimensions spanned service type, delivery mode, customer category, and menu compliance tier across the projection horizon. CAGRs derived from historical contract renewal velocity and technology adoption curves in kitchen management platforms. Industry-specific forecast inputs incorporated USDA mandate implementation timelines and carbon disclosure rule adoption trajectories.
The model holds under stable regulatory enforcement intensity and continued enterprise outsourcing momentum; deviation in allergen-labeling mandate severity or climate-driven supply disruption frequency would shift contract value trajectories. Forecasts reflect documented assumptions regarding technology platform penetration rates and procurement team aggregator adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Singapore Hospitality Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Tech Savvy Hotel Chains Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Catering Services Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
US Restaurant Management Market