
 Australia HRI Market | 2026-2036
Australia HRI Market Size, Share, and Industry Trends Forecast 2026-2036
Australia HRI Market Outlook
Full-service restaurants are unwinding their historical dominance as quick-service chains capture a larger share of equipment spending. McDonald's Corporation leverages its scale to standardize kitchen configurations across Australian locations. Hungry Jack's Pty Ltd anchors its procurement through long-term distributor partnerships in Queensland and Western Australia. Domino's Pizza, Inc. differentiates by optimizing its equipment footprint for delivery-centric operations.
Hotel, restaurant, and institutional (HRI) equipment encompasses commercial-grade appliances, preparation surfaces, and service systems engineered to withstand continuous operation at volumes exceeding ten times residential duty cycles, typically constructed from 304 stainless steel for corrosion resistance and sanitation compliance. The equipment serves the core function of enabling safe, efficient food production and service in regulated commercial environments. Foodservice Equipment dominates current revenue flows, while Beverage Dispensers represent the fastest-expanding product category driven by specialty coffee culture proliferation. Tableware procurement concentrates margin pools in the premium hotel segment, where brand differentiation commands sustained investment.
Food Standards Australia New Zealand (FSANZ) mandates strict equipment sanitation protocols that shape product design and replacement cycles. The Australian Competition and Consumer Commission (ACCC) enforces consumer guarantee provisions that extend liability to equipment performance in commercial settings. Australian Standard AS 4674 for commercial kitchen design influences installation specifications and facility renovation timelines. Stakeholders must weigh the trade-off between equipment standardization for operational efficiency and modular flexibility to accommodate evolving menu formats.
Market Dynamics
Quick-service restaurant chains in New South Wales and Victoria are compressing equipment replacement cycles as FSANZ sanitation mandates tighten compliance thresholds for stainless steel fabrication standards.
Growth Catalysts
- FSANZ Standard 3.2.3:Mandatory food safety protocols are accelerating equipment refresh rates across commercial kitchens in Sydney and Melbourne as operators retrofit facilities to meet elevated sanitation benchmarks.
- Specialty coffee infrastructure:Beverage dispenser procurement is expanding rapidly as independent cafés in Victoria invest in precision brewing systems to capture premium positioning.
- Queensland hospitality investment:Tourism infrastructure projects in Brisbane and Gold Coast are driving institutional kitchen installations at hotels and convention centers.
Market Restraints
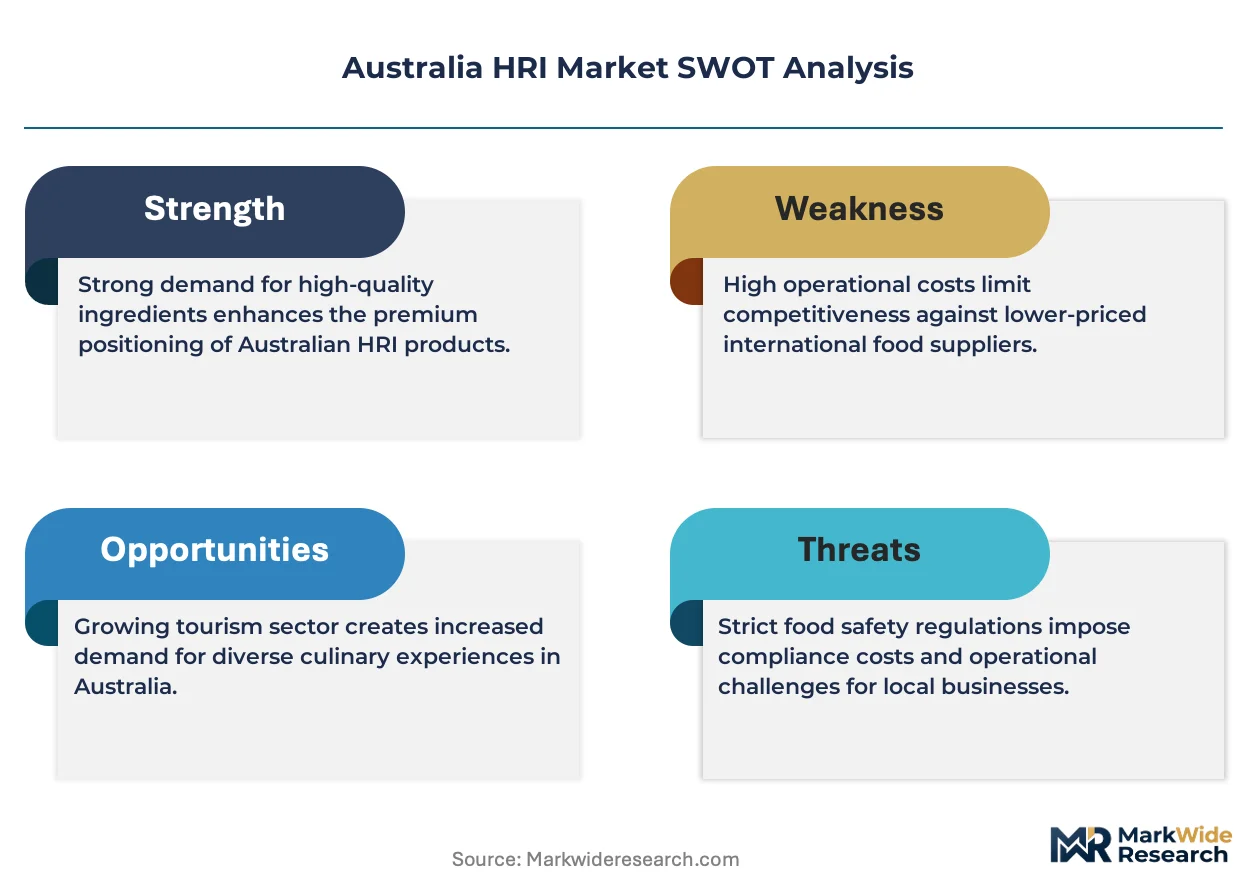
- 304 stainless steel price volatility:Raw material cost fluctuations are compressing margins for equipment fabricators serving mid-tier restaurant operators.
- Import dependency for control systems:Electronic components and automation modules concentrate supply risk with Asian manufacturing hubs, exposing Australian distributors to extended lead times.
- AS 4674 compliance complexity:Commercial kitchen design standards create regulatory friction for facility renovations, extending project timelines and deterring smaller operator upgrades.
Strategic Opportunities
- Western Australia mining camps:Remote workforce catering infrastructure remains underpenetrated, creating demand for durable, high-throughput foodservice equipment in Pilbara and Kimberley regions.
- Smart kitchen convergence:Integration of IoT sensors with traditional cooking equipment is enabling predictive maintenance models that reduce downtime for franchise operators.
- Queensland distributor partnerships:Direct-to-operator digital procurement platforms are displacing traditional wholesaler networks in Brisbane and Townsville markets.
Industry Challenges
- Commercial refrigeration technician shortage:Specialized installation and maintenance skills are scarce across Victoria and New South Wales, delaying project completions and inflating service costs.
- Legacy gas-to-electric conversion:Existing kitchen infrastructure in established Sydney restaurants requires costly electrical upgrades to accommodate induction equipment, complicating equipment refresh decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia HRI Market |
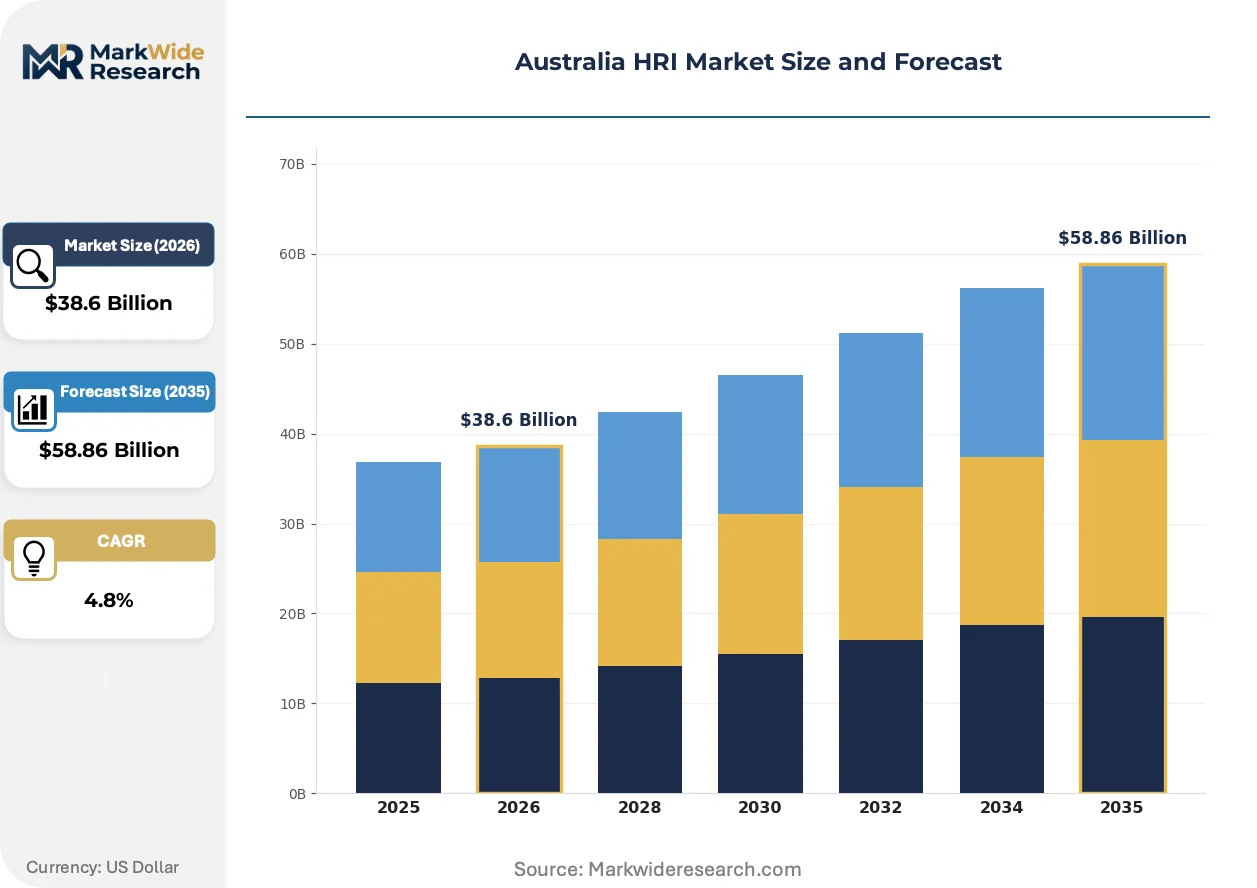
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foodservice Equipment, Tableware, Kitchen Utensils, Beverage Dispensers End User: Restaurants, Hotels, Cafes, Catering Services Service Type: Delivery, Installation, Maintenance, Consulting Distribution Channel: Online Retail, Direct Sales, Distributors, Showrooms |
| Companies Covered | McDonald's Corporation, Yum! Brands, Inc., Domino's Pizza, Inc., Starbucks Corporation, Restaurant Brands International Inc., Nando's, Hungry Jack's Pty Ltd., Bucking Bull, Burger Urge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia HRI Market Strategic Shifts
Equipment footprints are contracting across Australian commercial kitchens as operators prioritize spatial efficiency and multi-functional appliances to accommodate rising real estate costs in dense urban centers.
Combi-oven technology is miniaturizing. These integrated steam-convection systems consolidate multiple cooking functions into single units, reducing floor space requirements by half compared to conventional setups. Quick-service chains in Melbourne are adopting compact combi-ovens aggressively to maximize kitchen throughput in limited footprints. The technology is miniaturizing equipment procurement budgets while enabling menu expansion without facility expansion.
FSANZ is tightening equipment surface sanitation requirements through revised Food Safety Standard 3.2.3 provisions. Fabricators must now certify 304 stainless steel finishes to stricter roughness averages, increasing production costs but reducing bacterial adhesion risks. Premium hotel operators in Sydney are absorbing these cost premiums to maintain brand positioning, while mid-tier restaurants delay upgrades pending clearer enforcement timelines.
Lease-to-own financing is displacing outright equipment purchase among independent restaurant operators. Distributor finance programs in Queensland and South Australia are bundling installation, maintenance, and upgrade options into single contracts. This shift is most visible in Adelaide's emerging food precincts, where chef-entrepreneurs prioritize capital flexibility over asset ownership to manage cash flow volatility.
Australia HRI Market Segmentation
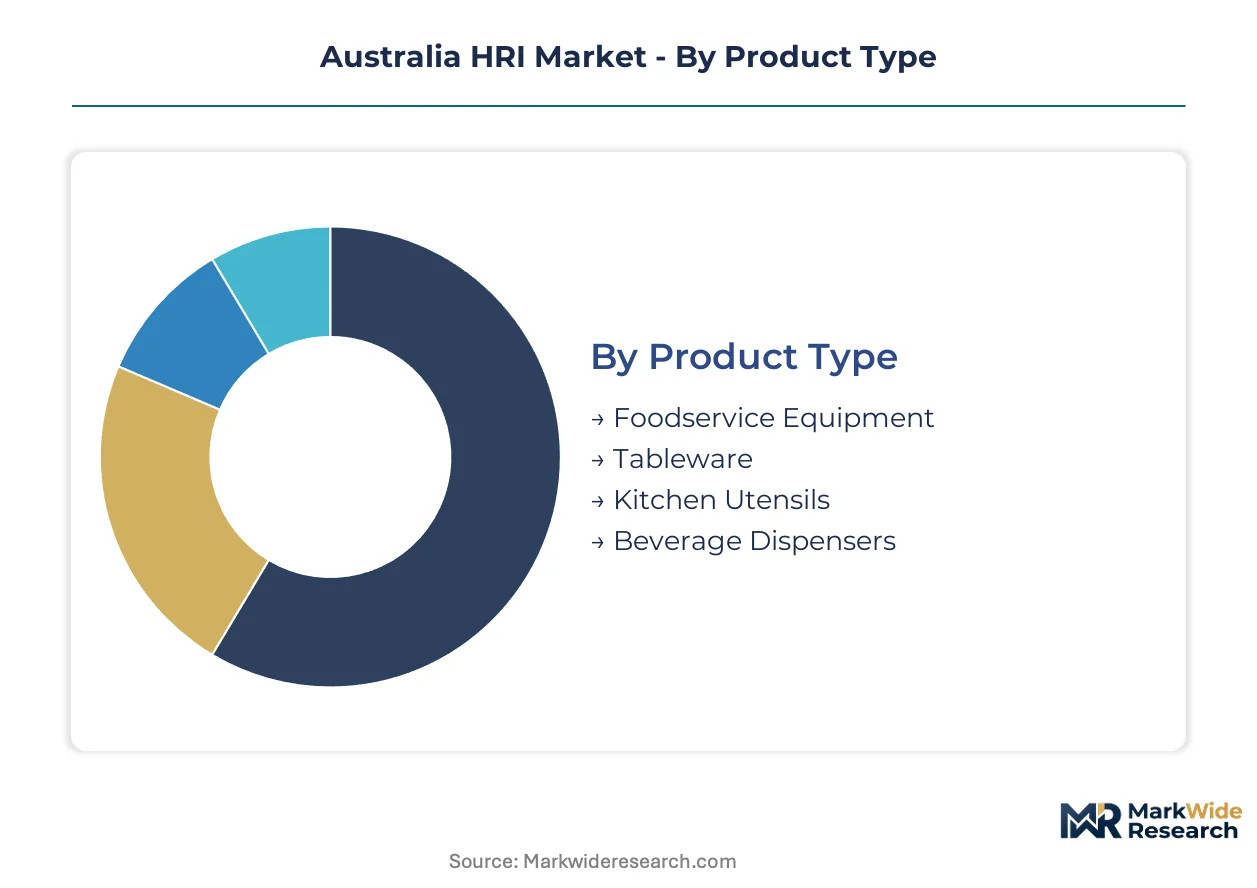
Equipment procurement patterns across Australian hospitality diverge sharply by operational scale and regulatory exposure. FSANZ compliance tiers and AS 4674 installation mandates create natural segmentation boundaries that reshape vendor prioritization and distributor investment.
Product Type:
FSANZ Standard 3.2.3 sanitation protocols differentiate equipment categories by surface certification requirements and replacement cycle intensity.
- Foodservice Equipment:Heavy-duty cooking appliances, refrigeration systems, and food preparation stations fabricated from certified 304 stainless steel dominate capital expenditure across New South Wales and Victoria. Quick-service chains in Sydney compress replacement cycles to meet tightening FSANZ surface roughness mandates.
- Beverage Dispensers:Precision brewing systems and commercial coffee infrastructure are expanding most quickly as Melbourne's independent café sector invests in specialty equipment to capture premium positioning.
- Tableware:Premium porcelain and service collections concentrate procurement in Sydney's hotel segment where brand differentiation commands sustained investment.
- Kitchen Utensils:Hand tools and smallwares represent high-frequency replacement purchases across mid-tier restaurant operators managing tighter working capital constraints.
Established volume favors Foodservice Equipment; emerging adoption favors Beverage Dispensers.
End User:
Customer scale determines procurement complexity, with franchise networks demanding standardization while independent operators prioritize flexibility.
- Restaurants:Full-service and quick-service operators generate the largest equipment procurement volumes, with Melbourne's chain restaurants driving standardization through centralized purchasing.
- Hotels:Premium properties in Sydney and Brisbane anchor demand for integrated kitchen systems and front-of-house service equipment, with procurement cycles tied to renovation timelines.
- Cafes:Victoria's specialty coffee culture fuels concentrated demand for compact, high-throughput brewing equipment optimized for limited urban footprints.
- Catering Services:Event and institutional caterers across Queensland prioritize mobile and modular equipment configurations for venue flexibility.
Contract value concentrates with Hotels; transaction frequency peaks with Cafes.
Service Type:
Post-sale revenue streams fragment by customer technical capability and equipment criticality to operations.
- Installation:AS 4674 compliance requirements for commercial kitchen design extend project timelines and elevate demand for certified technical services in Sydney and Melbourne.
- Maintenance:Predictive service contracts are gaining share fastest as IoT-enabled equipment allows remote monitoring and downtime reduction for franchise operators.
- Delivery:Logistics coordination for bulky stainless steel fabrication remains a margin-challenged necessity, particularly for regional Queensland and Western Australia deployments.
- Consulting:Kitchen design advisory services concentrate among hotel developers and large-scale restaurant groups navigating complex regulatory compliance.
Recurring revenue anchors on Maintenance; project-based margins concentrate in Consulting.
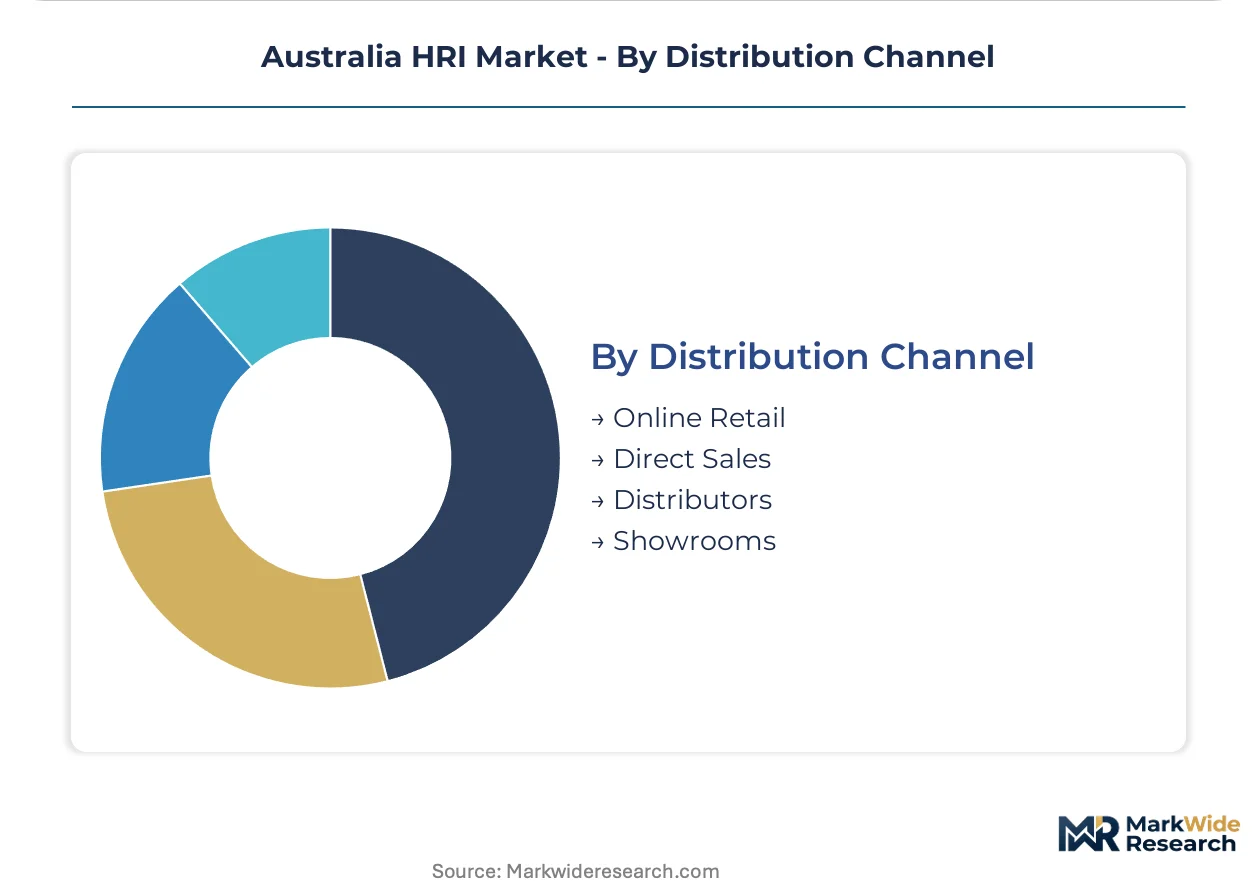
Distribution Channel:
Channel economics shift as digital procurement platforms displace traditional wholesaler relationships in concentrated urban markets.
- Distributors:Long-established networks in Queensland and Western Australia maintain leverage through bundled financing and technical service capabilities.
- Direct Sales:Manufacturer-to-operator relationships are expanding among large franchise accounts seeking volume pricing and configuration standardization.
- Online Retail:Digital platforms are displacing traditional channels fastest in Brisbane and Townsville, particularly for replacement parts and smallwares.
- Showrooms:Physical demonstration spaces retain importance for complex equipment purchases requiring operational validation, concentrated in Sydney and Melbourne hospitality precincts.
Relationship depth favors Distributors; cost efficiency favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Victoria and New South Wales, where stainless steel processing capacity and distributor networks align with dense hospitality demand. TGA food safety oversight and FSANZ mandates shape procurement patterns across all states, with compliance intensity varying by local enforcement capacity.
New South Wales
Sydney's quick-service chains drive compressed replacement cycles for 304 stainless steel cooking equipment. FSANZ Standard 3.2.3 enforcement tightens surface roughness certification requirements for commercial kitchen fabricators. The Parramatta hospitality precinct anchors demand for integrated front-of-house systems as hotel renovation activity accelerates.
Victoria
Melbourne's independent café sector fuels specialty coffee equipment procurement at premium price points. AS 4674 commercial kitchen design standards extend project timelines for certified installations across metropolitan venues. The inner-north restaurant cluster prioritizes compact combi-oven configurations to maximize throughput in constrained urban footprints.
Queensland
Tourism infrastructure investment in Brisbane and Gold Coast drives institutional kitchen installations at convention centers and hotels. Long-established distributor networks maintain leverage through bundled financing programs for regional operators. The Townsville market experiences fastest digital procurement platform adoption for replacement parts and smallwares.
Western Australia
Remote mining camp catering infrastructure creates demand for durable, high-throughput foodservice equipment in Pilbara and Kimberley regions. Import dependency for electronic control systems extends lead times for automation modules across Perth distribution channels. The state shows lowest penetration of IoT-enabled predictive maintenance contracts due to technician scarcity.
South Australia
Adelaide's emerging food precincts favor lease-to-own financing structures over outright equipment purchase. Chef-entrepreneurs prioritize capital flexibility through distributor finance programs bundling installation and maintenance. The Barossa Valley wine tourism corridor generates seasonal demand spikes for mobile catering equipment configurations.
Australia HRI Market Competitive Environment
Concentration sits with quick-service franchise networks that standardize procurement through centralized purchasing agreements. The vendor landscape fragments across equipment fabricators, specialty distributors, and digital procurement platforms competing on compliance certification and financing flexibility. Two strategic archetypes dominate: scale-driven chains leveraging volume pricing, and regional distributors bundling technical services with equipment supply. Competitive moves center on distributor partnership exclusivity and smart kitchen technology integration for predictive maintenance offerings.
Among quick-service operators, McDonald's Corporation exemplifies the standardization archetype through centralized kitchen configuration protocols. Domino's Pizza, Inc. occupies a position emphasizing delivery-centric equipment optimization, while Hungry Jack's Pty Ltd anchors distributor-dependent procurement models in Queensland and Western Australia markets.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Yum! Brands, Inc. |
| Domino's Pizza, Inc. |
| Starbucks Corporation |
| Restaurant Brands International Inc. |
| Nando's |
| Hungry Jack's Pty Ltd. |
| Bucking Bull |
| Burger Urge |
| Others |
Value Chain & Pricing Dynamics
FSANZ Standard 3.2.3 certification gates both supplier qualification and price tiering simultaneously, forcing fabricators to absorb elevated 304 stainless steel surface roughness testing costs while premium hotel operators in Sydney accept these premiums for brand protection. Mid-tier restaurant operators defer upgrades pending enforcement clarity, compressing demand into compliance-driven replacement spikes rather than smooth upgrade cycles.
Pricing Analysis
FSANZ Standard 3.2.3 dictates the pricing tier structure across Australian HRI equipment, separating certified premium fabrication from uncertified standard imports and economy-grade alternatives lacking Australian distributor support. Price differentiation centers on certification grade and volume scale, with quick-service chains extracting bulk discounts while independent cafés absorb list pricing. Cost compression in mid-tier equipment is intensifying because 304 stainless steel price volatility transfers raw material risk to fabricators. Franchise networks demonstrate lowest price sensitivity through centralized procurement, whereas chef-entrepreneurs in Adelaide's emerging precincts exhibit highest sensitivity, prioritizing lease-to-own structures over outright purchase.
Supply Chain Analysis
China and South Korea anchor electronic control system and automation module production for Australian HRI equipment, while domestic Victorian and New South Wales fabricators concentrate 304 stainless steel processing and final assembly. Supply chains draw from imported semiconductors, precision sensors, and specialized heating elements, with raw material flows resting on nickel and chromium price benchmarks. Single-source vulnerability concentrates in Asian manufacturing hubs for IoT-enabled kitchen modules, exposing Perth distributors to extended lead times. Distribution runs through long-established Queensland and Western Australia distributor networks bundling financing and technical services, though digital procurement platforms displace traditional channels fastest in Brisbane and Townsville markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia HRI Market sits in early-cycle expansion as FSANZ compliance mandates force accelerated equipment refresh rates across commercial kitchens, creating sustained replacement demand independent of new build activity.
For Market Incumbents: Secure distributor partnership exclusivity in Queensland and Western Australia where Hungry Jack's anchors procurement through long-term relationships, defending against direct-to-operator digital platforms eroding traditional channel leverage. Invest in IoT-enabled predictive maintenance certification to capture recurring service revenue as franchise operators prioritize uptime guarantees over transactional equipment sales. For New Entrants and Emerging Players: Lead with lease-to-own financing structures targeting Adelaide's emerging food precincts and South Australia's chef-entrepreneur segment, where capital flexibility outweighs asset ownership preferences. Target Western Australia's Pilbara and Kimberley mining camp catering infrastructure, the most underpenetrated geography for durable high-throughput equipment, with rental-service hybrid models addressing technician scarcity through remote monitoring capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with neglected foodservice equipment divisions lacking FSANZ certification investment and smart kitchen integration roadmaps. Long-term viability over a 5-10 year horizon hinges on regulatory compliance depth rather than commodity fabrication scale. Watch AS 4674 enforcement intensity across Victoria and New South Wales as the signal for replacement cycle acceleration and margin expansion in certified fabrication.| Strategic Initiative | Industry Significance |
|---|---|
| FSANZ Certification Investment | Surface roughness certification separates compliant fabricators from import displacement in Sydney and Melbourne. |
| IoT Predictive Maintenance Platform | Remote monitoring contracts reduce downtime for McDonald's and Domino's franchise operators. |
| Lease-to-Own Financing Program | Capital flexibility structures capture Adelaide chef-entrepreneurs managing cash flow volatility. |
| Western Australia Distribution Partnership | Technical service bundling addresses technician scarcity in Pilbara mining camp deployments. |
| Compact Combi-Oven Product Line | Miniaturized steam-convection systems maximize throughput in Melbourne's constrained urban footprints. |
Study Parameters
Initial hypotheses were tested against primary input from commercial kitchen equipment fabricators, quick-service restaurant procurement directors, hospitality distributor account managers, and FSANZ compliance officers, and refined through secondary validation against TGA food safety oversight records, Australian Bureau of Statistics hospitality investment data, AS 4674 technical standards documentation, and import customs records for stainless steel fabrication. Bottom-up equipment shipment data triangulated against top-down hospitality construction permits across New South Wales, Victoria, Queensland, Western Australia, and South Australia.
Variance decomposition across product type, end user scale, service attachment rate, and distribution channel penetration shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated FSANZ enforcement timeline assumptions, 304 stainless steel price elasticity coefficients, and quick-service chain expansion pipelines.
The analysis sits within stated boundaries; outcomes outside sustained FSANZ compliance tightening, stable mining camp workforce levels, or continued specialty coffee culture proliferation would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle compression and import dependency persistence. Recalibration cycles align with material shifts in FSANZ Standard 3.2.3 enforcement intensity and electronic component supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Smart Hospitality Market
Hospitality Management and Services
US Wedding Services Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Smart Hospitality and Coworking Spaces Market
Hospitality Management and Services
Turkey Hospitality Market
Hospitality Management and Services
North America Restaurant Furniture Market
Hospitality Management and Services
Chinese Restaurant Franchising Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
France HRI Market
Hospitality Management and Services
Smart Hospitality Management Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
US Catering Services Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Hotel and Hospitality Management Software Market