
 Singapore Hospitality Market | 2026-2036
Singapore Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Hospitality Market Insights
Corporate and MICE visitor demand is shifting toward integrated resort properties with dedicated convention facilities. Marina Bay Sands leverages its vertical integration of exhibition halls, luxury retail, and casino operations to anchor large-scale events. Resorts World Sentosa sustains its competitive position through Universal Studios Singapore and marine attractions that extend average guest stays. Pan Pacific Hotels Group specializes in business-oriented properties near Changi Airport and the central business district.
Singapore hospitality encompasses lodging, food service, and guest experience management across commercial properties operating under strict licensing and safety protocols, with properties typically ranging from 200 to over 2,500 keys and integrating smart building systems for energy and security management. The hotel segment dominates revenue generation through premium room rates in the Marina Bay and Orchard Road sub-markets, while serviced apartments capture extended-stay demand from relocating executives and project-based consultants. Online travel agencies now control a substantial share of booking volume, though direct booking channels are recovering as properties invest in loyalty programs and mobile-first reservation platforms.
The Singapore Tourism Board enforces hotel licensing under the Hotels Act, while the Urban Redevelopment Authority governs zoning and development intensity across precincts, and the National Environment Agency regulates food hygiene standards across all on-premise dining operations. These frameworks elevate operating costs but also limit unlicensed competition and protect established operators. Stakeholders must monitor the Sentosa Development Corporation's master plan revisions and the Jurong Lake District transformation for new supply injection points.
Market Dynamics
The Singapore Tourism Board's Hotel Licensing Framework is tightening operational standards while MICE tourism from corporate buyers accelerates demand for integrated convention facilities. This dual pressure is compressing margins for independent operators while rewarding scaled players with capital to absorb compliance costs and build dedicated event infrastructure.
Growth Catalysts
- Changi Airport Terminal 5 Development:The upcoming terminal expansion is electrifying business travel volumes through Singapore's eastern corridor. Pan Pacific Hotels Group and other airport-adjacent operators are capturing extended layover demand with transit-friendly room configurations.
- Urban Redevelopment Authority Zoning Incentives:Density bonuses for mixed-use hospitality developments in the Jurong Lake District are pulling investment westward from saturated Orchard Road precincts. Developers are stacking residential, office, and hotel functions to maximize plot ratios.
- Sentosa-Brunei Wellness Corridor:Cross-border medical tourism partnerships are generating extended-stay demand for post-procedure recovery. Serviced apartments near Mount Elizabeth Novena and Gleneagles Hospital are retrofitting rooms with clinical-grade air filtration and nurse-call systems.
Market Restraints
- Labor Quota Rigidities:Ministry of Manpower work permit dependencies for housekeeping and F&B functions create wage floor pressures that independent hotels cannot absorb as easily as integrated resort operators with casino revenue cross-subsidies.
- Land Lease Concentration:State-owned land released through Government Land Sales tenders concentrates in Marina Bay and Orchard Road sub-markets, limiting greenfield entry for mid-market brands in emerging precincts like Punggol Digital District.
- Energy Tariff Volatility:Singapore Power's quarterly electricity rate adjustments transmit directly to operating costs for properties with aging chiller plants, disadvantaging older stock against newer builds with district cooling connections.
Strategic Opportunities
- Tampines Regional Centre Hospitality Gap:The eastern sub-market lacks branded inventory despite Changi Business Park's expansion and Singapore Expo's event calendar. Mixed-use developments integrating co-living and short-stay formats could capture project-based consultant demand.
- SkillsFuture Subsidy Capture:Workforce Singapore's training grants for digital upskilling enable properties to retrain front-desk staff into revenue management and guest experience design roles at subsidized cost.
- Marina Bay Sands Convention Halo:Large-scale medical congresses and financial services forums are compressing booking windows and extending length-of-stay for adjacent properties with shuttle partnerships to the Sands Expo.
Industry Challenges
- Building Management System Fragmentation:Legacy properties with proprietary Schneider Electric or Siemens HVAC controls struggle to integrate guest-facing mobile key and in-room automation platforms without full infrastructure replacement.
- Food Hygiene Grade Maintenance:National Environment Agency's annual inspections and demerit point systems require continuous kitchen staff retraining, with Grade C or below ratings triggering mandatory closure periods that destroy revenue recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Hospitality Market |
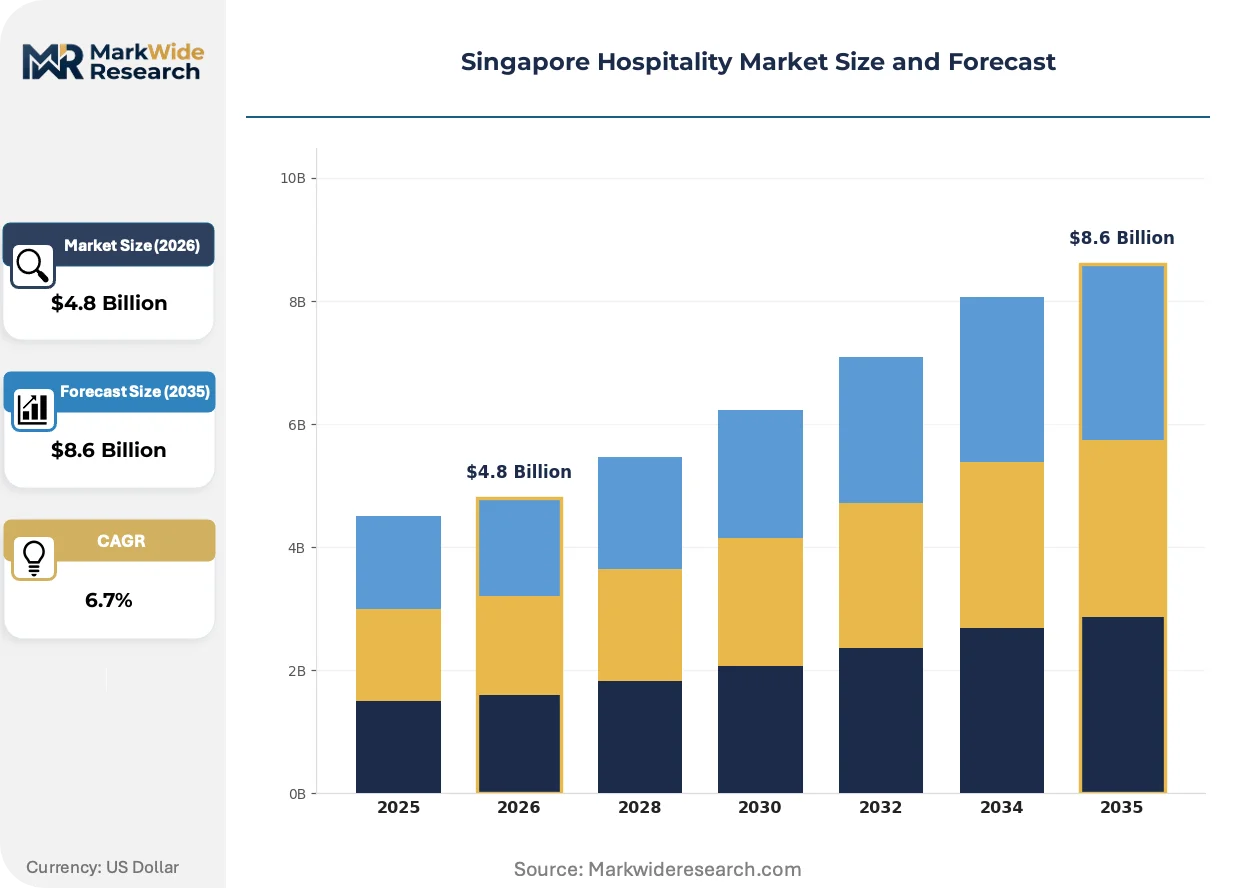
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Hotels, Resorts, Serviced Apartments, Hostels Service Type: Room Service, Food & Beverage, Event Management, Concierge Services Client Type: Business Travelers, Leisure Tourists, Long-term Residents, Families Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Corporate Bookings |
| Companies Covered | Far East Hospitality, Pan Pacific Hotels Group, Marina Bay Sands, Resorts World Sentosa, Accor Asia Pacific, Capella Hotel Group, IHG Hotels & Resorts, Hilton Hotels & Resorts, Shangri-La Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Hospitality Market Trends and Innovations
Guest-facing automation and sustainability certification are compressing capital planning cycles while redefining competitive positioning across Singapore's premium and select-service segments. Properties are racing to deploy systems that reduce touchpoints and document carbon intensity before regulatory mandates harden.
Smart building management systems are electrifying energy and security operations across Singapore's hospitality stock. Pan Pacific Hotels Group and comparable operators are retrofitting properties with IoT-enabled lighting, predictive HVAC maintenance, and integrated access control. The technology is compressing utility spend and enabling real-time sustainability reporting for corporate account RFPs.
Singapore's Building and Construction Authority Green Mark certification is tightening energy efficiency thresholds for new hotel developments. Properties seeking Platinum or Zero Energy ratings must install photovoltaic arrays and advanced water recycling systems. The Marina Bay and Orchard Road sub-markets are seeing the highest concentration of certified stock as developers target multinational corporate travel policies with documented ESG compliance.
Corporate travel managers are compressing approved property lists and demanding bundled meeting space with room blocks. Procurement teams at financial services and pharmaceutical firms are bypassing online travel agencies for direct negotiated rates with properties offering guaranteed AV technical standards and F&B minimums. The shift is most visible in the Changi Business Park and one-north precincts where project-based consulting teams require predictable spend caps.
Singapore Hospitality Market Segmentation
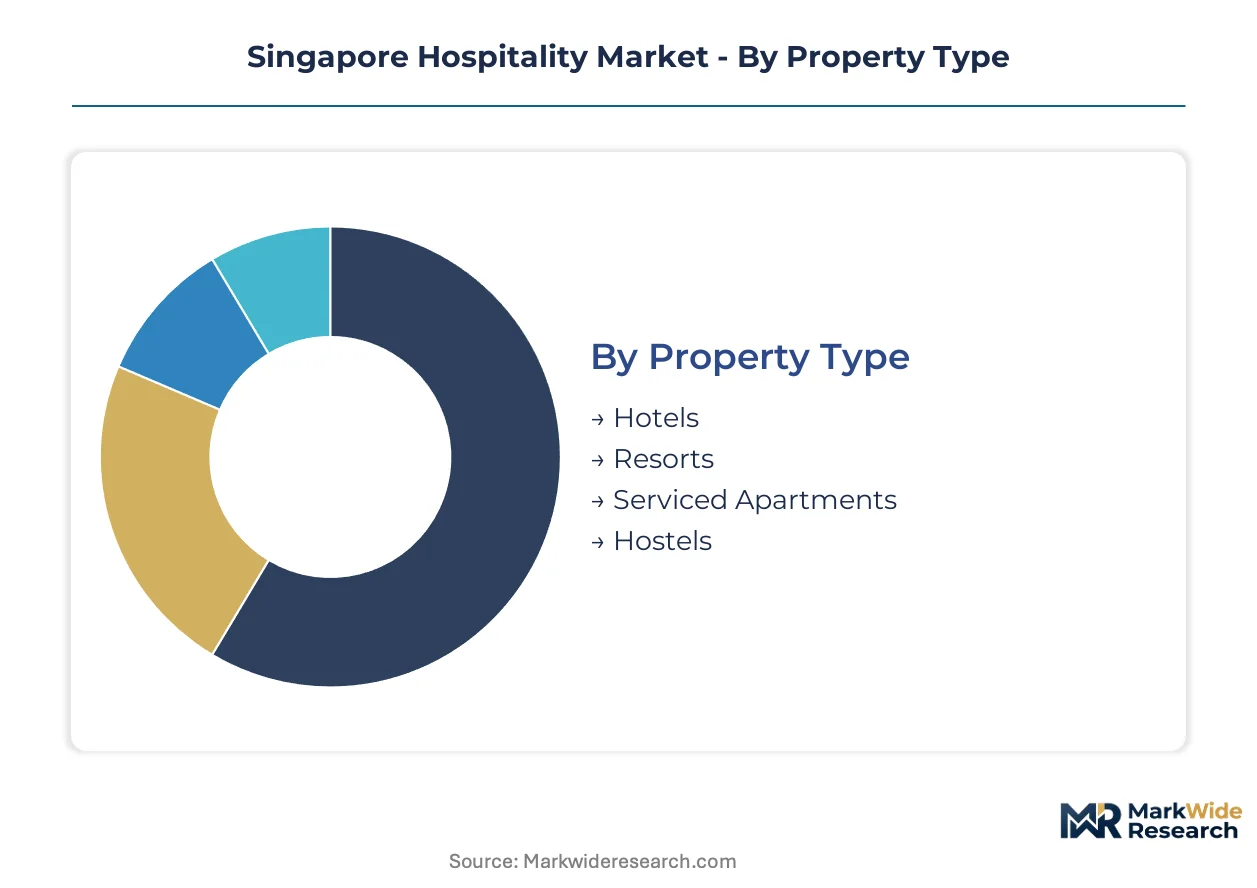
Property configuration and service delivery models in Singapore hospitality are diverging as capital cycles refresh aging stock and new licensing requirements force operational upgrades. Segmentation reveals where investment concentrates and which guest profiles command premium rate realization.
Property Type:
Upgrade cycles are compressing as the Singapore Tourism Board's tightened Hotel Licensing Framework accelerates obsolescence for properties unable to meet revised safety and accessibility standards.
- Hotels:Full-service properties with 200-2,500 keys dominate revenue generation through premium positioning in Marina Bay and Orchard Road precincts. Corporate travel managers are compressing approved property lists around properties with guaranteed AV standards and bundled meeting space.
- Resorts:Integrated properties on Sentosa and at Changi leverage casino revenue cross-subsidies to absorb compliance costs while anchoring MICE demand through dedicated convention infrastructure. Marina Bay Sands and Resorts World Sentosa sustain competitive positioning through vertical integration of exhibition halls, luxury retail, and entertainment attractions.
- Serviced Apartments:Extended-stay formats capture relocating executives and project-based consultants, with properties near Mount Elizabeth Novena retrofitting rooms with clinical-grade air filtration for medical tourism recovery stays.
- Hostels:Budget dormitory and pod configurations concentrate in Little India and Kampong Glam, serving price-sensitive backpackers and digital nomads on extended visas.
Hotels sit at the top of the volume ranking, with serviced apartments climbing the fastest as corporate relocation patterns extend average length-of-stay.
Service Type:
Cost tier differentiation separates properties that bundle services into rate structures from those unbundling F&B and event access to compete on headline price.
- Room Service:In-room dining operations face margin compression from food delivery platform competition, with premium properties differentiating through 24-hour kitchen availability and personalized dietary accommodation.
- Food & Beverage:On-premise restaurants, bars, and banquet operations generate ancillary revenue while supporting National Environment Agency hygiene grade maintenance. Grade C or below ratings trigger mandatory closure periods that destroy recovery timelines.
- Event Management:Dedicated conference and wedding coordination services anchor MICE demand, with Marina Bay Sands Convention Centre compressing booking windows for adjacent properties through shuttle partnerships.
- Concierge Services:Guest experience design and local arrangement facilitation are expanding as properties invest in loyalty program differentiation and mobile-first platforms.
Food & Beverage operations capture the highest share of ancillary spend, with event management gaining share fastest as corporate procurement teams demand guaranteed meeting space with room blocks.
Client Type:
Application-based segmentation tracks how guest purpose shapes length-of-stay, rate sensitivity, and amenity requirements across Singapore's precincts.
- Business Travelers:Corporate account travelers prioritize proximity to Changi Business Park and one-north precincts, with procurement teams bypassing online travel agencies for direct negotiated rates with predictable spend caps.
- Leisure Tourists:Vacation and sightseeing visitors concentrate demand around Orchard Road retail and Sentosa attractions, with Universal Studios Singapore and marine exhibits extending average guest stays at integrated resorts.
- Long-term Residents:Extended-stay guests including relocating executives and project consultants drive serviced apartment occupancy, particularly near Gleneagles Hospital and the Jurong Lake District transformation zone.
- Families:Multi-generational travel parties seek properties with connecting rooms, child-care facilities, and proximity to Sentosa attractions, with Resorts World Sentosa sustaining competitive position through marine and entertainment offerings.
Business travelers anchor occupancy rate stability, with leisure tourists showing the steepest expansion trajectory as Singapore positions itself as a regional convention hub.
Booking Channel:
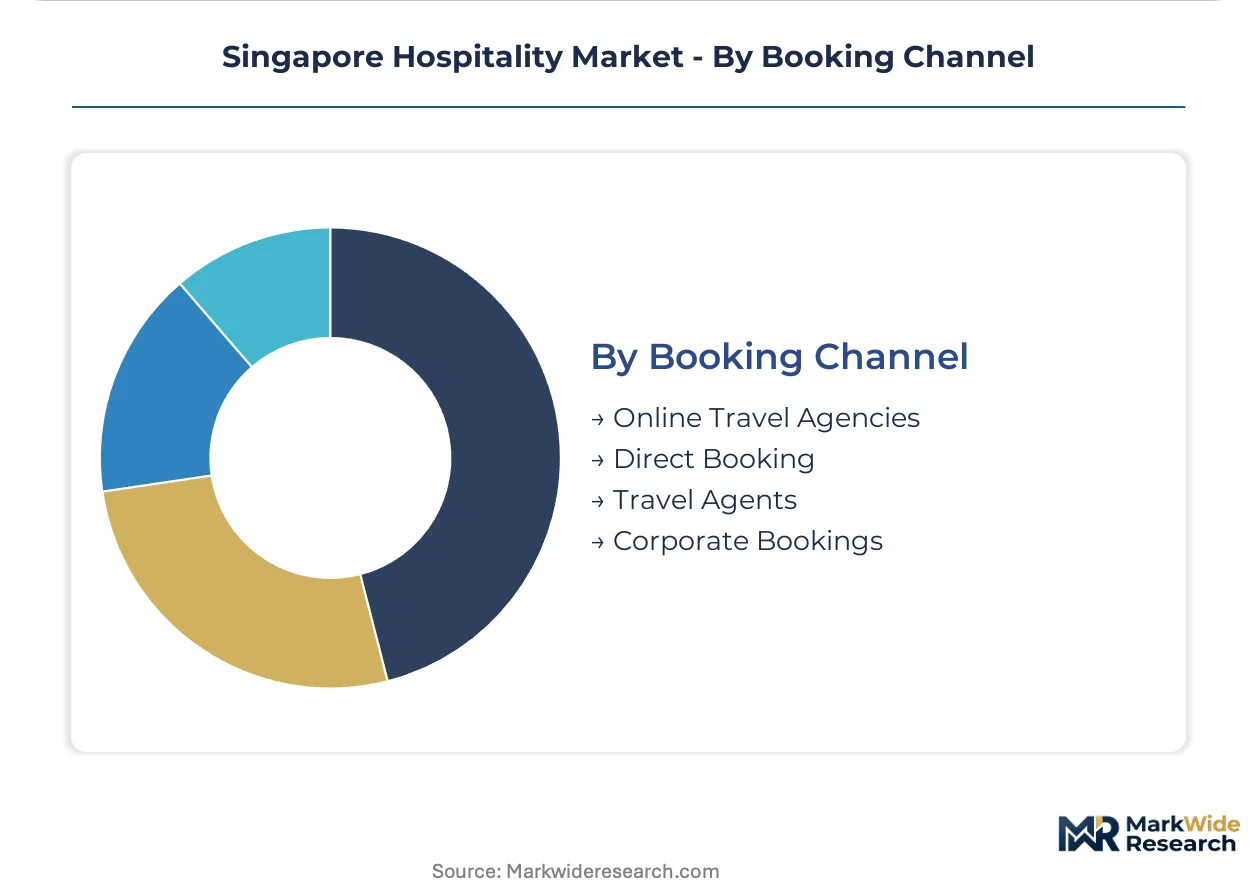
Customer type concentration is shifting as online travel agencies cede share to direct channels and corporate procurement platforms.
- Online Travel Agencies:Third-party platforms control substantial booking volume through price transparency and loyalty program integration, though properties are recovering share through mobile-first reservation platforms.
- Direct Booking:Property-owned websites and loyalty program channels are gaining traction as operators invest in guest data capture and personalized rate offers, particularly at Pan Pacific Hotels Group properties near Changi Airport.
- Travel Agents:Traditional intermediary bookings persist for complex itineraries and group arrangements, though share is compressing as self-service platforms mature.
- Corporate Bookings:Direct negotiated rates with multinational firms are expanding as procurement teams at financial services and pharmaceutical companies demand bundled meeting space with documented ESG compliance.
Online travel agencies retain volume leadership, with corporate bookings climbing the fastest as procurement teams compress approved property lists around properties with guaranteed technical standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marina Bay and Orchard Road anchor Singapore's hospitality concentration, with premium inventory clustering around convention infrastructure and luxury retail corridors. The Urban Redevelopment Authority governs zoning intensity across precincts, while the Singapore Tourism Board enforces licensing standards that elevate operating costs. Sub-regional dynamics reveal where supply expansion meets regulatory constraints.
Central Region
Marina Bay Sands and Resorts World Sentosa compress booking windows for adjacent properties through integrated convention and entertainment infrastructure. The Singapore Tourism Board's Hotel Licensing Framework tightens operational standards across properties in this precinct. Marina Bay's vertical integration of exhibition halls, luxury retail, and casino operations anchors large-scale MICE events.
Orchard Road Precinct
Premium room rates concentrate along Singapore's prime retail corridor where international luxury brands drive footfall. The Urban Redevelopment Authority's density bonuses for mixed-use developments are pulling limited investment westward from this saturated sub-market. Shangri-La Group and comparable operators maintain flagship properties serving corporate travel managers with guaranteed AV standards.
Changi Corridor
Pan Pacific Hotels Group captures extended layover demand with transit-friendly room configurations near Terminal 5 development. The Changi Airport Group's expansion electrifies business travel volumes through Singapore's eastern corridor. Airport-adjacent operators retrofit properties with IoT-enabled systems to compress utility spend.
Jurong Lake District
Density bonuses for mixed-use hospitality developments are pulling investment westward from saturated central precincts. The Urban Redevelopment Authority incentivizes stacking residential, office, and hotel functions to maximize plot ratios. Developers target this transformation zone for new supply injection as the district matures.
Sentosa Island
Cross-border medical tourism partnerships generate extended-stay demand for post-procedure recovery accommodations. The Sentosa Development Corporation's master plan revisions govern supply expansion on the island. Resorts World Sentosa sustains competitive positioning through Universal Studios Singapore and marine attractions that extend average guest stays.
Singapore Hospitality Market Competitive Landscape
Portfolio diversification dominates the current landscape as operators balance premium positioning with select-service expansion. The vendor base concentrates around integrated resort operators with casino revenue cross-subsidies, full-service hotel groups with loyalty scale, and boutique specialists targeting experiential positioning. Strategic archetypes include MICE-anchored integrated resorts, airport-adjacent business hotels, and heritage-luxury conversion properties. Competitive moves center on loyalty program investment and direct booking platform development to recover share from online travel agencies.
Within the integrated resort tier, Marina Bay Sands and Resorts World Sentosa exemplify vertical control over convention infrastructure and entertainment assets. Pan Pacific Hotels Group represents the airport-adjacent business hotel archetype with properties near Changi Airport and the central business district. Among diversified hospitality groups, Far East Hospitality and Shangri-La Group occupy positions spanning premium and select-service segments across multiple Singapore precincts.
| Leading Market Players |
|---|
| Far East Hospitality |
| Pan Pacific Hotels Group |
| Marina Bay Sands |
| Resorts World Sentosa |
| Accor Asia Pacific |
| Capella Hotel Group |
| IHG Hotels & Resorts |
| Hilton Hotels & Resorts |
| Shangri-La Group |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement teams at financial services and pharmaceutical firms compressing approved property lists around guaranteed AV standards and bundled meeting space force supply response toward integrated convention infrastructure, elevating rate premiums for compliant properties while squeezing headline rates for unbundled competitors.
Pricing Analysis
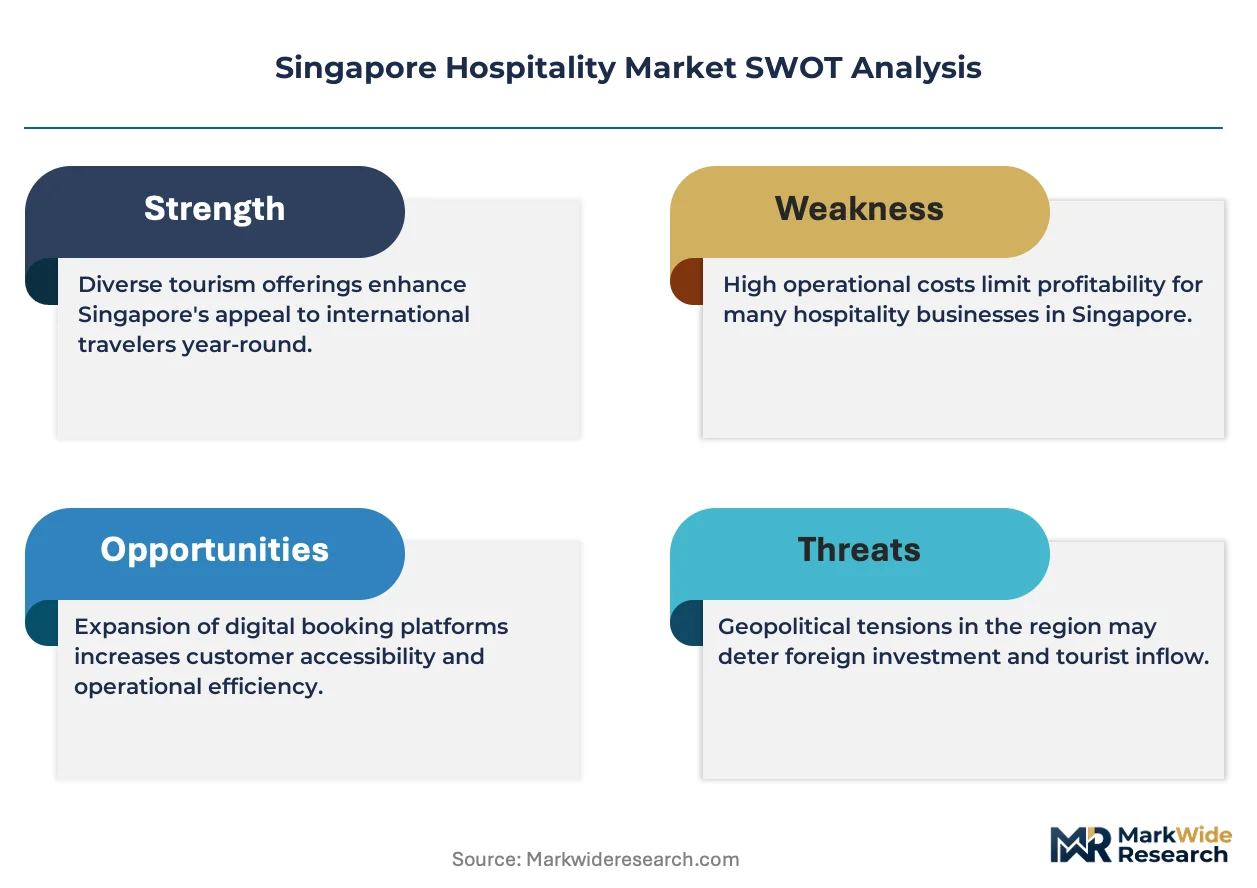
Energy tariff pass-through from Singapore Power's quarterly electricity rate adjustments compresses operating margins for properties with aging chiller plants, creating pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on Green Mark certification level and proximity to MICE infrastructure, with Marina Bay and Orchard Road precincts commanding premiums. Pricing pressure intensifies as online travel agencies force transparency on headline rates. Budget hostels in Little India exhibit highest price sensitivity; integrated resorts with casino cross-subsidies show lowest.
Supply Chain Analysis
Freight costs for imported F&B provisions and hospitality equipment from Malaysia, Thailand, and Australia feed into operating cost structures across Singapore properties. Raw material dependencies center on seafood supply chains, imported linens, and smart building system components from regional manufacturing hubs. Supply chain risk concentrates in single-source vulnerability for premium seafood and specialty ingredients. Distribution runs through consolidated procurement networks serving hotel groups, with direct supplier relationships at luxury properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in properties capturing SkillsFuture subsidies for workforce digital upskilling and those retrofitting for Green Mark Platinum certification to access corporate ESG-mandated rate premiums.
For Market Incumbents: Acquire underperforming mid-market properties in the Jurong Lake District transformation zone to capture density bonus incentives and extend loyalty program footprint before new supply saturates the precinct. Consolidate housekeeping and F&B functions across portfolio properties to absorb Ministry of Manpower work permit rigidities through scale. Defend against independent operator encroachment by locking in multi-year corporate negotiated rates with guaranteed meeting space bundles. For New Entrants and Emerging Players: The Singapore Tourism Board's Hotel Licensing Framework opens a window for white-space capture in the Tampines Regional Centre hospitality gap, where Changi Business Park expansion outpaces branded inventory supply. Target project-based consultant demand with mixed-use developments integrating co-living and short-stay formats. Enter through partnership with established F&B operators to bypass National Environment Agency hygiene grade ramp-up risk. For Investors and Strategic Acquirers: Asymmetric upside sits with airport-adjacent business hotel operators positioned for Terminal 5 traffic electrification. Long-term viability favors properties with district cooling connections and IoT-enabled building management systems already deployed. Monitor Sentosa Development Corporation master plan revisions as supply injection signal for integrated resort exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Green Mark Certification Investment | Platinum ratings unlock corporate ESG-mandated rate premiums from multinational procurement teams. |
| SkillsFuture Subsidy Capture | Workforce Singapore grants enable front-desk retraining into revenue management roles at subsidized cost. |
| Direct Booking Platform Development | Mobile-first reservation systems recover share from online travel agencies and capture guest data. |
| Mixed-Use Development Stacking | Urban Redevelopment Authority density bonuses maximize plot ratios in Jurong Lake District transformation zone. |
| Shuttle Partnership with MICE Anchors | Properties adjacent to Marina Bay Sands Convention Centre compress booking windows through transport integration. |
Research Methodology
Multiple input streams — property development databases, corporate travel procurement disclosures, and regulatory filing repositories — were reconciled through bottom-up and top-down triangulation. Primary interviews with hotel general managers, revenue management directors, corporate travel procurement officers, and Singapore Tourism Board licensing officials were validated against secondary sources including Urban Redevelopment Authority zoning records, National Environment Agency hygiene grade registries, and SkillsFuture program documentation.
Historical booking volume trajectories were cross-referenced against expert panel assessments to construct analytical framework projections across the analysis window. Segmentation dimensions modeled include property type, service configuration, client application, and booking channel, with CAGRs derived from supply pipeline tracking and demand elasticity estimates. Forecast inputs incorporated Changi Airport passenger volume projections and Sentosa Development Corporation master plan revision timelines.
Revisions become necessary when regulatory enforcement intensity shifts, energy tariff volatility exceeds modeled bands, or corporate travel policy ESG mandates accelerate beyond current adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality Management and Services
Saudi Arabia Wedding Services Market
Hospitality Management and Services
Hospitality Staffing Market
Hospitality Management and Services
US Laundry Facilities and Dry-Cleaning Service Market
Hospitality Management and Services
Hotel Ice Dispensers Market
Hospitality Management and Services
Malaysia Hospitality Market
Hospitality Management and Services
Airport Lounge Operation Services Market
Hospitality Management and Services
US Hospitality Market
Hospitality Management and Services
Restaurant Furniture Market
Hospitality Management and Services
Australia HRI Market
Hospitality Management and Services
Mexico Wedding Services Market
Hospitality Management and Services
Luxury Hospitality Market
Hospitality Management and Services
Global Offshore Catering Services Market
Hospitality Management and Services
Catering Management Market
Hospitality Management and Services
Europe Casino Management Market
Hospitality Management and Services
Bowling Centers Market
Hospitality Management and Services
Indonesia Hospitality Real Estate Market