
 Space Power Supply Market | 2026-2036
Space Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Space Power Supply Market Insights
The EU Green Deal is restructuring supplier compliance burdens for European vendors seeking space-qualified component contracts. Northrop Grumman Corporation leverages captive semiconductor fabrication to shield its satellite power bus designs from terrestrial supply volatility. Airbus S.A.S anchors its orbital power portfolio through vertical integration into gallium arsenide cell manufacturing. Saft Groupe SA specializes in lithium-ion cell architectures optimized for geostationary duty cycles.
Space power supply encompasses the generation, storage, conditioning, and distribution of electrical energy for spacecraft operating in vacuum environments with incident solar flux ranging from 1,361 W/m² near Earth to fractional intensities in outer-planet missions. Photovoltaic arrays paired with rechargeable battery banks constitute the dominant architecture for near-Earth applications, while radioisotope thermoelectric generators provide continuous output for deep-space probes beyond Jupiter's orbit. Solar panels dominate the power source type category due to decades of flight heritage and declining specific mass. Batteries represent the fastest-expanding segment as megaconstellation operators demand higher cycle-life chemistries for low-Earth orbit replacement cadences. Thermoelectric technology occupies the mature margin pool, constrained by plutonium-238 availability but insulated from price competition.
FAA launch licensing requirements shape power system qualification protocols for commercial missions originating from U.S. ranges. ESA's Clean Space initiative restricts hazardous material content in European-built power subsystems, affecting cell chemistry selection. NASA's technical standards for crewed lunar surface operations are forcing thermal management redesigns in battery enclosures. Stakeholders must monitor plutonium production restart timelines and terrestrial solar cell tariff schedules to calibrate sourcing strategies.
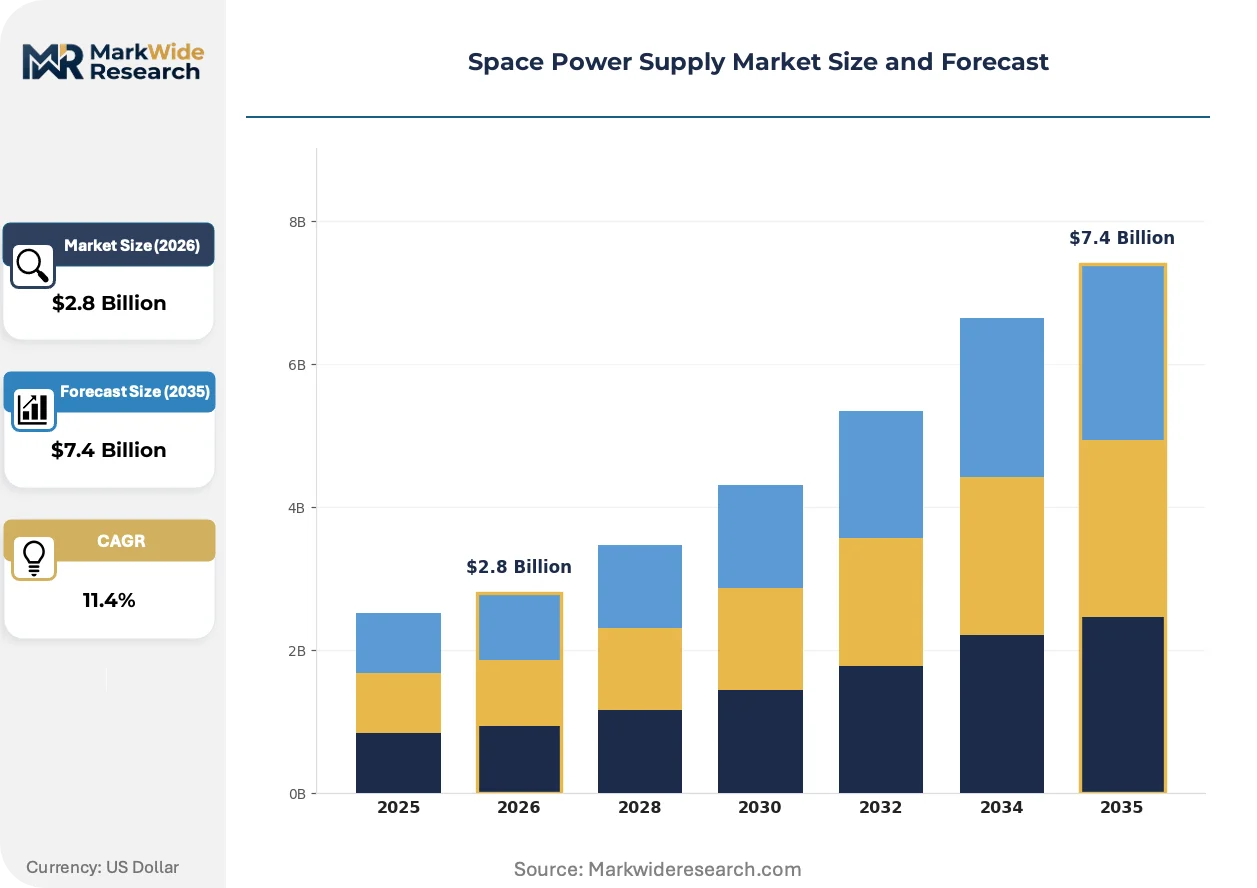
Market Dynamics
Satellite constellation operators are compressing procurement cycles for photovoltaic and battery systems, forcing power subsystem vendors to align qualification timelines with rapid launch cadences rather than traditional geostationary mission schedules.
Growth Catalysts
- Artemis Program Requirements:NASA's crewed lunar surface operations are mandating higher-capacity energy storage architectures, pulling forward demand for advanced thermal management in battery enclosures.
- Low-Earth Orbit Constellation Deployment:Commercial operators deploying broadband megaconstellations are procuring radiation-hardened power buses at volumes previously reserved for government science missions.
- ESA Clean Space Initiative:Hazardous material restrictions are accelerating qualification of alternative cell chemistries for European-built spacecraft power systems.
Market Restraints
- Plutonium-238 Supply Concentration:Radioisotope thermoelectric generator production remains hostage to single-source domestic stockpiles, constraining deep-space mission planning beyond Jupiter orbit.
- Gallium Arsenide Substrate Costs:Epitaxial wafer pricing volatility for triple-junction solar cells compresses margins on high-efficiency array contracts.
- FAA Launch Licensing Protocols:Power system qualification requirements for commercial missions from U.S. ranges extend development timelines relative to uncrewed cargo standards.
Strategic Opportunities
- In-Space Manufacturing Nodes:Orbital assembly platforms will demand regenerative fuel cell systems for eclipse-period operations, opening procurement channels outside traditional satellite prime contracts.
- India's NSIL Launch Access:Polar Satellite Launch Vehicle availability is attracting constellation operators seeking geographic diversification of launch manifests, requiring power subsystem vendors to qualify against ISRO interface standards.
- Perovskite Tandem Integration:Laboratory-scale efficiency gains in thin-film architectures present a pathway to disrupt incumbent silicon and III-V cell dominance in near-Earth applications.
Industry Challenges
- Radiation-Hardened Electronics Talent Pool:Specialized design expertise for single-event upset mitigation remains concentrated among legacy defense contractors, constraining new entrant scaling.
- Cell-to-String Qualification Timelines:Battery cycling validation for geostationary duty spans 18-24 months, misaligning with constellation operator demand for 6-month procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Power Supply Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source Type: Solar Panels, Radioisotope Thermoelectric Generators, Fuel Cells, Batteries, Dynamic Systems Technology: Photovoltaic Cells, Thermoelectric, Piezoelectric, Capacitive, Inductive Application: Satellites, Space Probes, Space Stations, Lunar Modules, Microgravity Experiments End User: Government Space Agencies, Commercial Space Operators, Research Institutions, Defense Organizations |
| Companies Covered | Northrop Grumman Corporation, Airbus S.A.S, Saft Groupe SA, EaglePicher Technologies, GS Yuasa International Ltd, Teledyne Technologies, Moog Inc., L3Harris Technologies, AAC Clyde Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Power Supply Market Trends and Innovations
Power subsystem architectures are bifurcating between mass-optimized designs for disposable small satellites and longevity-focused systems for extended lunar surface operations. This divergence is fragmenting supplier specialization and compressing cross-platform economies of scale.
Solid-state lithium-metal cells are overtaking traditional lithium-ion architectures in next-generation constellation bids. These cells deliver 40% higher energy density for equivalent mass budgets. SpaceX and Amazon's Project Kuiper are qualifying pouch formats for 5-year replacement cadences. The chemistry is overtaking cylindrical 18650 formats that dominated Iridium and Globalstar heritage designs.
REACH substance restrictions are forcing reformulation of electrolyte solvents and thermal interface materials in European-qualified power systems. ECHA's candidate list expansion for persistent organic pollutants now covers several legacy flame retardants used in battery enclosures. Prime contractors serving ESA science missions are redesigning enclosure architectures to eliminate restricted halogenated compounds ahead of 2027 enforcement deadlines.
Fixed-price power subsystem contracts are displacing cost-plus arrangements for commercial constellation awards. Operators now bundle array, battery, and power management unit procurement under single-source agreements with penalty clauses for mass overrun. This consolidation is most visible in Starlink and OneWeb tier-2 supplier selections, where vertically integrated bus vendors capture power subsystem margin previously allocated to specialized cell manufacturers.
Space Power Supply Market Segmentation
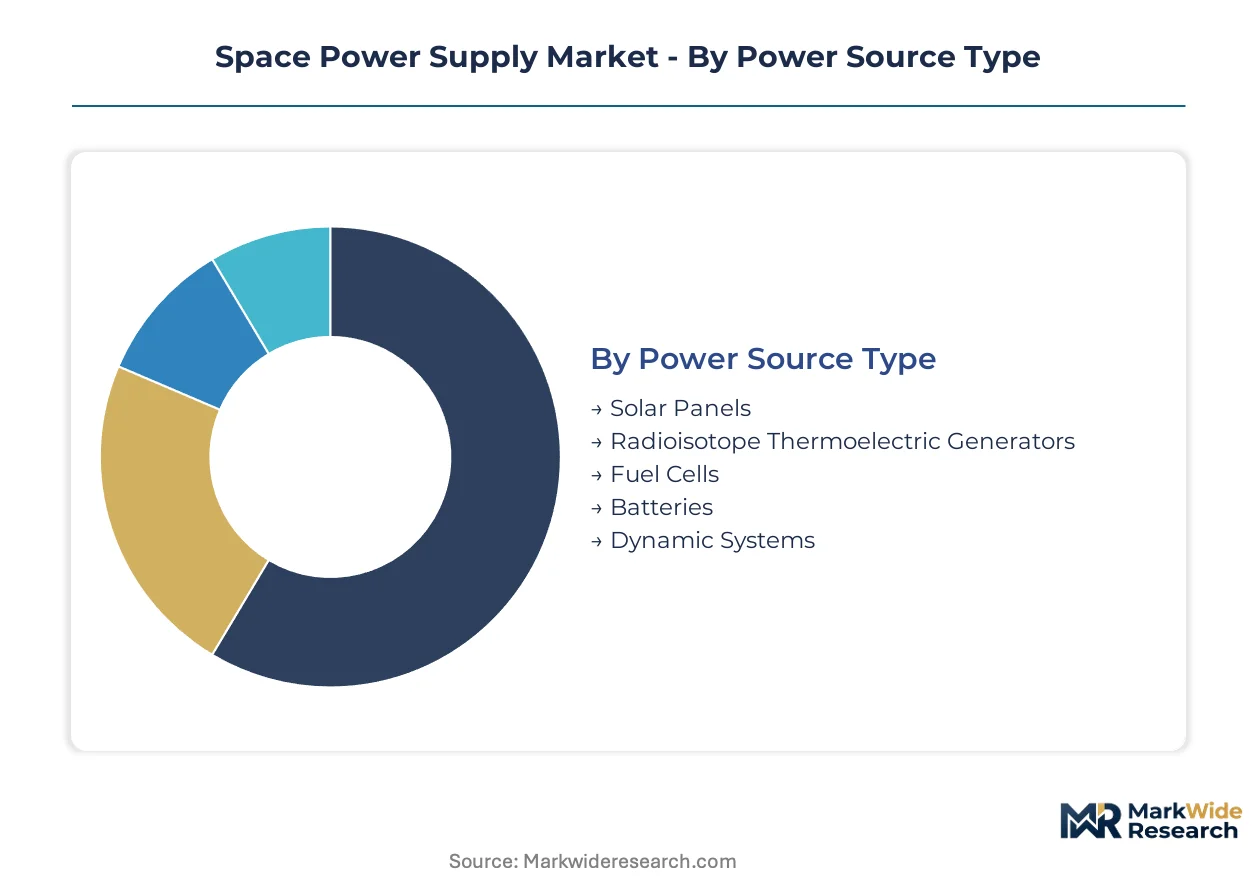
Power subsystem procurement patterns fragment sharply across mission profiles, with constellation operators demanding commodity-scale production while deep-space science missions require bespoke qualification cycles. Segment boundaries increasingly blur as vendors bundle generation, storage, and conditioning hardware under unified contract structures.
Power Source Type:
Supply concentration in photovoltaic manufacturing has shifted procurement leverage toward array integrators with captive cell capacity.
- Solar Panels:Triple-junction gallium arsenide cells deliver conversion efficiencies exceeding 30% in AM0 conditions. Demand concentrates in Starlink-class megaconstellations, where SpaceX and Amazon's Project Kuiper are absorbing triple-junction wafer output previously allocated to geostationary satellites.
- Batteries:Lithium-ion cell architectures dominate near-Earth storage, with solid-state lithium-metal chemistries displacing cylindrical 18650 formats in next-generation bids. Low-Earth orbit replacement cadences are accelerating cycle-life qualification requirements beyond traditional 15-year geostationary benchmarks.
- Radioisotope Thermoelectric Generators:Plutonium-238 decay provides continuous output for missions beyond Jupiter's orbit where solar flux drops below 50 W/m².
- Fuel Cells:Regenerative systems combine hydrogen-oxygen reaction with electrolysis for eclipse-period operations in lunar surface architectures.
- Dynamic Systems:Stirling engines and Brayton cycle converters offer theoretical efficiency advantages for high-power nuclear-electric propulsion concepts.
Today's leader: Solar Panels. Tomorrow's challenger: Batteries.
Technology:
Cost tier stratification separates heritage-qualified technologies from laboratory-scale alternatives seeking flight demonstration opportunities.
- Photovoltaic Cells:Silicon substrates retain cost advantage for small satellite applications, while III-V multi-junction architectures command premium pricing for high-power geostationary platforms. Perovskite tandem integration at laboratory scale threatens incumbent dominance in near-Earth applications.
- Thermoelectric:Bismuth telluride and silicon germanium junctions convert temperature differentials directly to electrical output without moving parts. Radioisotope-powered missions to the outer planets depend on heritage-qualified thermoelectric couples from single-source domestic suppliers.
- Piezoelectric:Vibration harvesting generates microwatt-scale output for distributed sensor networks on large deployable structures.
- Capacitive:Supercapacitor banks provide burst power for electric propulsion thruster ignition sequences.
- Inductive:Wireless power transfer architectures enable cross-satellite energy distribution in formation-flying constellations.
Photovoltaic Cells anchor current revenue. Thermoelectric holds the mature margin pool.
Application:
Volume concentration in low-Earth orbit broadband constellations is compressing margins previously sustained by bespoke geostationary contracts.
- Satellites:Bus power requirements range from 50W for CubeSats to 25kW for high-throughput geostationary platforms. Constellation operators are standardizing 3-5kW bus architectures across hundreds of identical spacecraft.
- Space Stations:International Space Station power systems exceed 100kW combined output from silicon photovoltaic arrays. Commercial successor platforms will demand regenerative fuel cell integration for eclipse operations.
- Space Probes:Outer-planet missions require radioisotope or solar-electric propulsion with power conditioning optimized for extreme radiation environments.
- Lunar Modules:NASA's Artemis lander specifications mandate battery enclosures capable of surviving 14-day lunar night thermal cycling.
- Microgravity Experiments:Suborbital and free-flyer platforms require compact, autonomous power systems with minimal ground intervention.
Satellites command present volume. Space Stations represent the steepest expansion trajectory.
End User:
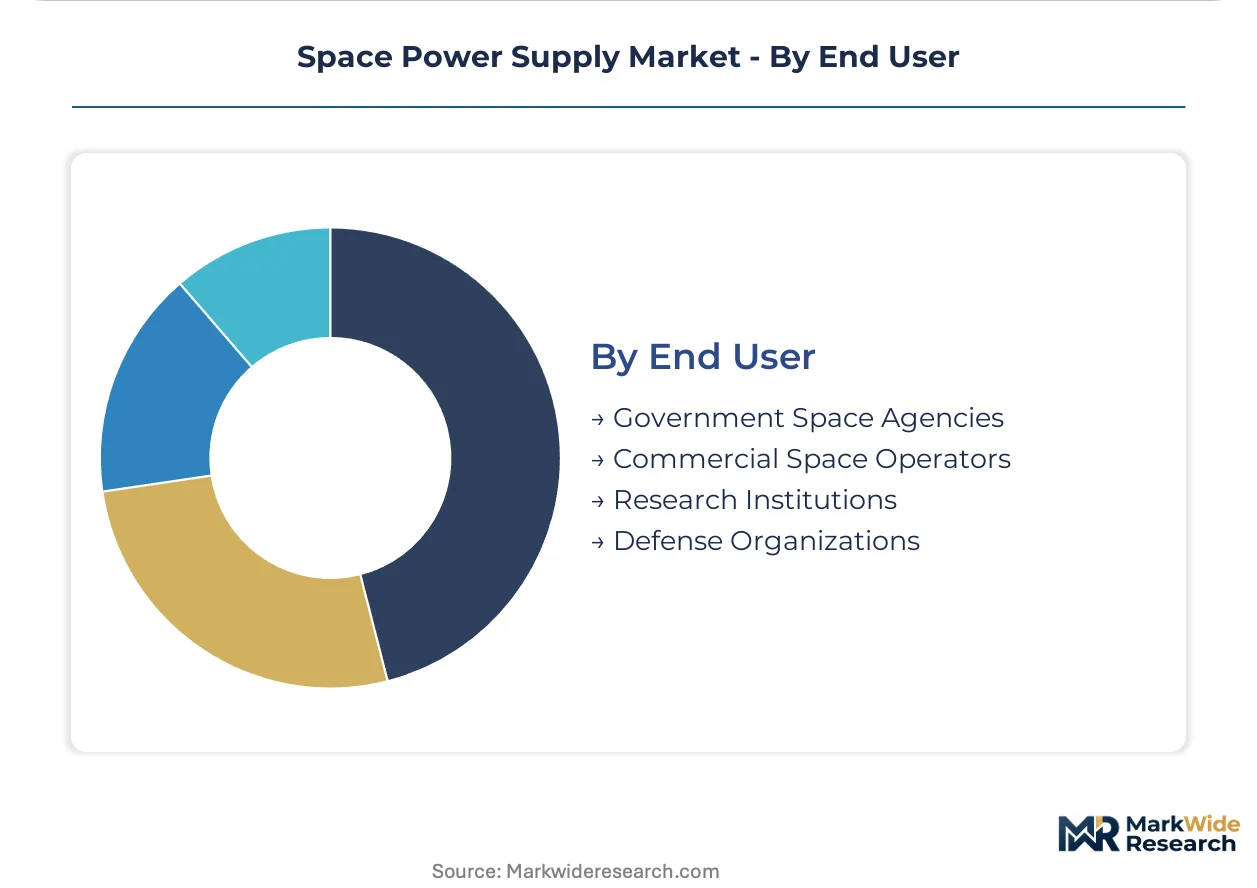
Customer type determines qualification burden, with government agencies demanding full traceability and commercial operators accepting reduced documentation for cost savings.
- Government Space Agencies:NASA, ESA, and JAXA procurement specifications mandate radiation hardness assurance and lot acceptance testing. Artemis program timelines are pulling forward demand for lunar-qualified battery architectures.
- Commercial Space Operators:SpaceX, Amazon, and OneWeb are absorbing power subsystem production capacity at scales previously reserved for aggregated government demand. Fixed-price contracts with mass overrun penalties are displacing cost-plus arrangements.
- Research Institutions:University-led CubeSat missions drive demand for commercial-off-the-shelf power components with minimal space qualification.
- Defense Organizations:Classified spacecraft programs require cleared manufacturing facilities and personnel, constraining vendor pools.
Commercial Space Operators are gaining procurement leverage fastest. Government Space Agencies retain specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiation-hardened electronics specialists concentrate in Southern California and Colorado corridors, anchoring qualification expertise for photovoltaic and battery subsystem vendors serving NASA and commercial constellation operators.
United States
Artemis program timelines are pulling forward demand for lunar-qualified battery architectures with 14-day thermal cycling endurance. FAA launch licensing protocols extend power system qualification timelines for commercial missions from Cape Canaveral and Vandenberg ranges. Huntsville, Alabama and Denver, Colorado host concentrated engineering pools for thermal management enclosure design.
France
Saft Groupe SA's lithium-ion heritage anchors European cell qualification for geostationary duty cycles. ESA's Clean Space initiative restricts hazardous material content in power subsystems, forcing electrolyte solvent reformulation. Toulouse and Paris-Saclay clusters concentrate satellite prime contractor engineering for orbital power bus integration.
Germany
Airbus S.A.S leverages captive gallium arsenide cell fabrication for high-efficiency array contracts. REACH substance restrictions accelerate redesign of thermal interface materials ahead of 2027 enforcement deadlines. Munich and Bremen house concentrated photovoltaic manufacturing and satellite integration facilities.
Japan
GS Yuasa International Ltd supplies heritage-qualified lithium-ion architectures for JAXA science missions. METI technology roadmaps prioritize solid-state cell development for next-generation constellation applications. Tsukuba and Nagoya corridors concentrate space-qualified battery testing and qualification infrastructure.
United Kingdom
AAC Clyde Space exemplifies small satellite power subsystem commoditization for constellation operators. UK Space Agency funding programs support qualification of commercial-off-the-shelf components for reduced documentation burden. Glasgow and Harwell clusters concentrate CubeSat power bus manufacturing and radiation testing capabilities.
Space Power Supply Market Competitive Landscape
The competitive structure tilts toward vertically integrated satellite primes capturing power subsystem margin previously allocated to specialized cell manufacturers. Tier-1 array integrators with captive triple-junction wafer capacity wield procurement leverage over constellation operators. Three archetypes dominate: defense conglomerates with radiation-hardened electronics heritage, European satellite primes with in-house photovoltaic fabrication, and Asian battery specialists with cycle-life qualification depth. Dominant competitive moves include backward integration into semiconductor substrate production and fixed-price contract consolidation bundling generation, storage, and power management units.
Among defense-heritage conglomerates, Northrop Grumman Corporation and L3Harris Technologies exemplify archetypes leveraging captive fabrication to shield satellite power bus designs from terrestrial supply volatility. Within the European prime contractor tier, Airbus S.A.S occupies a position representing vertical control over gallium arsenide cell manufacturing for high-efficiency array contracts. Saft Groupe SA sits within the specialized energy storage archetype, anchoring lithium-ion expertise optimized for geostationary duty cycles and ESA compliance requirements.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Airbus S.A.S |
| Saft Groupe SA |
| EaglePicher Technologies |
| GS Yuasa International Ltd |
| Teledyne Technologies |
| Moog Inc. |
| L3Harris Technologies |
| AAC Clyde Space |
| Others |
Pricing and Supply Chain Analysis
Gallium arsenide epitaxial wafer pricing volatility cascades through space power supply tiers, compressing margins on high-efficiency array contracts while fixed-price constellation procurement bundles generation and storage hardware under single-source agreements with mass overrun penalties.
Pricing Analysis
Fixed-price subsystem contracts now dominate commercial constellation awards, displacing legacy cost-plus arrangements. Price differentiation separates radiation-hardened heritage tiers from commercial-off-the-shelf small satellite components, with government agencies accepting premium documentation burdens while constellation operators prioritize volume scale. Cost compression in battery cell procurement intensifies as solid-state lithium-metal formats displace cylindrical 18650 architectures. Megaconstellation operators exhibit highest price sensitivity, whereas deep-space science missions tolerate premium pricing for bespoke qualification cycles.
Supply Chain Analysis
Specialized radiation-hardened electronics talent pools concentrate in Southern California and Colorado corridors, constraining new entrant scaling in thermal management enclosure design. Manufacturing gravity centers on the United States, France, and Germany, with captive semiconductor fabrication shielding prime contractors from terrestrial supply volatility. Raw material dependencies span plutonium-238 stockpiles for deep-space thermoelectric generators, lithium carbonate for cell chemistries, and germanium substrates for multi-junction arrays. Single-source vulnerability in radioisotope fuel production constrains outer-planet mission planning. Distribution runs through vertically integrated satellite primes capturing subsystem margin previously allocated to specialized cell manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with NASA's Artemis program timelines pulling demand toward lunar-qualified battery architectures with 14-day thermal cycling endurance.
For Market Incumbents: Cement radiation-hardened design expertise concentration through targeted hiring in Huntsville and Denver engineering clusters, while expanding captive gallium arsenide wafer capacity to defend against terrestrial solar cell tariff exposure. Backward integration into semiconductor substrate production remains the critical margin defense lever against emerging thin-film perovskite challengers. For New Entrants and Emerging Players: Enter via India's NSIL launch access corridor, where Polar Satellite Launch Vehicle availability attracts constellation operators seeking geographic diversification and requires power subsystem qualification against ISRO interface standards. Solid-state lithium-metal cell manufacturing for low-Earth orbit replacement cadences represents the most penetrable white-space, with pouch format qualification partnerships offering the clearest go-to-market path. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized energy storage archetypes possessing cycle-life qualification depth and ESA Clean Space compliance infrastructure. Long-term viability hinges on positioning for in-space manufacturing node procurement as orbital assembly platforms demand regenerative fuel cell systems. Watch plutonium-238 production restart timelines as the critical inflection signal for deep-space mission pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Substrates | Captive gallium arsenide wafer production shields Airbus and Northrop Grumman from epitaxial pricing volatility. |
| Solid-State Cell Chemistry Qualification | GS Yuasa and Saft Groupe SA are validating lithium-metal architectures for 5-year constellation replacement cycles. |
| Regenerative Fuel Cell Development | NASA's Artemis lander specifications pull forward demand for hydrogen-oxygen systems with eclipse-period electrolysis. |
| REACH Compliance Redesign | European primes are eliminating halogenated flame retardants from battery enclosures ahead of ECHA enforcement deadlines. |
| ISRO Interface Standard Qualification | Power subsystem vendors qualifying against Indian standards gain access to NSIL's Polar Satellite Launch Vehicle manifest. |
Research Methodology
Coverage spans the United States, France, Germany, Japan, and the United Kingdom, with primary inputs from each market cluster combining interviews with satellite prime contractor procurement officers, battery subsystem engineering directors, space agency program managers, and launch range qualification specialists. Secondary validation draws from FAA launch licensing databases, ESA Clean Space technical standards, NASA Artemis program specifications, and customs records for space-qualified component trade flows. Bottom-up segment sizing triangulates against top-down market consolidation estimates.
Granularity-level modeling disaggregates power source type, technology tier, application profile, and end-user category across the projection horizon. Analytical frameworks derive expansion trajectories from constellation deployment schedules, lunar mission timelines, and regulatory compliance phase-ins. Modeled inputs include megaconstellation operator procurement volumes, plutonium-238 production capacity restarts, and REACH substance restriction enforcement calendars.
The model holds under baseline launch cadence assumptions and stable radioisotope fuel availability; deviation in Artemis program funding levels or plutonium stockpile release schedules would shift subsystem demand timing and chemistry selection patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Blockchain in BFSI Market
Others
Moveable Water Tap Market
Others
Latin America Video Conferencing Hardware Market
Others
Coconut Activated Carbon Market
Others
Medium-Voltage Switchgear Market
Others
Video Paas Market
Others
Smart Doorbell Market
Others
Global Emergency Spill Response Market
Others
Manometers Market
Others
Tobacco Packaging Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Global Optical Comparator Market
Others
United States Printed Signage Market
Others
Global Recruitment and Staffing Market
Others
Snus Market
Others
Conditional Access System (CAS) Market