
 Latin America Video Conferencing Hardware Market | 2026-2036
Latin America Video Conferencing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Video Conferencing Hardware Market Insights
Silicon carbide thermal management substrates are restructuring heat dissipation economics in high-resolution video conferencing endpoints, enabling denser component packing without fan noise penalties. Logitech International SA leverages its supply chain scale to dominate USB peripheral distribution across Brazilian retail channels. Cisco Systems Inc. anchors enterprise-grade security certifications in its codec architectures, sustaining premium positioning in government and financial verticals. Poly Inc. specializes in acoustic beamforming arrays that differentiate its speakerphone portfolio in noisy open-plan deployments.
Latin America video conferencing hardware encompasses physical endpoints—video cameras, microphones, speakers, and collaboration bars—that capture, process, and transmit audiovisual signals for real-time remote communication, typically supporting H.264/H.265 encoding at 1080p or 4K resolution with sub-150ms latency thresholds. These devices serve commercial and institutional users requiring synchronous visual collaboration across distributed locations. Collaboration bars represent the fastest-growing product category as all-in-one form factors displace discrete component assemblies in mid-market conference rooms. HD technology still occupies the largest installed base, though 4K adoption accelerates in executive boardroom segments where display resolution expectations have risen. Corporate applications command the deepest margin pools due to longer replacement cycles and higher service attach rates compared to education or healthcare verticals.
Brazil's national telecommunications regulator ANATEL mandates electromagnetic compatibility and radio frequency certifications for wireless conferencing peripherals, creating compliance barriers that favor established suppliers with in-country testing relationships. Mexico's IFT equipment approval framework shapes demand by determining which SKUs distributors can stock, directly affecting product availability timelines for small business buyers. Stakeholders must monitor evolving data localization requirements across Andean and Southern Cone jurisdictions, as pending cloud infrastructure rules could force architecture changes in cloud-connected endpoints.
Market Dynamics
Hybrid work permanence across Brazilian and Mexican enterprises is compressing refresh cycles for conference room infrastructure, forcing hardware vendors to align product roadmaps with IT department consolidation mandates rather than discretionary facility budgets.
Growth Catalysts
- IFT Certification Streamlining:Mexico's telecommunications regulator has reduced equipment approval timelines, enabling faster SKU availability for small business distributors.
- Silicon Carbide Thermal Substrates:These materials enable fanless 4K camera designs that satisfy acoustic requirements in open-plan corporate deployments.
- São Paulo Corporate Corridor:Financial services and professional services firms in this cluster sustain premium endpoint procurement volumes despite broader IT budget constraints.
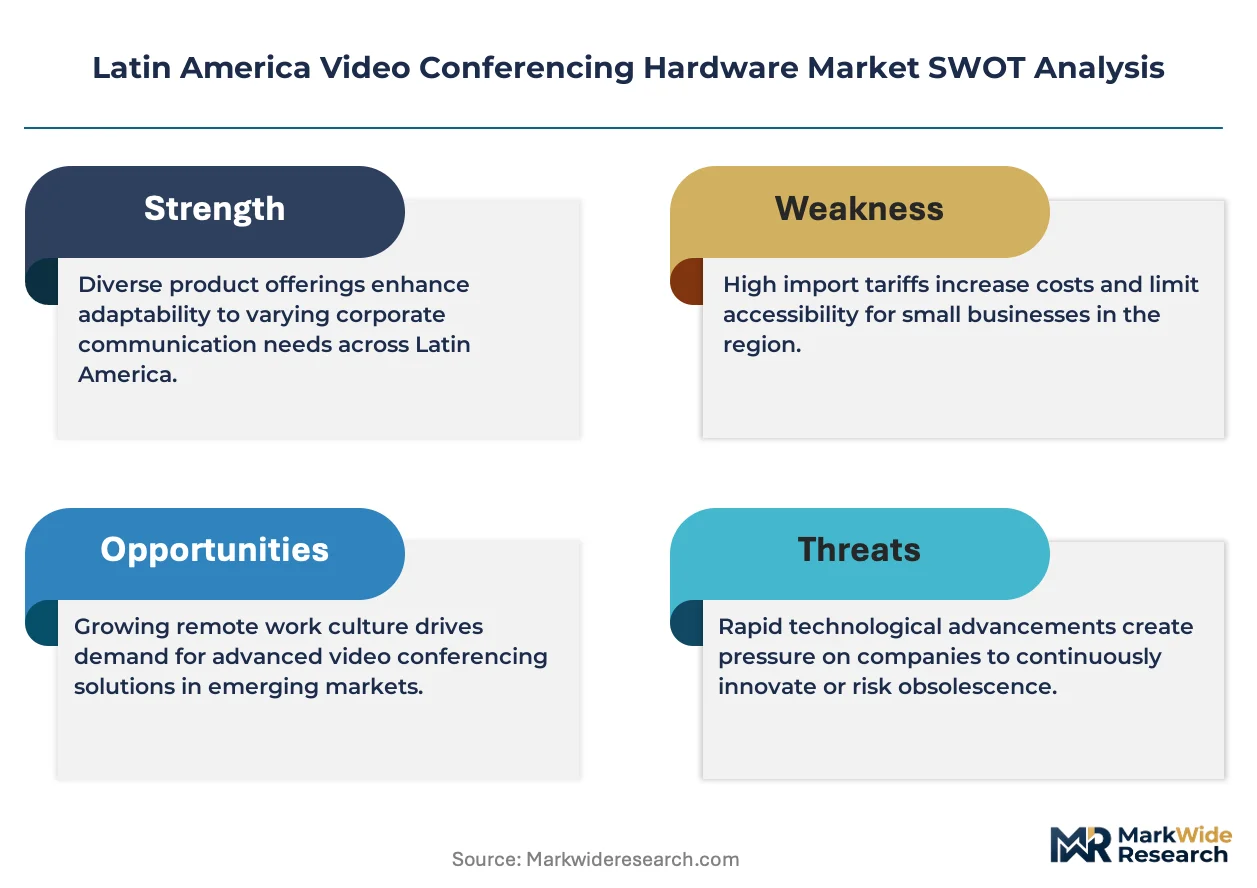
Market Restraints
- ANATEL Compliance Burden:Brazil's electromagnetic compatibility and radio frequency certification requirements favor established suppliers with in-country testing relationships, raising barriers for new entrants.
- Discrete Component Assembly Displacement:Collaboration bars are displacing traditional multi-vendor room builds, compressing addressable market for standalone microphone and speaker vendors.
- Cloud Infrastructure Localization:Pending data residency rules across Andean and Southern Cone jurisdictions could force architecture changes in cloud-connected endpoints, extending development cycles.
Strategic Opportunities
- Mid-Market Collaboration Bars:All-in-one form factors remain underpenetrated outside São Paulo and Mexico City corporate cores, with secondary cities presenting whitespace for volume-tier products.
- Healthcare Vertical Expansion:Telemedicine infrastructure mandates in several Latin American jurisdictions are creating dedicated procurement streams for HIPAA-aligned endpoint configurations.
- Acoustic Beamforming Convergence:Integration of AI-driven noise cancellation with hardware beamforming arrays opens differentiation in education and co-working space deployments.
Industry Challenges
- Legacy Codec Integration:Enterprise IT departments face complexity marrying new H.265 endpoints with existing H.264 infrastructure, extending deployment timelines and support costs.
- Specialized Field Engineering Scarcity:Room acoustics optimization and network QoS configuration for sub-150ms latency require skills concentrated in major metropolitan integrators, limiting rollout velocity in peripheral markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Video Conferencing Hardware Market |
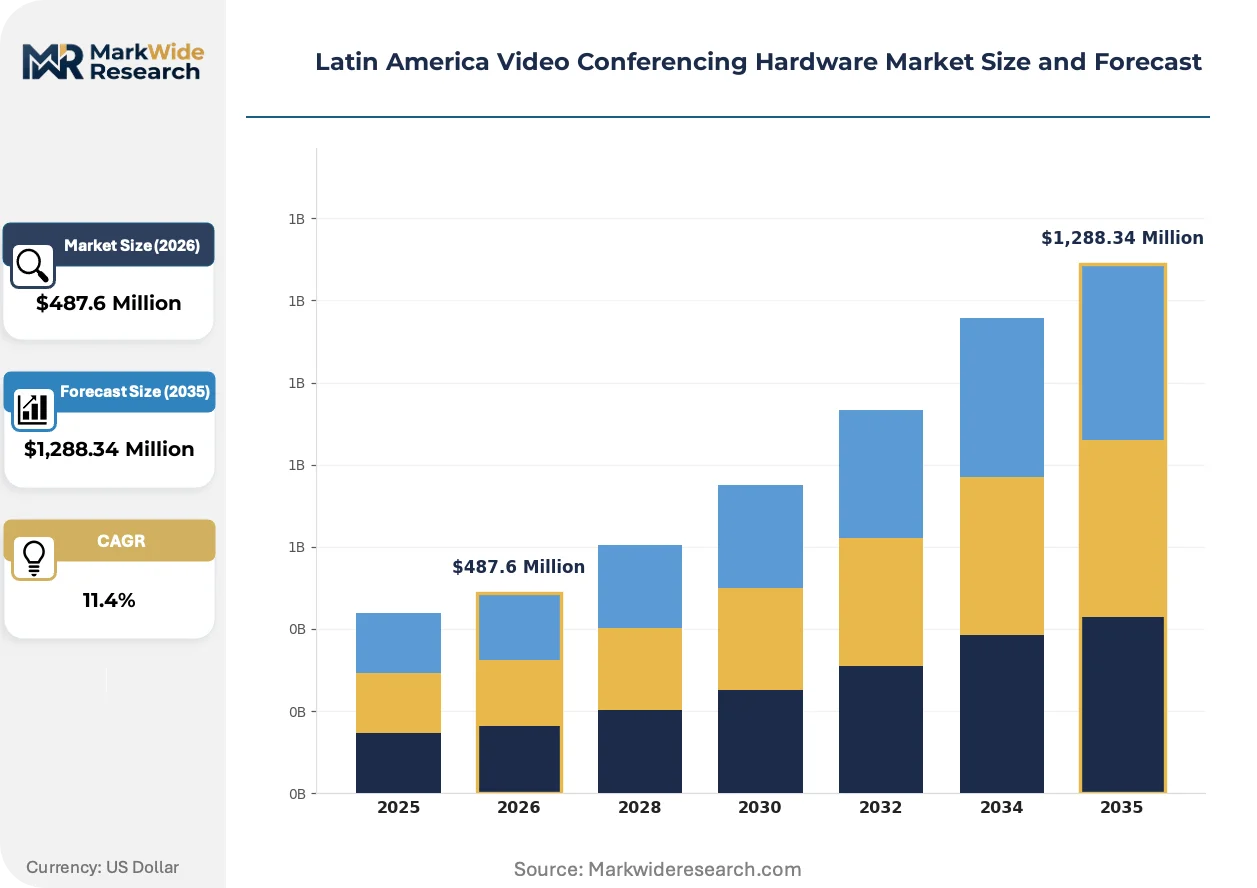
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Cameras, Microphones, Speakers, Collaboration Bars Technology: HD, 4K, Wireless, VoIP Application: Corporate, Education, Healthcare, Government End User: Small Businesses, Enterprises, Educational Institutions, Healthcare Providers |
| Companies Covered | EPOS, Poly Inc, Cisco Systems Inc., Logitech International SA, Jabra, Huawei Technologies Co. Ltd, Panasonic Corporation, Dahua Technology Co. Ltd, Barco NV, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Video Conferencing Hardware Market Trends and Innovations
Hardware architecture is converging around intelligent edge processing, with on-device inference engines reshaping how video conferencing endpoints handle bandwidth constraints and privacy requirements across Latin American enterprise networks.
Edge-based AI inference engines are decentralizing compute loads from cloud infrastructure to local endpoints. Large Brazilian banks and professional services firms are deploying these systems to maintain call quality during intermittent connectivity events. This shift is decentralizing vendor power away from pure cloud-platform providers toward hardware-software integrated suppliers.
ANATEL's evolving electromagnetic compatibility framework is tightening emission standards for wireless peripherals in enterprise environments. Manufacturers must redesign RF shielding and antenna configurations to maintain certification eligibility. Brazilian government and financial verticals are responding by tightening procurement specifications to pre-qualify only compliant SKUs.
Facility managers are consolidating vendor relationships around single-source room system contracts rather than assembling best-of-breed components. Systems integrators in Mexico City and São Paulo are capturing this shift through managed service attachments. Education and healthcare verticals exhibit the most pronounced preference for bundled deployment and support agreements.
Latin America Video Conferencing Hardware Market Segmentation
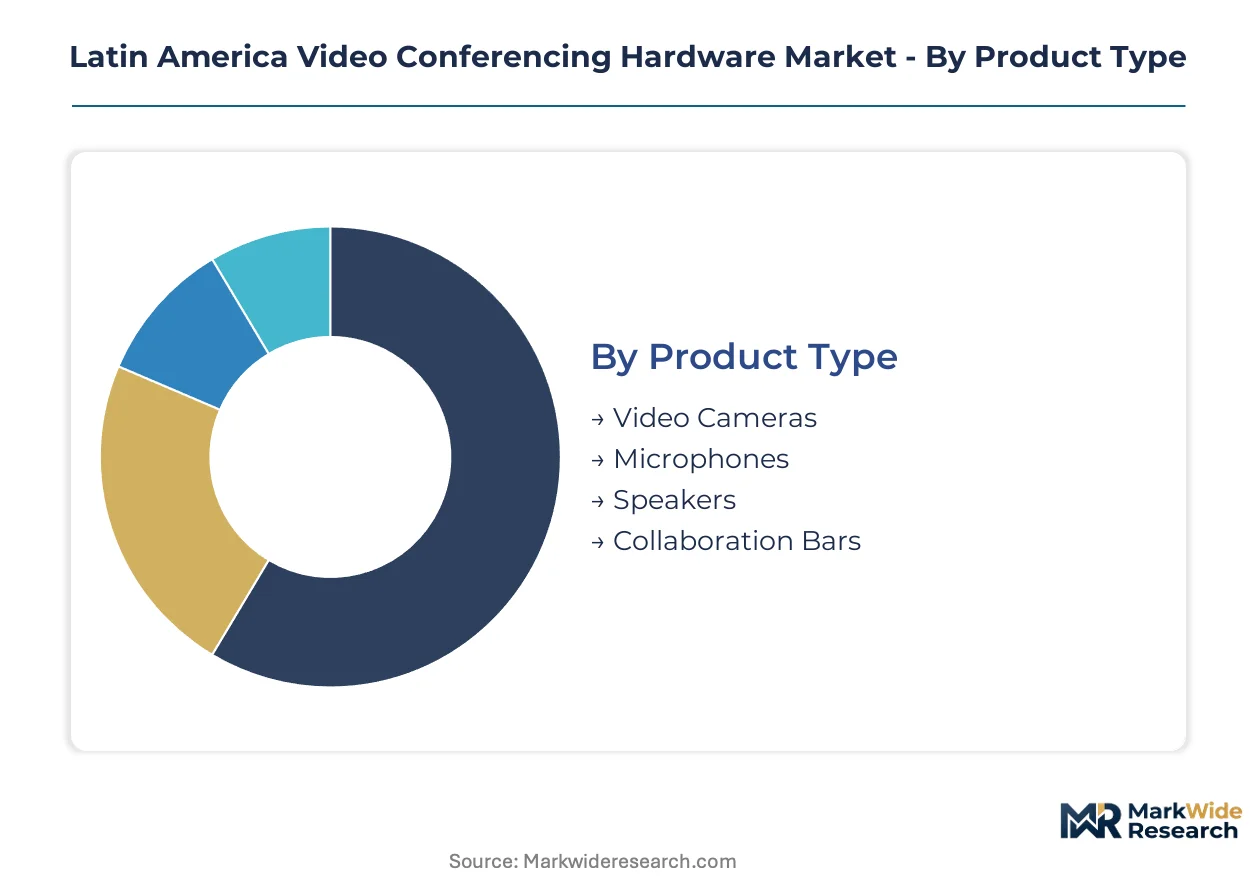
Segmentation in Latin America video conferencing hardware reveals how procurement patterns diverge across technical specifications, organizational scale, and regulatory exposure. Understanding these fault lines enables suppliers to align certification investments and distribution partnerships with actual demand concentration.
Product Type:
Standardization dominates at the low end with USB peripherals, while integrated room systems require extensive customization for acoustic and network conditions across Brazilian and Mexican corporate facilities.
- Video Cameras:Fixed and PTZ units supporting H.265 encoding at 1080p or 4K resolution with sub-150ms latency thresholds. São Paulo financial services firms drive premium 4K procurement despite broader IT budget constraints.
- Collaboration Bars:All-in-one form factors integrating camera, microphone, and speaker arrays in single enclosures. These units are displacing discrete component assemblies in mid-market conference rooms across Mexico City and secondary Brazilian cities.
- Microphones:Beamforming arrays and tabletop units for room-scale audio capture. ANATEL electromagnetic compatibility certification shapes available SKUs for wireless variants.
- Speakers:Soundbars and satellite units completing room audio systems. Demand concentrates in education verticals requiring wide-area coverage.
Most installed capacity flows through Video Cameras. Expansion is steepest in Collaboration Bars.
Technology:
Cost tiers separate legacy infrastructure from next-generation deployments, with premium segments commanding three-year replacement cycles versus seven-year horizons in baseline categories.
- HD:1080p H.264 encoding remains the largest installed base across Latin American enterprises. Legacy infrastructure compatibility requirements extend deployment timelines in government and healthcare verticals.
- 4K:Ultra-high resolution with H.265 compression and silicon carbide thermal management. Executive boardroom segments in São Paulo corporate corridor sustain premium positioning despite higher unit costs.
- Wireless:RF-based peripherals reducing cable infrastructure requirements. IFT certification streamlining in Mexico accelerates SKU availability for small business distributors.
- VoIP:Packet-switched audio transmission integrated with unified communications platforms. Cloud infrastructure localization requirements across Andean jurisdictions force architecture modifications.
HD retains the dominant installed base. 4K is climbing the fastest among technology tiers.
Application:
Volume concentration sits with corporate deployments, while margin pools deepen in segments with specialized compliance requirements and longer support attach rates.
- Corporate:Financial services and professional services firms in São Paulo and Mexico City drive premium endpoint procurement with managed service attachments.
- Healthcare:Telemedicine infrastructure mandates create dedicated procurement streams for HIPAA-aligned endpoint configurations.
- Education:K-12 and university deployments favor bundled deployment and support agreements with systems integrators.
- Government:ANATEL pre-qualified SKU requirements restrict vendor eligibility in Brazilian federal and state procurement.
Corporate applications absorb the deepest volume. Healthcare shows the steepest expansion trajectory.
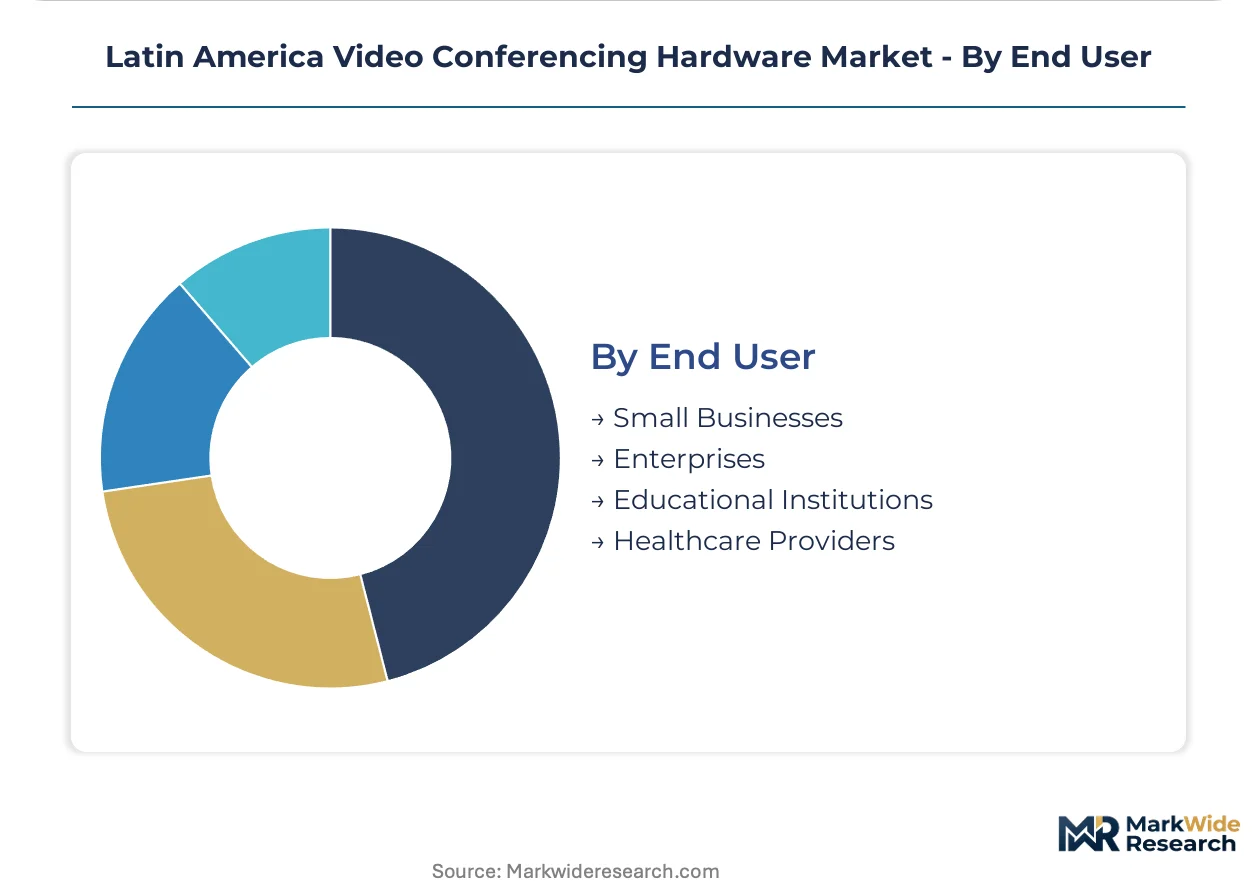
End User:
Customer type determines purchasing modality, with enterprises consolidating around single-source contracts while smaller buyers rely on distributor stock availability shaped by regulatory approval timelines.
- Enterprises:Multi-site organizations with dedicated IT departments and facility consolidation mandates. These buyers compress refresh cycles for conference room infrastructure.
- Small Businesses:Organizations purchasing through retail and distributor channels. IFT certification timelines directly affect product availability for this segment.
- Healthcare Providers:Hospitals and clinics requiring telemedicine-capable endpoints with data localization compliance.
- Educational Institutions:Universities and school districts prioritizing acoustic performance in multi-purpose spaces.
Enterprises command the largest procurement volumes. Healthcare Providers are gaining share fastest among end user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's corporate technology corridor anchors procurement volume across Latin America, with financial services and professional services firms driving premium endpoint demand despite broader IT budget constraints in secondary markets.
Brazil
ANATEL certification requirements for electromagnetic compatibility and radio frequency standards shape hardware availability timelines for wireless peripherals. Brazilian federal and state procurement channels restrict vendor eligibility to pre-qualified SKUs, favoring established suppliers with in-country testing relationships. São Paulo concentrates demand from banking and legal sectors deploying 4K cameras and collaboration bars.
Mexico
IFT streamlining of equipment approval timelines accelerates SKU availability for small business distributors purchasing through retail channels. Mexico City enterprises compress refresh cycles for conference room infrastructure under IT consolidation mandates. Nuevo León's manufacturing and technology corridor generates secondary demand for mid-market collaboration bars.
Argentina
Economic volatility compresses procurement timelines for imported hardware, forcing distributors to optimize inventory turnover on certified endpoints. The country's national telecommunications regulator maintains equipment type approval requirements that extend market entry lead times. Buenos Aires corporate clusters sustain demand for USB peripherals and entry-level video cameras.
Chile
Telemedicine infrastructure mandates create dedicated procurement streams for HIPAA-aligned endpoint configurations in Santiago healthcare networks. The country's data protection authority shapes cloud-connected architecture requirements for cross-border video traffic. Valparaíso logistics corridors facilitate hardware distribution to Andean markets.
Colombia
Bogotá's financial services sector drives enterprise-grade security certification requirements in codec procurement specifications. Pending cloud infrastructure localization rules could force architecture modifications in cloud-connected endpoints. Medellín technology clusters exhibit growing demand for acoustic beamforming arrays in co-working space deployments.
Latin America Video Conferencing Hardware Market Competitive Landscape
Global majors compete with regional champions across certification relationships and distribution reach. Market structure tilts toward consolidated supply at the premium tier, with fragmented competition in USB peripherals and entry-level cameras. Three archetypes dominate: integrated systems vendors with security certifications, peripheral specialists leveraging retail scale, and acoustic engineering-focused suppliers. Dominant competitive moves include strategic partnerships with systems integrators and portfolio diversification into all-in-one collaboration bars.
Within the integrated systems tier, Cisco Systems Inc. and Poly Inc. exemplify vendors anchoring enterprise-grade positioning through security architecture. Logitech International SA occupies a scale-driven position across Brazilian retail channels for USB peripherals. EPOS and Jabra represent specialists in acoustic beamforming technology, sitting within the audio-centric supplier archetype targeting open-plan deployments.
| Leading Market Players |
|---|
| EPOS |
| Poly Inc |
| Cisco Systems Inc. |
| Logitech International SA |
| Jabra |
| Huawei Technologies Co. Ltd |
| Panasonic Corporation |
| Dahua Technology Co. Ltd |
| Barco NV |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide thermal management adoption in 4K camera production simultaneously compresses unit manufacturing costs and concentrates supply relationships among substrate-qualified foundries. This materials transition rewards vendors with backward integration into thermal component sourcing, while distributors face margin pressure from consolidated upstream control.
Pricing Analysis
Input-cost pass-through from electromagnetic compatibility testing and radio frequency certification dominates pricing formation across Brazilian and Mexican distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates ANATEL-pre-qualified enterprise SKUs from uncertified retail peripherals, with certification grade and volume scale as primary differentiation drivers. Cost compression in mid-market collaboration bars is intensifying because IFT streamlining has accelerated SKU proliferation. Small business buyers exhibit highest price sensitivity, while São Paulo financial services firms show lowest sensitivity due to security specification mandates.
Supply Chain Analysis
Certification and qualification gating through ANATEL and IFT frameworks concentrates hardware sourcing among established suppliers with in-country testing infrastructure. Manufacturing concentrates in China, Taiwan, and Mexico for camera modules, audio chipsets, and final assembly operations. Raw material dependencies span silicon carbide substrates, CMOS sensors, and rare-earth magnet components for speaker arrays. Single-source vulnerability sits with specialized acoustic beamforming foundries serving premium tier production. Distribution runs through systems integrator partnerships in São Paulo and Mexico City, with retail channels handling USB peripheral volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Mexico's streamlined IFT certification timelines and Brazil's rigorous ANATEL compliance costs creates margin expansion opportunities for dual-qualified suppliers. Regulatory cost differentials of this magnitude typically sustain competitive positioning for 18-24 months.
For Market Incumbents: Anchor enterprise-grade positioning through ANATEL pre-qualification investments that new entrants cannot replicate within compressed procurement windows. Deepen acoustic engineering capabilities to defend against collaboration bar displacement of discrete speakerphone assemblies. Certification investment represents the priority defensive lever against emerging Chinese peripheral manufacturers. For New Entrants and Emerging Players: Begin with secondary Brazilian cities outside São Paulo's corporate corridor, where mid-market collaboration bar penetration remains underdeveloped and distributor relationships are less entrenched. Target healthcare vertical procurement streams created by telemedicine infrastructure mandates, leveraging HIPAA-aligned endpoint configurations as entry wedge. Direct-to-integrator partnerships bypass retail certification delays. For Investors and Strategic Acquirers: Roll-up economics work for acoustic engineering specialists because beamforming IP scarcity concentrates vendor power in education and co-working space deployments. Five-to-ten year viability hinges on cloud infrastructure localization rules forcing architecture modifications that favor hardware-software integrated suppliers over pure peripheral vendors. Monitor pending data residency legislation across Andean jurisdictions as inflection signal for cloud-connected endpoint consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Pre-Qualification Investment | Brazilian federal procurement channels restrict vendor eligibility to certified SKUs, favoring established suppliers. |
| Acoustic Beamforming IP Acquisition | Education and co-working space deployments prioritize AI-driven noise cancellation integrated with hardware arrays. |
| Mid-Market Collaboration Bar Launch | All-in-one form factors displace discrete component assemblies in secondary cities outside São Paulo corridor. |
| Healthcare Vertical Partnership | Telemedicine infrastructure mandates create dedicated procurement streams for HIPAA-aligned endpoint configurations. |
| Silicon Carbide Thermal Integration | Fanless 4K camera designs satisfy acoustic requirements in open-plan corporate deployments across Mexico City. |
Research Methodology
Multiple input streams — hardware procurement managers at Brazilian financial services firms, Mexican systems integrators, ANATEL certification consultants, IFT regulatory affairs specialists, and acoustic engineering directors — were reconciled against secondary validation from customs import records, telecommunications regulator disclosure filings, and SEC 10-K segment reporting. Bottom-up endpoint shipment analysis and top-down IT infrastructure spending estimates were triangulated to establish market sizing.
Data-stream reconciliation across product type, technology tier, application vertical, and end-user scale dimensions informed the analytical framework over the projection horizon. CAGRs were derived from regression analysis against hybrid work permanence indicators and refresh cycle compression patterns. Forecast inputs incorporated ANATEL certification timeline variability and IFT equipment approval velocity assumptions.
Several conditions sit outside the modeled scope, including potential electromagnetic compatibility standard revisions, cloud infrastructure localization rule implementations, and macroeconomic volatility affecting Argentine and Colombian import financing. Forecasts reflect documented assumptions about regulatory stability and enterprise IT consolidation continuity. A model refresh is warranted upon material change in data residency legislation across Andean or Southern Cone jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Snus Market
Others
Smart Home Service Market
Others
Flexible PVC Films and Sheets Market
Others
Bicycle Panniers Market
Others
Retail Media Platform Market
Others
Global Pregnancy Tracker Apps Market
Others
Middle East and Africa Home Care Packaging Market
Others
Construction Wearables Market
Others
Europe Battery Packaging Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Port Replicator Market
Others
North America Commercial Vehicles Lubricants Market
Others
Drum Motor Market
Others
Interference Mitigation Filters Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Land Surveying Equipment Market