
 Language Translation Device Market | 2026-2036
Language Translation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Language Translation Device Market Analysis
China is narrowing the gap between component sourcing and finished-device assembly through Shenzhen-based manufacturing clusters. iFLYTEK leverages its speech recognition heritage to dominate Mandarin-centric neural machine translation. Timekettle anchors its position in wearable earbuds with real-time bidirectional interpretation. Pocketalk competes through retail channel density in Japanese electronics stores and airport kiosks.
A language translation device converts spoken or written input from one natural language into another via embedded processors, cloud APIs, or hybrid architectures operating with latency thresholds below 500 milliseconds for conversational use. These systems serve commercial communication, emergency response, and cross-border service delivery where human interpreters prove unavailable or cost-prohibitive. Handheld devices occupy the highest margin tier due to dedicated hardware and offline capability in remote locations. AI-powered solutions attract the fastest investment as large language models compress error rates in low-resource language pairs. Smartphone apps remain the volume leader but face monetization pressure from free alternatives.
The EU AI Act classifies public-sector translation systems as high-risk applications, mandating human oversight and accuracy auditing before deployment. Japan's METI promotes JIS-standard interoperability for tourism-facing devices through subsidy programs targeting regional municipalities. The FCC in the United States enforces electromagnetic compatibility and hearing-aid compatibility for wireless translation hardware entering commercial channels. Stakeholders must weigh regulatory certification timelines against the accelerating pace of model updates from upstream AI providers.
Market Dynamics
Neural machine translation compression is collapsing latency thresholds below human conversation speed while fragmenting hardware margins between dedicated devices and smartphone-integrated solutions.
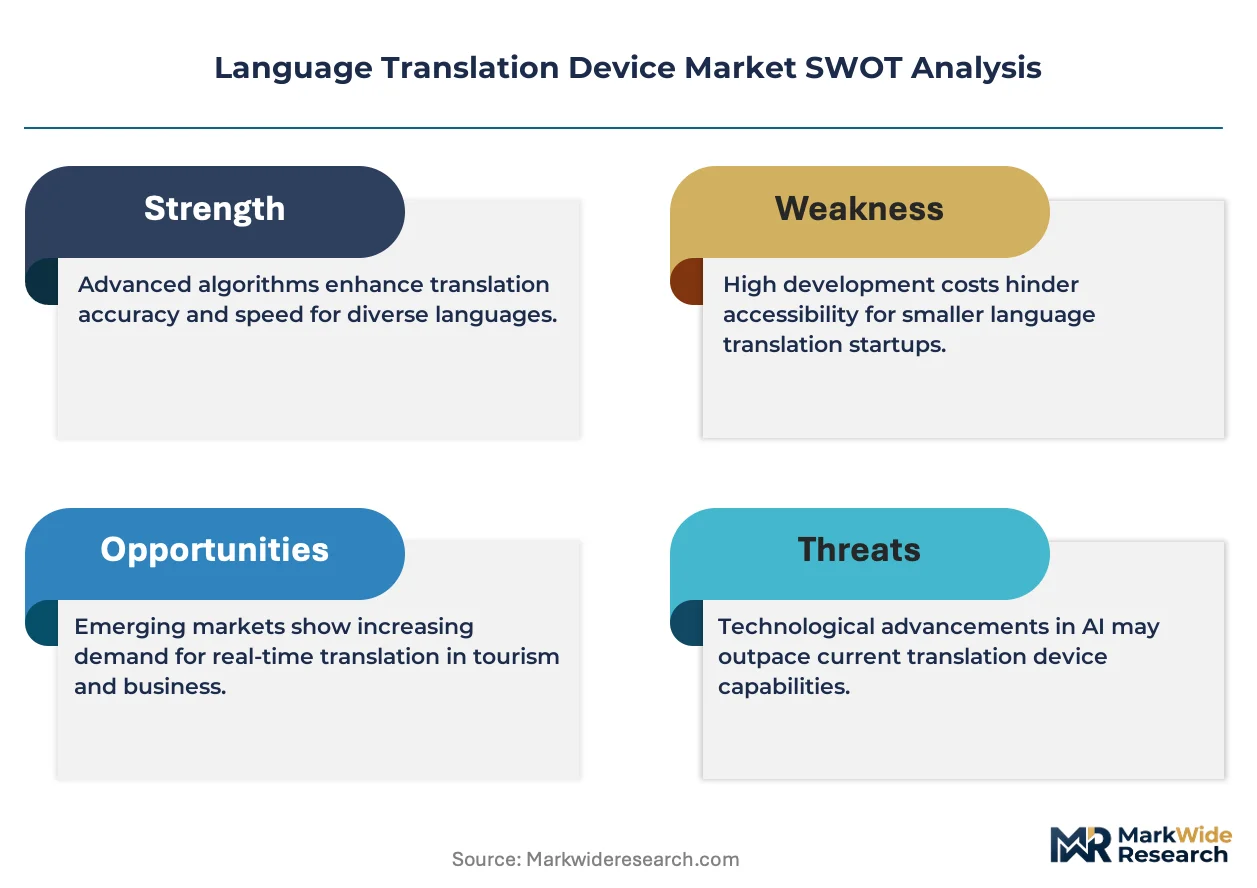
Growth Catalysts
- Inbound Tourism Pressure:Japan's aging demographics and visitor surge create dual demand for voice-based hardware at municipal touchpoints and hospitality front desks.
- EU AI Act Transparency Mandates:Public-sector translation deployments now require accuracy auditing and human oversight, accelerating certified device procurement cycles.
- Edge AI Chip Proliferation:Embedded processors with dedicated neural accelerators enable offline inference in remote locations where cloud connectivity fails.
Market Restraints
- Smartphone App Substitution:Free downloadable alternatives with comparable cloud-based performance erode willingness-to-pay for standalone hardware.
- Component Supply Concentration:Shenzhen-based manufacturing clusters control MEMS microphone and neural accelerator sourcing, creating geographic vulnerability.
- Low-Resource Language Technical Ceiling:Neural models struggle with dialectal variation and tonal languages outside high-resource training corpora.
Strategic Opportunities
- Emergency Response Integration:First responder agencies seek ruggedized handheld units with push-to-translate functionality for disaster zones.
- METI Subsidy Programs:Japan's JIS-standard interoperability incentives target regional municipalities for tourism-facing device deployment.
- Wearable Form Factor Convergence:Earbud-integrated real-time bidirectional interpretation captures consumer segments rejecting handheld bulk.
Industry Challenges
- Certification Timeline Compression:FCC electromagnetic compatibility and hearing-aid compatibility testing delays product launches against accelerating AI model release cycles.
- Legacy System Integration Friction:Enterprise call center deployments require API harmonization with existing CRM and ticketing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Language Translation Device Market |
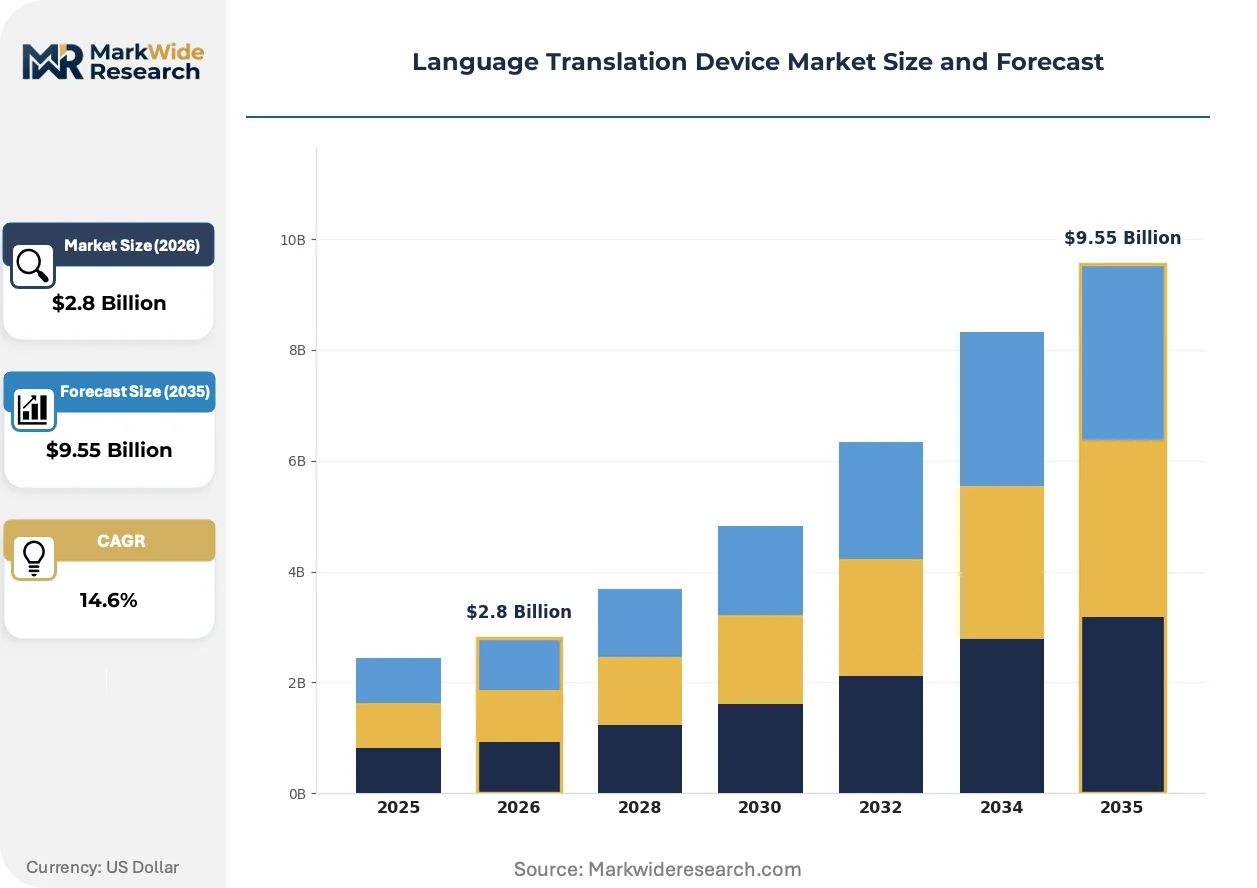
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Smartphone Apps, Wearable Devices, Desktop Software Technology: Machine Translation, AI-Powered Solutions, Speech Recognition, Text-to-Speech End User: Travelers, Businesses, Educational Institutions, Government Agencies Deployment: Cloud-Based, On-Premises, Hybrid, Offline |
| Companies Covered | iFLYTEK, Sourcenext, Timekettle, Langogo, Jarvisen, Pocketalk, Cheetah Mobile, Vavus, Vasco Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Language Translation Device Market Emerging Trajectories
Large language model integration is collapsing the traditional segmentation between cloud-dependent and edge-capable translation systems while redefining buyer expectations for conversational fluidity.
Neural audio codecs are virtualizing the boundary between hardware and software translation layers. Hospitality chains in Southeast Asia now deploy hybrid architectures where embedded processors handle routine phrases while cloud APIs manage complex negotiations. This architecture is virtualizing margin allocation between device manufacturers and API providers.
The EU AI Act imposes high-risk classification on public-sector translation systems, mandating accuracy auditing and human-in-the-loop oversight before deployment. Municipal procurement offices now embed compliance checkpoints into tender specifications. Healthcare and judicial interpreting services face the steepest compliance ramps.
Buyer preference is rotating from ownership toward subscription-enabled feature access. Enterprise accounts increasingly demand usage-based licensing with guaranteed latency SLAs rather than perpetual hardware purchases. This shift concentrates in Japanese corporate travel departments and European public service agencies.
Language Translation Device Market Segmentation
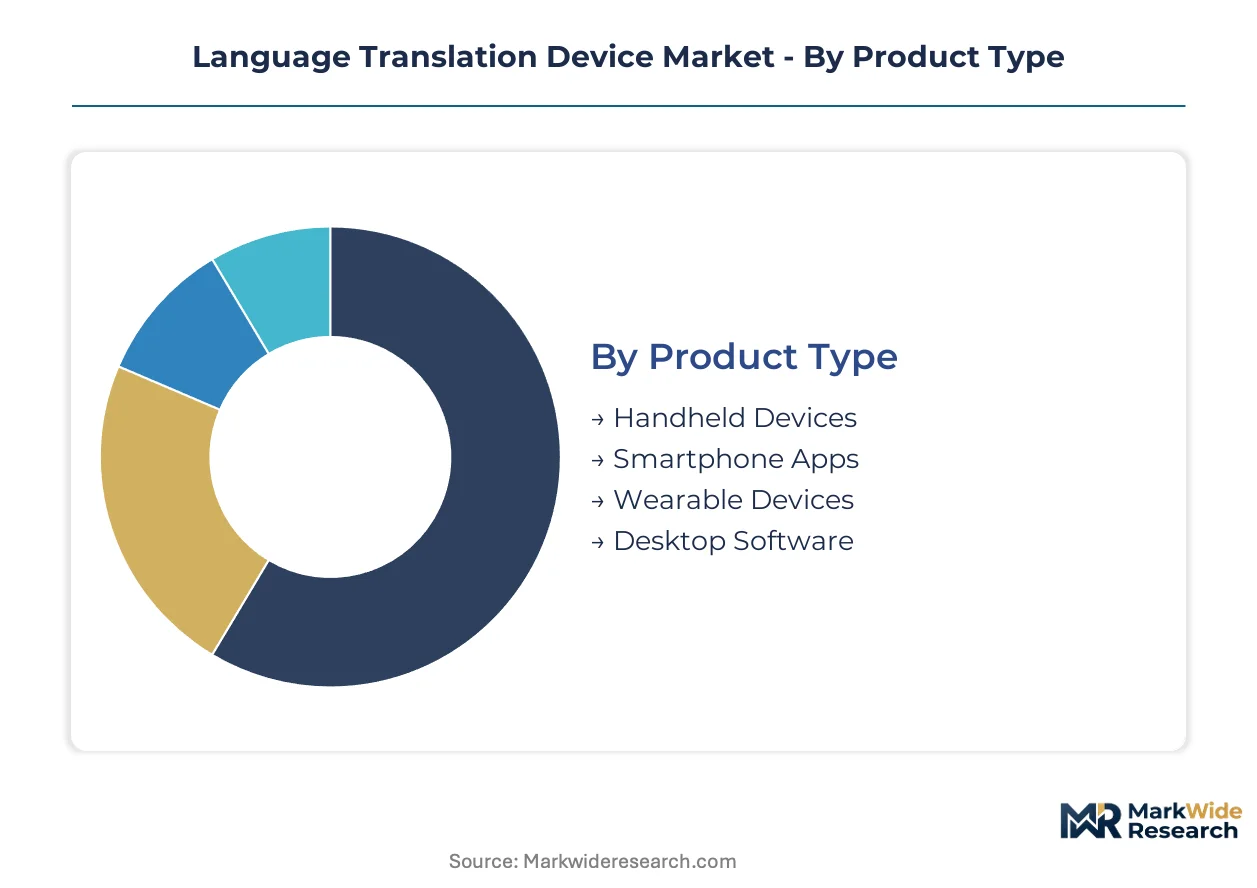
Segmentation in language translation devices reveals how hardware specialization, processing architecture, and buyer economics fragment procurement patterns across tourism, enterprise, and public service channels. Understanding these divisions exposes where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Use-case spectrum spans pocketable consumer hardware through embedded software layers, with physical form factor determining pricing power and replacement cycle length.
- Handheld Devices:Dedicated hardware units with embedded processors and offline neural inference capability command premium positioning in remote tourism and emergency response settings. Japanese municipal governments and Southeast Asian hospitality chains deploy these at front desks where cloud connectivity proves unreliable.
- Smartphone Apps:Downloadable software leveraging device-native microphones and cloud APIs dominates unit volume through free-to-freemium monetization, though ARPU compression limits developer investment in low-resource language pairs.
- Wearable Devices:Earbud-integrated bidirectional interpretation from Shenzhen-based manufacturers captures consumer segments rejecting handheld bulk.
- Desktop Software:Workstation-deployed solutions with batch document processing serve legal and healthcare transcription workflows.
Established volume favors smartphone apps; emerging adoption favors wearable devices.
Technology:
Processing methodology determines latency thresholds, offline functionality, and regulatory classification under emerging AI governance frameworks.
- Machine Translation:Rules-based and statistical legacy systems persist in enterprise legacy stacks where retraining costs exceed replacement economics.
- AI-Powered Solutions:Large language model architectures with sub-500 millisecond conversational latency attract the fastest investment flows as neural compression reduces error rates in tonal and low-resource languages.
- Speech Recognition:Acoustic modeling and natural language understanding pipelines from iFLYTEK and similar specialists enable Mandarin-centric and other high-resource language dominance.
- Text-to-Speech:Neural vocoder synthesis delivers naturalistic output for accessibility and tourism applications where auditory clarity outweighs processing overhead.
Legacy infrastructure retains machine translation; capability expansion favors AI-powered solutions.
End User:
Buyer sophistication and procurement authority shape feature requirements from consumer spontaneity through institutional compliance mandates.
- Travelers:Individual consumers prioritize portability, battery endurance, and airport retail availability over translation depth.
- Businesses:Corporate travel departments and multinational call centers demand API interoperability with CRM platforms and guaranteed latency SLAs under usage-based licensing.
- Educational Institutions:Universities and language academies seek multi-user licensing with curriculum integration and progress tracking.
- Government Agencies:Public-sector procurement faces EU AI Act high-risk classification, mandating accuracy auditing and human-in-the-loop oversight before deployment.
Consumer spontaneity drives traveler volume; compliance complexity elevates government agency contract values.
Deployment:
Architecture choice between cloud dependency and edge autonomy reflects connectivity infrastructure quality and data sovereignty requirements.
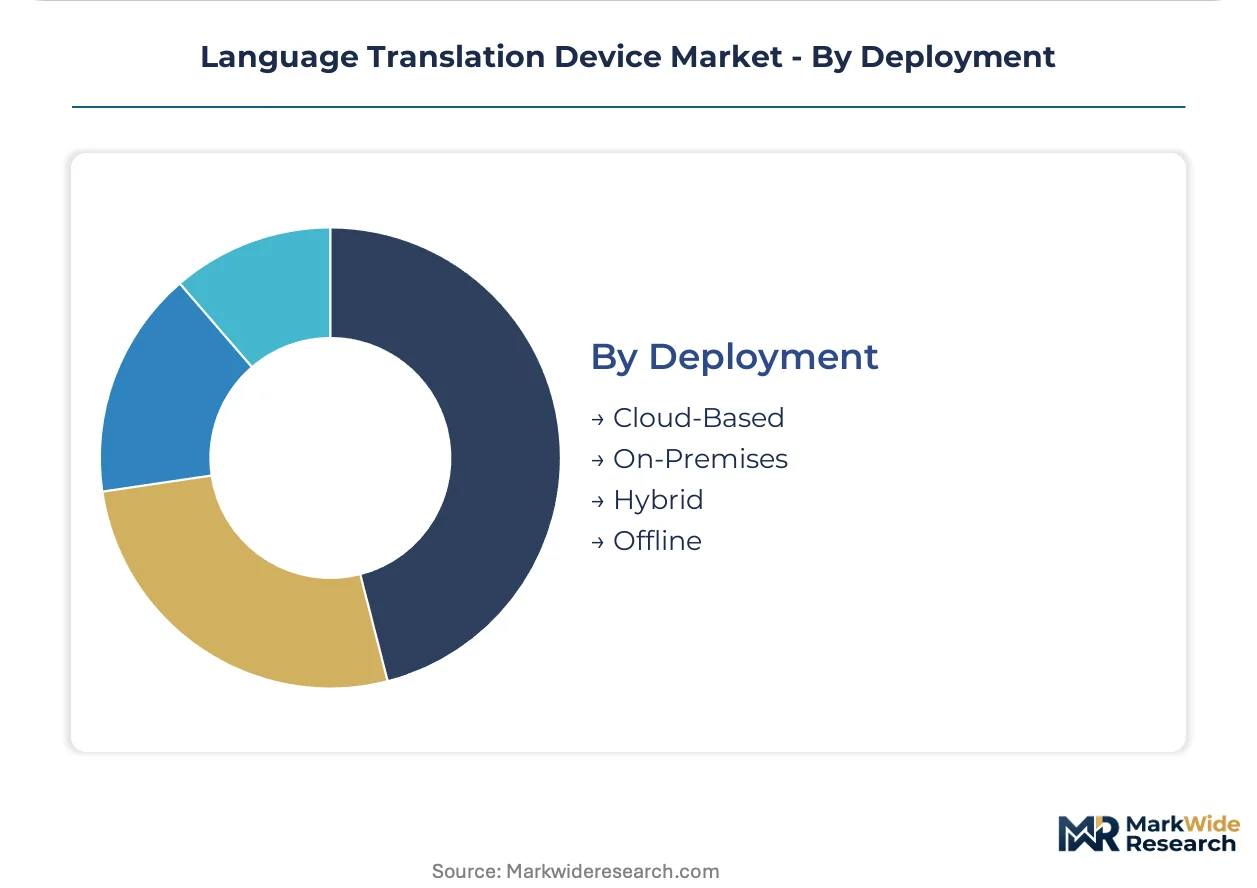
- Cloud-Based:API-dependent processing enables continuous model updates and lowest hardware BOM costs, though latency variability and subscription lock-in generate buyer friction.
- On-Premises:Private server deployments satisfy healthcare and judicial interpreting services with strict data residency requirements.
- Hybrid:Embedded processors handle routine phrase matching while cloud APIs manage complex negotiations, an architecture hospitality chains across Southeast Asia now deploy to virtualize margin allocation.
- Offline:Edge AI chip proliferation with dedicated neural accelerators enables inference in disaster zones and remote tourism locations where connectivity fails entirely.
Operational convenience favors cloud-based; resilience planning favors offline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen-based manufacturing clusters dominate component sourcing for neural accelerators and MEMS microphones, while finished-device assembly spreads across multiple geographies to satisfy local certification requirements.
United States
FCC electromagnetic compatibility mandates and hearing-aid compatibility testing create procedural delays for wireless translation hardware entering commercial channels. Enterprise call centers in Austin and Seattle drive API-integrated procurement with guaranteed latency SLAs. Silicon Valley cloud providers supply upstream large language model infrastructure to downstream device manufacturers.
China
MIIT certification requirements and GB standards govern neural accelerator deployment in consumer electronics. Shenzhen manufacturing clusters compress the gap between component sourcing and finished-device assembly through integrated supply chains. iFLYTEK anchors Mandarin-centric speech recognition development from its Hefei headquarters.
Japan
METI subsidy programs promote JIS-standard interoperability for tourism-facing devices across regional municipalities. Aging demographics and inbound tourism create dual pressure for voice-based translation hardware at municipal touchpoints and hospitality front desks. Tokyo and Osaka electronics retail channels maintain dense distribution for handheld units.
Germany
EU AI Act high-risk classification mandates accuracy auditing and human-in-the-loop oversight for public-sector translation deployments. Industrial automation clusters in Bavaria and Baden-Württemberg test ruggedized handheld units for manufacturing floor communication. Stuttgart-based automotive suppliers evaluate wearable form factors for multinational workforce integration.
United Kingdom
GDPR data residency requirements push enterprise buyers toward hybrid deployment architectures with on-premises processing options. London financial services firms pilot real-time interpretation for client-facing compliance interactions. Edinburgh and Cambridge speech technology clusters contribute acoustic modeling expertise to upstream AI providers.
Language Translation Device Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying neural accelerators and MEMS microphones to finished-device manufacturers. The vendor base separates between speech recognition heritage players, wearable form factor innovators, and retail channel density operators. Three archetypes dominate: cloud-dependent platform builders, edge-capable hardware specialists, and hybrid architecture deployers. Competitive moves concentrate on strategic partnerships with upstream AI model providers and geographic expansion through airport kiosk and electronics retail placement.
Within the speech recognition heritage tier, iFLYTEK occupies a position exemplifying Mandarin-centric neural machine translation dominance. Among wearable form factor specialists, Timekettle sits within the real-time bidirectional interpretation segment through earbud-integrated solutions. On the retail channel density vector, Pocketalk anchors Japanese electronics store and airport kiosk presence. These three represent distinct competitive vectors: upstream AI leverage, hardware-software convergence, and distribution depth.
| Leading Market Players |
|---|
| iFLYTEK |
| Sourcenext |
| Timekettle |
| Langogo |
| Jarvisen |
| Pocketalk |
| Cheetah Mobile |
| Vavus |
| Vasco Electronics |
| Others |
Supply Flow & Price Mechanics
Shenzhen manufacturing clusters anchor neural accelerator and MEMS microphone supply, translating component scarcity into tiered hardware margins where edge-capable devices command premium positioning against cloud-dependent alternatives. Japanese municipal procurement and Southeast Asian hospitality chains absorb these premiums for offline resilience, while smartphone app substitution erodes mid-tier pricing power.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for public-sector translation deployments, mandating accuracy auditing and human-in-the-loop oversight that concentrates contract value in certified device categories. Three-tier pricing structure across premium certified, standard enterprise, and economy consumer levels separates procurement by compliance burden, with hospitality chains in Southeast Asia and first responder agencies showing lowest price sensitivity. Cost compression in the mid-tier intensifies because free smartphone alternatives match cloud-based latency thresholds, forcing handheld manufacturers to differentiate through offline neural inference capability.
Supply Chain Analysis
Export-control restrictions on advanced neural accelerators limit technology flows from United States and allied fabrication facilities to Shenzhen assembly lines, compressing availability of edge-AI components for offline-capable devices. China, South Korea, and Taiwan concentrate MEMS microphone and neural accelerator production, with raw material dependencies spanning rare-earth magnet substrates, silicon carbide wafers, and precision optical sensors. Single-source vulnerability runs through TSMC-adjacent packaging facilities for advanced inference chips. Distribution runs through Japanese electronics retail chains, airport kiosk networks, and enterprise direct-procurement channels serving METI-subsidized municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-AI engineering talent and certified regulatory affairs capability sit in acute shortage relative to cloud-platform scale, constraining how quickly hardware specialists can capture public-sector procurement windows before large language model APIs commoditize conversational latency.
For Market Incumbents: Insulate offline-capable product lines through captive neural accelerator supply agreements with Shenzhen packaging houses, while accelerating JIS-standard and EU AI Act certification pipelines ahead of model-update cycles that obsolete cloud-dependent architectures. METI subsidy program capture and FCC hearing-aid compatibility positioning defend against smartphone app substitution in institutional channels. For New Entrants and Emerging Players: European regional municipalities underpenetrated by certified device vendors offer whitespace where EU AI Act compliance timelines have outpaced incumbent certification capacity. Target first responder agencies in German industrial automation clusters and Scottish emergency services with ruggedized handheld units, using push-to-translate functionality as the wedge feature against established hospitality-focused competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid-architecture deployers with demonstrated regulatory certification velocity over pure cloud-platform integrators. Five-to-ten year viability hinges on edge-AI chip procurement relationships and municipal procurement relationship density rather than consumer retail channel scale. Watch for METI subsidy expansion or EU AI Act enforcement intensity as the signal indicating whether certified-hardware margins compress or expand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Acceleration | EU AI Act and FCC compliance timelines determine public-sector contract eligibility before model obsolescence. |
| Neural Accelerator Supply Agreement | Shenzhen packaging partnerships secure edge-AI chip allocation against export-control tightening. |
| Hybrid Architecture Deployment | Southeast Asian hospitality chains virtualize margin between embedded processors and cloud APIs. |
| METI Subsidy Program Capture | Japanese municipal procurement concentrates demand through JIS-standard interoperability mandates. |
| Wearable Form Factor Convergence | Earbud-integrated bidirectional interpretation captures consumer segments rejecting handheld bulk. |
Methodological Framework
A standing panel of device engineering leads, municipal procurement officers, hospitality technology directors, and neural accelerator supply chain managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FCC equipment authorization databases, METI subsidy disbursement records, EU AI Act implementation guidance, and Shenzhen customs export filings. Bottom-up shipment estimates by form factor and top-down market sizing by end-use channel were triangulated against cloud API usage disclosures from major platform providers.
Scenario bracketing around edge-AI chip availability, EU AI Act enforcement intensity, and METI subsidy renewal framed projection uncertainty across the analysis window. Segmentation dimensions modeled include product type, processing architecture, deployment mode, and buyer procurement authority. CAGRs were derived from elasticity-adjusted adoption curves fitted to municipal procurement cycle data and hospitality chain replacement patterns. Neural compression rate trajectories and low-resource language model error reduction curves served as technology-specific forecast inputs.
Practitioners should monitor export-control expansion, EU AI Act delegated act releases, and METI subsidy budget allocations for early signals of forecast revision. Forecasts reflect assumptions about neural accelerator supply continuity and certification timeline stability. Material shifts in semiconductor trade policy or large language model capability release cadence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Adtech Market
Others
South Korea Automotive LED Lighting Market
Others
CAR T Cell Therapy Market
Others
Japan Smart Home Market
Others
Bimodal Identity Management Solutions Market
Others
Global Alpha Cypermethrin Market
Others
Indoor LBS Market
Others
Connected Homes Market
Others
Magnesite Market
Others
Global Car Wax Market
Others
Europe Postal Services Market
Others
Fibert Market
Others
Caster Wheels Market
Others
Global Tobacco Market
Others
Digital Audio Decoders Market
Others
Global Injectable Nanomedicine Market