
 Aerial Imaging in Insurance Service Market | 2026-2036
Aerial Imaging in Insurance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Aerial Imaging in Insurance Service Market Outlook
Buyer concentration across the insurance sector is broadening as regional carriers and managing general agents adopt aerial imaging alongside national underwriters. Verisk Analytics leverages its catastrophe modeling heritage to integrate geospatial data into underwriting workflows. EagleView Technologies sustains dominance in property measurement analytics through proprietary oblique image libraries. PrecisionHawk competes with specialized agricultural and infrastructure inspection platforms that extend into insurance adjacency.
Aerial imaging in insurance service encompasses the acquisition, processing, and analytical interpretation of overhead visual data captured via unmanned aerial vehicles, satellites, or manned aircraft to assess property condition, quantify damage, and validate claims. Resolution thresholds below five centimeters per pixel enable roof material classification and structural deformation detection from safe standoff distances. Drone imaging leads the technology segment due to on-demand deployment flexibility and sub-hour response times after weather events. Satellite imagery occupies the high-volume, lower-frequency tier for portfolio-level risk monitoring across dispersed geographies. Lidar penetration remains concentrated in commercial property and industrial facility applications where three-dimensional point clouds support precise volumetric and structural analysis.
The FAA governs commercial drone operations through Part 107 certification, while EASA's specific category framework shapes European deployment standards for beyond-visual-line-of-sight missions. ISO 21384-3 provides unmanned aircraft system operational safety benchmarks that insurers reference when contracting third-party flight providers. Stakeholders must evaluate whether to build captive drone fleets or deepen vendor partnerships as regulatory clarity on autonomous flight and airspace integration advances.
Market Dynamics
Drone-based roof inspection platforms are compressing claims cycle times from weeks to days, forcing carriers to restructure field operations and adjuster deployment models around rapid aerial data capture.
Growth Catalysts
- FAA Part 107 Certification:Standardized commercial drone pilot licensing in the United States accelerates carrier deployment of in-house flight teams for catastrophe response.
- Hurricane Exposure:Gulf Coast and Atlantic seaboard states drive carrier investment in pre-positioned drone fleets for post-storm damage assessment.
- Sub-5cm Resolution Thresholds:Advances in camera sensor density enable automated roof material classification without physical adjuster presence.
Market Restraints
- Aviation Insurance Cost Structure:Hull and liability coverage for commercial drone operations adds 15-25% to per-flight economics, squeezing third-party vendor margins.
- Battery Chemistry Volatility:Lithium-polymer cell degradation in temperature extremes limits flight endurance and drives replacement cycles.
- EASA Beyond-Visual-Line-of-Sight Friction:European specific-category authorization timelines stretch 6-18 months, delaying automated corridor inspection deployment.
Strategic Opportunities
- Wildfire-Prone Western States:California, Oregon, and Colorado carriers lack scaled aerial response networks, creating vendor expansion white space.
- Lidar-Photogrammetry Convergence:Hybrid sensors combining dense point clouds with RGB texture open commercial property and industrial facility adjacency.
- ISO 21384-3 Adoption:Insurers increasingly mandate third-party flight provider certification, creating audit and compliance service demand.
Industry Challenges
- Part 107 Remote Pilot Pipeline:Carrier captive fleet expansion outpaces FAA-certified operator supply, inflating recruitment costs.
- Legacy Claims System Integration:Aerial imagery platforms require API development to feed structured damage data into 1990s-era mainframe systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerial Imaging in Insurance Service Market |
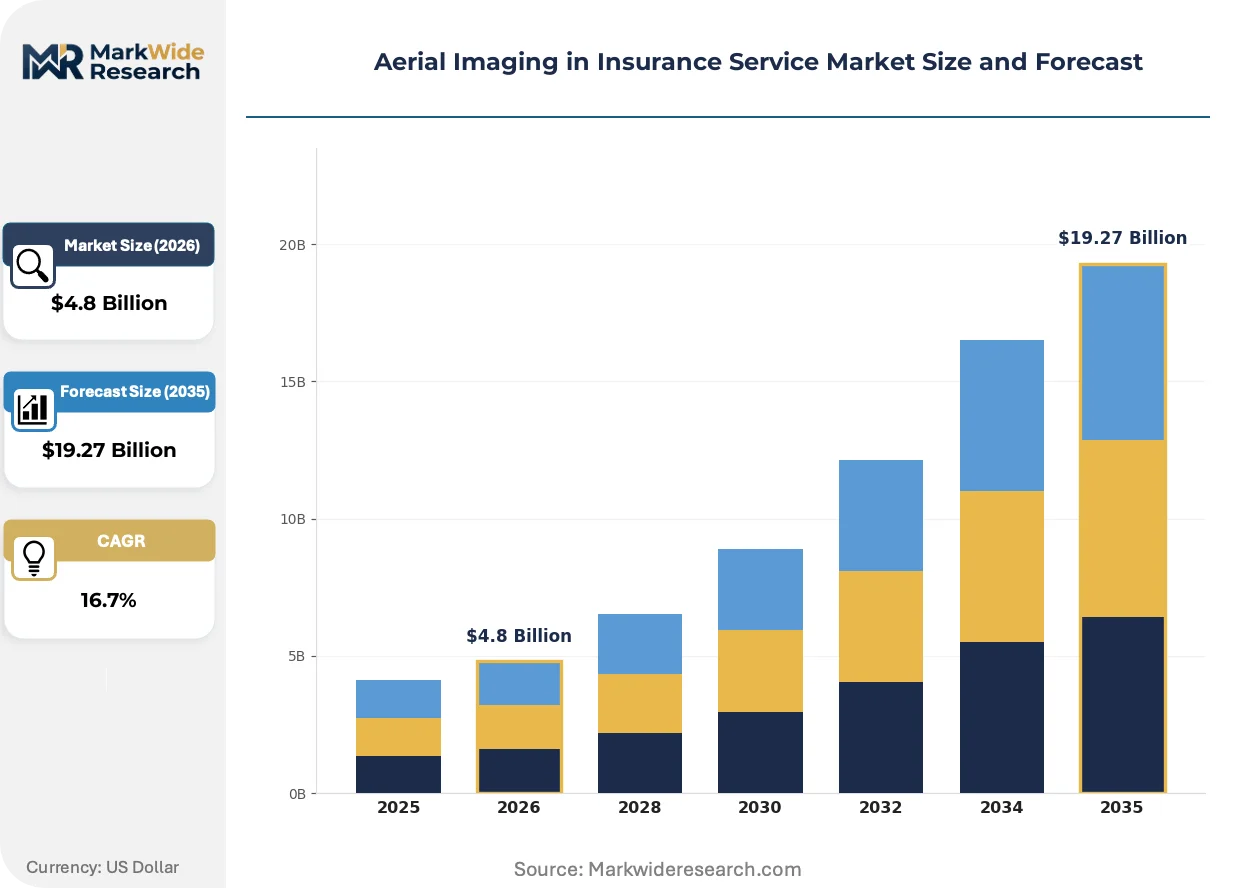
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Risk Assessment, Property Inspection, Loss Adjusting, Claims Verification Technology: Drone Imaging, Satellite Imagery, Lidar, Photogrammetry End User: Insurance Companies, Brokers, Adjusters, Loss Assessors Offering: Data Analysis, Analytical Reporting, Image Processing, Custom Solutions |
| Companies Covered | EagleView Technologies, Verisk Analytics, PrecisionHawk, Terrene Labs, TensorFlight, Betterview, DroneDeploy, Nearmap, Fugro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerial Imaging in Insurance Service Market Strategic Shifts
Artificial intelligence inference at the network edge is transforming how aerial data converts into actionable underwriting and claims inputs without centralized processing delays.
Edge-based damage detection is consolidating fragmented post-flight workflows. Convolutional neural networks running on drone-mounted GPUs classify roof conditions in real time. Major carriers now deploy fleets that transmit only flagged anomalies rather than full image sets, compressing bandwidth costs and accelerating adjuster triage decisions.
EASA's specific category framework for beyond-visual-line-of-sight operations is reshaping European deployment economics. Operators securing light unmanned aircraft system operator certificates gain automated corridor access for linear infrastructure inspection. German and French carriers are piloting pre-approved flight paths over policyholder concentrations to enable same-day response without case-by-case authorization.
Carrier procurement of aerial services is fragmenting across specialized vendors. National underwriters maintain master service agreements with full-stack providers while regional carriers contract point solutions for roof measurement or catastrophe response. Texas and Florida markets exhibit the most pronounced bifurcation, with hurricane-exposed carriers splitting contracts between rapid-response drone fleets and satellite portfolio monitoring.
Aerial Imaging in Insurance Service Market Segmentation
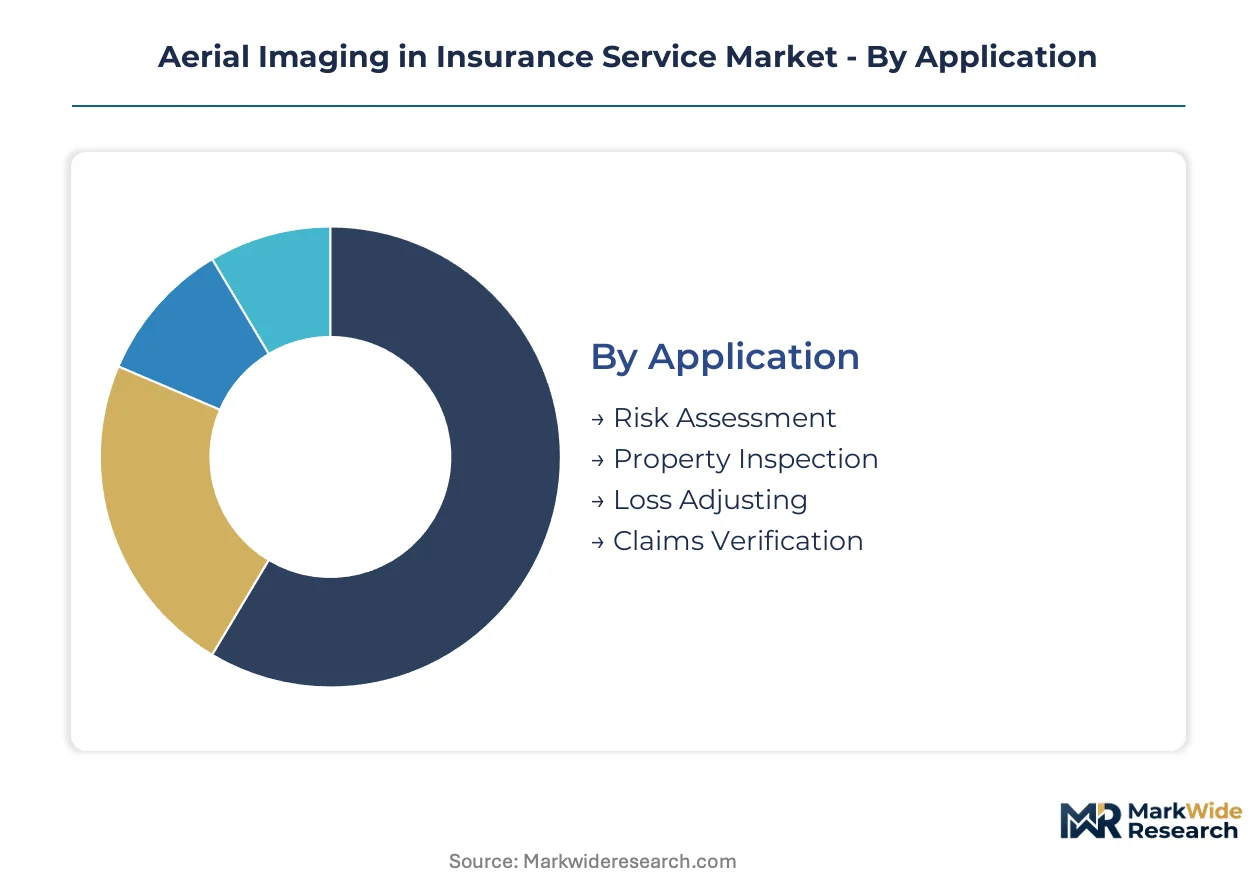
Segmentation reveals how aerial imaging value pools concentrate across distinct technical capabilities and buyer workflows. Technology choice dictates resolution, speed, and regulatory burden. Application focus determines whether vendors capture recurring underwriting revenue or episodic catastrophe fees.
Technology:
Resolution thresholds and deployment flexibility separate the technology tiers, with flight autonomy and sensor density driving carrier procurement decisions.
- Drone Imaging:Unmanned aerial vehicles equipped with RGB and multispectral sensors deliver sub-5cm resolution for roof material classification. Gulf Coast carriers deploy pre-positioned fleets for post-hurricane response, compressing claims cycles from weeks to days. FAA Part 107 certification requirements shape pilot recruitment economics.
- Satellite Imagery:Constellation-based capture enables portfolio-scale risk monitoring across dispersed geographies without flight authorization delays. Revisit frequency limitations constrain damage verification timing, pushing demand toward synthetic aperture radar for all-weather capability.
- Lidar:Laser scanning generates dense three-dimensional point clouds for structural deformation detection and volumetric analysis. Commercial property underwriters leverage millimeter-precision measurements for industrial facility assessments.
- Photogrammetry:Software-derived elevation models from overlapping two-dimensional images reduce hardware costs for regional carriers. Processing latency limits real-time catastrophe response applications.
Mature deployment sits with Drone Imaging. Newer deployment is concentrated in Lidar-photogrammetry convergence platforms.
Application:
Workflow integration depth varies sharply across the application spectrum, with front-end underwriting applications commanding longer contract terms than back-end claims verification.
- Risk Assessment:Pre-bind property condition scoring enables tiered pricing differentiation and coverage exclusion triggers. Wildfire-exposed California carriers deploy annual aerial surveys to update wildland-urban interface exposure models.
- Property Inspection:Roof condition documentation replaces manual adjuster climbs, reducing ladder-assist contractor costs and injury liability exposure. Texas hail markets exhibit the steepest adoption trajectory.
- Loss Adjusting:Damage quantification workflows integrate structured aerial data into claims reserving systems. Legacy mainframe integration requirements delay deployment for mid-tier carriers.
- Claims Verification:Post-repair validation confirms contractor work quality and prevents supplemental claim inflation. Fraud detection algorithms cross-reference aerial timestamps against contractor invoices.
Volume concentrates in Property Inspection. Value capture is expanding fastest in Risk Assessment.
End User:
Procurement authority and technical sophistication fragment the buyer landscape, with national underwriters demanding API integrations that regional players cannot support.
- Insurance Companies:Captive drone fleet investments and master service agreements with full-stack providers dominate national carrier strategies. Capital allocation favors catastrophe response pre-positioning over routine underwriting support.
- Brokers:Independent placement specialists contract point solutions for client risk differentiation and coverage negotiation leverage. Commission compression limits aerial service budget allocation.
- Adjusters:Staff and independent claims professionals license per-inspection platforms for damage documentation. Mobile application usability drives vendor selection.
- Loss Assessors:Third-party valuation specialists require court-admissible image metadata and chain-of-custody documentation. Certification requirements exceed standard commercial photography standards.
Contract value aggregates with Insurance Companies. User growth is climbing the fastest among Adjusters.
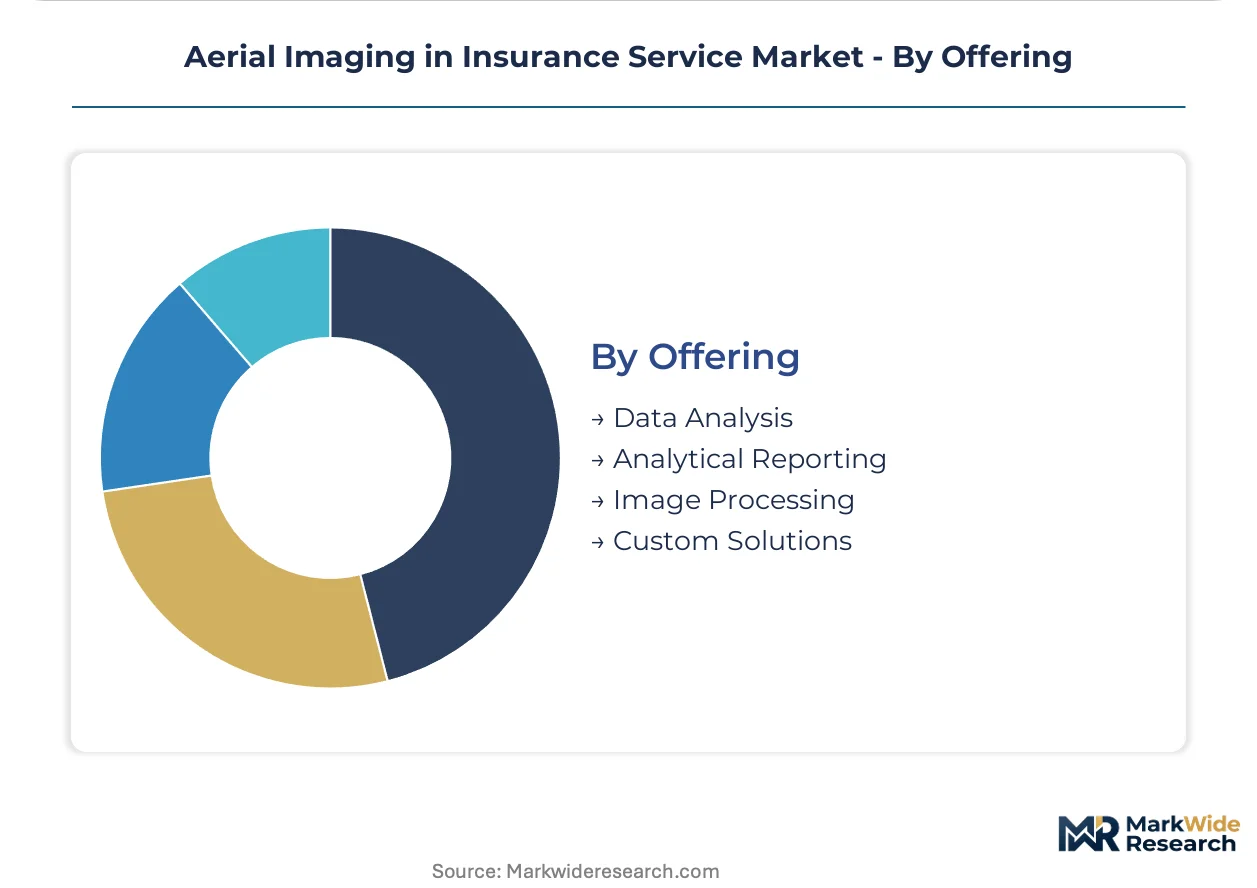
Offering:
Service packaging determines margin structure, with pure data provision commoditizing while integrated analytics command premium positioning.
- Data Analysis:Machine learning models extract condition scores and damage severity indices from raw imagery. Carrier data science teams increasingly insource algorithm development.
- Analytical Reporting:Structured deliverables integrate aerial findings into underwriting files and claims documentation. E&O liability coverage requirements elevate vendor qualification barriers.
- Image Processing:Orthomosaic generation and point cloud classification services support carriers lacking in-house photogrammetry capability. Turnaround time guarantees differentiate tier-one vendors.
- Custom Solutions:Bespoke platform development for proprietary risk scoring models and white-label adjuster applications. Long implementation cycles concentrate among top-ten national carriers.
Revenue stability favors Analytical Reporting. Platform investment is concentrating in Custom Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier investment in aerial imaging clusters along catastrophe-exposed coastlines and wildland-urban interfaces. The United States dominates deployment scale, while European markets advance regulatory frameworks for automated flight. Asia-Pacific adoption concentrates in climate-vulnerable emerging markets.
United States
Hurricane and hail exposure along the Gulf Coast and Great Plains drives carrier fleet pre-positioning. FAA Part 107 certification standardizes commercial pilot licensing for property inspection workflows. Florida and Texas carriers deploy drone networks for post-storm roof assessment, compressing claims cycles from weeks to days.
Germany
Industrial property underwriting demand for millimeter-precision structural assessment shapes lidar adoption curves. EASA's specific category framework for beyond-visual-line-of-sight operations enables automated corridor inspection authorization. Munich and Frankfurt carriers pilot pre-approved flight paths over policyholder concentrations for same-day catastrophe response.
United Kingdom
Flood-exposed property portfolios in Thames Basin and coastal counties accelerate aerial survey integration into annual risk repricing. Civil Aviation Authority operational authorizations govern commercial drone deployment for insurance workflows. London market underwriters contract specialized vendors for high-value commercial property condition verification.
Australia
Bushfire risk modeling across Victoria and New South Wales drives investment in rapid aerial response capabilities. Civil Aviation Safety Regulations Part 101 governs unmanned aircraft operations for commercial insurance applications. Sydney and Melbourne carriers deploy satellite-drone hybrid monitoring for portfolio-scale exposure tracking.
Japan
Typhoon and earthquake exposure in Pacific coastal prefectures creates demand for rapid damage verification without ground crew deployment. Ministry of Land, Infrastructure, Transport and Tourism unmanned aircraft system guidelines shape carrier vendor qualification requirements. Tokyo and Osaka insurers integrate aerial data into parametric catastrophe bond trigger mechanisms.
Aerial Imaging in Insurance Service Market Competitive Environment
Established analytics providers occupy the standard tier; emerging entrants pursue specialized catastrophe response and edge-computing adjacencies. The vendor base stratifies across full-stack platform operators, point-solution measurement specialists, and flight-technology licensors. Two strategic archetypes dominate: proprietary image library owners and API-first workflow integrators. Competitive moves concentrate on vendor consolidation for geographic coverage and partnership structures for legacy system integration.
Among analytics-focused platform operators, Verisk Analytics and EagleView Technologies exemplify divergent scale strategies. Verisk leverages catastrophe modeling heritage to embed geospatial intelligence into underwriting systems. EagleView sustains market presence through proprietary oblique image capture infrastructure. PrecisionHawk occupies a specialized position spanning agricultural inspection heritage and insurance workflow extension.
| Leading Market Players |
|---|
| EagleView Technologies |
| Verisk Analytics |
| PrecisionHawk |
| Terrene Labs |
| TensorFlight |
| Betterview |
| DroneDeploy |
| Nearmap |
| Fugro |
| Others |
Value Chain & Pricing Dynamics
FAA Part 107 certified pilots concentrated in Texas and Florida command wage premiums that compress third-party vendor margins and widen spreads between economy-tier per-flight rates and premium managed-service contracts. Labor-cost differentials between catastrophe-response specialists and routine inspection operators feed directly into carrier procurement tiering, with national underwriters absorbing premium pricing for pre-positioned fleet guarantees while regional carriers select spot-market alternatives.
Pricing Analysis
Volume concentrates in per-inspection transactional pricing while margin pools in multi-year SaaS-tiered subscriptions bundling flight operations with AI damage classification. Price differentiation rests on ISO 21384-3 certification status and FAA Part 107 waiver breadth for beyond-visual-line-of-sight operations. Cost compression in the economy tier is intensifying as battery replacement cycles and aviation insurance surcharges squeeze per-flight economics. Regional carriers exhibit the highest price sensitivity, whereas national underwriters prioritize response-time guarantees over unit cost.
Supply Chain Analysis
Freight costs for lithium-polymer battery cells and high-resolution CMOS sensors from South Korea and Japan elevate hardware procurement expenses for fleet operators. Component sourcing draws from Chinese gimbal manufacturers, German optics specialists, and Taiwanese semiconductor fabricators. Single-source vulnerability concentrates in solid-state lidar emitters, where qualified suppliers number fewer than five globally. Distribution runs through direct OEM relationships for enterprise carriers and regional distributor networks for independent adjuster licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
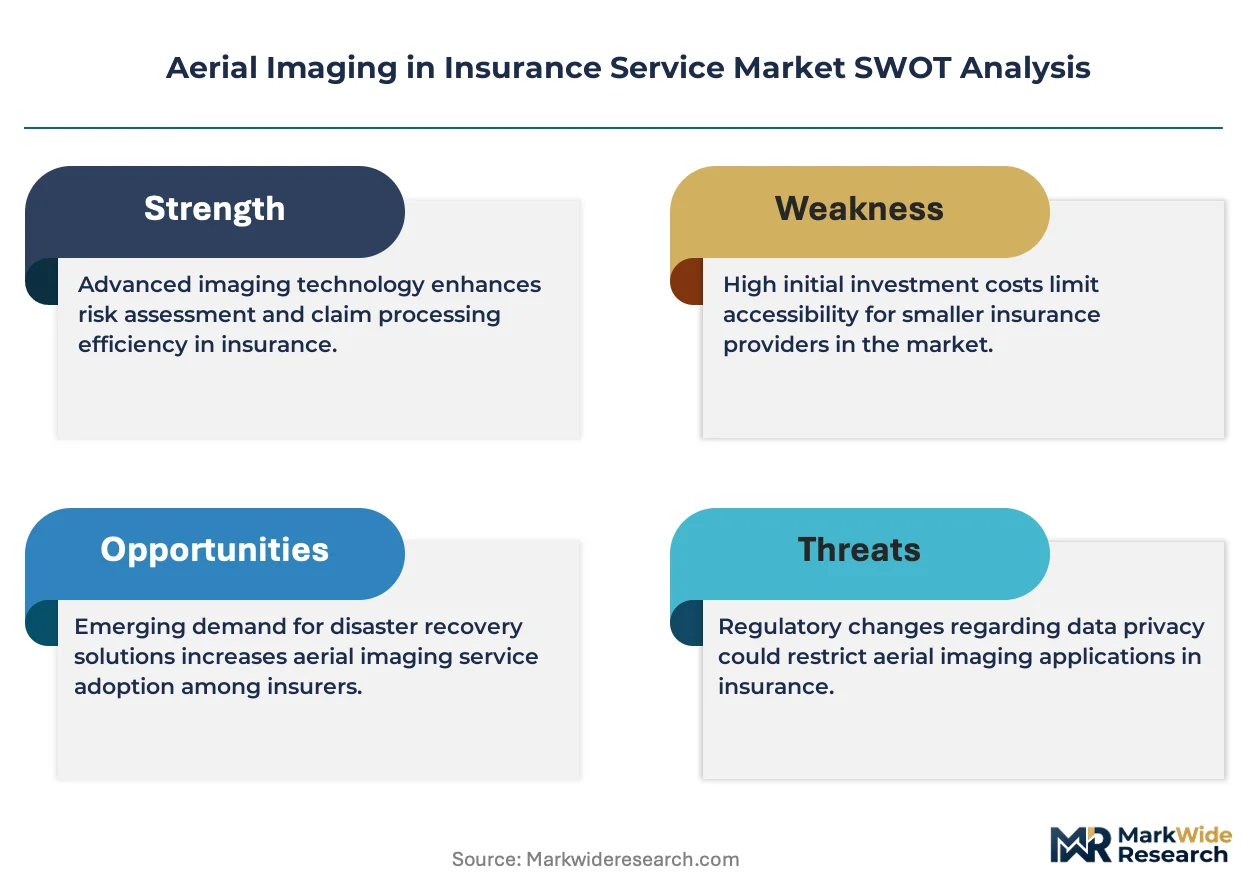
This market reads as a cost-of-compliance story where FAA Part 107 certification requirements and ISO 21384-3 operational safety mandates erect barrier-to-entry moats that favor incumbent platforms with established audit trails and waiver portfolios.
For Market Incumbents: Extend proprietary image library coverage into wildfire-prone Western states before specialized catastrophe-response entrants capture California and Oregon carrier contracts. Deepen API integration partnerships with legacy claims system vendors to lock in switching costs. Edge-computing specialists threaten real-time inference advantages; counter by acquiring GPU-enabled drone hardware platforms.
For New Entrants and Emerging Players: EASA's specific category framework in Germany opens a window for automated corridor inspection services targeting Munich and Frankfurt industrial property underwriters. White space concentrates in lidar-photogrammetry convergence for commercial facility assessment, where incumbent platforms lack hybrid sensor deployment. Pursue loss assessor certification pathways to capture court-admissible documentation premiums.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated flight-analytics platforms given carrier procurement consolidation toward full-stack providers. Long-term viability favors vendors with captive pilot training pipelines and proprietary geospatial data assets. Monitor FAA autonomous flight rulemaking as the signal for fleet economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Beyond-Visual-Line-of-Sight Waiver Acquisition | FAA Part 107 waivers enable automated corridor inspection, reducing per-mile labor costs for linear infrastructure assessment. |
| Edge-Computing Hardware Integration | Drone-mounted GPU deployment permits real-time damage classification, compressing bandwidth and accelerating adjuster triage. |
| Legacy Claims System API Development | Structured data feeds into 1990s-era mainframe systems reduce carrier integration friction and extend contract duration. |
| ISO 21384-3 Certification Investment | Operational safety benchmarks satisfy insurer vendor qualification requirements, creating audit and compliance service revenue. |
| Wildfire-Response Fleet Pre-Positioning | California and Oregon carrier contracts lack scaled aerial networks, offering first-mover advantage in high-growth exposure zones. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with FAA Part 107 flight operations directors, carrier claims technology executives, and third-party aerial service procurement managers combined with secondary validation from EASA authorization databases and ISO certification registries. Bottom-up triangulation across technology deployment metrics and top-down reconciliation against carrier capital expenditure disclosures ensured cross-verification.
Data-stream reconciliation integrated flight-hour utilization rates, pilot certification pipeline flows, and sensor procurement volumes across the projection horizon. Segmentation dimensions modeled include technology tier, application workflow depth, end-user procurement authority, and geographic regulatory cluster. CAGRs were derived from carrier fleet expansion plans and vendor contract value trajectories. Forecast inputs incorporated FAA autonomous flight rulemaking timelines and EASA specific-category adoption curves.
The model assumes a particular technology adoption path; alternative pathways for edge-based AI inference would alter the outlook if centralized processing cost reductions outpace on-device capability advances. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Dental Insurance Market
Insurance
Endowment Insurances Market
Insurance
Business Travel Insurance Market
Insurance
Global SME Insurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Art Insurance Market
Insurance
Germany Reinsurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Car Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Liability Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Djibouti Insurance Market