
 Global Flood Insurance Market | 2026-2036
Global Flood Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flood Insurance Market Analysis
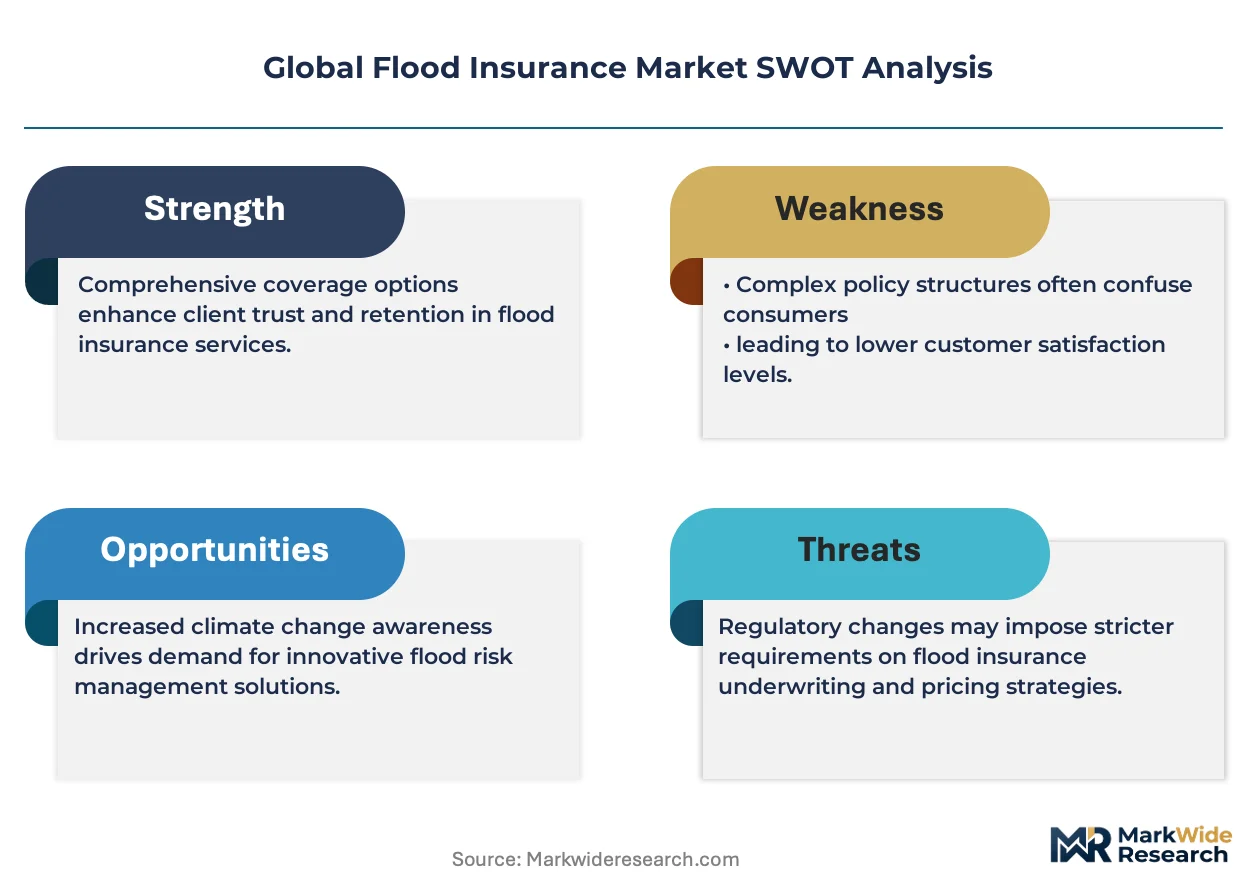
Actuarial modeling talent is collapsing across legacy carriers, forcing incumbents to rebuild pricing infrastructure from parametric foundations. Berkshire Hathaway leverages its reinsurance balance sheet to sustain capacity in catastrophe-exposed markets. Allianz SE anchors European flood coverage through granular river-basin underwriting. Swiss Reinsurance Company Ltd competes on proprietary hydrological datasets that differentiate its risk-selection protocols.
Flood insurance indemnifies policyholders against water-inundation damage to structures, contents, and business interruption, typically triggered when water exceeds normal boundaries across normally dry land or accumulates from surface runoff, storm surge, or fluvial overflow. The product transfers catastrophic hydrological risk from mortgage lenders, property owners, and municipal bondholders to capital markets through layered reinsurance structures. Residential policies dominate premium volume across developed economies, though commercial lines command wider margins due to bespoke business-interruption riders and higher per-risk limits. Variable premium structures are gaining traction as satellite-based elevation mapping and real-time precipitation feeds enable dynamic pricing that adjusts to seasonal flood-stage probability rather than static zone classifications.
The US Federal Emergency Management Agency administers the National Flood Insurance Program, while state regulators in Florida, Louisiana, and Texas oversee private-market rate filings that increasingly incorporate climate-adjusted catastrophe models. The EU Solvency II framework and the UK's Prudential Regulation Authority mandate stress-testing of flood exposure concentrations against 1-in-200-year return periods, compressing capital relief for undiversified portfolios. Stakeholders must monitor whether parametric triggers and blockchain-based smart contracts displace traditional indemnity structures in high-frequency flood zones before next-generation capital requirements crystallize.
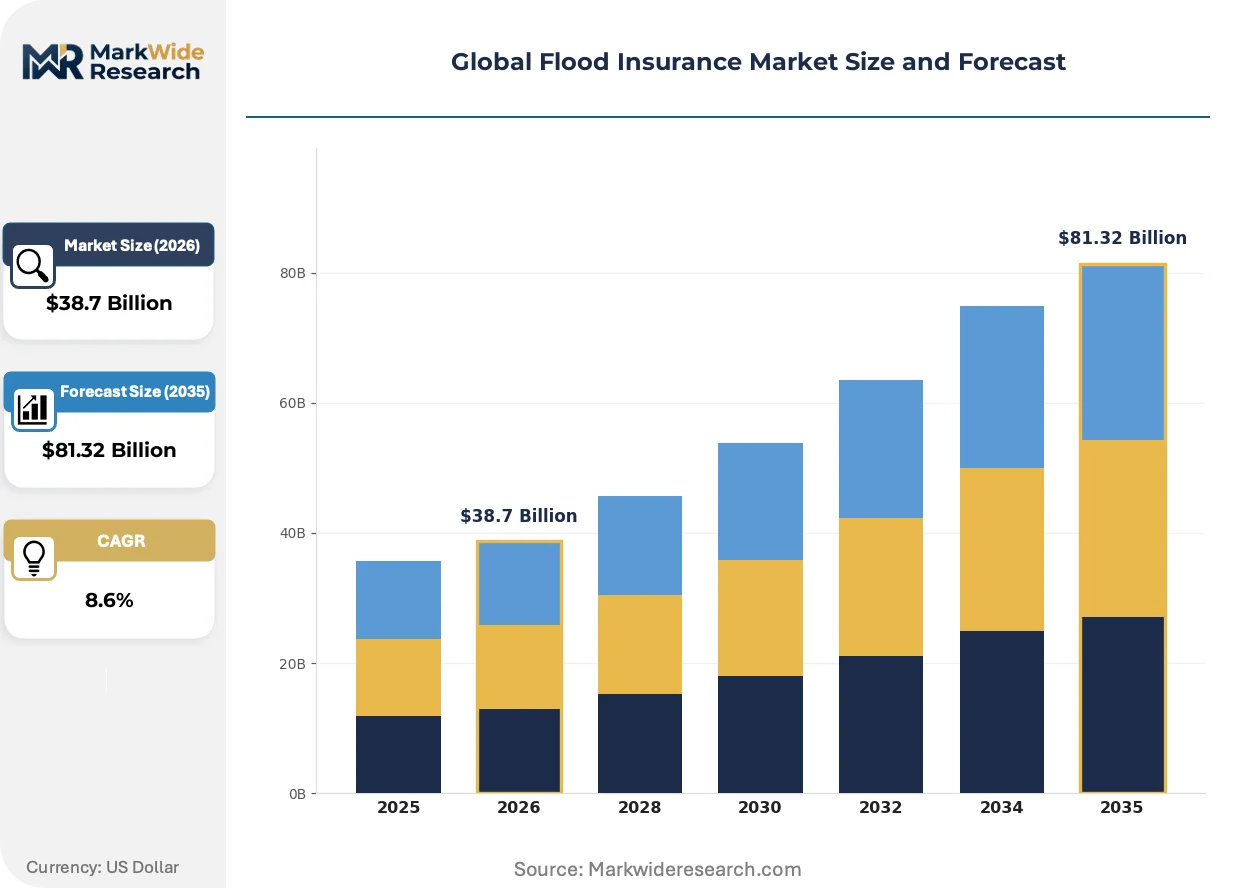
Market Dynamics
Parametric flood triggers are compressing traditional indemnity settlement cycles from months to days, forcing incumbent carriers to rebuild core claims infrastructure around satellite precipitation feeds and blockchain-verified payouts.
Growth Catalysts
- NFIP Reform:The US Federal Emergency Management Agency's Risk Rating 2.0 methodology now prices individual property risk rather than zone averages, accelerating private-market policy migration in Florida, Louisiana, and Texas.
- Commercial Property Expansion:Mortgage lenders in coastal urban corridors now mandate flood coverage for refinancing, embedding insurance into capital-market due diligence.
- Satellite Elevation Mapping:Lidar-derived digital terrain models enable meter-scale risk stratification, unlocking previously uninsurable exposures in Bangladesh delta regions.
Market Restraints
- Reinsurance Capacity Squeeze:Catastrophe bond spreads in Bermuda and London have widened as climate-adjusted loss models compress retrocession availability for peak flood zones.
- Actuarial Talent Collapse:Legacy carriers face acute shortages of hydrological modelers capable of integrating fluvial, pluvial, and coastal surge dynamics into unified pricing frameworks.
- Basel III Capital Treatment:Flood exposure concentrations attract punitive risk-weighting for European insurers under Solvency II, compressing return on equity for undiversified portfolios.
Strategic Opportunities
- Netherlands Delta Infrastructure:Public-private partnerships around Room for the River programs create captive demand for business-interruption riders tied to controlled inundation protocols.
- Blockchain Smart Contracts:Automated parametric payouts triggered by river-gauge sensors eliminate loss-adjustment expenses and accelerate capital recycling.
- India Coastal Urbanization:Mumbai and Chennai municipal bond issuances now require flood insurance wrap coverage, opening municipal finance as a distribution channel.
Industry Challenges
- Legacy System Integration:Incumbent policy-administration platforms built on static FEMA zone classifications cannot ingest real-time precipitation feeds without multimillion-dollar core replacements.
- Model Validation Timelines:State regulators in Florida and Texas require 18-month filing periods for climate-adjusted catastrophe models, delaying rate adequacy corrections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flood Insurance Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Residential, Commercial, Agricultural, Industrial Coverage Area: Urban, Rural, Coastal, Inland Customer Type: Homeowners, Businesses, Farmers, Government Premium Type: Fixed, Variable, Multi-year, Pay-as-you-go |
| Companies Covered | Berkshire Hathaway Inc., Assurant Inc., Allianz SE, Axa S.A., Liberty Mutual Insurance Company, American International Group Inc., Swiss Reinsurance Company Ltd, Chubb Limited, Munich Re Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flood Insurance Market Emerging Trajectories
Real-time hydrological data streams are collapsing the information asymmetry between insurers and insureds, compressing pricing cycles and enabling dynamic coverage adjustments that respond to seasonal flood-stage probability rather than annual contract terms.
Parametric triggers indexed to satellite-derived precipitation accumulation and river-stage telemetry are supplanting traditional loss-adjustment protocols in high-frequency flood zones. Commercial property managers in Miami and Rotterdam now prefer instantaneous payouts over indemnity verification. This compression eliminates claims-handling overhead while transferring basis risk to policyholders.
The EU Green Deal's climate adaptation disclosure mandates now require European insurers to stress-test flood exposure against 1-in-200-year return periods under the European Insurance and Occupational Pensions Authority's guidance. Solvency II capital relief compresses for undiversified river-basin concentrations. German and Dutch carriers respond by ceding peak risks to collateralized reinsurance vehicles.
Municipal procurement of flood coverage is fragmenting from national programs toward bespoke city-level placements. Bangladesh's Dhaka and Chattogram now negotiate standalone policies with international reinsurers rather than relying on sovereign risk pools. This shift concentrates underwriting expertise in urban catastrophe modeling while bypassing bureaucratic allocation mechanisms.
Global Flood Insurance Market Segmentation
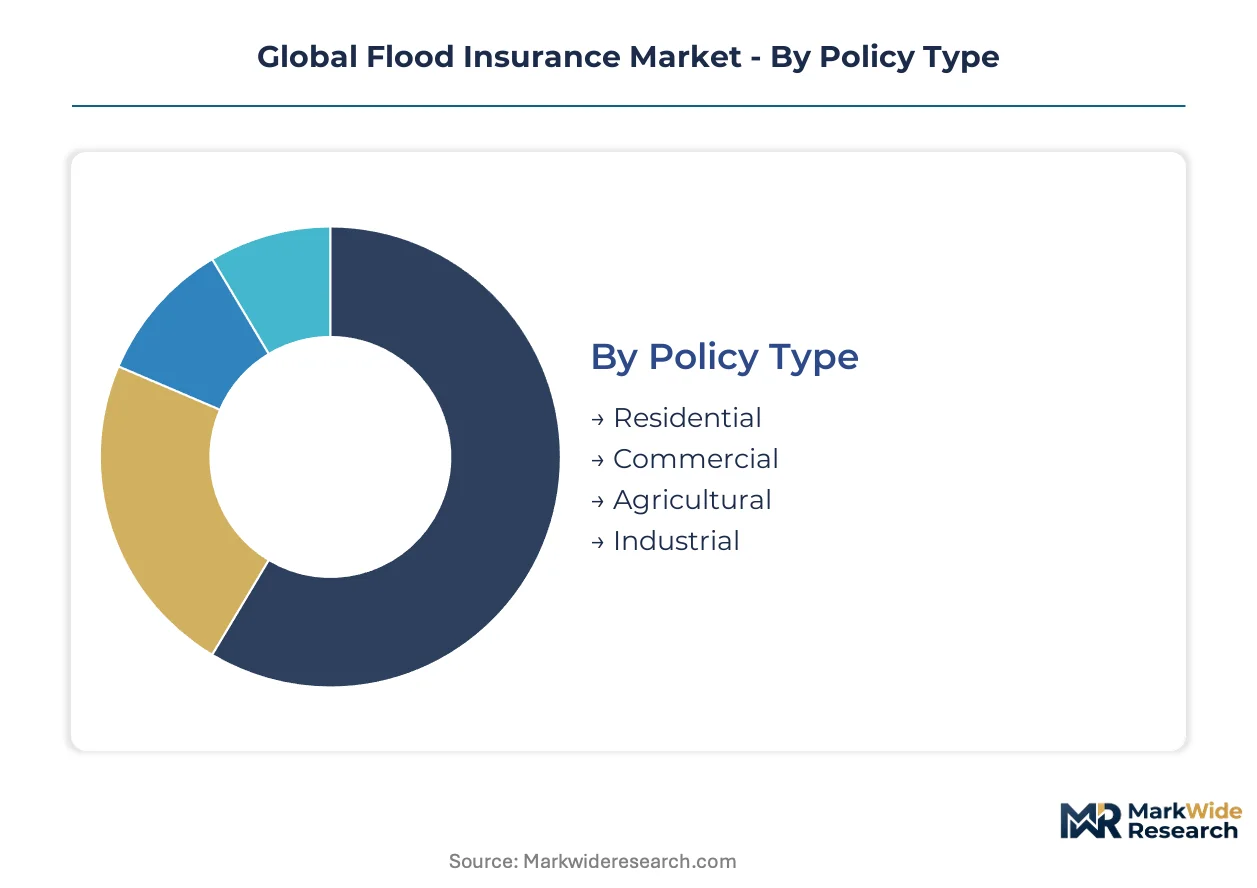
Flood insurance segmentation reveals where capital deployment concentrates and where parametric substitutes threaten traditional indemnity structures. Distinct risk profiles across policy types, geographies, and customer bases determine pricing granularity and reinsurance layering strategies.
Policy Type:
Residential policies face the strongest substitution pressure from parametric microinsurance products, while commercial and industrial lines retain pricing power through bespoke engineering.
- Residential:Standard dwelling and contents coverage dominates premium volume across developed economies. Mortgage lenders in Florida, Louisiana, and Bangladesh now mandate coverage for refinancing, embedding insurance into property finance workflows.
- Commercial:Bespoke business-interruption riders and higher per-risk limits command wider margins. Property managers in Miami and Rotterdam prefer instantaneous parametric payouts over indemnity verification, compressing traditional settlement cycles.
- Agricultural:Crop and livestock protection against fluvial inundation. Indian and Vietnamese rice belt cooperatives drive uptake through government-subsidized premium pools.
- Industrial:Manufacturing facility protection with extended business interruption clauses. German chemical processors along the Rhine require specialized coverage for controlled inundation protocols under Room for the River programs.
Residential retains volume leadership; Commercial holds the steepest expansion curve.
Coverage Area:
Cost tier stratification separates satellite-mapped urban exposures from actuarially opaque rural territories.
- Urban:Meter-scale risk stratification through lidar-derived digital terrain models enables dynamic pricing. Mumbai and Chennai municipal bond issuances now require flood insurance wrap coverage, opening municipal finance as a distribution channel.
- Coastal:Storm surge and tidal inundation coverage concentrates in Florida, the Netherlands, and Bangladesh delta regions. Swiss Reinsurance Company Ltd competes on proprietary hydrological datasets that differentiate risk-selection protocols here.
- Rural:Sparse elevation data and dispersed infrastructure elevate loss-adjustment expenses. German and Dutch carriers cede peak risks to collateralized reinsurance vehicles to manage capital relief compression.
- Inland:Fluvial and pluvial overflow protection for riverine communities. Allianz SE anchors European coverage through granular river-basin underwriting in this segment.
Urban commands premium pricing; Coastal faces the most acute capacity constraints.
Customer Type:
Volume concentration tilts toward institutional purchasers with captive risk management functions.
- Homeowners:Individual policyholders purchasing through agent networks or direct channels. The US Federal Emergency Management Agency's Risk Rating 2.0 methodology now prices individual property risk rather than zone averages, accelerating private-market policy migration.
- Businesses:Corporate risk managers negotiating layered coverage with business interruption extensions. Commercial property portfolios are expanding coverage as climate-related risk assessments tighten.
- Farmers:Agricultural producers relying on cooperative purchasing or government schemes. Bangladesh's Dhaka and Chattogram now negotiate standalone policies with international reinsurers rather than relying on sovereign risk pools.
- Government:Municipal and national entities procuring coverage for public infrastructure. The EU Green Deal's climate adaptation disclosure mandates now require European insurers to stress-test flood exposure against 1-in-200-year return periods.
Businesses drive margin expansion; Government procurement is fragmenting toward city-level placements.
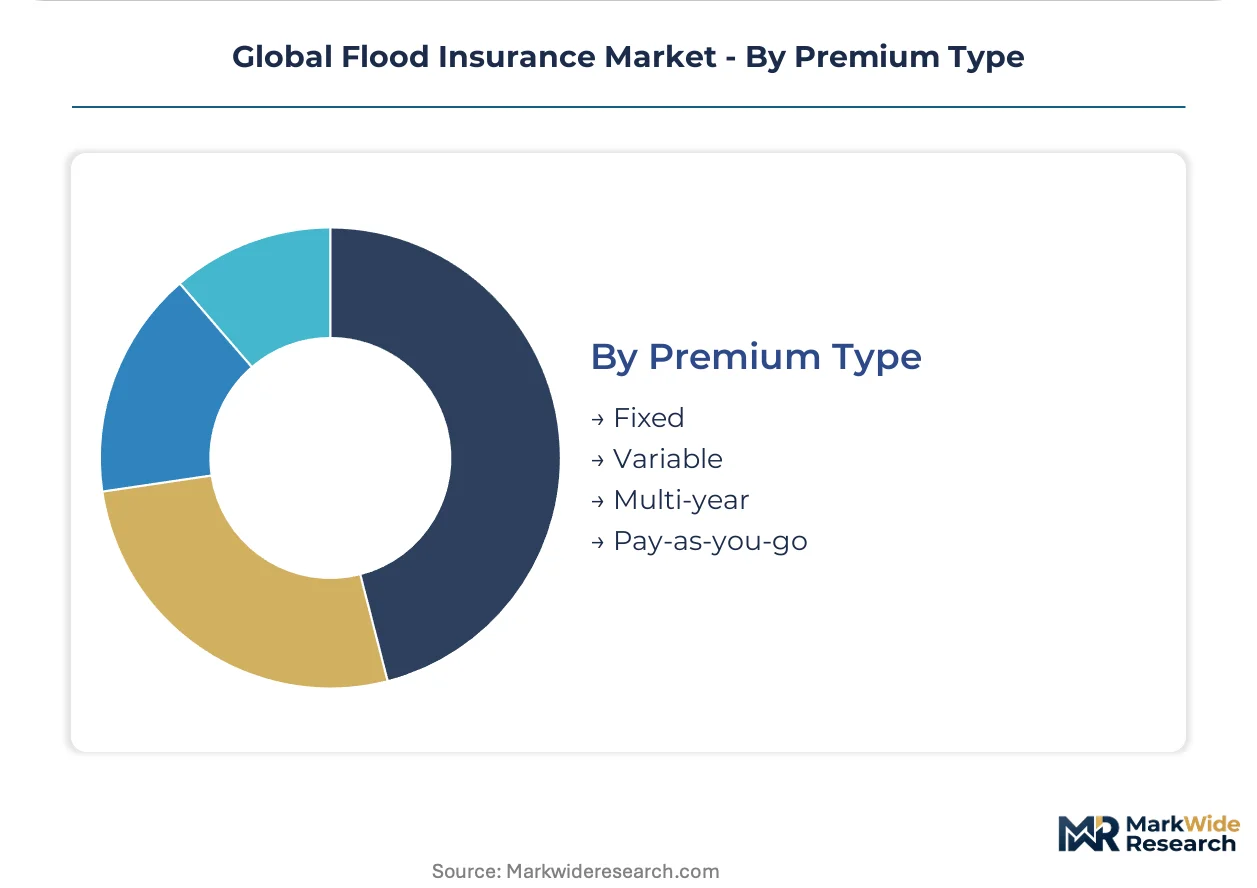
Premium Type:
Structural maturity separates legacy fixed-rate contracts from technology-enabled variable structures.
- Fixed:Annual premium determined at inception based on static zone classifications. Legacy policy-administration platforms built on FEMA zone classifications cannot ingest real-time precipitation feeds without multimillion-dollar core replacements.
- Variable:Dynamic pricing adjusting to seasonal flood-stage probability through satellite-based elevation mapping and real-time precipitation feeds. Variable premium structures are gaining traction as underwriting infrastructure modernizes.
- Multi-year:Contract terms spanning multiple annual cycles to smooth rate volatility. Bermuda and London catastrophe bond markets facilitate duration-matched capital for these structures.
- Pay-as-you-go:Usage-based coverage triggered by real-time hydrological monitoring. Blockchain smart contracts enable automated parametric payouts triggered by river-gauge sensors, eliminating loss-adjustment expenses.
Fixed retains policy count dominance; Variable is climbing the fastest as telemetry infrastructure spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FEMA anchors the dominant geography through NFIP reforms that accelerate private-market migration. The United States, Germany, Netherlands, Bangladesh, and India concentrate underwriting capacity and regulatory innovation.
United States
Florida, Louisiana, and Texas drive private-market policy migration as mortgage lenders mandate coverage for refinancing. FEMA's Risk Rating 2.0 methodology prices individual property risk rather than zone averages. Miami property managers now prefer instantaneous parametric payouts over traditional indemnity verification.
Germany
Rhine-basin chemical processors require specialized coverage for controlled inundation protocols under Room for the River programs. The EU Green Deal's climate adaptation disclosure mandates stress-test flood exposure against 1-in-200-year return periods. Munich anchors European flood coverage through granular river-basin underwriting.
Netherlands
Rotterdam commercial property portfolios expand coverage as climate-related risk assessments tighten. Public-private partnerships around Delta Infrastructure programs create captive demand for business-interruption riders. The Randstad urban corridor concentrates meter-scale risk stratification through lidar-derived digital terrain models.
Bangladesh
Dhaka and Chattogram municipal bond issuances now require flood insurance wrap coverage, opening municipal finance as a distribution channel. Sparse elevation data in rural delta regions elevates loss-adjustment expenses. International reinsurers now negotiate standalone city-level policies rather than sovereign risk pools.
India
Mumbai and Chennai drive uptake through government-subsidized premium pools for coastal urbanization. The Insurance Regulatory and Development Authority of India oversees private-market rate filings incorporating climate-adjusted catastrophe models. Agricultural cooperatives in the rice belt expand crop and livestock protection against fluvial inundation.
Global Flood Insurance Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in flood insurance. Reinsurance giants with proprietary hydrological datasets compete against property-casualty carriers rebuilding pricing infrastructure from parametric foundations. Strategic archetypes include balance-sheet-heavy capacity providers, granular river-basin underwriters, and technology-enabled parametric specialists. Competitive moves concentrate on M&A to acquire actuarial modeling talent and strategic partnerships to access satellite-based elevation mapping.
Among integrated reinsurance groups, Berkshire Hathaway Inc. and Swiss Reinsurance Company Ltd occupy positions defined by catastrophe-exposed market capacity and proprietary risk-selection protocols. Allianz SE anchors European coverage through granular river-basin underwriting. These three exemplify how scale and data differentiation separate leaders from carriers struggling with legacy system integration.
| Leading Market Players |
|---|
| Berkshire Hathaway Inc. |
| Assurant Inc. |
| Allianz SE |
| Axa S.A. |
| Liberty Mutual Insurance Company |
| American International Group Inc. |
| Swiss Reinsurance Company Ltd |
| Chubb Limited |
| Munich Re Group |
| Others |
Supply Flow & Price Mechanics
Parametric trigger mechanisms displacing traditional indemnity verification simultaneously redistribute supply geography toward satellite telemetry providers and compress pricing economics for loss-adjustment infrastructure. This substitution collapses settlement cycles from months to days, forcing carriers to rebuild core systems around blockchain-verified payouts and real-time precipitation feeds.
Pricing Analysis
Long-term multi-year contracts dominate commercial property placements, while residential lines mix annual fixed-rate policies with emerging pay-as-you-go structures. Three-tier pricing structure across premium, standard, and economy levels separates bespoke business-interruption riders from basic dwelling coverage. Cost compression in standard residential tiers intensifies because FEMA's Risk Rating 2.0 methodology exposes zone-average mispricing. Commercial buyers in Miami and Rotterdam exhibit the least price sensitivity, prioritizing instantaneous parametric payouts over premium minimization.
Supply Chain Analysis
Just-in-time capital deployment through collateralized reinsurance vehicles and catastrophe bond markets contrasts with strategic stockpiling of actuarial modeling talent at integrated carriers. Risk-bearing capacity concentrates in Bermuda, London, and Switzerland. Raw material dependencies include proprietary hydrological datasets, satellite elevation mapping, and river-gauge sensor networks. Single-source vulnerability sits with legacy policy-administration platforms that cannot ingest real-time telemetry without core replacement. Distribution runs through layered reinsurance structures to capital markets, with municipal bond channels emerging in Bangladesh and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in municipal procurement as city-level placements displace sovereign risk pools, creating niche underwriting expertise demands. Parametric product substitution accelerates this shift.
For Market Incumbents: Secure proprietary hydrological datasets through exclusive partnerships with satellite elevation mapping providers, defending against parametric specialists eroding commercial margins. Rebuild pricing infrastructure from parametric foundations to compress settlement cycles below competitor thresholds. Capacity addition in Rotterdam and Miami anchors retention of business-interruption riders.
For New Entrants and Emerging Players: Anchor in Bangladesh's Dhaka and Chattogram municipal bond channels where international reinsurers negotiate standalone city-level policies outside sovereign pools. Target agricultural cooperatives in Vietnam's rice belt through government-subsidized premium pools. Go-to-market leverage rests on blockchain smart contracts eliminating loss-adjustment expenses.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed parametric technology platforms possessing satellite precipitation feed integrations but lacking balance-sheet capacity. Long-term viability frames around underwriting margin recovery as climate-adjusted models achieve regulatory acceptance. Acquisition target archetype: mid-cap carriers with river-basin modeling expertise stranded by legacy system integration costs. Watch catastrophe bond spread compression in Bermuda as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Launch | Blockchain-verified payouts triggered by river-gauge sensors eliminate loss-adjustment overhead for commercial property managers. |
| Proprietary Dataset Acquisition | Exclusive lidar-derived digital terrain model partnerships differentiate risk-selection protocols in Bangladesh delta regions. |
| Municipal Channel Partnership | Mumbai and Chennai bond issuance requirements open distribution through infrastructure finance workflows. |
| Core System Replacement | Real-time precipitation feed ingestion modernizes policy-administration platforms beyond static FEMA zone classifications. |
| Reinsurance Vehicle Structuring | Collateralized vehicles ceding peak Dutch and German risks manage Solvency II capital relief compression. |
Methodological Framework
Initial hypotheses were tested against primary input from flood underwriting executives, catastrophe modelers, municipal risk managers, and reinsurance brokers and refined through secondary validation. Sources included NFIP rate filing documents, EIOPA stress-testing guidelines, SEC insurer 10-K disclosures, and satellite telemetry provider technical specifications. Bottom-up premium volume estimates triangulated against top-down reinsurance capacity assessments.
Variance decomposition across policy type, coverage area, customer segment, and premium structure dimensions informed projection mechanics. Growth trajectories derived from climate-adjusted loss model adoption curves and regulatory filing timelines. Forecast inputs incorporated FEMA Risk Rating 2.0 migration rates and parametric trigger penetration in commercial lines.
Material uncertainties — regulatory model validation delays, catastrophe bond spread volatility, and blockchain smart contract adoption — sit outside the modeled envelope. Forecasts reflect documented assumptions about capital market capacity and municipal procurement fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
India Online Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
Crime Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Property Insurance Market
Insurance
Engineering Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
Insurance Big Data Analytics Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Switzerland Reinsurance Market