
 Italy Freight and Logistics Market | 2026-2036
Italy Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Freight and Logistics Market Outlook
Software-defined fleet management is repositioning how Italian logistics providers monetize capacity, shifting revenue from per-shipment rates to subscription-based visibility and optimization tools. DACHSER leverages its European network density to sustain cross-border road dominance from northern Italy. Arcese Trasporti SpA anchors domestic freight flows through specialized temperature-controlled and industrial cargo services. Poste Italiane competes on last-mile reach, exploiting its unmatched provincial branch footprint for e-commerce final delivery.
Italy freight and logistics encompasses the physical movement and storage of goods via multimodal networks spanning road, rail, air, and maritime corridors, with operational parameters governed by EU-wide cabotage rules, axle weight limits of 44 tonnes for international transit, and cold-chain compliance standards for pharmaceutical and perishable cargo. The sector's primary commercial purpose is synchronizing supply chain velocity with inventory cost minimization across Italy's manufacturing heartlands and import-dependent consumption centers. Road transport retains structural dominance due to peninsula geography and fragmented rail infrastructure, though rail freight captures growing modal share on the Brenner and Tarvisio corridors where Rail Cargo Group operates terminal facilities. E-commerce end users drive fastest expansion in automated sorting and fulfillment services, while healthcare logistics commands premium margin pools through temperature-validated chain requirements.
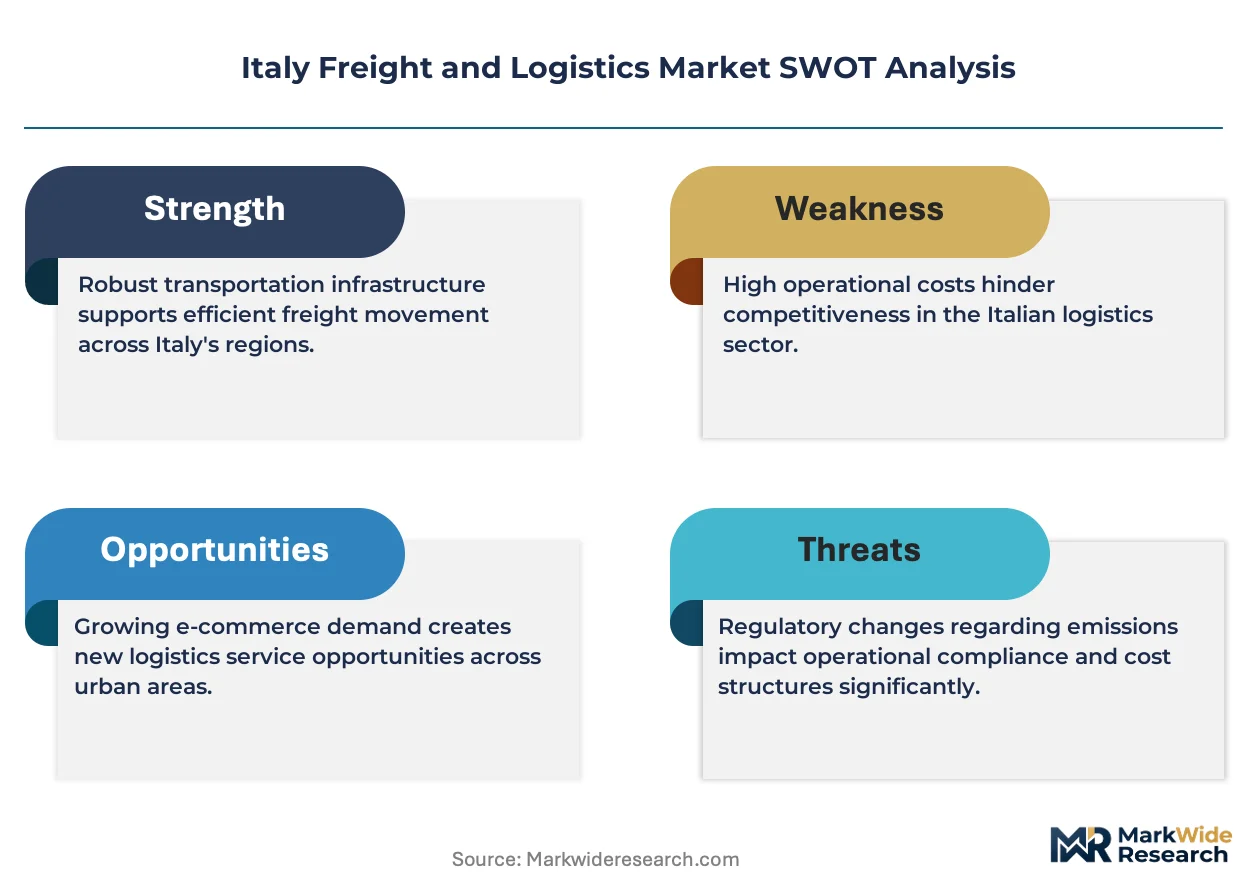
Italy's logistics sector operates under concurrent oversight from EU REACH and F-Gas Regulation for vehicle emissions compliance, alongside national enforcement by the Ministry of Infrastructure and Transport for road safety and driver hour regulations. The EU Green Deal's phased CO2 reduction targets for heavy-duty vehicles are forcing fleet renewal timelines and reshaping procurement criteria for contract logistics tenders. CSRD disclosure requirements will soon mandate emissions transparency across logistics supply chains, elevating data infrastructure investments. Stakeholders must monitor how EU AI Act provisions on automated decision-making affect route optimization algorithms and warehouse robotics deployment.
Market Dynamics
The EU Green Deal's phased CO2 reduction targets for heavy-duty vehicles are forcing Italian logistics operators into accelerated fleet renewal cycles, compressing payback periods for electric and hydrogen-powered commercial vehicles while reshaping procurement criteria for contract tenders.
Growth Catalysts
- E-commerce Fulfillment Networks:Pharmaceutical distributors and fashion retailers are expanding automated sorting facilities across the Lombardy-Milan corridor, pulling refrigerated and parcel freight volumes.
- CSRD Disclosure Mandates:The EU Corporate Sustainability Reporting Directive elevates emissions transparency requirements across logistics supply chains, driving data infrastructure investments.
- Brenner Corridor Electrification:Rail Cargo Group's terminal investments on the Italy-Austria border are capturing modal share from road haulage on north-south freight flows.
Market Restraints
- Axle Weight Limits:Italy's enforcement of 44-tonne international transit caps restricts payload optimization for cross-border operators serving Alpine routes.
- Fragmented Rail Infrastructure:Peninsula geography and legacy track gauge mismatches limit intermodal competitiveness against road-dominant last-mile networks.
- Driver Hour Regulations:Ministry of Infrastructure and Transport enforcement of EU-wide cabotage rules constrains fleet utilization rates during peak seasonal demand.
Strategic Opportunities
- Sicily-Calabria Logistics Gap:Underpenetrated southern Italian corridors offer first-mover advantage for temperature-controlled distribution serving expanding pharmaceutical manufacturing.
- EU AI Act Route Optimization:Automated decision-making compliance frameworks create competitive differentiation for operators investing in explainable algorithmic dispatch systems.
- Battery Swapping Infrastructure:Convergence of electric vehicle platforms with automated exchange stations addresses range anxiety for urban last-mile fleets.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems require costly middleware development to interface with cloud-based visibility platforms demanded by enterprise shippers.
- Cold-Chain Certification Timelines:Temperature-validated GDP compliance for pharmaceutical logistics extends facility commissioning cycles and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Freight and Logistics Market |
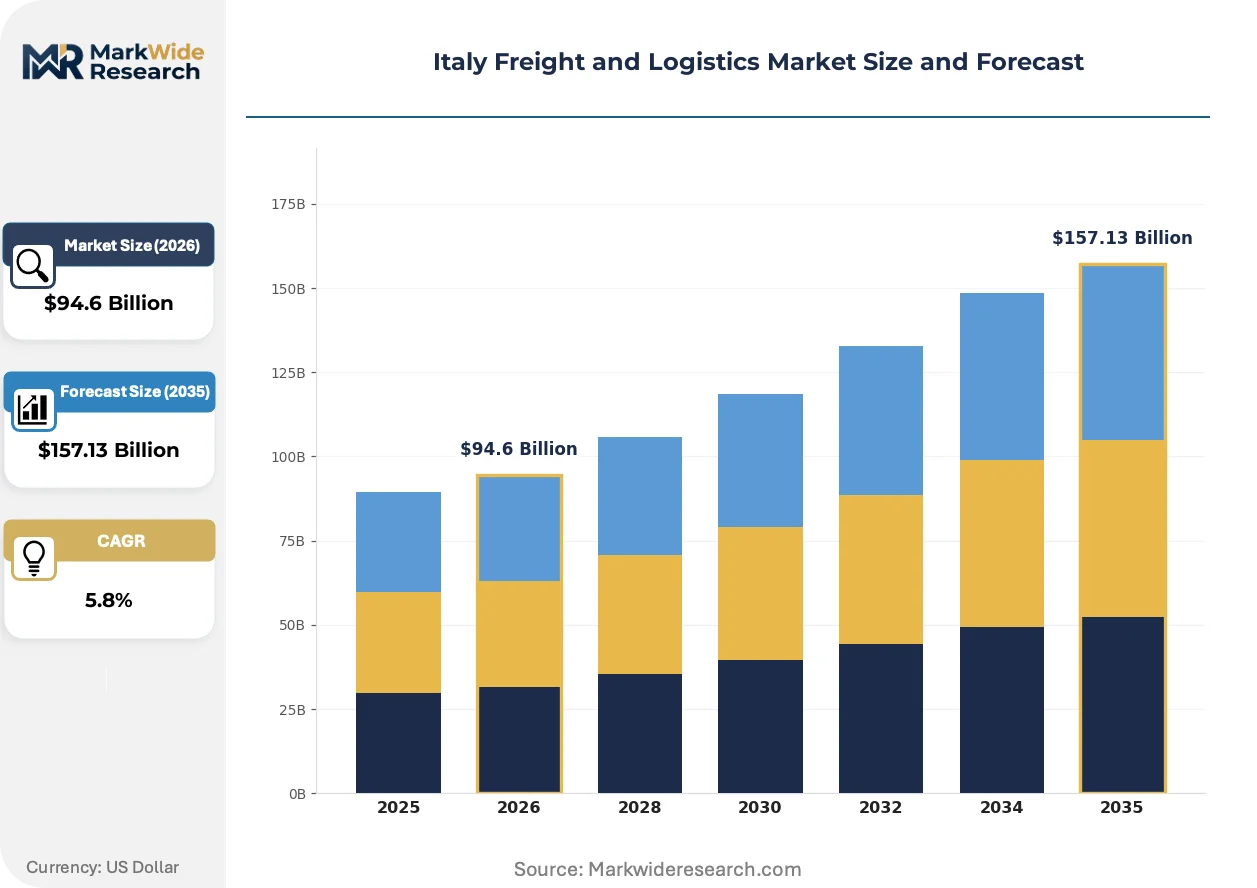
| Market Size in 2026 | $94.6 Billion |
| Market Size in 2035 | $157.13 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Transport, Air Freight, Sea Freight, Rail Freight End User: E-commerce, Manufacturing, Retail, Healthcare Technology: Transportation Management Systems, Warehouse Management Systems, IoT Solutions, Automated Sorting Delivery Model: Third-Party Logistics, Last Mile Delivery, Cross-Docking, Fulfillment Services |
| Companies Covered | DACHSER, Arcese Trasporti SpA, Poste Italiane, FedEx, UPS, DHL Group, Fercam SpA, Rail Cargo Group, DSV A/S (Including DB Schenker), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Freight and Logistics Market Strategic Shifts
Software-defined logistics platforms are unifying previously siloed fleet operations, warehouse execution, and freight matching into continuous optimization loops that compress working capital cycles for Italian operators.
Telematics convergence with AI-driven predictive maintenance is unifying vehicle health monitoring, route recalculation, and driver behavior analytics into single-dashboard visibility tools. Mid-sized freight operators serving the Veneto industrial belt are adopting these platforms fastest, replacing fragmented telematics point solutions. The structural consequence is collapsing IT integration costs that previously locked out smaller carriers from enterprise contract eligibility.
F-Gas Regulation phase-down schedules are compressing refrigeration fleet replacement timelines for Italian temperature-controlled operators. The industrial consequence is accelerated procurement of CO2 and hydrocarbon-based transport refrigeration units ahead of 2030 service bans. Pharmaceutical and fresh produce distributors in the Emilia-Romagna cluster are responding with captive retrofit programs rather than outsourced fleet leasing.
Shippers are consolidating contract logistics relationships around integrated fulfillment partners capable of binding warehousing, transport, and returns management under single SLA frameworks. The traditional spot-market brokerage layer faces disintermediation as manufacturing enterprises in the Turin automotive cluster demand inventory visibility from factory gate to final customer. This consolidation is most visible in Lombardy, where pharmaceutical exporters are eliminating multi-vendor fragmentation in favor of end-to-end cold-chain custody guarantees.
Italy Freight and Logistics Market Segmentation
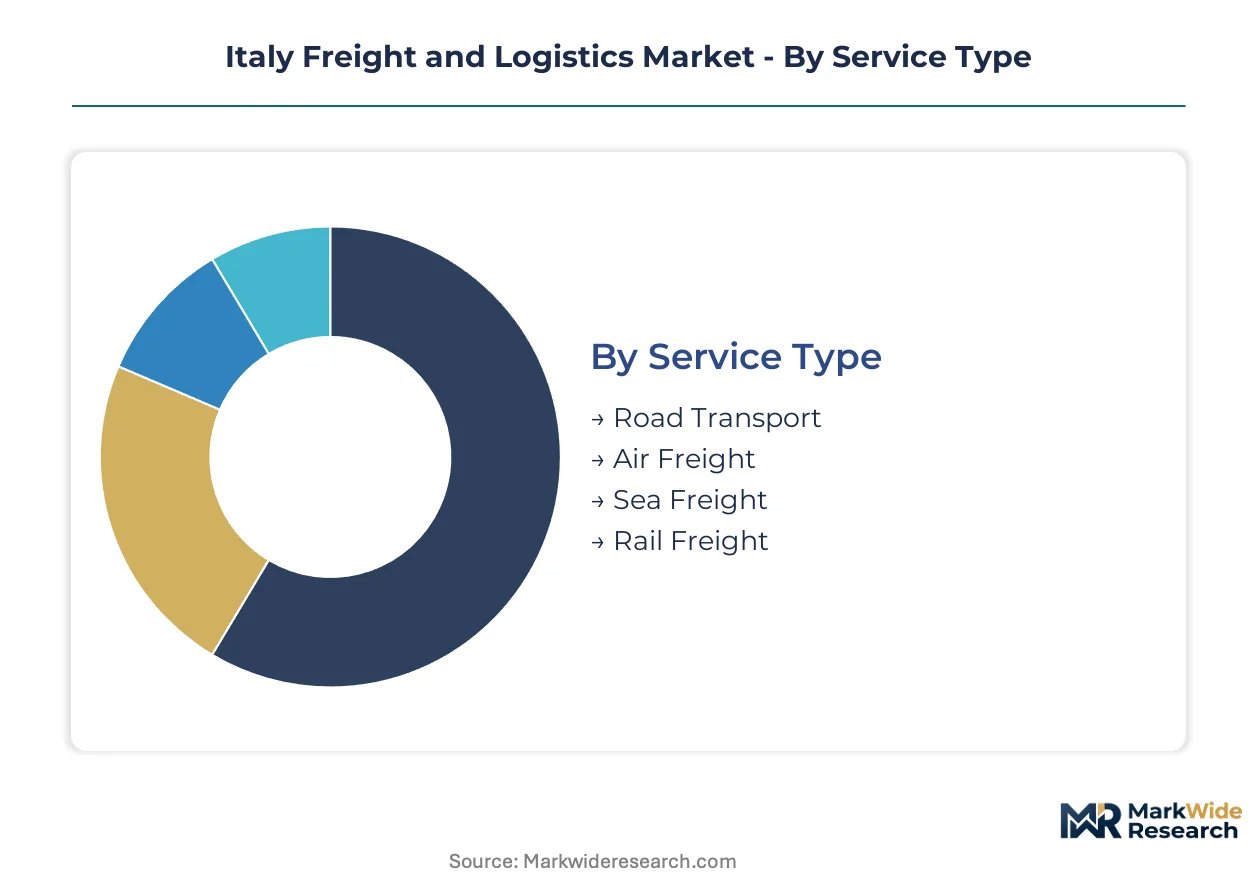
Italian freight and logistics operators configure service portfolios around modal specialization, end-use verticals, and technology integration depth. Segmentation reveals where margin pools concentrate and where infrastructure investments face longest payback cycles.
Service Type:
Road transport commands disproportionate capacity investment across Italian logistics networks due to peninsula geography and last-mile imperatives.
- Road Transport:Palletized and full-truckload services move through the Brenner and Tarvisio corridors under 44-tonne axle weight limits enforced by the Ministry of Infrastructure and Transport. Pharmaceutical distributors in Lombardy and automotive suppliers in Piedmont generate sustained contract volumes.
- Air Freight:Temperature-controlled and high-value cargo flows through Milan Malpensa and Rome Fiumicino, serving fashion exporters and medical device manufacturers with EU REACH-compliant handling protocols.
- Sea Freight:Container movements concentrate at Genoa, La Spezia, and Gioia Tauro, handling import-dependent manufacturing inputs and agricultural exports.
- Rail Freight:Intermodal services capture north-south bulk flows where Rail Cargo Group terminal investments offset road congestion on Alpine routes.
Today's leader: Road Transport. Tomorrow's challenger: Rail Freight.
End User:
Demand concentration varies sharply by vertical, with e-commerce and healthcare commanding premium pricing against commoditized manufacturing flows.
- E-commerce:Automated sorting investments across the Lombardy-Milan corridor pull parcel volumes from Poste Italiane and private operators. Fashion retailers and marketplace platforms drive fastest expansion in same-day and next-day fulfillment.
- Healthcare:GDP-validated cold-chain requirements for pharmaceutical distribution create defensible margin pools. Temperature-controlled logistics in Emilia-Romagna serves expanding vaccine and biologics manufacturing.
- Manufacturing:Just-in-time automotive components and industrial machinery move through Veneto and Piedmont clusters under strict delivery windows.
- Retail:Grocery and general merchandise distributors consolidate regional distribution center networks to balance inventory cost against omnichannel fulfillment speed.
E-commerce and healthcare segments are expanding most quickly, while manufacturing retains volume dominance.
Technology:
Technology procurement patterns split between enterprise shippers demanding unified visibility and mid-sized operators replacing fragmented point solutions.
- Transportation Management Systems:Cloud-based platforms unify route optimization, carrier selection, and freight audit for Italian 3PLs serving multinational contract accounts.
- Warehouse Management Systems:Real-time inventory positioning and labor optimization modules support automated fulfillment centers in Milan and Bologna logistics parks.
- IoT Solutions:Sensor networks track location, temperature, and shock events across pharmaceutical and perishable supply chains under CSRD disclosure mandates.
- Automated Sorting:High-throughput parcel handling systems reduce labor dependency for e-commerce peak volumes in Lombardy and Lazio distribution hubs.
Transportation Management Systems anchor current spending, while Automated Sorting shows steepest expansion trajectory.
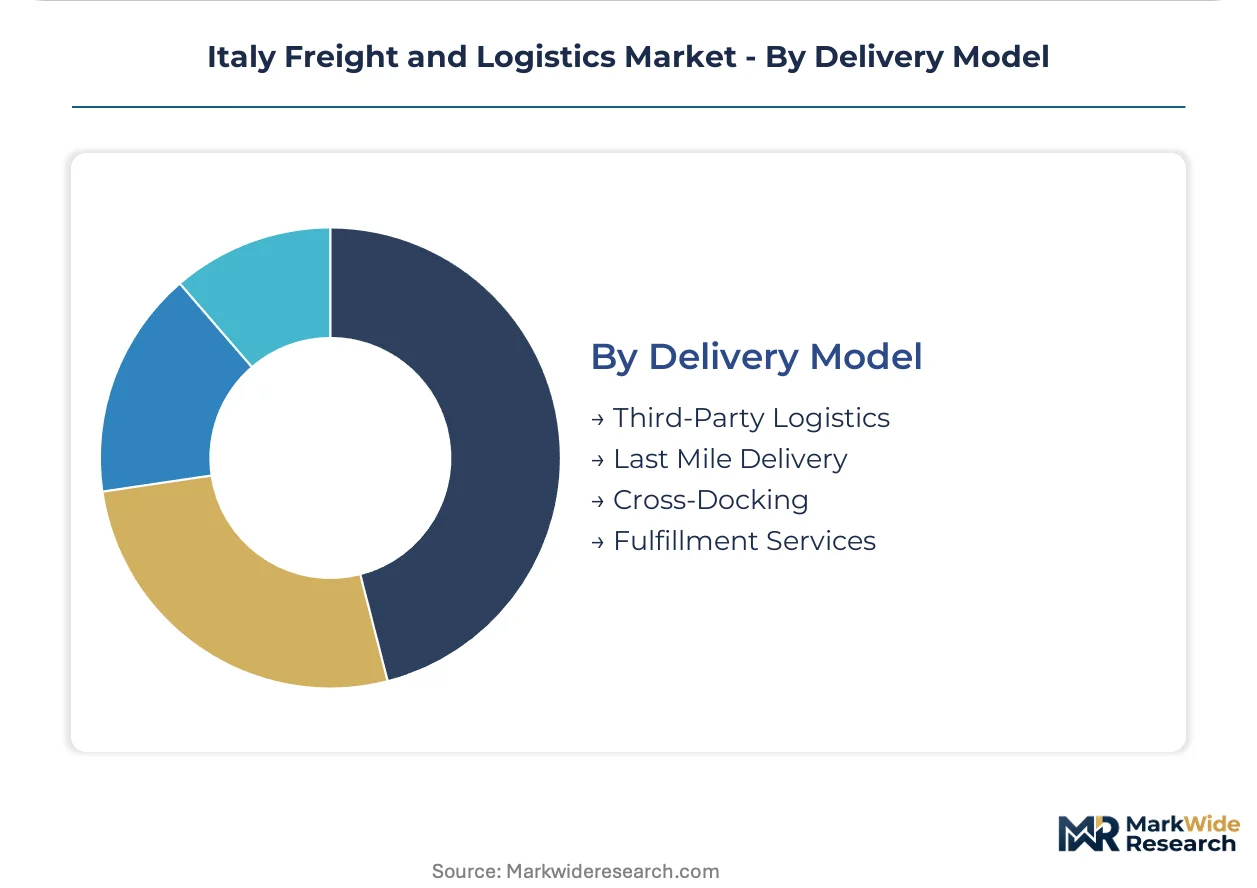
Delivery Model:
Delivery model selection reflects shipper preferences for asset control versus flexibility across seasonal demand cycles.
- Third-Party Logistics:Integrated warehousing, transport, and value-added services under single SLA frameworks attract pharmaceutical and automotive exporters eliminating multi-vendor fragmentation.
- Last Mile Delivery:Dense urban networks in Rome, Milan, and Naples face regulatory pressure from EU Green Deal emissions standards and municipal access restrictions.
- Cross-Docking:Rapid freight consolidation at Turin and Verona hubs minimizes inventory holding for fast-moving consumer goods distributors.
- Fulfillment Services:End-to-end inventory management, picking, packing, and returns processing binds e-commerce merchants to platform operators.
Third-Party Logistics retains contract value leadership, while Fulfillment Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's freight density exceeds Italy's by a factor of three, yet Italian operators command higher margins on pharmaceutical and fashion logistics due to specialized cold-chain requirements. France and Spain present contrasting regulatory environments for cross-border haulage. The Netherlands and Switzerland complete the competitive perimeter with distinct modal specializations.
Germany
Automotive component flows and chemical exports sustain heavy freight volumes through the KBA-regulated corridor network. The EU Green Deal's truck CO2 standards accelerate fleet turnover at Duisburg intermodal terminals. Bavaria's manufacturing belt generates contract logistics demand that spills into northern Italian distribution networks.
France
Wine exports and aerospace components create temperature-sensitive cargo requirements through ANSM-monitored pharmaceutical channels. The EU AI Act's algorithmic transparency rules reshape route optimization software procurement in Lyon logistics parks. The Île-de-France cluster anchors continental freight consolidation for Italian-bound goods.
Spain
Perishable agricultural exports from Valencia and Barcelona drive refrigerated transport demand under EFSA food safety protocols. The Brenner corridor's rail electrification captures modal share from road haulage on Italy-Spain freight lanes. Madrid's distribution centers serve as southern European gateways for Italian automotive supply chains.
Netherlands
Rotterdam port throughput and Schiphol air cargo dominance position Dutch operators as modal integrators for Italian importers. REACH chemical handling standards govern transshipment protocols at Venlo logistics parks. The Randstad's automated sorting investments set benchmark efficiency standards that Lombardy operators emulate.
Switzerland
Swissmedic-regulated pharmaceutical logistics create premium service tiers for temperature-validated transit through Alpine tunnels. The Gotthard Base Tunnel's rail capacity offers modal alternatives to Brenner road congestion for Italian northbound freight. Basel's tri-national logistics zone anchors chemical and healthcare distribution into Italian manufacturing regions.
Italy Freight and Logistics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated 3PLs capturing pharmaceutical and automotive accounts while asset-light brokers serve seasonal spot demand. The vendor base concentrates around four operational archetypes: European network operators with cross-border density, domestic temperature-controlled specialists, postal-last-mile hybrids, and intermodal rail incumbents. Consolidation pressures favor operators with captive warehousing assets and CSRD-compliant emissions tracking infrastructure. Strategic moves center on single-SLA contract bundling and automated fulfillment center expansion in Lombardy logistics parks.
Among European network operators, DACHSER and DSV A/S occupy positions defined by cross-border road density and integrated warehousing capabilities. Domestic specialists Arcese Trasporti SpA exemplify the temperature-controlled and industrial cargo archetype anchored in northern Italian manufacturing corridors. These three represent distinct competitive vectors: transcontinental network reach, vertical specialization depth, and asset-heavy contract logistics integration.
| Leading Market Players |
|---|
| DACHSER |
| Arcese Trasporti SpA |
| Poste Italiane |
| FedEx |
| UPS |
| DHL Group |
| Fercam SpA |
| Rail Cargo Group |
| DSV A/S (Including DB Schenker) |
| Others |
Value Chain & Pricing Dynamics
Fuel costs and driver wages cascade through Italian logistics pricing tiers, compressing margins for road-dominant operators while electrification premiums reshape contract structures for pharmaceutical and e-commerce shippers in the Lombardy-Milan corridor.
Pricing Analysis
Capacity additions in automated sorting facilities across Emilia-Romagna are reshaping price floors for parcel fulfillment, forcing legacy operators into volume-discount structures to retain e-commerce accounts. Three-tier pricing structure across premium cold-chain, standard palletized, and economy parcel levels stratifies by GDP certification and temperature-validation requirements. Pricing pressure stems from EU Green Deal fleet renewal mandates accelerating electric vehicle procurement timelines. Small and mid-sized freight operators show highest price sensitivity, while pharmaceutical distributors accept premium rates for end-to-end custody guarantees.
Supply Chain Analysis
Dual-sourcing requirements from automotive and pharmaceutical shippers mandate multi-carrier qualification across Brenner corridor operators, preventing single-fleet dependency for north-south freight flows. Manufacturing inputs draw heavily from Germany, China, and Eastern European component hubs, while perishable exports feed from southern Italian agricultural regions. Diesel fuel and lithium-ion battery cells anchor cost volatility, with aluminum trailer chassis adding metals exposure. Single-source vulnerability concentrates around Rail Cargo Group's terminal monopoly on Alpine rail freight. Distribution runs through Lombardy consolidation hubs before final-mile dispersal to provincial consumption centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy freight market offers geographic-arbitrage value through southern corridor underpenetration, where logistics costs run 15-20% above northern benchmarks due to infrastructure gaps and carrier scarcity.
For Market Incumbents: Hedge against modal shift by securing captive warehousing assets in Verona and Bologna logistics parks before rail electrification captures additional Alpine freight share. Consolidate temperature-controlled fleet positions through GDP certification investments that lock out smaller competitors from pharmaceutical contract eligibility. Prioritize CSRD-compliant emissions tracking infrastructure to meet enterprise shipper disclosure mandates.
For New Entrants and Emerging Players: AI-driven predictive maintenance platforms offer technology-first entry into mid-sized carrier segments currently locked out of enterprise contracts by IT integration barriers. Target Sicily-Calabria pharmaceutical distribution corridors where temperature-controlled capacity scarcity meets expanding vaccine manufacturing. Lead with subscription-based visibility tools rather than asset-heavy fleet competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where CSRD disclosure requirements fragment mid-sized operators unable to fund emissions data infrastructure independently. Five-to-ten year viability favors integrated 3PLs with captive warehousing and cross-border network density over pure-play road hauliers. Watch for inflection when EU AI Act enforcement triggers algorithmic transparency investments that favor explainable route optimization systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fulfillment Center Expansion | Lombardy logistics parks capture e-commerce volume growth from fashion retailers and marketplace platforms. |
| Electric Fleet Procurement Acceleration | EU Green Deal CO2 targets force compressed payback timelines for battery-swapping infrastructure investments. |
| GDP Certification Investment | Temperature-validated cold-chain compliance locks pharmaceutical contract eligibility against unqualified competitors. |
| Cross-Border Network Integration | Brenner corridor density sustains modal competitiveness against Rail Cargo Group's terminal investments. |
| Software-Defined Logistics Platform Launch | Unified fleet-warehouse-freight matching compresses working capital cycles for enterprise shipper contracts. |
Study Parameters
Direct dialogue with logistics operations directors, fleet procurement managers, pharmaceutical supply chain leads, and e-commerce fulfillment executives grounded qualitative findings in operational reality. Secondary validation drew from EU transport statistics, Ministry of Infrastructure and Transport enforcement records, Rail Cargo Group terminal throughput disclosures, and CSRD implementation guidance documents. Bottom-up carrier capacity assessments triangulated against top-down freight volume projections from customs and intermodal terminal data.
Bottom-up modeling segmented the market by service type, end-use vertical, technology integration depth, and delivery model complexity across the analysis window. CAGRs derived from historical volume trends, fleet renewal cycle timing, and e-commerce penetration trajectories in comparable European corridors. Forecast inputs incorporated EU Green Deal phase-in schedules for heavy-duty vehicle emissions standards and pharmaceutical GDP compliance adoption curves.
The model holds under stable EU regulatory enforcement and continued e-commerce growth; deviation in Brenner corridor rail electrification timelines or sudden diesel price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
India Cold Chain Logistics Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
Sweden Freight and Logistics Market